
Market Overview:
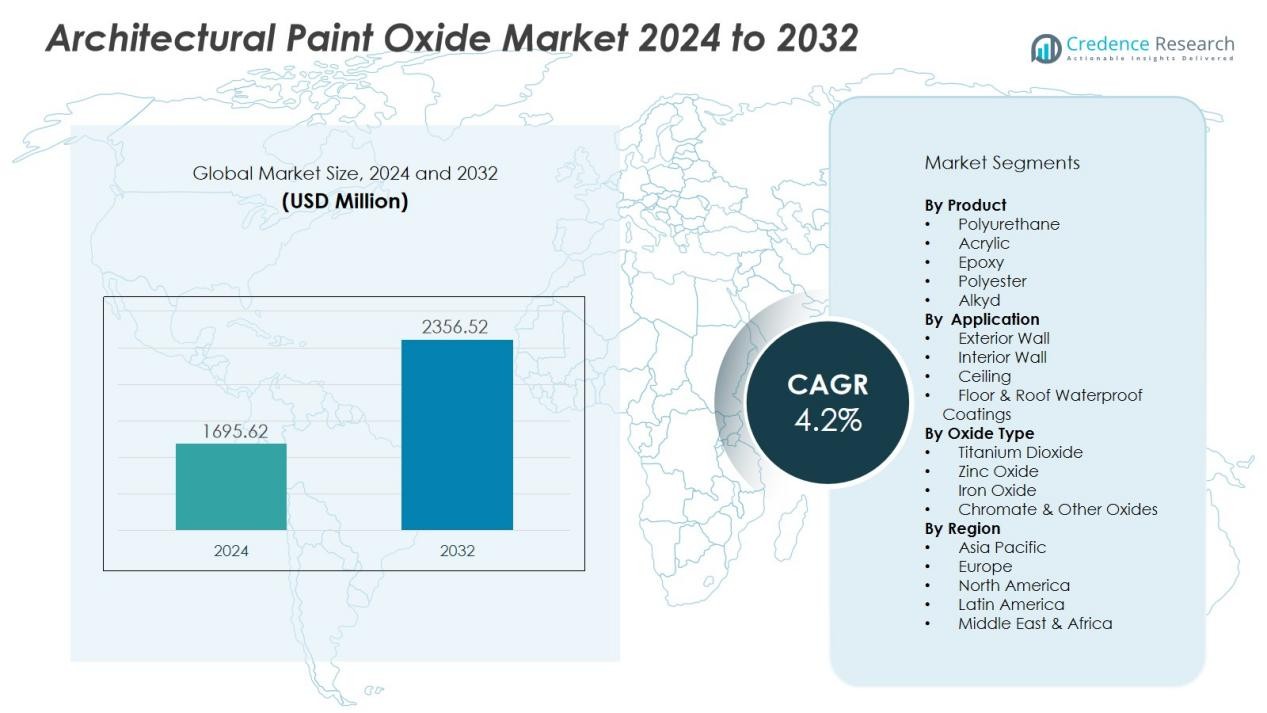
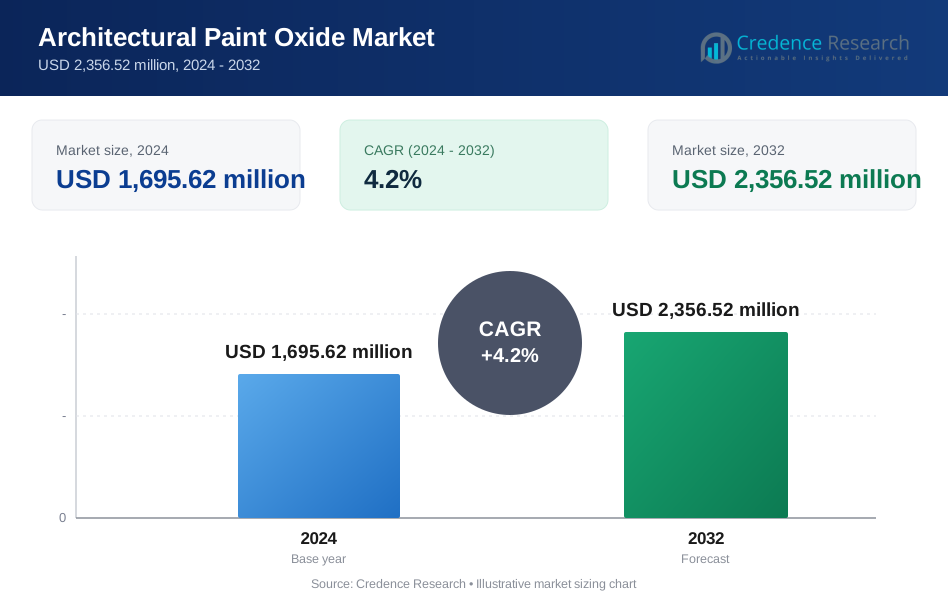
The Architectural Paint Oxide Market size was valued at USD 1695.62 million in 2024 and is anticipated to reach USD 2356.52 million by 2032, at a CAGR of 4.2 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Architectural Paint Oxide Market Size 2024 | USD 1695.62 Million |
| Architectural Paint Oxide Market, CAGR | 4.2% |
| Architectural Paint Oxide Market Size 2032 | USD 2356.52 Million |
Growth in this market is primarily driven by rapid urbanization, heightened infrastructure investment, and rising demand for aesthetically rich and performance-oriented coatings. The push for low-VOC and sustainable paints has further stimulated demand for oxide pigments that offer high weather resistance, UV stability, and compliance with environmental regulations.
Regionally, the Asia-Pacific region leads with the largest share—about 42.3% in 2024—driven by fast-moving urban development in countries such as China and India. North America is expected to exhibit strong growth ahead of other regions due to increasing renovation activity and stringent eco-regulations. Europe also remains significant thanks to its mature construction base and high focus on eco-friendly solutions.
Market Insights:
- The Architectural Paint Oxide Market was valued at USD 1,695.62 million in 2024 and is projected to reach USD 2,356.52 million by 2032, growing at a CAGR of 4.2% during the forecast period.
- The Asia-Pacific region holds the largest market share at 42.3% in 2024, driven by rapid urbanization, large-scale infrastructure projects, and growing demand for durable, eco-friendly coatings.
- North America, with a 28.5% market share in 2024, shows strong growth due to increasing renovation activities, stringent environmental regulations, and the demand for sustainable paints.
- Europe accounts for 30% of the global market share in 2024, supported by strict building sustainability regulations and high demand for aesthetic and functional coatings in renovation projects.
- By segment, the product segment (Polyurethane, Acrylic, Epoxy, Polyester, Alkyd) holds the highest share, followed by the application segment (Exterior Wall, Interior Wall, Ceiling, Floor & Roof Waterproof Coatings).
Market Drivers:
Rising Urbanization and Infrastructure Development
The rapid urbanization witnessed globally plays a pivotal role in driving the growth of the Architectural Paint Oxide Market. Increasing urban populations create a higher demand for residential and commercial spaces, leading to the expansion of the construction industry. Urban infrastructure projects, including roads, bridges, and public buildings, further enhance the need for durable and visually appealing coatings. Architectural paints with oxide pigments are preferred for their ability to withstand weather conditions while offering vibrant, long-lasting colors.
- For instance, Shepherd Color has developed chromium iron oxide pigments such as Black 10G975, which delivers exceptional durability through high infrared reflection combined with UV and chemical stability, making it well-suited for building materials including siding, roofing extrusions, and architectural panels requiring long-term weather resistance.
Demand for Sustainable and Low-VOC Paints
Sustainability is a significant driver in the Architectural Paint Oxide Market. Growing environmental concerns and stringent regulations on volatile organic compound (VOC) emissions are pushing the industry toward eco-friendly solutions. Paints made with oxide pigments, which are typically low in VOCs, meet these requirements while ensuring excellent durability and performance. The market’s shift toward sustainability is evident in consumer preference for products that contribute to healthier indoor environments and greener buildings.
- For instance, Sherwin-Williams' Harmony Interior Acrylic Latex Paint delivers a zero VOC formula at less than 50 g/L combined with antimicrobial agents that inhibit mold and mildew growth on the paint film
Advancements in Coating Technologies
Technological advancements in coating systems are shaping the demand for architectural paint oxides. Innovations in pigment formulations, such as the development of more weather-resistant and UV-stable oxide pigments, enhance the durability of paints and coatings. These advancements not only improve the aesthetic appeal but also increase the longevity of painted surfaces, making oxide-based paints highly sought after for both residential and commercial applications.
Increasing Renovation and Remodeling Activities
The growing trend of home renovations and commercial space remodeling is fueling demand for high-quality architectural paints. Consumers are opting for paint products that offer enhanced aesthetic qualities and long-term performance. The Architectural Paint Oxide Market benefits from this trend as oxide-based paints offer a wide range of colors and finishes, meeting both aesthetic and functional requirements for renovation projects. As people continue to invest in upgrading existing structures, the market for architectural paint oxides remains robust.
Market Trends:
Adoption of Low‑VOC and Water‑based Formulations
The Architectural Paint Oxide Market shows strong momentum toward low‑VOC and water‑based paint systems. Many manufacturers invest in oxide pigments that disperse well in aqueous media and support compliance with tighter environmental regulations. The shift away from solvent‑borne coatings drives usage of iron oxides, titanium dioxide and zinc oxides with improved performance. These pigments deliver enhanced durability and weather resistance while meeting sustainability targets. Industry players adopt these blends to respond to rising demands from green building certifications and eco‑conscious consumers.
- For instance, AkzoNobel launched its Dulux Trade Scuffshield Matt, a water-based decorative paint that achieves VOC content below 10g/L, contributing to compliance with EU limits and boosting usage in certified green buildings.
Functional and Smart Coatings Integration
Coating products in this market increasingly incorporate smart or functional properties such as self‑cleaning, antimicrobial or reflective capabilities. Innovations in oxide pigment chemistry enable coatings to reflect UV light, resist microbial growth or reduce surface soiling. This trend expands usage beyond pure aesthetic decoration into performance‑driven applications in commercial and residential projects. Suppliers in the Architectural Paint Oxide Market partner with technology firms to embed new pigment‑based functionalities. End‑users favour these advanced coatings for their long‑term asset value, reduced maintenance costs and selective premium pricing.
- For instance, Rhino Shield has developed advanced UV-reflective ceramic coatings that achieve a Solar Reflectance Index (SRI) rating of 106 to 107, enabling homeowners to reduce cooling costs through superior solar heat reflection while maintaining UV resistance through top-grade titanium dioxide pigments combined with ceramic microspheres.
Market Challenges Analysis:
Raw‑Material Price Volatility and Supply‑Chain Constraints
The Architectural Paint Oxide Market confronts substantial pressure from fluctuating prices of key pigment raw materials such as titanium, iron and zinc oxides. Manufacturers struggle to set stable product pricing when underlying input costs swing due to geopolitical tensions or supply shortages. It takes longer for producers to adjust formulations and secure alternative sources without affecting performance. The ripple effect of cost increases often forces either margin compression or higher end‑product pricing. Supply‑chain disruptions add uncertainty that can delay delivery and upset project schedules in construction and renovation.
Regulatory Compliance Complexity and Performance Trade‑Offs
This market also faces intricate regulatory demands covering volatile organic compounds (VOCs), heavy‑metal content, and environmental impact of coatings. Producers in the architectural paint oxide market must invest heavily in R&D to reformulate pigments and binders to comply with regional standards. It becomes difficult to maintain durability, colour stability and weather resistance while operating under tighter emission limits. Some end‑users resist paying premium prices for reformulated products, which reduces market uptake. Manufacturers must navigate diverse regulatory frameworks across regions, increasing complexity and administrative burden.
Market Opportunities:
Expansion in Emerging Construction and Renovation Sectors
The Architectural Paint Oxide Market presents substantial opportunities through growth in residential and commercial construction in emerging economies. Rapid urbanisation and rising infrastructure budgets in regions like Asia‑Pacific drive demand for high‑performance coating solutions. Manufacturers can leverage this trend by developing oxide pigments that meet durability and aesthetic criteria demanded in large‑scale projects. Renovation and refurbishment of older buildings also open the market for premium oxide‑based coatings that deliver superior weathering resistance and colour retention. It becomes possible to capture new segments by targeting such retrofit applications where performance and lifecycle costs matter. Suppliers who adjust their product portfolios to serve these evolving needs stand to gain competitive advantage.
Technology‑Driven Product Differentiation and Eco‑Friendly Solutions
Innovating oxide pigment formulations offers another strategic opportunity in the architectural paint oxide market. Development of pigments tailored for water‑based and low‑VOC systems addresses increasing regulatory and consumer pressure for environmentally safe coatings. Smart coatings that offer additional functionalities—such as UV reflection, antimicrobial surfaces or rapid colour change—open new high‑value niches. It benefits companies to invest in R&D collaborations and integrate advanced pigment technologies to raise barriers to entry. Strategic partnerships between pigment producers and paint formulators can accelerate product launches and differentiation. By focusing on sustainability and functionality, it becomes feasible to penetrate premium segments and enhance margin potential.
Market Segmentation Analysis:
By Product (Resin/Coating Type)
The product segment covers polyurethane, acrylic, epoxy, polyester and alkyd coatings. Acrylic resin holds a leading share thanks to its durability, weather‑resistance and strong performance in both interior and exterior uses. Epoxy coatings show higher growth potential due to superior chemical resistance and protective film formation. Manufacturers adopt these resin types and tailor oxide pigments for each formulation to meet performance demands. This segmentation lets suppliers target product portfolios more precisely and capture value from high‑end applications.
- For instance, PPG Industries' fluoropolymer-based (PVDF) 'PPG DURANAR® coatings' have demonstrated over 30 years of exterior color and gloss retention on major architectural projects globally
By Oxide Type (Pigment Chemistry)
Oxide type segmentation divides the market into titanium dioxide, zinc oxide, iron oxide, chromate and other oxide pigments. Titanium dioxide dominates because of its high whiteness, opacity and UV resistance. Iron oxide is growing faster due to cost‑effectiveness, colour versatility and strong use in decorative paints. Zinc oxide serves niche roles in antimicrobial or UV‑blocking coatings. This breakdown guides pigment producers toward the chemical classes that capture value and meet regulatory, aesthetic and functional demands.
By Application (Surface & End‑Use)
Application segmentation includes exterior wall, interior wall, ceiling, floor and roof waterproof coatings. Exterior wall coatings account for the largest share since buildings require high‑performance protection against weather and UV exposure. Floor and roof waterproof coatings reveal rising demand in renovation and infrastructure sectors, showing fastest growth potential. The application analysis helps paint formulators and pigment suppliers align R&D and marketing efforts with surfaces where performance and aesthetics matter most. It also highlights opportunities in retrofit and commercial projects.
Segmentations:
By Product
- Polyurethane
- Acrylic
- Epoxy
- Polyester
- Alkyd
By Application
- Exterior Wall
- Interior Wall
- Ceiling
- Floor & Roof Waterproof Coatings
By Oxide Type
- Titanium Dioxide
- Zinc Oxide
- Iron Oxide
- Chromate & Other Oxides
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia‑Pacific Region
The Asia‑Pacific region held a market share of 42.3% in the Architectural Paint Oxide Market in 2024. It benefited from intensifying urbanisation, large‐scale infrastructure projects and rising disposable incomes in countries like China and India. Builders and developers in this region chose oxide‑based coatings for their high durability and strong weather resistance. Regulatory emphasis on eco‑friendly construction further increased demand for low‑VOC and sustainable pigment systems. Supply chains in the region matured, enabling faster local production and reducing lead times. Product makers targeted this region for custom formulations tailored to both new builds and renovation sectors.
North America Region
The North America region accounted for an estimated 28.5% share of the architectural paint oxide market in 2024. It experienced strong demand due to renovation trends, stringent environmental standards and growth in sustainable building paints. It featured a strong preference for coatings offering high performance, low VOC emissions and long surface lifetimes. Manufacturers invested in R&D to develop advanced oxide pigments and partnered with paint formulators to deliver region‑specific solutions. The mature construction market and replacement cycles further supported volume uptake. Regional suppliers emphasised quick delivery, local service and tailored colour palettes to maintain competitive edge.
Europe Region
Europe contributed roughly 30% of the global architectural paint oxide market share in 2024. Market growth came from strict regulatory frameworks for indoor air quality and building sustainability, which favoured oxide‑based coatings. It featured widespread renovation activity in heritage and commercial buildings, driving demand for coatings offering both aesthetics and functional performance. Manufacturers focused on high‑performance pigments suitable for complex substrates and demanding climates. Regional paint companies emphasised green credentials, reduced heavy‑metal content and lifecycle durability to meet buyer expectations. The competitive landscape encouraged consolidation and technology partnerships to expand regional reach.
Key Player Analysis:
- The Sherwin-Williams Company (U.S.)
- PPG Industries, Inc. (U.S.)
- Nippon Paints (India) Private Limited (India)
- Asian Paints (India)
- Akzo Nobel N.V. (Netherlands)
- Kansai Paint Co., Ltd. (Japan)
- DuPont (U.S.)
- BASF SE (Germany)
- RPM International Inc. (U.S.)
- Axalta Coating Systems Ltd. (U.S.)
- Jotun A/S (Norway)
- Berger Paints India Ltd. (India)
Competitive Analysis:
In the competitive landscape of the Architectural Paint Oxide Market, major players such as RPM International Inc. (U.S.), Axalta Coating Systems Ltd. (U.S.), Jotun A/S (Norway) and Berger Paints India Ltd. (India) dominate. These companies invest heavily in R&D to develop oxide‐pigment formulations that offer high durability and comply with low‑VOC requirements. They leverage broad distribution networks and established relationships with large‐scale construction and renovation firms. It forces smaller niche suppliers to differentiate through specialty products or regional focus. These market leaders maintain cost efficiency by scaling procurement and production of raw materials. They position their offerings around premium functionality and aesthetic appeal to capture higher margin segments. Stakeholders entering this market must anticipate strong brand competition and focus on innovation, service, or partnerships to carve out meaningful share.
Recent Developments:
- In October 2025, The Sherwin-Williams Company completed the acquisition of BASF’s Brazilian architectural paints business, Suvinil, enhancing its presence in the Latin American market.
- In July 2025, Nippon Paints (India) Private Limited, in collaboration with India Champions for the World Championship of Legends 2025, launched the n-SHIELD range of vehicle protection films.
Report Coverage:
The research report offers an in-depth analysis based on Product, Application, Oxide Type and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Demand will expand in emerging economies due to intensified urban construction projects.
- Suppliers will shift toward water‑based and low‑VOC oxide pigments to meet regulatory and consumer pressures.
- Product developers will integrate functional properties like UV reflection and antimicrobial performance into oxide pigments.
- Renovation and retrofit applications will create growth niches for premium oxide‑based coatings offering durability and aesthetics.
- Pigment manufacturers will invest in local sourcing and regional production hubs to reduce cost and lead‑time risks.
- Digital‑direct sales channels and DIY consumer segments will open new distribution pathways for oxide‑based paints.
- Partnerships between pigment producers and paint formulators will accelerate specialized product launches and market penetration.
- Sustainability credentials—including recyclability and reduced heavy‑metal content—will become key selection criteria for oxide pigments.
- Colour trends toward earthy, natural tones will boost demand for iron oxides and specialized mineral pigment blends.
- Raw‑material price volatility and supply‑chain constraints will drive innovation in alternative pigment chemistries and sourcing strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Architectural Paint Oxide Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate (CAGR) is the Architectural Paint Oxide Market projected to grow between 2024 and 2032?
Which Architectural Paint Oxide Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Architectural Paint Oxide Market?
Who are the leading companies in the Architectural Paint Oxide Market?
Which region commanded the largest share of the Architectural Paint Oxide Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Architectural Paint Oxide Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Architectural Paint Oxide Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,695.62 million → 2032: USD 2,356.52 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Architectural Paint Oxide Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Architectural Paint Oxide Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Architectural Paint Oxide Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Architectural Paint Oxide Market Drivers
- 3.3 Architectural Paint Oxide Market Restraints & Challenges
- 3.4 Architectural Paint Oxide Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Architectural Paint Oxide Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Architectural Paint Oxide Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Architectural Paint Oxide category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Architectural Paint Oxide Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Architectural Paint Oxide Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Architectural Paint Oxide market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Architectural Paint Oxide Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Architectural Paint Oxide Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Architectural Paint Oxide Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Architectural Paint Oxide (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Architectural Paint Oxide Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Architectural Paint Oxide Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Architectural Paint Oxide Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Architectural Paint Oxide Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Architectural Paint Oxide Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Architectural Paint Oxide Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Architectural Paint Oxide Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Architectural Paint Oxide Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Architectural Paint Oxide Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
