
Market Overview:
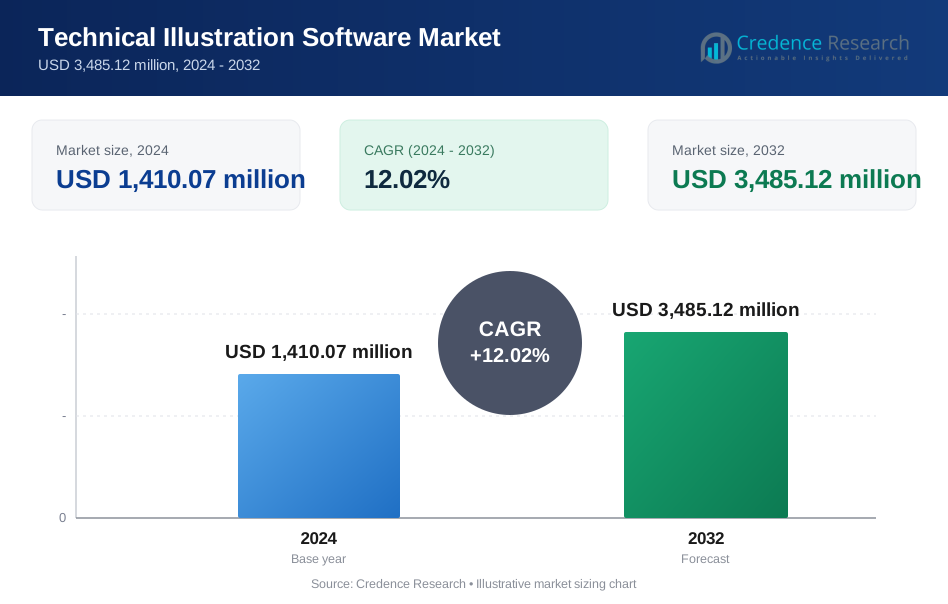
The Technical Illustration Software Market size was valued at USD 920.00 million in 2018 to USD 1,410.07 million in 2024 and is anticipated to reach USD 3,485.12 million by 2032, at a CAGR of 12.02% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Technical Illustration Software Market Size 2024 | USD 1,410.07 million |
| Technical Illustration Software Market, CAGR | 12.02% |
| Technical Illustration Software Market Size 2032 | USD 3,485.12 million |
Market growth is driven by rising demand for accurate visual documentation across manufacturing, aerospace, and automotive sectors. Enterprises rely on software to streamline service manuals, training content, and compliance materials. Integrated CAD tools, AR features, and cloud-based platforms enhance usability and reduce documentation errors. Digital transformation strategies and product complexity continue to push adoption. Cost savings from reduced training time and first-time fix improvements further support uptake. Technical illustration tools also aid multilingual publishing and version control. Vendors prioritize collaboration, scalability, and modular interfaces to serve diverse enterprise needs.
North America leads the market due to its advanced industrial base and early adoption of digital tools, with strong contributions from the U.S. and Canada. Europe follows closely, supported by strong usage in automotive and engineering segments across Germany, France, and the UK. Asia Pacific is emerging rapidly, driven by industrial expansion in China, India, and Southeast Asia. Latin America and the Middle East show moderate growth with increasing cloud adoption. Africa remains in early adoption stages but shows potential with growing digital infrastructure and industrial projects.

Market Insights:
- The Technical Illustration Software Market was valued at USD 920.00 million in 2018, reached USD 1,410.07 million in 2024, and is projected to hit USD 3,485.12 million by 2032, growing at a CAGR of 12.02%.
- North America led the market with a 32.4% share, supported by advanced industrial infrastructure, strong defense spending, and high adoption of digital documentation tools.
- Europe held the second-largest share at 21.1%, driven by strong demand from automotive and machinery manufacturers across Germany, France, and the UK.
- Asia Pacific followed with a 17.5% share and also recorded the fastest CAGR of 13.6%, fueled by rapid industrialization, digital transformation, and rising use of cloud-based solutions in China and India.
- The software segment dominated with the largest share due to integration with CAD tools, while the cloud-based (SaaS) deployment model gained momentum for its scalability and cost efficiency.
Market Drivers
Rising Adoption Across Manufacturing and Industrial Engineering Applications for Visual Documentation
Manufacturing firms adopt technical illustration tools to simplify equipment assembly and maintenance guides. The software helps convert complex engineering data into readable visuals. This improves workforce efficiency and reduces training time. Product lifecycle management benefits from consistent visual documentation. It enhances cross-functional communication across engineering, service, and marketing teams. The Technical Illustration Software Market grows as firms seek digital methods to replace static manuals. It plays a role in compliance, especially in regulated industries like aerospace and defense. Streamlined updates across product changes further support demand for digital illustration tools.
- For instance, Siemens Power Generation Services used DiSTI's VE Studio to develop a Virtual Maintenance Trainer (VMT) for the SGT-8000H gas turbine, reducing traditional 5-day hands-on training to 8 hours of self-paced exploration for novices.
Growing Demand for Precision and Accuracy in Product Representation in High-Risk Sectors
Industries like aviation, military, and heavy equipment require exact technical documentation. These sectors depend on precise illustrations for operational safety and compliance. The software ensures consistent representation of systems and assemblies. Operators use illustrations to reduce operational risk and downtime. It helps eliminate ambiguity in part identification, troubleshooting, and repair. In high-stakes sectors, visual clarity drives user trust and system reliability. The Technical Illustration Software Market gains traction where equipment complexity demands high detail. It strengthens after-sales service and technical support efficiency.
- For instance, Lockheed Martin employs technical illustration software integrated with CAD for F-35 joint strike fighter maintenance manuals, achieving over 90% first-time fix rates in field operations through precise part identification visuals.
Integration with CAD and 3D Modelling Software to Enable Seamless Workflow Management
The growing interoperability with CAD platforms boosts illustration software usage. Engineers import 3D designs directly into illustration tools for rapid visual rendering. This improves workflow speed while reducing manual rework. Integration simplifies version control across engineering and documentation teams. The Technical Illustration Software Market benefits from this CAD compatibility trend. It supports multiple file types and formats across hardware platforms. Cross-software collaboration enhances documentation consistency across global teams. Manufacturers value how this integration accelerates product readiness.
Digital Transformation and Shift Toward Paperless Technical Communication Environments
Companies embrace digital-first documentation strategies to meet sustainability goals. Printed manuals are replaced with interactive digital illustrations. This shift improves user access and supports multi-platform deployment. The Technical Illustration Software Market evolves to meet these digital trends. It enables updates in real-time, improving accuracy for end-users. Teams collaborate remotely with cloud-based platforms and annotation tools. Firms reduce operational costs by eliminating static documentation. These tools align with broader digitization in industry 4.0 environments.
Market Trends
Growing Use of Augmented Reality (AR) and Interactive Technical Illustrations in Field Services
Augmented reality enhances how field engineers access visual guides in real-time. Technicians use AR headsets to overlay instructions on machinery during repairs. This trend reduces error rates and training time for new hires. Interactive illustrations engage users better than static visuals. The Technical Illustration Software Market responds by adding AR content integration. Companies use this approach in sectors such as aerospace, automotive, and utilities. It supports remote diagnostics and guided maintenance tasks. AR-ready documentation becomes a key trend in improving service outcomes.
Increased Focus on Real-Time Collaboration and Remote Authoring Capabilities
Teams across geographies collaborate using cloud-hosted illustration platforms. Designers, engineers, and content developers work on shared projects simultaneously. Real-time tools improve version control and reduce update delays. The Technical Illustration Software Market supports these changes through integrated collaboration features. It enables quick annotation, markup, and publishing workflows. Remote access empowers teams during global product launches. Clients demand scalable solutions to manage large illustration libraries. This trend supports efficiency across distributed workforces.
- For instance, Siemens Teamcenter enables real-time collaboration across global teams on complex projects like gas turbines, streamlining version control through shared digital threads.
Surge in Customization Needs for Multi-Language and Region-Specific Documentation
Global businesses require tailored manuals to meet local language and regulatory norms. Software now includes translation support and multi-format output options. Firms generate localized illustrations without duplicating entire design processes. The Technical Illustration Software Market grows with these customization demands. It helps reduce localization time across product lines. Users expect interface elements, annotations, and symbols to adapt by region. Companies view this as a way to enhance user experience. It improves compliance and end-user satisfaction worldwide.
Emergence of Subscription-Based Licensing Models and Scalable Deployment Options
Enterprises shift from perpetual licenses to flexible subscription models. This allows scaling software use across projects and departments. The Technical Illustration Software Market reflects this preference in pricing and delivery models. Software providers offer tiered access based on user roles. Organizations manage costs better through predictable billing cycles. Cloud-native tools simplify deployment and maintenance. This trend supports agile documentation teams that need scalability. It encourages adoption among mid-sized firms and startups.
- For instance, Autodesk Fusion 360's subscription model supports scalable cloud deployment for engineering teams, enabling on-demand access without large upfront costs.
Market Challenges Analysis
High Learning Curve and Complexity in Software Adoption Across Non-Design Professionals
Despite growing demand, many users struggle with technical illustration software’s complexity. Non-design professionals such as technical writers or service staff face training hurdles. Mastering CAD imports, layer control, and 3D markup requires skill and time. The Technical Illustration Software Market must address this usability gap to expand faster. Complex user interfaces reduce adoption across small firms. Companies often incur high onboarding costs to train documentation teams. Feature-rich platforms may overwhelm users who need only basic illustration tools. This slows down adoption, especially in low-tech environments or regions.
Data Security Risks and Intellectual Property Protection in Cloud-Based Workflows
Cloud platforms increase productivity but introduce data protection concerns. Companies hesitate to host proprietary product data on third-party servers. The Technical Illustration Software Market faces security scrutiny in IP-sensitive industries. Software vendors must invest in encryption, access control, and data governance. Breaches or leaks may expose product blueprints and confidential drawings. These risks limit cloud adoption for military, aerospace, and defense contractors. Regulatory compliance becomes challenging across cross-border operations. Security constraints may delay digital documentation transitions.

Market Opportunities
Growing Demand from Small and Medium Enterprises in Emerging Economies for Affordable Tools
SMEs in emerging economies seek affordable digital tools to modernize documentation. These businesses look for lightweight, cloud-based platforms with easy onboarding. The Technical Illustration Software Market can expand by targeting this demand. Vendors that offer simplified tools with lower price points gain traction. Market expansion in Latin America, Southeast Asia, and Africa presents strong potential. Localization, ease of use, and integration support will be key.
Rise in Demand for Mobile-Optimized Illustration Viewing Across Service and Field Teams
Field technicians and mobile workers require instant access to repair visuals. Mobile-friendly tools that allow zoom, markup, and offline access grow in relevance. The Technical Illustration Software Market evolves to meet these user behaviors. Opportunities exist in creating responsive design formats and lightweight viewers. This trend supports better service outcomes and boosts field accuracy.
Market Segmentation Analysis:
By component, the technical Illustration Software Market is segmented by component into software and services. Software holds the major share due to growing demand for advanced authoring tools, 3D modeling, and integrated publishing features. Services support deployment, customization, and user training, gaining traction among enterprises seeking smooth implementation and workflow alignment.
By deployment type, desktop/on-premise solutions dominate in industries with strict data control needs, such as defense and aerospace. However, cloud-based (SaaS) deployment is expanding rapidly, supported by lower upfront costs, remote accessibility, and easier scalability for cross-functional teams.
- For instance, Dassault Systèmes’ 3DEXPERIENCE platform, used by Vertical Aerospace, integrates design, simulation, and product data management tools to streamline full aircraft structure development and documentation. CATIA Composer within the platform enables the creation of technical illustrations directly from 3D models.
By end-users, the automotive segment leads due to consistent demand for repair manuals, training content, and compliance documentation. Aerospace and defense require precision visuals for operational safety and maintenance. Machinery manufacturing adopts technical illustration to simplify part catalogs and assembly guides. The technical documentation and medical devices segment relies on visual clarity to support usability, safety, and regulatory needs.
- For instance, Zuri Helicopter uses Dassault Systèmes’ 3DEXPERIENCE cloud platform with CATIA to design its VTOL aircraft and streamline collaboration between engineers and suppliers across development and documentation workflows.
By enterprise size, large enterprises contribute the highest share due to higher documentation volume and complex workflow requirements. Small and medium enterprises (SMEs) show strong potential growth as cloud-based tools become more affordable and user-friendly. The market adapts to SME needs through simplified interfaces and modular pricing models.
Segmentation:
By Component Segment
- Software
- Services
By Deployment Type Segment
- Desktop/On-Premise
- Cloud-Based (SaaS)
By End-User Segment
- Automotive
- Aerospace & Defense
- Machinery Manufacturing
- Technical Documentation and Medical Devices
By Enterprise Size Segment
- Small and Medium Enterprises (SMEs)
- Large Enterprises
By Regional Segment
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Regional Analysis:
North America
The North America Technical Illustration Software Market size was valued at USD 381.80 million in 2018 to USD 578.97 million in 2024 and is anticipated to reach USD 1,429.25 million by 2032, at a CAGR of 12.0% during the forecast period. North America holds the largest market share, accounting for 32.4% of the global Technical Illustration Software Market in 2024. The region benefits from a strong presence of aerospace, automotive, and advanced manufacturing industries. Leading software vendors operate in the U.S., driving innovation and early technology adoption. High demand for cloud-based solutions and interactive manuals fuels growth. The defense sector supports spending on precise visual documentation. Technical training and support functions are increasingly digitized across enterprises. Canada and Mexico contribute to regional expansion through industrial modernization. The region continues to invest in AR-based service tools and mobile-first technical communication.
Europe
The Europe Technical Illustration Software Market size was valued at USD 254.66 million in 2018 to USD 375.89 million in 2024 and is anticipated to reach USD 880.18 million by 2032, at a CAGR of 11.3% during the forecast period. Europe represents 21.1% of the global market share in 2024. The region shows strong adoption in automotive, machinery, and aerospace sectors. Germany, France, and the UK lead in deploying illustration tools within digital manufacturing workflows. European firms invest in real-time documentation to meet complex regulatory standards. Sustainability goals drive the shift from printed manuals to digital assets. Engineering teams use CAD-integrated software for multilingual technical publishing. SMEs increasingly adopt scalable, cloud-based platforms. Eastern Europe presents new growth opportunities through localized software offerings.
Asia Pacific
The Asia Pacific Technical Illustration Software Market size was valued at USD 194.12 million in 2018 to USD 312.82 million in 2024 and is anticipated to reach USD 865.36 million by 2032, at a CAGR of 13.6% during the forecast period. Asia Pacific holds 17.5% of the market in 2024 and shows the fastest growth. Rapid industrialization across China, India, and Southeast Asia drives software demand. Manufacturers adopt illustration tools to support after-sales service and equipment manuals. Government-led digital initiatives accelerate software penetration in local industries. Cloud platforms gain popularity among mid-sized firms. Multinational OEMs expand local operations, requiring regionalized technical content. Mobile-first solutions see rising demand among field teams. Japan and South Korea lead in adopting AR-based illustration platforms. Asia Pacific will play a major role in global volume expansion.
Latin America
The Latin America Technical Illustration Software Market size was valued at USD 54.28 million in 2018 to USD 82.33 million in 2024 and is anticipated to reach USD 187.74 million by 2032, at a CAGR of 10.9% during the forecast period. Latin America accounts for 4.6% of the market in 2024. Brazil dominates regional adoption, supported by a growing machinery and automotive base. Manufacturers use technical illustration tools to improve documentation accuracy and reduce service costs. Local enterprises adopt cloud-based models due to lower deployment barriers. Language localization features gain traction across Spanish and Portuguese-speaking markets. The region sees steady investment in digital design ecosystems. Service companies use these platforms for maintenance guides and client-facing materials. Argentina and Chile show increasing demand among industrial SMEs. Vendor partnerships with regional resellers strengthen market access.
Middle East
The Middle East Technical Illustration Software Market size was valued at USD 19.32 million in 2018 to USD 26.22 million in 2024 and is anticipated to reach USD 52.64 million by 2032, at a CAGR of 9.2% during the forecast period. Middle East holds 1.5% market share in 2024. The region witnesses rising interest from energy, aerospace, and infrastructure sectors. Governments push digital transformation agendas across Gulf countries. Defense and aviation programs invest in visual documentation and maintenance training. The Technical Illustration Software Market gains attention from public sector modernization efforts. UAE and Saudi Arabia lead in terms of software adoption. Data security concerns slow down cloud transitions in regulated sectors. Local system integrators support enterprise deployments. Future growth will depend on tech partnerships and customized features.
Africa
The Africa Technical Illustration Software Market size was valued at USD 15.82 million in 2018 to USD 33.85 million in 2024 and is anticipated to reach USD 69.94 million by 2032, at a CAGR of 9.0% during the forecast period. Africa contributes 1.9% to the global market in 2024. South Africa leads regional activity, driven by demand in automotive, rail, and mining industries. Enterprises adopt technical illustration tools to improve equipment maintenance and workforce training. Growth remains moderate due to infrastructure gaps and low digital maturity. SaaS-based models lower entry barriers for SMEs. Nigeria, Kenya, and Egypt emerge as next growth nodes. International software vendors explore distributor-led expansion strategies. Local language support and mobile accessibility remain key adoption enablers. Africa's market shows long-term potential through industrial modernization.
Key Player Analysis:
- PTC (Parametric Technology Corporation)
- Corel Corporation
- Adobe Inc.
- Dassault Systèmes
- Autodesk, Inc.
- Siemens AG
- QuadriSpace Corporation
- Canvas GFX, Inc.
- Lattice Technology, Inc.
- Cortona3D
- SAP SE
- EON Reality
Competitive Analysis:
The Technical Illustration Software Market features a mix of global software giants and niche players competing on innovation, integration, and scalability. PTC, Adobe, Corel, and Autodesk lead with comprehensive platforms that support 3D modeling, AR features, and CAD compatibility. Dassault Systèmes and Siemens offer strong industrial integration for engineering-heavy use cases. Canvas GFX, QuadriSpace, and Cortona3D serve specialized needs in defense, aerospace, and manufacturing sectors. The Technical Illustration Software Market reflects increasing vendor focus on cloud-based deployment, real-time collaboration, and mobile-friendly tools. Companies invest in UI simplification and cross-platform functionality to expand reach across enterprise sizes. Strategic moves include product enhancements, regional expansion, and partnerships with OEMs and system integrators. Competitive intensity rises as more vendors enter with modular, subscription-based offerings. Global firms differentiate through feature-rich suites and multilingual publishing capabilities, while smaller players focus on cost-efficiency and customization. The market evolves through continuous updates and end-user feedback integration.
Recent Developments:
- In November 2025, PTC announced a major acquisition deal involving its industrial connectivity and IoT businesses. TPG agreed to acquire PTC's Kepware and ThingWorx businesses to accelerate growth in manufacturing connectivity.
- In October 2025, Adobe Inc. expanded its strategic partnership with Google Cloud. The collaboration integrates Google's AI models like Gemini into Adobe apps such as Firefly and Photoshop for advanced creative content generation
- In April 2025, PTC acquired IncQuery Group to enhance its application lifecycle management capabilities and launched Codebeamer 3.0 with a focus on AI integration and SaaS solutions.
Report Coverage:
The research report offers an in-depth analysis based on Component Segment, Deployment Type Segment, End-User Segment and Enterprise Size Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Cloud-based deployment will dominate new implementations, driven by demand for scalable and remote-ready solutions.
- Technical illustration tools will increasingly integrate AR and 3D visualization to support immersive maintenance and training experiences.
- Automotive, aerospace, and machinery sectors will remain the highest users, focusing on service manuals and compliance documentation.
- SMEs will adopt modular platforms with simplified interfaces to meet cost and usability expectations.
- Mobile-first technical illustration tools will gain traction among field technicians and distributed service teams.
- Real-time collaboration features will become standard, supporting cross-functional and cross-border documentation teams.
- Vendors will expand localization features to meet growing global demand for multilingual technical content.
- Regulatory environments in aerospace and medical sectors will drive investments in accurate and compliant visual documentation.
- Competitive differentiation will depend on CAD integration, UI/UX design, and automation in content updates.
- Emerging regions like Asia Pacific will lead in volume growth, supported by industrial expansion and digitalization efforts.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Adoption in Manufacturing and Industrial Engineering
Manufacturing and industrial engineering sectors increasingly use technical illustration software to create accurate, up-to-date visual documentation for assembly, maintenance, and compliance, improving workforce efficiency and reducing training time.
Demand for Precision in High-Risk Sectors
Aerospace, defense, and heavy equipment industries require highly precise technical illustrations to ensure operational safety, regulatory compliance, and effective maintenance, driving adoption of advanced illustration tools.
Integration with CAD and 3D Modeling Platforms
Seamless interoperability with CAD and 3D modeling software enables faster, more accurate creation of technical visuals, streamlining workflows and reducing manual rework for engineering and documentation teams.
Digital Transformation and Paperless Documentation
Organizations are shifting to digital-first documentation strategies, replacing static manuals with interactive, cloud-based illustrations that support real-time updates, remote collaboration, and multi-platform access.
Growth of AR and Mobile-Optimized Solutions
The integration of augmented reality and mobile-friendly viewing capabilities enhances field service efficiency and training, making technical illustration tools more valuable for distributed and on-the-go teams.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Technical Illustration Software Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Technical Illustration Software Market projected to grow between 2024 and 2032?
Which Technical Illustration Software Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Technical Illustration Software Market?
Who are the leading companies in the Technical Illustration Software Market?
Which region commanded the largest share of the Technical Illustration Software Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Automotive
- 1.2.2 Aerospace & Defense
- 1.2.3 Machinery Manufacturing
- 1.2.4 Technical Documentation and Medical Devices
- 1.3 By Component
- 1.3.1 Software
- 1.3.2 Services
- 1.4 By Deployment Type
- 1.4.1 Desktop/On-Premise
- 1.4.2 Cloud-Based (SaaS)
- 1.5 By Enterprise Size
- 1.5.1 Small and Medium Enterprises (SMEs)
- 1.5.2 Large Enterprises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,410.07 million → 2032: USD 3,485.12 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Technical Illustration Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Technical Illustration Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Technical Illustration Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Technical Illustration Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Technical Illustration Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Technical Illustration Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Technical Illustration Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Technical Illustration Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,410.07 million → 2032: USD 3,485.12 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Technical Illustration Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Automotive
- 12.3.6.2 Aerospace & Defense
- 12.3.6.3 Machinery Manufacturing
- 12.3.6.4 Technical Documentation and Medical Devices
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Software
- 12.4.6.2 Services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Desktop/On-Premise
- 12.5.6.2 Cloud-Based (SaaS)
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Enterprise Size - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Small and Medium Enterprises (SMEs)
- 12.6.6.2 Large Enterprises
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Technical Illustration Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Technical Illustration Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Technical Illustration Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Technical Illustration Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 PTC (Parametric Technology Corporation)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Corel Corporation
- 18.4 Adobe Inc.
- 18.5 Dassault Systèmes
- 18.6 Autodesk, Inc.
- 18.7 Siemens AG
- 18.8 QuadriSpace Corporation
- 18.9 Canvas GFX, Inc.
- 18.10 Lattice Technology, Inc.
- 18.11 Cortona3D
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

