
Market Overview:
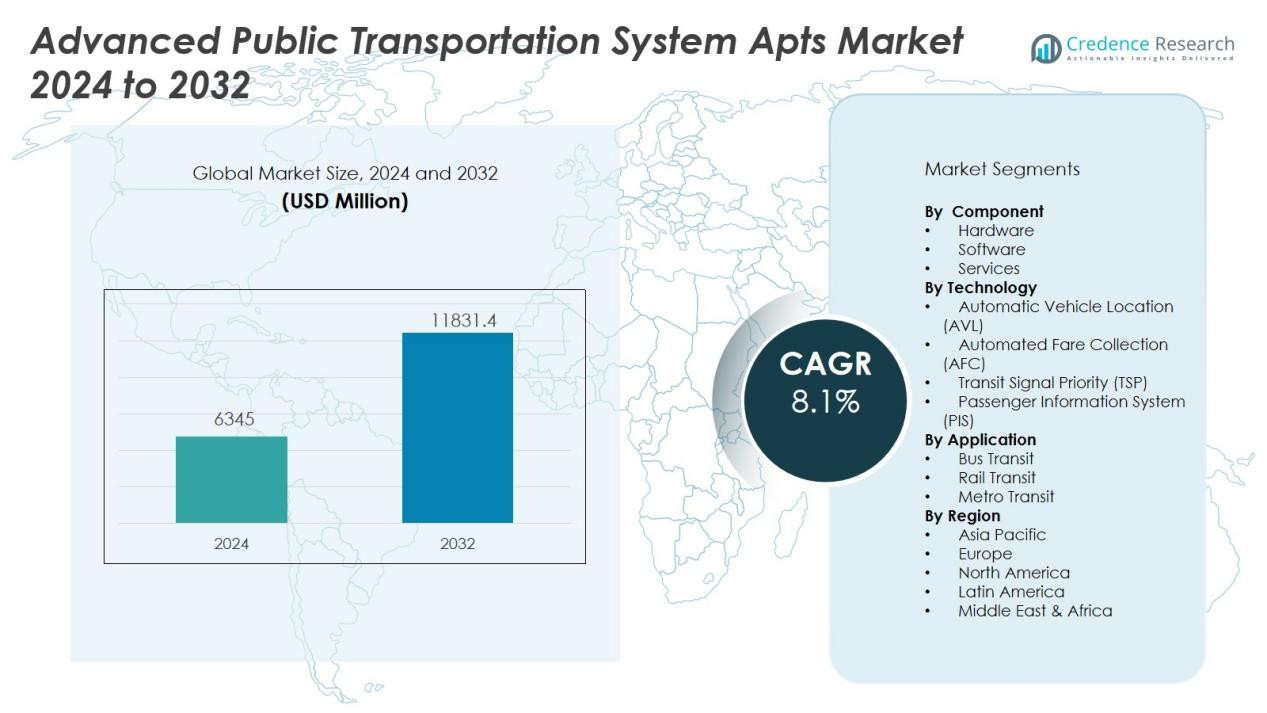
The Advanced Public Transportation System (APTS) Market size was valued at USD 6345 million in 2024 and is anticipated to reach USD 11831.4 million by 2032, at a CAGR of 8.1 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Advanced Public Transportation System Market Size 2024 | USD 6345 Million |
| Advanced Public Transportation System Market, CAGR | 8.1 % |
| Advanced Public Transportation System Market Size 2032 | USD 11831.4 Million |
Market growth is primarily driven by increasing urbanization, growing demand for efficient mass transit systems, and the rising need to reduce traffic congestion and emissions. Governments and transportation authorities are investing in intelligent transport systems (ITS) to improve mobility, enhance commuter experience, and optimize operational costs. Technological advancements such as AI-powered traffic management, IoT-enabled monitoring systems, and mobile ticketing platforms are further propelling the market forward. The integration of APTS with electric and autonomous public transport fleets also supports long-term growth potential.
Regionally, North America leads the APTS market, driven by early technology adoption, supportive policy frameworks, and strong public infrastructure funding. Europe follows, with substantial investments in eco-friendly transportation and regulatory alignment. The Asia-Pacific region is witnessing the fastest growth, led by rapid urban expansion, government initiatives for smart mobility, and infrastructure modernization in countries such as China, India, and Japan.
Market Insights:
- The APTS market was valued at USD 6345 million in 2024 and is expected to reach USD 11831.4 million by 2032, reflecting strong demand for intelligent transit solutions.
- Urbanization and population growth are key drivers, prompting city authorities to invest in efficient mass transit systems that alleviate congestion and emissions.
- Government initiatives and smart city projects continue to inject capital into intelligent transport systems (ITS), supporting advanced fare collection, vehicle tracking, and predictive analytics.
- Integration of AI, IoT, and mobile platforms enhances real-time communication, optimizes operations, and improves commuter satisfaction.
- High implementation and maintenance costs challenge small municipalities and financially constrained regions, limiting broader adoption of APTS.
- North America leads the market with a 38% share in 2024, backed by strong infrastructure, early adoption, and policy support for sustainable mobility.
- Asia-Pacific remains the fastest-growing region, driven by infrastructure modernization, smart city expansion, and large-scale investments in countries such as China, India, and Japan.
Market Drivers:
Increasing Urbanization Accelerates Adoption of Advanced Transportation Solutions:
Rapid urbanization is a primary driver for the advanced public transportation system APTS market. Expanding urban populations create unprecedented demand for efficient and reliable transit systems. Cities face rising congestion and pollution challenges, pushing authorities to adopt advanced technologies to optimize public transportation networks. The integration of real-time passenger information and automated fare collection systems significantly enhances service reliability, thereby encouraging greater public transit usage.
- For instance, Transport for London’s Oyster gates can process up to 40 people per minute, accelerating passenger flow through barriered stations.
Government Initiatives and Smart City Investments Foster Market Growth:
Government initiatives aimed at developing smart and sustainable urban environments strongly support the advanced public transportation system APTS market. Authorities allocate substantial funds toward infrastructure modernization projects to improve public transit efficiency and reduce environmental impact. Policies promoting intelligent transportation solutions attract significant private-sector investments, accelerating technology deployment. These targeted investments empower transportation agencies to adopt innovative systems and technologies, creating favorable conditions for market expansion.
- For instance, Transport for London deployed Countdown real-time displays at 2,500 bus stops, reducing the waiting-time value multiplier from 2.5× to 2.0× and improving perceived wait-time accuracy by 20%.
Rising Demand for Improved Commuter Experience Stimulates Technology Integration:
Growing commuter expectations for enhanced travel experiences drive the advanced public transportation system APTS market forward. Passengers increasingly demand real-time transit information, comfortable journeys, and reliable connectivity. Operators respond by deploying advanced solutions such as vehicle tracking systems, automated ticketing, and mobile-based communication platforms. This focus on customer satisfaction improves passenger engagement and increases overall public transport utilization rates.
Technological Advancements Boost Market Momentum:
Continuous innovation and technological breakthroughs propel the advanced public transportation system APTS market. Advances in artificial intelligence, Internet of Things (IoT), and data analytics enable sophisticated transit management and monitoring solutions. Intelligent traffic management, predictive analytics, and smart signaling systems optimize operational efficiency and reduce service disruptions. These advancements enhance the capability and performance of public transport systems, strengthening market demand.
Market Trends:
Integration of Artificial Intelligence and IoT Technologies Enhances Operational Efficiency:
The integration of artificial intelligence (AI) and Internet of Things (IoT) solutions marks a significant trend within the advanced public transportation system APTS market. AI-driven analytics facilitate real-time monitoring and predictive maintenance, enabling transit operators to enhance fleet reliability and reduce downtime. IoT-based sensors installed in vehicles and infrastructure provide crucial data on passenger flow, vehicle status, and route optimization. This data-driven approach allows agencies to make informed decisions, improve scheduling accuracy, and streamline operations. Enhanced connectivity through IoT also supports real-time passenger information systems, creating seamless commuter experiences. Transit authorities increasingly adopt AI and IoT innovations to address operational challenges effectively.
- For instance, Hitachi’s 360Flow solution aggregates real-time sensor and camera feeds across bus and rail networks, delivering passenger-flow counts with over 95 percent accuracy to optimize vehicle deployment.
Growing Emphasis on Sustainable and Electric Public Transport Systems:
The rising emphasis on sustainable transportation solutions influences the advanced public transportation system APTS market significantly. Governments and transit agencies globally prioritize the shift toward electric buses and low-emission public transport fleets. Advanced management solutions integrated into electric and hybrid systems optimize energy usage, monitor battery performance, and manage charging infrastructure efficiently. Cities implement these technologies to meet stringent emission standards, reduce environmental impact, and promote eco-friendly mobility. Electric public transport solutions supported by advanced systems deliver cost savings through lower energy consumption and reduced maintenance requirements. Investments in sustainable infrastructure projects continue to drive the transition toward cleaner public transit options.
- For instance: BYD has delivered 70,000 pure electric buses worldwide, whose fleets have collectively covered 5.5 billion electric kilometers.
Market Challenges Analysis:
High Implementation Costs and Financial Constraints Limit Market Adoption:
High initial costs and significant capital investments pose substantial challenges to the advanced public transportation system APTS market. Public transport agencies often face financial limitations that restrict their capacity to deploy comprehensive advanced transit solutions. Procuring advanced technologies such as real-time monitoring systems, automated fare collection, and integrated communication networks require substantial upfront funding. Smaller municipalities and transit authorities, in particular, experience difficulties due to limited budgets and competing financial priorities. Maintenance and operational expenditures associated with sophisticated systems further strain financial resources. These cost barriers deter broader market penetration, especially in regions with constrained funding sources.
Technical Complexity and Interoperability Issues Impact System Integration:
The advanced public transportation system APTS market faces notable hurdles from technical complexity and integration difficulties. Diverse technologies, standards, and platforms create interoperability challenges when merging new solutions with legacy infrastructure. Transportation authorities frequently encounter obstacles while attempting to unify various transit modes, data systems, and operational processes. Skilled technical expertise required for installation and maintenance of complex systems remains scarce, leading to implementation delays and inefficiencies. Overcoming these technical barriers requires considerable time, effort, and resources from agencies. Persistent interoperability issues complicate seamless service delivery, thereby impacting user satisfaction and system efficiency.
Market Opportunities:
Growing Integration with Autonomous Vehicles Opens New Opportunities:
The advanced public transportation system APTS market benefits from increasing integration with autonomous vehicle technologies. Transit authorities actively explore autonomous buses and shuttles to enhance operational efficiency and passenger safety. Autonomous technology implementation reduces human errors, optimizes fuel usage, and enables precise scheduling. Adoption of driverless vehicles allows transport operators to extend service hours and coverage areas economically. Public-private partnerships encourage investments in autonomous transit infrastructure, generating additional market opportunities. These technological integrations position the market strategically, creating avenues for sustained growth and innovation in urban mobility.
Expansion in Emerging Markets Presents Significant Growth Prospects:
Emerging markets offer considerable opportunities for the advanced public transportation system APTS market. Rapid urbanization and increased infrastructure investment in regions such as Asia-Pacific, Latin America, and Africa enhance demand for efficient transit solutions. Government initiatives promoting smart transportation projects and sustainable urban mobility contribute to market growth in these regions. Large-scale transit projects, backed by international funding agencies, foster implementation of advanced transportation technologies. Untapped markets with expanding middle-class populations provide fresh customer bases for advanced transit solutions. Vendors and technology providers capitalize on these regions by offering customized, cost-effective solutions tailored to local transportation needs.
Market Segmentation Analysis:
By Component:
The advanced public transportation system APTS market is segmented by component into hardware, software, and services. Hardware dominates this segment due to high adoption of sensors, automated fare collection systems, and real-time tracking devices. Software components, including predictive analytics and transit management applications, witness increasing demand among transit authorities seeking operational efficiency. Services such as system integration, training, and maintenance also hold notable market potential, driven by the complexity of implementing advanced transportation technologies.
- For instance, Cubic Transportation Systems delivered over 1,200 pieces of fare collection hardware-including mobile validators, driver control units, and external modems-to Metro Vancouver’s HandyDART paratransit fleet of 347 vehicles, with installations on three buses completed as of March 2021.
By Technology:
Based on technology, the advanced public transportation system APTS market segments into Automatic Vehicle Location (AVL), Automated Fare Collection (AFC), Transit Signal Priority (TSP), and Passenger Information Systems (PIS). AVL technology leads this segment by providing real-time vehicle tracking, improving transit reliability. AFC solutions gain traction among transit operators aiming to streamline fare management and minimize revenue losses. The adoption of TSP technology grows steadily, enhancing traffic flow and reducing delays at intersections. Passenger Information Systems increasingly become essential, providing commuters with accurate travel data and improving the user experience.
- For instance, TriMet’s AVL implementation archives over 500,000 stop and event data records each day, enabling planners to analyze route performance and adjust schedules based on exact vehicle movements.
By Application:
The advanced public transportation system APTS market, segmented by application, includes bus transit, rail transit, and metro transit systems. Bus transit dominates the application segment, reflecting extensive deployment in urban and suburban regions to reduce congestion. Metro transit applications steadily expand due to significant infrastructure investments and demand for high-capacity transit solutions in dense urban areas. Rail transit leverages advanced technologies to enhance scheduling accuracy, safety, and passenger comfort, reinforcing its market presence globally.
Segmentations:
By Component:
- Hardware
- Software
- Services
By Technology:
- Automatic Vehicle Location (AVL)
- Automated Fare Collection (AFC)
- Transit Signal Priority (TSP)
- Passenger Information System (PIS)
By Application:
- Bus Transit
- Rail Transit
- Metro Transit
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America :
North America holds a 38% share of the advanced public transportation system APTS market in 2024, driven by well-established infrastructure and proactive policy frameworks. The region demonstrates early technology adoption, fostering advanced transit solutions and smart mobility initiatives. The U.S. and Canada invest significantly in intelligent transport systems (ITS), incorporating advanced traffic management and real-time monitoring solutions. Government policies actively support sustainable transportation programs and fund infrastructure modernization. Collaborative public-private partnerships accelerate technology integration, enhancing regional competitiveness. High commuter expectations for efficient and reliable transportation further reinforce market growth in North America.
Europe:
system APTS market in 2024, supported by substantial investments in eco-friendly transit solutions. Regulatory measures encourage adoption of clean and energy-efficient transportation systems across major European cities. Countries including Germany, France, and the United Kingdom implement advanced technologies to optimize traffic flow, passenger comfort, and safety. The region prioritizes electric mobility initiatives, deploying intelligent systems for electric fleet management and charging infrastructure. European Union funding programs provide critical support to regional transport modernization and digitalization projects. Increasing urban populations across European cities reinforce the demand for advanced public transit services.
Asia-Pacific :
Asia-Pacific region is witnessing the fastest growth rate within the advanced public transportation system APTS market, driven by rapid urbanization and infrastructure development. Emerging economies such as China and India actively pursue smart city programs, enhancing urban mobility through innovative transit technologies. Government-led initiatives significantly boost investments in advanced public transit systems, aiming to ease congestion and reduce emissions. Japan, South Korea, and Singapore showcase advanced transit management systems and continue to expand intelligent infrastructure deployments. Extensive public and private investments in transit infrastructure modernization drive market opportunities throughout the region. Expansion of metropolitan areas further amplifies demand for reliable and efficient public transportation solutions.
Key Player Analysis:
- Alstom
- Garmin
- Thales Group
- Hitachi Rail
- Cubic
- EasyMile
- Siemens Mobility
- Indra
- Kapsch
Competitive Analysis:
The advanced public transportation system APTS market is characterized by intense competition among major technology providers and transit solutions specialists. Key players include Alstom, Garmin, Thales Group, Hitachi Rail, Cubic, and EasyMile, which leverage technological innovation and extensive market presence to maintain competitive advantage. Alstom and Hitachi Rail actively deploy advanced signaling, automation, and passenger information systems, strengthening their positions in large-scale transit projects globally. Garmin and Cubic differentiate through expertise in integrated fare collection, real-time passenger tracking, and comprehensive data analytics solutions. Thales Group consistently invests in cybersecurity, automation, and integrated transportation management platforms to enhance system reliability and safety. EasyMile leads in autonomous transit solutions, implementing driverless vehicle technologies across various public transportation networks. Strategic partnerships, continuous product innovation, and targeted expansion strategies significantly influence competitive dynamics, enabling these companies to capture market share effectively.
Recent Developments:
- In July 2025, Garmin announced the acquisition of MYLAPS, a Dutch firm specializing in advanced timing technology for racing events, expanding Garmin's offerings in athlete performance solutions.
- In June 2025, Alstom opened a new state-of-the-art Plant 4 facility in Hornell, NY, strengthening U.S. rail manufacturing capabilities.
- In May 2025, Thales launched the TRAC SIGMA multi-mission Primary Surveillance Radar for approach and long-range air traffic surveillance, offering advanced 3D detection in congested airspace.
Market Concentration & Characteristics:
The advanced public transportation system APTS market exhibits moderate concentration, dominated by key global and regional players. Prominent companies leverage technological expertise, established brand presence, and strategic partnerships to maintain competitive positions. The market displays strong innovation characteristics, driven by continuous advancements in artificial intelligence, IoT, and data analytics. Competitive dynamics focus heavily on product differentiation, cost-efficiency, and system interoperability. Players actively pursue strategic collaborations, mergers, and acquisitions to expand geographic footprints and enhance technological capabilities. New entrants face challenges from high investment requirements, technological complexity, and the need for regulatory compliance, limiting rapid shifts in market concentration.
Report Coverage:
The research report offers an in-depth analysis based on Component, Technology, Application, Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Advanced artificial intelligence and predictive analytics will transform public transit operations, delivering smarter scheduling and improved reliability.
- It will integrate real-time passenger feedback mechanisms to enhance traveler satisfaction and system responsiveness.
- Seamless interoperability between modes - buses, trams, subways, autonomous shuttles - will ensure unified and efficient mobility networks.
- It will facilitate wider deployment of edge computing solutions for faster decision-making and reduced latency in transit management.
- Integration with electric and autonomous vehicle fleets will become standard, improving energy efficiency and passenger safety.
- Smart fare systems will adopt contactless, mobile and biometric authentication methods for secure and seamless boarding.
- It will leverage 5G connectivity and high-speed networks to enable high-volume data exchanges and support expansive IoT deployments.
- Transit authorities will adopt modular, scalable platforms to extend system functionality and support future upgrades easily.
- Integration with municipal smart city platforms will enable holistic traffic management and environmental monitoring.
- It will support flexible mobility-as-a-service (MaaS) ecosystems, combining public and private transport options through unified platforms.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Urbanization and Population Growth
Expanding urban populations are straining existing transit infrastructure, prompting city authorities to invest in advanced public transportation systems that can efficiently manage increased commuter volumes and reduce congestion.
Government Initiatives and Smart City Investments
Substantial government funding and policy support for intelligent transport systems and smart city projects are accelerating the deployment of advanced fare collection, vehicle tracking, and predictive analytics in public transit networks.
Technological Advancements in AI and IoT
The integration of artificial intelligence and IoT technologies enables real-time monitoring, predictive maintenance, and data-driven decision-making, significantly improving operational efficiency and commuter experience in public transportation.
Demand for Sustainable and Eco-Friendly Transit
Rising environmental concerns and regulatory mandates are driving the adoption of electric and low-emission public transport fleets, with advanced management systems optimizing energy use and supporting the shift toward sustainable urban mobility.
Focus on Enhanced Commuter Experience
Increasing expectations for real-time information, seamless ticketing, and reliable service are pushing transit operators to implement advanced solutions that improve passenger satisfaction and boost public transport utilization rates.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the value of the advanced public transportation system APTS market in 2024, and what is its projected value by 2032?
What are the primary factors driving the growth of the advanced public transportation system APTS market?
Which region held the largest share of the advanced public transportation system APTS market in 2024?
What challenges restrict the widespread adoption of advanced public transportation systems?
Which technologies are gaining traction within the advanced public transportation system APTS market?
Who are the key players operating in the advanced public transportation system APTS market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Hardware
- 1.2.2 Software
- 1.2.3 Services
- 1.3 By Technology
- 1.3.1 Automatic Vehicle Location (AVL)
- 1.3.2 Automated Fare Collection (AFC)
- 1.3.3 Transit Signal Priority (TSP)
- 1.3.4 Passenger Information System (PIS)
- 1.4 By Application
- 1.4.1 Bus Transit
- 1.4.2 Rail Transit
- 1.4.3 Metro Transit
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6345 million → 2032: USD 11831.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Advanced Public Transportation System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Advanced Public Transportation System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Advanced Public Transportation System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Advanced Public Transportation System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Advanced Public Transportation System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Advanced Public Transportation System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Advanced Public Transportation System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Advanced Public Transportation System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6345 million → 2032: USD 11831.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Advanced Public Transportation System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Software
- 12.3.7.3 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automatic Vehicle Location (AVL)
- 12.4.7.2 Automated Fare Collection (AFC)
- 12.4.7.3 Transit Signal Priority (TSP)
- 12.4.7.4 Passenger Information System (PIS)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Bus Transit
- 12.5.7.2 Rail Transit
- 12.5.7.3 Metro Transit
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Advanced Public Transportation System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Advanced Public Transportation System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Advanced Public Transportation System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Advanced Public Transportation System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Alstom
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Garmin
- 18.4 Thales Group
- 18.5 Hitachi Rail
- 18.6 Cubic
- 18.7 EasyMile
- 18.8 Siemens Mobility
- 18.9 Indra
- 18.10 Kapsch
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

