
Market Overview
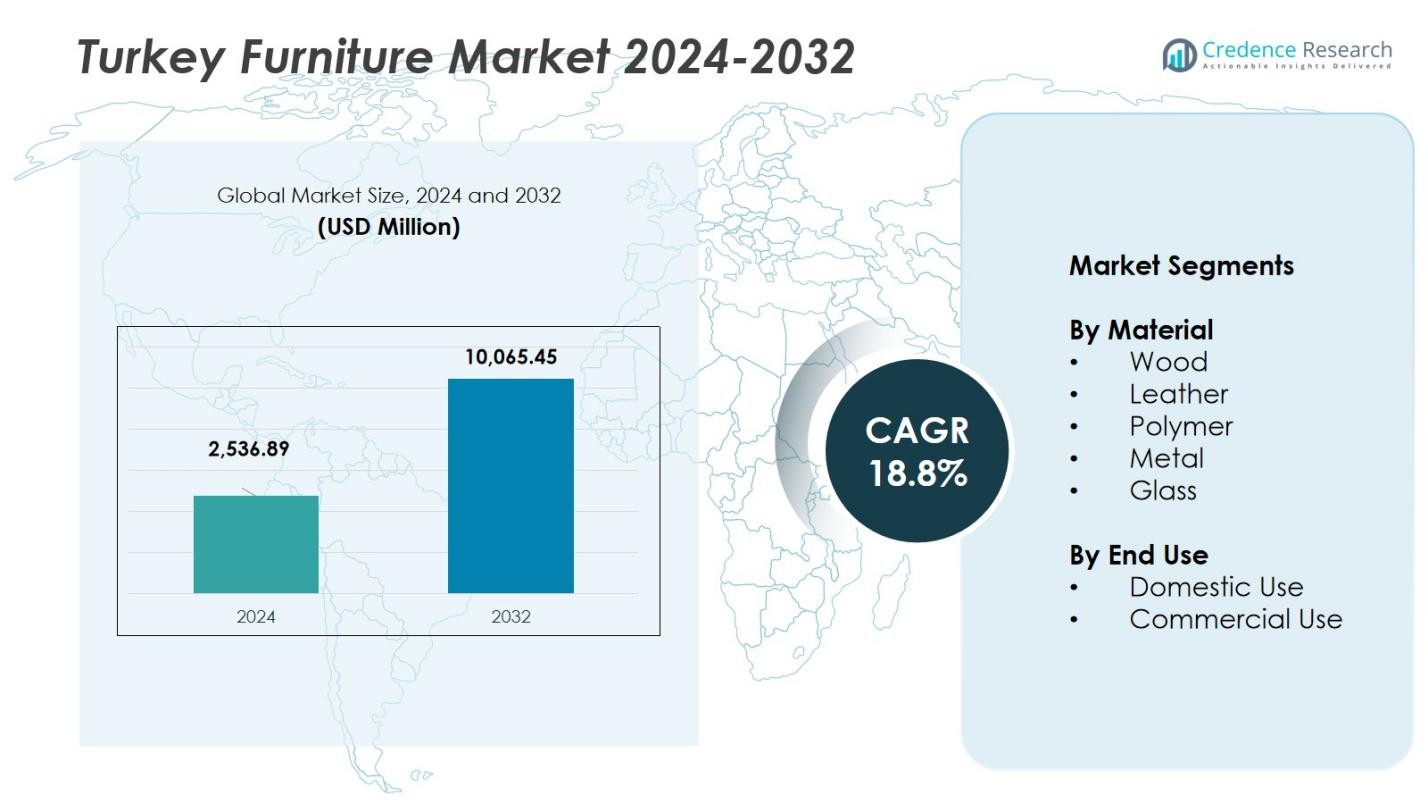
The Turkey Furniture Market size was valued at USD 2,536.89 Million in 2024 and is anticipated to reach USD 10,065.45 Million by 2032, at a CAGR of 18.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Turkey Furniture Market Size 2024 | USD 2,536.89 Million |
| Turkey Furniture Market, CAGR | 18.8% |
| Turkey Furniture Market Size 2032 | USD 10,065.45 Million |
The Turkey Furniture Market is led by prominent companies such as İstikbal Mobilya, Kelebek Mobilya, Bellona, Doğtaş Mobilya, and IKEA Turkey. These companies dominate the market due to their strong brand recognition, extensive product offerings, and nationwide distribution networks. They focus on innovation, sustainable practices, and modern designs to cater to evolving consumer preferences. The market is experiencing significant growth, driven by factors such as rising disposable incomes, urbanization, and a shift towards stylish, eco-friendly furniture. Western Turkey holds the largest market share, accounting for approximately 45%. This region benefits from its established industrial base, particularly around major cities like Bursa and İzmir, which are key hubs for furniture manufacturing. The infrastructure in Western Turkey also facilitates efficient supply chain operations, contributing to the region's market leadership. With rapid urbanization and increased demand for both residential and commercial furniture, Western Turkey continues to drive the overall market growth.
 Market Insights
- The Turkey Furniture Market size reached USD 2,536.89 million in 2024 and is projected to expand at a CAGR of 18.8%.
- Rising disposable incomes and rapid urbanisation are driving demand for furniture in residential and commercial sectors, especially with wood-based products holding a 40% share and domestic use at 60%.
- Multi-functional and space‑saving furniture designs are gaining traction in urban dwellings, while customisation options are drawing younger consumers seeking unique styles.
- Major firms such as İstikbal Mobilya, Kelebek Mobilya, Bellona, Doğtaş Mobilya and IKEA Turkey dominate the marketplace, leveraging strong brand recognition, broad retail networks and integrated manufacturing.
- Raw‑material price volatility and competition from low‑cost imports continue to constrain growth, while Western Turkey leads with a 45% regional share and remains the focal point for production and innovation.
Market Segmentation Analysis:
By Material:
In the Turkey Furniture Market, the Wood segment holds the largest market share, accounting for approximately 40% of the total market. Wood-based furniture continues to dominate due to its aesthetic appeal, durability, and widespread use in both residential and commercial settings. The growing demand for eco-friendly, sustainable materials, along with the preference for custom-made wooden furniture, further drives the growth of this segment. Additionally, wood's versatility in design and finish makes it a preferred choice for a wide range of consumers.
- For instance, Istikbal Mobilya utilizes advanced manufacturing technologies to produce durable wooden furniture collections that blend traditional Turkish design with contemporary styles, catering to diverse consumer preferences.
By End Use:
The Domestic Use segment leads the Turkey Furniture Market, with a market share of around 60%. The demand for furniture in the residential sector is driven by factors such as rising disposable incomes, urbanization, and the growing trend of home decoration. Additionally, the increasing number of home renovation projects, coupled with the need for functional and stylish home furnishings, supports the continued dominance of this segment. Consumer preference for multi-functional and space-saving furniture is another key driver in this sub-segment.
- For instance, Bellona Mobilya offers extendable dining tables and storage-integrated ottomans that blend style and functionality, meeting the trend for versatile home furnishings.
Key Growth Drivers
Rising Disposable Incomes and Urbanization
The increasing disposable income of Turkey's middle class is a major driver of the furniture market. As more consumers can afford premium products, demand for high-quality and stylish furniture is rising, especially in urban areas. This growth is further fueled by rapid urbanization, where people seek to enhance their living spaces with modern and functional furniture. The expanding construction and real estate sectors also contribute to higher demand for both residential and commercial furniture.
- For instance, AS MENU, specializes in high-quality rattan furniture, reflecting growing consumer preferences for durable, eco-friendly outdoor pieces in rapidly urbanizing regions.
Growing Focus on Sustainable and Eco-friendly Furniture
Sustainability is becoming a key priority among Turkish consumers, who are increasingly inclined toward eco-friendly furniture made from renewable materials. Wood, particularly sourced from sustainable forests, is in high demand. The rise of environmentally conscious consumers, along with government regulations encouraging green products, is driving growth in this segment. Furniture manufacturers are also adopting eco-friendly production processes to meet consumer expectations and improve their market position, further accelerating the trend.
- For instance, Ersa Mobilya installed a 22,000 square meter solar panel system on its Ankara factory roof to meet 65% of its energy needs with renewable solar power, preventing 1,472 tons of CO2 emissions as of 2023.
Technological Advancements and Online Retail Expansion
Technological innovations in manufacturing processes, such as the integration of automation and artificial intelligence, have helped Turkish furniture companies increase production efficiency and product quality. Furthermore, the rise of online retail platforms has made purchasing furniture easier and more accessible for consumers. E-commerce growth, along with virtual reality and augmented reality technologies for online shopping, is expanding the reach of Turkish furniture brands. This trend is expected to continue as more consumers embrace the convenience of buying furniture online.
Key Trends & Opportunities
Rise in Multi-functional and Space-saving Furniture
As space constraints become a growing concern in urban Turkey, multi-functional and space-saving furniture is gaining popularity. Items that serve multiple purposes, such as convertible sofas or extendable dining tables, are highly sought after. This trend is particularly noticeable among younger, urban dwellers who live in apartments and are looking for practical solutions to optimize their living spaces. Furniture manufacturers are increasingly focusing on creating innovative designs that combine aesthetics and functionality to meet this demand.
- For instance, one of IKEA’s extendable dining tables (from the EKEDALEN series) hides an extra leaf to expand when needed and then stows away neatly when not.
Growing Demand for Customization and Personalization
Turkish consumers are increasingly seeking customized furniture that reflects their individual style and preferences. This trend is pushing manufacturers to offer bespoke designs, including unique finishes, colors, and sizes. The demand for personalized furniture is also spurred by advancements in digital design tools, which allow consumers to visualize their ideas before making a purchase. With the rise of customization, furniture brands have an opportunity to cater to a wider range of consumer needs, further boosting market growth.
- For instance, Homelli, a custom furniture manufacturer based in Istanbul, produces high-quality bespoke pieces with a variety of fabrics, finishes, and dimensions tailored to client specifications.
Key Challenges
Fluctuating Raw Material Prices
The fluctuating prices of raw materials, especially wood and metals, pose a significant challenge to the Turkey furniture market. These price fluctuations often lead to increased production costs, which may be passed on to consumers, potentially reducing demand for high-end furniture. Additionally, supply chain disruptions, such as those caused by global events, can further exacerbate this issue. Furniture manufacturers must find ways to manage these price variances effectively while maintaining product quality and profitability.
Intense Competition from Low-Cost Imports
One of the major challenges in the Turkey furniture market is the rising competition from low-cost furniture imports, particularly from Asia. These imports often offer similar designs at a lower price point, attracting budget-conscious consumers. Turkish manufacturers, who rely on premium materials and craftsmanship, find it difficult to compete on price alone. To combat this challenge, domestic brands must differentiate themselves by offering superior quality, unique designs, and focusing on the sustainability trend that is increasingly important to Turkish consumers.
Regional Analysis
Western Turkey
The Western Turkey region commands a market share of 45% of the country’s furniture market. This dominance reflects the region’s strong industrial base in textiles and furniture manufacturing, particularly around major hubs like Bursa and İzmir. The shift towards urban living and modern flats in this region boosts demand for stylish and modular furniture. Also, Western Turkey benefits from better infrastructure and logistics, enabling smoother supply‑chain operations and exports. As a result, manufacturers based in Western Turkey can scale and innovate more readily than in other regions.
Central Turkey
Central Turkey holds 30% of Turkey’s furniture market share. This region’s growth is driven by the expanding real‑estate market in cities such as Ankara and Konya, where commercial and office furniture demand is rising. Central Turkey also benefits from improved transport links connecting production centres to consumer markets. However, the region faces some constraints in raw‑material sourcing compared to Western Turkey, which compels manufacturers to focus on cost‑effective designs and regional distribution. The result is steady but slightly slower growth than in the western region.
Eastern Turkey
Eastern Turkey represents 25% of the national furniture market. Although less industrialised than the western and central regions, this region is gradually gaining traction due to rising urbanisation and government initiatives promoting local manufacturing. Furniture demand is bolstered by increasing incomes and housing developments in regional cities. Yet, infrastructure limitations and less concentration of large‑scale production units temper growth. Manufacturers here often cater to regional markets with simpler designs and rely on distribution networks from other regions for premium products.
Market Segmentations:
By Material
- Wood
- Leather
- Polymer
- Metal
- Glass
By End Use
- Domestic Use
- Commercial Use
By Region
- Western Turkey
- Central Turkey
- Eastern Turkey
Competitive Landscape
Competitive landscape analysis: The key players in the Turkey Furniture Market include Kelebek Mobilya, Doğtaş Mobilya, IKEA Turkey, Bellona, and İstikbal Mobilya. These companies dominate the market due to their established brand presence, extensive product ranges, and nationwide distribution networks. They continue to focus on innovation, with a strong emphasis on modern designs, sustainability, and technology integration in production processes. E-commerce and online retail channels have been pivotal in expanding their customer reach, particularly among younger, tech-savvy consumers. Additionally, these leading players invest heavily in manufacturing facilities to ensure high-quality production at scale. However, the market is becoming increasingly competitive as smaller and niche players enter the market, offering unique, cost-effective, and locally designed furniture. As competition intensifies, both large and small companies focus on improving customer service, enhancing the shopping experience, and optimizing supply chains to maintain market share while responding to changing consumer preferences.
Key Player Analysis
- İstikbal Mobilya
- Kelebek Mobilya
- Bellona
- Doğtaş Mobilya
- IKEA Turkey
- Enza Home
- Kilim Mobilya
- Lazzoni
- Çilek
- Weltew Home
Recent Developments
- In November 2025, Konfor Furniture of Türkiye entered the Indian market with its first store in Pune, through a partnership with Creaticity.
- In 2023, Bellona (Turkey) launched a new modular furniture collection designed to offer space-saving, customizable solutions.
Report Coverage
The research report offers an in-depth analysis based on Material, End Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Urbanisation and rising household formation will boost demand for furniture across Turkey.
- Increasing disposable incomes among the middle class will lead consumers to spend more on higher‑quality and designer furniture.
- The rapid growth of e‑commerce will enable furniture makers and retailers to reach more buyers and expand beyond traditional outlets.
- Sustainability‑driven sourcing and green production methods will become vital, offering firms competitive advantage in both domestic and export markets.
- Smart and multifunctional furniture suited to compact urban living will gain traction among younger buyers and apartment dwellers.
- Customisation and personalised furniture solutions will grow in importance as consumers seek unique styles and tailored home pieces.
- Export opportunities will expand as Turkey leverages its manufacturing base and cost competence to serve Middle East, Europe and African markets.
- Integration of digital design tools, augmented reality showrooms and virtual try‑outs will reshape the furniture shopping experience.
- Volatility in raw‑material costs and currency fluctuations will require manufacturers to optimise supply chains and maintain pricing discipline.
- Competitive pressure from low‑cost imports and shifting consumer preferences will force domestic brands to differentiate through design, quality and service.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Disposable Incomes and Urbanization
As Turkey's middle class expands and urbanization accelerates, more consumers are able to invest in premium, stylish, and functional furniture, particularly in urban centers where modern living spaces are in demand.
Growing Focus on Sustainable and Eco-friendly Furniture
Increasing environmental awareness and government regulations are driving demand for furniture made from renewable and sustainable materials, especially wood sourced from certified forests, pushing manufacturers to adopt greener production processes.
Technological Advancements and Online Retail Expansion
The integration of automation, artificial intelligence, and digital design tools in manufacturing, along with the rapid growth of e-commerce and virtual shopping experiences, is making furniture more accessible and customizable for Turkish consumers.
Demand for Multi-functional and Space-saving Designs
Urban dwellers, especially younger consumers in apartments, are seeking furniture that maximizes space and serves multiple purposes, prompting manufacturers to innovate with convertible and modular products.
Customization and Personalization Trends
Consumers increasingly desire unique, tailor-made furniture that reflects their personal style, leading to a surge in demand for bespoke designs and driving brands to offer more customization options.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Turkey Furniture Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Turkey Furniture Market projected to grow between 2025 and 2032?
Which Turkey Furniture Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Turkey Furniture Market?
Who are the leading companies in the Turkey Furniture Market?
Which region commanded the largest share of the Turkey Furniture Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Domestic Use
- 1.2.2 Commercial Use
- 1.3 By Material
- 1.3.1 Wood
- 1.3.2 Leather
- 1.3.3 Polymer
- 1.3.4 Metal
- 1.3.5 Glass
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,536.89 Million → 2032: USD 10,065.45 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Turkey Furniture Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Turkey Furniture Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Turkey Furniture Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Turkey Furniture Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Turkey Furniture Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Turkey Furniture Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Turkey Furniture Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Turkey Furniture Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,536.89 Million → 2032: USD 10,065.45 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Turkey Furniture Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Domestic Use
- 12.3.7.2 Commercial Use
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Wood
- 12.4.7.2 Leather
- 12.4.7.3 Polymer
- 12.4.7.4 Metal
- 12.4.7.5 Glass
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Turkey Furniture End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Turkey Furniture Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Turkey Furniture Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Turkey Furniture Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 İstikbal Mobilya
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Kelebek Mobilya
- 18.4 Bellona
- 18.5 Doğtaş Mobilya
- 18.6 IKEA Turkey
- 18.7 Enza Home
- 18.8 Kilim Mobilya
- 18.9 Lazzoni
- 18.10 Çilek
- 18.11 Weltew Home
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

