
U.S. Golf Putters Market Overview:
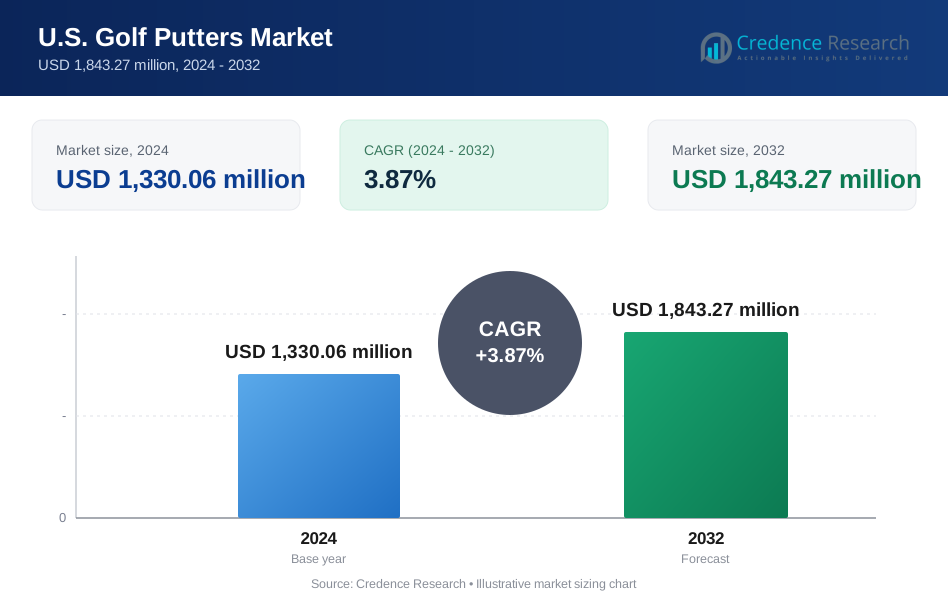
The U.S. Golf Putters market size was valued at USD 1,027.50 million in 2018, increased to USD 1,330.06 million in 2024, and is anticipated to reach USD 1,843.27 million by 2032, growing at a CAGR of 3.87% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Golf Putters Market Size 2024 | USD 1,330.06 Million |
| U.S. Golf Putters Market, CAGR | 3.87% |
| U.S. Golf Putters Market Size 2032 | USD 1,843.27 Million |
The U.S. Golf Putters market is led by top players including Odyssey, Scotty Cameron, TaylorMade Golf, Ping, and Cobra Golf, each holding between 16% to 20% market share in 2024. Odyssey remains the top performer with a 20% share, driven by its extensive product range and strong presence in professional tours. Scotty Cameron and TaylorMade Golf follow closely at 18% each, supported by premium offerings and loyal customer bases. Regionally, the South dominates the market with a 34% share, fueled by year-round golfing conditions, high course density, and strong demand across amateur and professional segments. The West and Northeast also contribute significantly, with 26% and 22% shares, respectively, driven by premium buyers and strong retail infrastructure.

U.S. Golf Putters Market Insights
- The U.S. Golf Putters market was valued at USD 1,027.50 million in 2018, reached USD 1,330.06 million in 2024, and is projected to hit USD 1,843.27 million by 2032, growing at a CAGR of 3.87%.
- Rising interest in golf among younger demographics, women, and recreational players continues to expand the consumer base for mid-range and entry-level putters.
- Smart putters, face-insert technologies, and alignment aids are trending, with customization gaining traction among serious golfers seeking performance improvements.
- Major players like Odyssey, Scotty Cameron, TaylorMade Golf, Ping, and Cobra Golf dominate, with Odyssey leading at 20% market share in 2024.
- The South region leads with 34% share, followed by the West (26%) and Northeast (22%); blade putters dominate by product type, holding over 35% share due to high user preference for feel and control.
U.S. Golf Putters Market Segmentation Analysis:
By Product Type
Blade putters dominate the U.S. market due to their simplicity and preference among experienced players, holding over 35% of the market share in 2024. Their straight, compact design offers better feedback and control, which appeals to low-handicap golfers. Mallet putters are gaining momentum with enhanced forgiveness and alignment features, especially for mid to high-handicap users. High-MOI and perimeter-weighted models address off-center hits, driving adoption among casual players. Custom-fitted putters are rising in demand, supported by golf retailers offering in-store fitting. Counterbalanced and stability-enhanced designs cater to aging golfers or those seeking improved consistency in swing arc and alignment.
- For instance, the Scotty Cameron Studio Style Newport Plus Putter is a premium blade putter crafted from 303 stainless steel, offering traditional feel and precise feedback that appeals to low‑handicap players.
By Material
Stainless steel remains the leading material, accounting for nearly 40% of the U.S. market in 2024, due to its durability, affordability, and feel balance. Aluminum putters follow closely, preferred for their lightweight nature and ability to integrate with alignment aids. Carbon and multi-material designs are expanding among premium and professional users, offering vibration damping and optimized weight distribution. These combinations enhance MOI performance and allow better custom fitting. Niche usage of titanium and tungsten inserts is increasing in high-end models for fine-tuned weight control and luxury aesthetics, reflecting demand for innovation in the tour-level segment.
- For example, mallet putters often incorporate aircraft‑grade aluminum bodies with face inserts for enhanced stability and forgiveness, as seen in mid‑mallet models from major brands.
By Technology
Face-balanced putters lead in market share, particularly favored by straight-back-and-through stroke golfers. The category holds strong appeal across amateur and senior segments. Insert-faced putters outperform milled-face options in the mid-range segment due to softer feel and affordability. Adjustable weight systems are increasingly common in premium lines, enabling users to fine-tune stroke stability. Alignment-assist technologies, including visual guides and contrasting face colors, enhance accuracy, especially for beginners. Smart or sensor-integrated putters, though still a niche, are emerging rapidly in training environments, offering data on stroke path, tempo, and impact for performance optimization.
U.S. Golf Putters Market U.S. Golf Putters Market Key Growth Drivers
Expanding Base of Amateur and Recreational Golfers
The growing number of amateur and recreational golfers across the U.S. continues to boost demand for golf putters. As golf gains popularity among younger demographics and women, fueled by social media visibility and golf entertainment venues like Topgolf, equipment purchases especially putters are rising. Recreational players often invest in entry-level or mid-range putters, supporting volume growth across retail and online channels. Golf associations and clubs are also promoting beginner-friendly initiatives, including community tournaments and coaching programs. This rising participation directly supports higher putter unit sales, especially blade and mallet types, while indirectly driving innovation in alignment technologies and lightweight materials. Seasonal golf tourism and suburban course expansion further contribute to steady market expansion across the Sun Belt states, especially Florida, Arizona, and Texas.
- For instance, the Sub 70 005 Wide Blade Center Shaft Putter is popular among beginners and casual players for its balance and feel, supporting higher putter purchases at retail.
Rising Demand for Custom-Fitted and High-Performance Putters
The shift toward precision and personalization in golf equipment has significantly driven the adoption of custom-fitted and high-MOI putters. Golfers increasingly seek improved control, stroke consistency, and comfort, prompting manufacturers to offer custom-fitting services that measure swing path, angle, and grip size. These services, now common in pro shops and high-end sporting goods stores, cater to both advanced amateurs and professional users. As more players realize the impact of fitting on putting accuracy, demand for tailored options with adjustable weights, toe-hang preferences, and face technologies continues to grow. Furthermore, high-performance putters with stability enhancements and premium materials like tungsten inserts appeal to experienced users looking to fine-tune their short game. These value-added features justify higher price points, boosting revenues in the premium and luxury segments.
- For instance, the Titleist Scotty Cameron Phantom 5 Putter Golf Club is chosen by experienced players for premium balance and feel.
Technological Advancements in Putter Design and Materials
Innovation in golf putter technology is a strong growth lever, particularly as manufacturers invest in lightweight materials, AI-driven designs, and smart integration. Advanced face inserts, alignment assist technologies, and vibration-dampening composites are now common even in mid-tier models. Multi-material construction combining carbon, aluminum, and tungsten enhances MOI performance and feedback response. Some brands have integrated sensor-based features to help players analyze stroke path, tempo, and impact data, catering to data-driven performance improvement. The use of 3D printing and AI modeling in R&D accelerates innovation cycles and supports the launch of differentiated products that meet diverse user preferences. These innovations expand the market beyond traditional users, attracting tech-savvy millennials and younger golfers seeking intelligent training tools. As a result, both volume and average selling price of golf putters are on the rise.

U.S. Golf Putters Market Key Trends & Opportunities
Growth of Direct-to-Consumer and Online Sales Channels
The rise of direct-to-consumer (D2C) models and e-commerce platforms has reshaped how golf putters are marketed and sold. Traditional retail still holds relevance, especially for hands-on fitting and trials, but online marketplaces now offer greater reach and cost efficiency. Golf brands leverage digital platforms to launch product demos, tutorials, and influencer-led promotions that engage consumers directly. Subscription models and seasonal discounts further boost buyer interest. Customization tools integrated into brand websites allow buyers to select grip, shaft length, and head design from home. COVID-19 accelerated online adoption, and that behavior persists, with hybrid buying journeys becoming the norm. For small and emerging brands, D2C strategies offer margin advantages and brand control, while established players are expanding their digital storefronts with AI-based recommendation engines to drive conversions.
- For instance, brands like Sub 70 and Stix Golf operate direct‑to‑consumer channels that let golfers order clubs, including putters, straight from brand sites without traditional retail intermediaries.
Sustainability and Eco-Friendly Materials in Golf Equipment
Sustainability is emerging as a relevant trend in the U.S. golf putters market, particularly among environmentally conscious consumers and premium buyers. Golf equipment makers are exploring sustainable materials such as recycled aluminum, biodegradable packaging, and low-impact coatings. While stainless steel and carbon remain dominant, manufacturers are optimizing production processes to reduce waste and emissions. Green initiatives by golf courses, including solar-powered operations and water-efficient landscaping, align with this movement, creating synergy across the value chain. Brands that integrate eco-conscious practices gain marketing advantages and customer loyalty, especially among millennials and Gen Z. Although niche today, the sustainable putters segment offers long-term opportunity as regulations tighten and consumer awareness deepens. This shift also opens space for innovation in material science and circular product design.

U.S. Golf Putters Market Key Challenges
High Price Sensitivity in Mid-Level Consumer Segments
One of the key challenges in the U.S. golf putters market is the high price sensitivity among casual and intermediate golfers. While professionals and serious amateurs are willing to invest in high-performance or custom-fitted models, many recreational players opt for affordable options, often below $150. This limits the penetration of advanced technologies and materials in the broader consumer base. Frequent discounting by online retailers, seasonal promotions, and knock-off imports further pressurize pricing strategies. Brands must balance innovation with affordability to attract volume sales without eroding margins. Moreover, price-focused buyers may delay upgrades or avoid premium add-ons like adjustable weights or sensor integration. Managing costs without compromising performance remains a critical issue, especially for brands trying to expand in the mid-range and economy segments.
Limited Product Differentiation and Brand Loyalty
Another major challenge is the saturation of similar product offerings in the market, which reduces differentiation and affects brand loyalty. Many blade and mallet putters across brands appear similar in design and material composition, making it hard for consumers to distinguish value beyond brand reputation or price. As a result, customers often switch brands based on promotions or aesthetic preferences rather than performance data. This dynamic creates a commoditization effect, especially in the mid-range category, where feature innovation is less visible. Smaller or newer brands struggle to gain traction unless backed by professional endorsements or significant marketing spend. To stand out, manufacturers must invest in R&D, storytelling, and experiential marketing that highlight tangible performance improvements and emotional brand connection.
Regional Analysis
Northeast
The Northeast holds approximately 22% of the U.S. golf putters market in 2024. States like New York, Massachusetts, and Pennsylvania maintain a mature golf culture with strong participation in club-level and recreational play. High household income in urban centers supports premium product demand, especially custom-fitted and branded putters. Seasonal limitations restrict year-round play, but indoor golf simulators and training centers help sustain demand. The region also benefits from a dense network of golf retailers and country clubs that offer advanced fitting services and promotional events targeting professionals and hobbyists alike.
Midwest
The Midwest accounts for nearly 18% of the market, led by golf-centric states such as Illinois, Ohio, and Michigan. Known for hosting amateur and collegiate tournaments, the region supports high sales volume of mid-range and custom putters. Golfers here favor blade and face-balanced putters due to their stroke style preference. Despite a shorter playing season, demand remains steady due to well-developed retail infrastructure and indoor training facilities. Community-driven clubs and university-level golf programs also play a vital role in product exposure and recurring purchases, especially among young players and coaches.
South
The Southern region leads the U.S. golf putters market with over 34% share in 2024, driven by year-round golfing conditions and high course density. States like Florida, Texas, and Georgia dominate due to a blend of tourism, retirement communities, and professional golf events. The region sees strong demand across all price tiers, from beginner-level putters to luxury models. Warm weather allows consistent use and higher replacement cycles. The presence of golf academies, private courses, and OEM distributors supports innovation adoption, while online direct-to-consumer channels see higher penetration compared to northern markets.
West
The Western U.S. contributes approximately 26% to the national market, with California alone representing a significant portion. The region’s diverse golfer base includes recreational players, youth segments, and elite athletes. High disposable income and focus on lifestyle sports fuel premium putter demand, especially those featuring smart sensors and multi-material construction. Golf tourism in Arizona and Nevada adds to sales through pro-shops and resort stores. Sustainability-conscious buyers in the West also show interest in eco-friendly materials, influencing product development. Online channels and D2C sales are particularly strong in metropolitan hubs like Los Angeles and San Francisco.
U.S. Golf Putters Market Segmentations:
By Product Type
- Blade Putters
- Mallet Putters
- High-MOI / Perimeter-Weighted Putters
- Custom-Fitted Putters
- Counterbalanced & Stability-Enhanced Putters
By Material
- Stainless Steel
- Aluminum
- Carbon & Multi-Material
- Others (Titanium, Tungsten Inserts)
By Technology
- Face-balanced vs Toe-hang
- Insert vs Milled Face
- Adjustable Weight Systems
- Alignment-Assist Technologies
- Smart / Sensor-Integrated Putters
By Price Range
- Economy
- Mid-range
- Premium
- Tour-Level / Luxury
By Distribution Channel
- Golf Specialty Stores
- Pro-shops & Country Clubs
- Sporting Retail Chains
- Online Direct-to-Consumer
- Online Marketplaces
- OEM & Private Label Channels
By End-User
- Amateur / Recreational Golfers
- Professional / Tournament Players
- Golf Academies & Training Facilities
By Geography
- Northeast
- Midwest
- South
- West

Competitive Landscape
The U.S. golf putters market is moderately consolidated, with five leading brands accounting for a significant share of total sales in 2024. Scotty Cameron, TaylorMade Golf, Ping, and Cobra Golf each hold an estimated 18–20% share, while Odyssey leads with approximately 20%, backed by consistent product innovation and endorsements by PGA Tour professionals. Brand loyalty plays a major role in purchase decisions, especially among experienced golfers. Competitive strategies revolve around face technology, MOI enhancement, alignment aids, and customization features. Players also differentiate by targeting emerging golfer segments and leveraging direct-to-consumer channels. Product development cycles are shortening, with brands releasing upgraded models yearly to stay relevant. Collaborations with golf coaches and professional players help drive credibility, while fitting services and AI-driven customization are being adopted to gain a competitive edge. The market favors brands that blend precision engineering, brand prestige, and advanced personalization to maintain user trust and premium pricing.
Key Player Analysis
- Odyssey
- Scotty Cameron
- TaylorMade Golf
- Ping
- Cobra Golf
Recent Developments
- In August 2025, PXG announced the launch of its latest high-MOI mallet putters in Scottsdale, Arizona, targeting the North America golf putters market. These new putters feature advanced customization options and performance enhancements designed for both amateur and professional golfers, reflecting the continued demand for innovative technology and premium quality in golf equipment.
- In August 2025, Breakthrough Golf Technology launched the Paradox putter, a zero torque model engineered with Swing Balance Technology to enhance distance control. The Paradox showed a 20% faster true roll and missed putts finishing 10% closer to the hole in testing, and is offered in both blade and fang designs with adjustable loft and lie options.
- In July 2025, L.A.B. Golf experienced a significant development with a $200 million acquisition by L. Catterton, a private equity firm backed by LVMH. This acquisition is set to enhance L.A.B. Golf’s market presence and product development capabilities. Known for its innovative putters that minimize torque during putting strokes, L.A.B. Golf combines traditional designs with advanced technology such as their LINK.1 Custom Putter, which promotes stability and accuracy.
- In March 2023, Straumann diversifies its offerings by acquiring GalvoSurge Dental AG, a Swiss medical device manufacturer, to address peri-implantitis treatment. The Galvo Surge device will be accessible in the European market by June 2023 and is compatible with various dental implant systems, enhancing its industry-wide usability.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, Technology, Price Range, Distribution Channel, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Youth golf programs and school-level training initiatives will expand the beginner segment.
- Professional endorsements will continue to influence brand choice and shape premium segment growth.
- Indoor golf simulators and tech-based training aids will boost putter experimentation and purchases.
- Artificial intelligence will improve putter design accuracy and custom fitting services.
- Direct integration of sensors with golf apps will gain popularity for performance tracking.
- Online product comparison tools will influence buying behavior and increase D2C conversions.
- Subscription-based equipment trials may emerge, especially in training-focused consumer segments.
- Multi-material designs using carbon, tungsten, and aluminum will become more mainstream.
- Players will seek putters with enhanced alignment technologies for accuracy and confidence.
- Manufacturers will focus on lightweight shaft innovations to support stroke consistency and fatigue reduction.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Base of Amateur and Recreational Golfers
The growing number of amateur and recreational golfers in the U.S., especially among younger demographics and women, is increasing demand for entry-level and mid-range putters. Initiatives by golf associations and the popularity of golf entertainment venues are broadening the consumer base and driving unit sales.
Rising Demand for Custom-Fitted and High-Performance Putters
Golfers are increasingly seeking custom-fitted and high-MOI putters for improved control and consistency, prompting manufacturers to offer advanced fitting services and adjustable features. This trend is boosting premium segment revenues and encouraging innovation in design and materials.
Technological Advancements in Putter Design and Materials
Manufacturers are investing in lightweight materials, AI-driven designs, and smart integration, resulting in putters with enhanced MOI, alignment aids, and sensor-based feedback. These innovations attract tech-savvy and performance-oriented golfers, raising both market volume and average selling price.
Growth of Direct-to-Consumer and Online Sales Channels
The shift toward direct-to-consumer and e-commerce platforms is making it easier for consumers to access a wide range of putters, including customizable options. Online channels offer convenience, product education, and competitive pricing, expanding market reach and supporting sales growth.
Increased Focus on Sustainability and Eco-Friendly Materials
Growing environmental awareness among consumers is encouraging brands to adopt recycled materials, eco-friendly packaging, and sustainable manufacturing processes. This trend is particularly influential among younger and premium buyers, opening new opportunities for differentiation and long-term growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the U.S. Golf Putters market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the U.S. Golf Putters market projected to grow between 2024 and 2032?
Which U.S. Golf Putters market segment held the largest share in 2024?
What are the primary factors fueling the growth of the U.S. Golf Putters market?
Who are the leading companies in the U.S. Golf Putters market?
Which region commanded the largest share of the U.S. Golf Putters market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Stainless Steel
- 1.2.2 Aluminum
- 1.2.3 Carbon & Multi-Material
- 1.2.4 Others (Titanium, Tungsten Inserts)
- 1.3 By Technology
- 1.3.1 Face-balanced vs Toe-hang
- 1.3.2 Insert vs Milled Face
- 1.3.3 Adjustable Weight Systems
- 1.3.4 Alignment-Assist Technologies
- 1.3.5 Smart / Sensor-Integrated Putters
- 1.4 By Product Type
- 1.4.1 Blade Putters
- 1.4.2 Mallet Putters
- 1.4.3 High-MOI / Perimeter-Weighted Putters
- 1.4.4 Custom-Fitted Putters
- 1.4.5 Counterbalanced & Stability-Enhanced Putters
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,330.06 million → 2032: USD 1,843.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Golf Putters Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Golf Putters Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Golf Putters Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Golf Putters Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Golf Putters Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Golf Putters Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Golf Putters Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Golf Putters Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,330.06 million → 2032: USD 1,843.27 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Golf Putters Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Stainless Steel
- 12.3.7.2 Aluminum
- 12.3.7.3 Carbon & Multi-Material
- 12.3.7.4 Others (Titanium, Tungsten Inserts)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Face-balanced vs Toe-hang
- 12.4.7.2 Insert vs Milled Face
- 12.4.7.3 Adjustable Weight Systems
- 12.4.7.4 Alignment-Assist Technologies
- 12.4.7.5 Smart / Sensor-Integrated Putters
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Blade Putters
- 12.5.7.2 Mallet Putters
- 12.5.7.3 High-MOI / Perimeter-Weighted Putters
- 12.5.7.4 Custom-Fitted Putters
- 12.5.7.5 Counterbalanced & Stability-Enhanced Putters
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Golf Putters Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 U.S. Golf Putters Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 U.S. Golf Putters Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Odyssey
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Scotty Cameron
- 17.4 TaylorMade Golf
- 17.5 Ping
- 17.6 Cobra Golf
- 17.7 PXG
- 17.8 L.A.B. Golf
- 17.9 Wilson Staff
- 17.10 Cleveland Golf
- 17.11 Mizuno
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

