
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Artificial Intelligence In Media Market Size 2024 | USD 0.33 Million |
| UK Artificial Intelligence In Media Market, CAGR | 34.6% |
| UK Artificial Intelligence In Media Market Size 2032 | USD 4.74 Million |
Market Overview
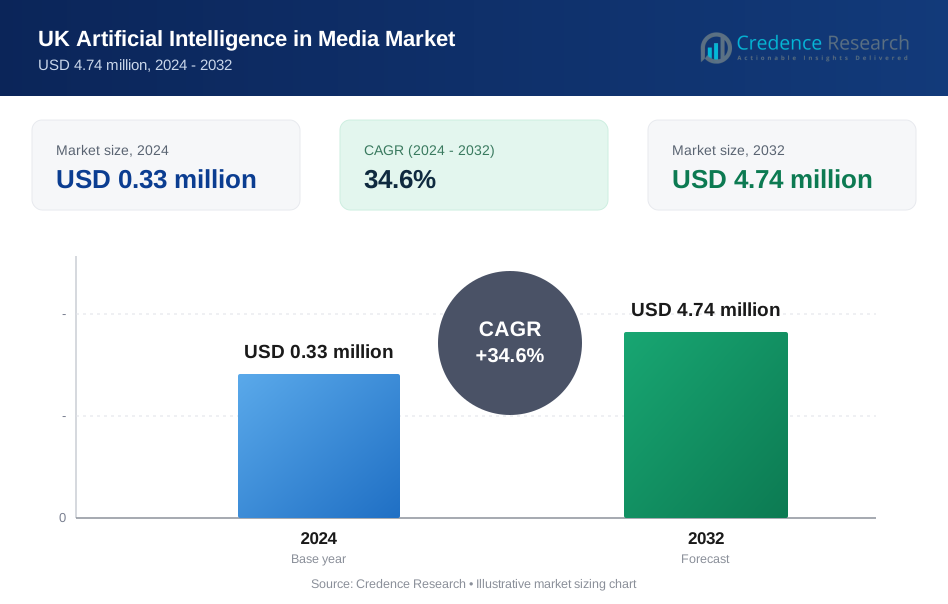
The UK Artificial Intelligence In Media Market is projected to grow from USD 0.33 million in 2024 to an estimated USD 4.74 million by 2032, with a compound annual growth rate (CAGR) of 34.6% from 2025 to 2032. The rapid growth in the adoption of AI technologies across various media applications is expected to drive this surge, as businesses seek to enhance content creation, audience engagement, and operational efficiency.
Several factors are contributing to the growth of the UK Artificial Intelligence in Media Market. Key drivers include increasing demand for data-driven content, advancements in machine learning algorithms, and the growing adoption of AI-powered tools for content personalization and distribution. Media companies are increasingly turning to AI to streamline operations, improve decision-making, and create more engaging, personalized experiences for their audiences. Additionally, AI technologies are transforming traditional media channels, enabling better content recommendation systems and enhanced consumer interaction.
Geographically, the UK is poised to lead the European AI in Media market due to its robust technological infrastructure, high media consumption, and a strong emphasis on innovation. Key players in the market include major media corporations, technology giants, and AI-focused startups that are continually introducing new solutions to meet the growing demands of the media industry. Prominent companies in this space include Google, IBM, Adobe, and Amazon, who are leading the charge in AI integration within media.
Market Insights
- The UK Artificial Intelligence in Media Market is projected to grow significantly from USD 0.33 million in 2024 to USD 4.74 million by 2032, with a CAGR of 34.6% from 2025 to 2032.
- Key drivers include the rising demand for personalized content, advancements in AI technologies like machine learning and NLP, and the increasing adoption of AI tools for content creation and distribution.
- AI technologies are streamlining content creation, enhancing personalization, and enabling real-time content moderation, driving higher engagement and operational efficiency in the media industry.
- Key challenges include data privacy concerns, ethical issues surrounding AI, and the high costs and technical complexity of AI implementation for media companies.
- The UK is positioned as a leader in AI integration within the European media sector due to its robust infrastructure, high media consumption, and strong focus on technological innovation.
- Major players such as Google, IBM, Adobe, and Amazon are at the forefront, driving innovation and providing AI solutions across content generation, predictive analytics, and personalized advertising.
- London leads the market, followed by Manchester, with other cities like Birmingham, Leeds, and Glasgow contributing to the growth of AI applications in media, particularly in gaming, advertising, and content moderation.
Market Drivers
Rising Demand for Personalized Content and User Experiences
One of the primary drivers for the growth of the UK Artificial Intelligence in Media Market is the increasing demand for personalized content and tailored user experiences. As consumers expect more relevant and engaging content, AI-powered solutions are enabling media companies to meet these expectations. By leveraging AI algorithms, companies can analyze vast amounts of consumer data, including browsing behavior, social media activity, and content preferences. This data-driven approach allows for the creation of highly personalized recommendations and content, which enhances user engagement and retention. For instance, streaming platforms like Netflix use AI to create personalized viewing recommendations based on user behavior and preferences. This not only enhances user engagement but also drives revenue through targeted advertising and subscription models.Personalized experiences not only improve customer satisfaction but also drive revenue through targeted advertising and subscription models. As a result, the demand for AI in media continues to rise as companies strive to offer more customized and compelling content that resonates with their audiences.
Advancements in Natural Language Processing (NLP) and Automation
Natural Language Processing (NLP) and automation are revolutionizing the way media companies create, distribute, and analyze content. NLP technologies enable machines to understand, interpret, and generate human language, which has numerous applications in the media industry. Automated content creation, for example, is becoming increasingly common in newsrooms, where AI-driven tools are used to generate news reports, sports summaries, and financial updates. By automating routine content generation tasks, media companies can streamline operations, reduce costs, and increase content production speed. For instance, newsrooms are increasingly using AI-driven tools to automate routine content generation tasks, such as generating news reports and sports summaries. This allows media companies to streamline operations and increase content production speed.Additionally, NLP-based AI tools are enhancing content search and discovery, improving how users interact with media platforms. AI chatbots powered by NLP are increasingly used in customer service and content discovery, offering real-time assistance and personalized recommendations. As these AI capabilities evolve, they are expected to play an even larger role in transforming content creation and consumer interaction in the UK media market.
Growth of Data-Driven Advertising and Targeted Marketing
Another key driver of the UK Artificial Intelligence in Media Market is the growing use of AI in data-driven advertising and targeted marketing. The ability to collect and analyze consumer data at an unprecedented scale has enabled businesses to deliver highly targeted advertising campaigns. AI-powered tools analyze data points from consumer interactions, search behaviors, social media engagement, and purchase patterns to create more precise audience segments. This allows advertisers to deliver personalized ads that are more likely to resonate with individual users, thereby increasing ad effectiveness and return on investment. For instance, companies like O2 have successfully used data-driven marketing by analyzing consumer interactions and location data to deliver personalized ads that show relevant offers and nearby store locations, significantly improving ad effectiveness.Additionally, AI can optimize ad placements in real time, ensuring that advertisements reach the right audience at the right moment. The ability to use AI for predictive analytics also allows businesses to forecast trends and consumer behavior more accurately, improving the strategic planning of marketing campaigns. As brands and media companies in the UK focus more on customer-centric advertising models, the demand for AI-driven advertising solutions is expected to continue to rise.
Improved Efficiency and Cost Reduction in Media Operations
The adoption of AI in media operations is also being driven by its potential to improve efficiency and reduce costs. Media companies are increasingly turning to AI solutions to automate labor-intensive tasks such as video editing, content tagging, and metadata generation. For example, AI can assist in automating video editing by recognizing key scenes, identifying faces, and suggesting edits, significantly reducing the time and cost required for manual editing. Similarly, AI algorithms can analyze vast amounts of content to tag and categorize media assets, making it easier to manage large volumes of digital content. By automating these repetitive tasks, media organizations can free up human resources for more creative and strategic activities, ultimately improving operational efficiency.AI-driven tools can also optimize content distribution, ensuring that media content reaches the most relevant audiences and maximizing the use of available resources. As AI continues to demonstrate its ability to streamline workflows and reduce operational costs, more media companies in the UK are likely to adopt these technologies as part of their digital transformation strategies.
Market Trends
AI-Driven Content Creation and Automation
One of the most significant trends in the UK Artificial Intelligence in Media Market is the growing reliance on AI-driven content creation and automation. Media companies are increasingly adopting AI technologies to streamline content production processes and reduce manual intervention. AI-powered tools are enabling automated video editing, article generation, and real-time news reporting, transforming how content is created. For example, AI-based systems can analyze and summarize news articles or create sports highlights by identifying key moments from the footage. This automation not only reduces production time but also helps manage the growing demand for real-time content in today’s fast-paced digital environment. Media companies are leveraging AI to generate content at scale, which can be customized and personalized for different audiences. The ability to automate repetitive tasks allows media outlets to allocate resources more effectively and focus on high-value activities, such as investigative journalism and strategic content planning. This trend is expected to continue as AI technologies evolve, leading to even greater automation and enhanced efficiency in the content creation process.
Personalized Content Recommendations and User Experience Optimization
Personalization is at the core of the current trends shaping the UK Artificial Intelligence in Media Market. AI-powered algorithms are being utilized to deliver highly personalized content recommendations, offering media companies the ability to tailor experiences for individual users based on their preferences, behavior, and interactions. Streaming services like Netflix, BBC iPlayer, and Spotify have successfully implemented AI-based recommendation engines to suggest content that aligns with users' tastes, driving engagement and user retention. These personalized experiences are powered by machine learning algorithms that analyze vast amounts of user data to make content suggestions, predict what users are likely to enjoy next, and optimize the viewing experience. In addition to content recommendations, AI is also being used to personalize advertising strategies, ensuring that users are exposed to relevant ads that match their interests and browsing history. By improving personalization, AI not only enhances the overall user experience but also drives revenue for media companies through targeted content and ads. As media organizations continue to collect more data and refine their AI models, the level of personalization is expected to become even more granular, further boosting the trend in the market.
AI in Media Analytics and Audience Insights
The use of AI in media analytics and audience insights is another growing trend in the UK Artificial Intelligence in Media Market. AI technologies are enabling media companies to gain deeper insights into audience behavior and preferences through data analytics. By leveraging machine learning and natural language processing, companies can process vast quantities of unstructured data-such as social media interactions, online reviews, and audience engagement metrics-to uncover valuable insights that can inform content strategies and advertising campaigns. AI-driven analytics platforms are capable of segmenting audiences based on various parameters, including demographics, location, and behavior, allowing media companies to better understand their audiences and develop targeted marketing efforts. These insights help companies predict audience preferences, identify emerging trends, and adjust content offerings accordingly, thus optimizing user engagement and enhancing the relevance of their media services. In addition, AI tools can help measure the effectiveness of marketing campaigns by providing real-time performance analytics and identifying which strategies are yielding the best results. The ongoing evolution of AI in analytics is expected to drive more accurate and actionable insights, helping businesses stay ahead of audience trends and refine their content offerings.
AI-Powered Advertising and Enhanced Targeting Capabilities
AI's impact on advertising in the UK media market is another major trend that is reshaping the industry. Media companies and advertisers are increasingly adopting AI to optimize advertising strategies and improve targeting capabilities. AI allows advertisers to analyze large datasets and identify patterns in consumer behavior, enabling them to deliver more targeted, relevant, and personalized advertisements to individual users. This shift towards data-driven advertising is particularly impactful in the context of digital media, where the ability to fine-tune targeting based on user interests, browsing habits, and demographics can significantly improve the effectiveness of campaigns. For example, AI-powered algorithms are used to determine the best times and channels to deliver ads, ensuring that they reach the right audience when they are most likely to engage. AI technologies are also helping advertisers to manage programmatic advertising, which automates the purchase and placement of ads in real time. By using predictive analytics, AI can anticipate user actions and optimize ad placement, increasing conversion rates and return on investment (ROI). Additionally, AI is improving ad creatives by analyzing which types of content resonate best with specific audiences, enabling advertisers to refine their messages. As AI continues to improve its targeting and optimization capabilities, its role in the advertising ecosystem will become even more prominent, further influencing the UK Artificial Intelligence in Media Market.
Market Challenges
Data Privacy and Ethical Concerns
One of the primary challenges in the UK Artificial Intelligence in Media Market is addressing data privacy and ethical concerns. The collection of vast amounts of personal data for AI-driven content personalization and advertising raises significant concerns about how this data is handled, stored, and shared. Media companies rely on user data to build more targeted experiences, but as the focus on personalized content and marketing grows, so do the risks of privacy breaches and misuse of sensitive information. The implementation of regulations such as the General Data Protection Regulation (GDPR) in the UK has put stricter controls on how companies can collect and utilize consumer data. While these regulations aim to protect consumer privacy, they can also complicate the process of data collection and AI implementation. Media companies must ensure they comply with these regulations while still maximizing the potential of AI in personalization. Ethical challenges also arise in areas such as algorithmic bias, where AI systems may inadvertently perpetuate or amplify existing biases in content recommendations or advertising targeting. Addressing these concerns requires robust data protection measures, transparency in AI decision-making, and a careful approach to ethical AI deployment. Failing to address data privacy and ethical issues could harm consumer trust and hinder the widespread adoption of AI in the media sector.
High Implementation Costs and Technical Complexity
Another significant challenge in the UK Artificial Intelligence in Media Market is the high cost and technical complexity associated with implementing AI solutions. Developing and integrating AI technologies requires substantial investment in both hardware and software infrastructure. For media companies, especially smaller organizations with limited budgets, the financial burden of adopting AI technologies can be a major barrier. The costs are not only limited to initial investment but also extend to ongoing maintenance, system updates, and hiring specialized AI talent, which can be prohibitively expensive. Additionally, integrating AI solutions into existing media workflows can be technically challenging, requiring the adaptation of legacy systems and processes to accommodate new technologies. This can lead to disruptions in operations and a steep learning curve for employees. For companies without the necessary technical expertise or resources, the complexity of AI adoption can slow down progress and create a significant barrier to entry. Despite the long-term benefits of AI, the high initial costs and technical challenges remain a major hurdle for many media organizations looking to adopt AI-driven solutions.
Market Opportunities
Expansion of AI-Driven Content Personalization
The growing demand for personalized user experiences presents a significant market opportunity in the UK Artificial Intelligence in Media Market. With increasing consumer expectations for tailored content, media companies have a prime opportunity to leverage AI technologies to deliver personalized recommendations, advertisements, and content curation. By utilizing AI-driven recommendation engines and machine learning algorithms, companies can provide more relevant, engaging, and customized experiences for viewers and readers. This not only enhances user satisfaction but also fosters higher engagement and retention rates, which are crucial for subscription-based and ad-supported media models. The potential for AI to revolutionize content personalization opens new avenues for media companies to attract and retain their audiences, thereby driving revenue growth and solidifying their competitive advantage in the market.
AI-Powered Advertising and Marketing Innovation
Another promising opportunity lies in the use of AI to transform advertising and marketing strategies within the UK media market. AI can significantly improve the targeting and efficiency of digital advertising by analyzing consumer data to identify trends, preferences, and behaviors. Media companies can capitalize on this capability to deliver highly targeted advertisements that resonate with the right audiences at the optimal time. Furthermore, AI can automate programmatic advertising, ensuring real-time optimization of ad placements and enhancing the return on investment for advertisers. As brands increasingly demand more data-driven and effective advertising solutions, the integration of AI in media marketing presents a strong opportunity for companies to drive growth through enhanced advertising capabilities and more personalized, engaging campaigns.
Market Segmentation Analysis
By Component:
The market is divided into two main segments: Solutions and Services. The Solutions segment holds the largest share, driven by the increasing adoption of AI-driven tools that automate content creation, enhance personalization, and optimize advertising strategies. AI solutions are crucial for media companies looking to improve operational efficiency, streamline workflows, and deliver a more tailored experience to their audiences. On the other hand, the Services segment, which includes consulting, implementation, and maintenance services, is also growing, as businesses require specialized expertise to integrate AI technologies into their existing systems.
By Technology:
The Generative AI segment is gaining significant traction due to its ability to create new content, such as articles, videos, and even music, based on given inputs. This technology is being used extensively in content creation for media companies, particularly in automating video production, generating scripts, and personalizing content for specific audiences. Other AI technologies, including machine learning algorithms and natural language processing (NLP), are also contributing to the market’s growth. NLP, for instance, is widely used in language moderation, content categorization, and chatbots for customer interaction.
Segments
Based on Component
- Solution
- Services
Based on Technology
- Generative AI
- Other AI
Based on Application
- Video Production
- Language Moderation
- Newsroom Analytics
- Real-time OTT Content Moderation
- Gaming Content Optimization
- Others
Based on End User
- Film Studios
- Advertising & Marketing Agencies
- Television & OTT Platforms
- Gaming Companies
- Music Production Companies
- Others
Based on Region
- London
- Manchester
- Birmingham
Regional Analysis
London (40%)
As the capital and the hub for technology and innovation, London holds the largest share of the AI in the media market in the UK, accounting for approximately 40% of the overall market. The region is home to a significant number of media companies, AI startups, and technology providers. London’s strong infrastructure, access to talent, and investment opportunities make it the primary location for the development and implementation of AI technologies in media. Companies in London are leveraging AI for content creation, automation, personalized user experiences, and digital advertising solutions. The city also has a well-established media ecosystem that integrates AI into traditional and digital platforms, such as TV broadcasters, streaming services, and online news agencies.
Manchester (25%)
Manchester follows London with a market share of around 25%. The city is rapidly emerging as a key player in the AI space, particularly in sectors like gaming, content creation, and OTT platforms. It has seen a surge in AI-powered media companies and startups, driven by its tech-focused initiatives and growing digital infrastructure. Media companies in Manchester are leveraging AI for gaming content optimization, video production, and real-time content moderation, contributing to the increasing demand for AI technologies. Additionally, Manchester benefits from collaborations between universities, research institutions, and the private sector, which is fostering innovation in the AI field.
Key players
- Google LLC
- Microsoft Corporation
- IBM Corporation
- Meta
- OpenAI
- Amazon Web Services (AWS)
- Adobe
- NVIDIA
- Salesforce
- Stability AI
- Eightfold AI
- io
- Synthesia
Competitive Analysis
The UK Artificial Intelligence in Media Market is highly competitive, with leading players like Google LLC, Microsoft, IBM, and Meta at the forefront. These tech giants leverage their extensive research capabilities, large-scale cloud infrastructure, and AI innovations to provide cutting-edge solutions for media companies. Google and Microsoft dominate the market with AI solutions that cater to content creation, data analytics, and personalized user experiences. Meanwhile, companies like OpenAI and Synthesia focus on generative AI, enabling advanced content production automation and media personalization. Adobe and NVIDIA contribute through AI tools for video editing and visual effects, while Amazon Web Services (AWS) supports media companies with cloud-based AI solutions. Smaller players like Stability AI and Eightfold AI focus on niche applications such as recruitment and data-driven insights for the media industry. As AI technologies evolve, competition intensifies, with each player innovating to maintain their market leadership.
Recent Developments
- In March 2025, Google expanded its UK AI business, focusing on data residency and AI agent development for enterprises.
- In March 2025, The CMA ended its investigation into Microsoft's partnership with OpenAI, finding no significant change in control.
- In February 2025, IBM reported positive earnings, with growth in AI and cloud services, and plans for further investments in these areas.
- In February 2025, Meta plans to launch six new AI wearables in 2025.
- In March 2025, AWS formed a new group focused on agentic AI to automate user tasks.
Market Concentration and Characteristics
The UK Artificial Intelligence in Media Market exhibits a moderate to high level of market concentration, with several key players such as Google LLC, Microsoft Corporation, IBM, Meta, and Amazon Web Services (AWS) holding significant market shares. These large, established companies dominate the market due to their substantial investments in AI research, development, and infrastructure, as well as their ability to offer comprehensive solutions for content creation, personalization, and data analytics. However, there is also a growing presence of smaller, innovative players like Stability AI, OpenAI, and Synthesia, which focus on specialized AI applications such as generative content and real-time media moderation. The market is characterized by rapid technological advancements, with a strong emphasis on AI-driven automation, machine learning, and natural language processing. As AI adoption continues to grow in the media sector, competition is expected to intensify, fostering an environment of continuous innovation and development.
Report Coverage
The research report offers an in-depth analysis based on Component, Technology, Application, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UK Artificial Intelligence in Media Market is expected to experience sustained growth as media companies increasingly integrate AI solutions to optimize content creation and distribution. This trend will be driven by the growing demand for personalized content and efficient workflows.
- Generative AI technologies, such as those used for content creation and video production, will play a more significant role in the market. Media companies will increasingly leverage AI to automate content generation and reduce time spent on manual tasks.
- AI-driven personalization in content recommendations and advertising will become more sophisticated, offering consumers highly tailored experiences across media platforms. This will lead to stronger customer engagement and higher revenue potential for media companies.
- AI-powered analytics will continue to improve, allowing media companies to gain deeper insights into consumer behavior. These insights will enable businesses to develop more effective marketing strategies and refine content offerings to meet audience preferences.
- With the rise of live-streaming platforms and social media, AI tools for real-time content moderation will see greater adoption. Companies will use AI to ensure content compliance with regulations and community guidelines in real time.
- AI technologies will increasingly power programmatic advertising, automating ad placements and optimizing campaigns based on user behavior and data insights. This will enable advertisers to deliver more relevant and targeted ads, improving return on investment.
- Over-the-top (OTT) platforms will continue to integrate AI to enhance user experiences through personalized recommendations, content filtering, and seamless navigation. AI will further solidify OTT’s position as a dominant force in the media industry.
- The UK market will see more venture capital investments in AI-driven media startups focused on innovation. These investments will foster the development of new AI technologies tailored to the unique needs of the media industry.
- Gaming companies in the UK will increasingly adopt AI to optimize gameplay, create dynamic narratives, and enhance user experiences. AI will play a crucial role in personalizing gaming content, making it more immersive and engaging.
- AI-driven automation will continue to streamline media production workflows, from video editing to scriptwriting. As AI becomes more sophisticated, it will reduce operational costs and improve efficiency, allowing media companies to scale their operations more effectively.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Personalized Content and User Experience
Media companies in the UK are leveraging AI to deliver highly personalized content and recommendations, which increases user engagement and retention. This demand for tailored experiences is driving rapid adoption of AI-powered tools across streaming, news, and advertising platforms.
Advancements in Generative AI and NLP
Breakthroughs in generative AI and natural language processing are enabling automated content creation, real-time moderation, and sophisticated language understanding. These technologies are transforming workflows in newsrooms, video production, and customer interaction, making AI integration increasingly attractive.
Growth of Data-Driven Advertising and Targeted Marketing
AI enables precise audience segmentation and real-time ad optimization, allowing advertisers and media companies to deliver more relevant ads and improve ROI. The ability to analyze vast datasets for targeted marketing is a key factor fueling market expansion.
Operational Efficiency and Cost Reduction
AI automates labor-intensive tasks such as video editing, content tagging, and metadata generation, reducing operational costs and freeing up human resources for creative work. This efficiency gain is a major incentive for media organizations to invest in AI solutions.
Strong UK Technological Infrastructure and Innovation Ecosystem
The UK’s robust digital infrastructure, high media consumption, and concentration of AI startups and research institutions - especially in cities like London and Manchester - create a fertile environment for AI adoption in media, accelerating market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the UK Artificial Intelligence in Media Market in 2023 and 2032?
What are the key drivers of growth in the UK AI in Media Market?
Which companies are leading the UK AI in Media Market?
How is AI transforming traditional media channels?
What impact is AI having on media content creation?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Film Studios
- 1.2.2 Advertising & Marketing Agencies
- 1.2.3 Television & OTT Platforms
- 1.2.4 Gaming Companies
- 1.2.5 Music Production Companies
- 1.2.6 Others
- 1.3 By Component
- 1.3.1 Solution
- 1.3.2 Services
- 1.4 By Technology
- 1.4.1 Generative AI
- 1.4.2 Other AI
- 1.5 By Application
- 1.5.1 Video Production
- 1.5.2 Language Moderation
- 1.5.3 Newsroom Analytics
- 1.5.4 Real-time OTT Content Moderation
- 1.5.5 Gaming Content Optimization
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 0.33 million → 2032: USD 4.74 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 UK Artificial Intelligence in Media Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 UK Artificial Intelligence in Media Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 UK Artificial Intelligence in Media Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 UK Artificial Intelligence in Media Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 UK Artificial Intelligence in Media Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 UK Artificial Intelligence in Media Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 UK Artificial Intelligence in Media Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 UK Artificial Intelligence in Media Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 0.33 million → 2032: USD 4.74 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 UK Artificial Intelligence in Media Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Film Studios
- 12.3.7.2 Advertising & Marketing Agencies
- 12.3.7.3 Television & OTT Platforms
- 12.3.7.4 Gaming Companies
- 12.3.7.5 Music Production Companies
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Solution
- 12.4.7.2 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Generative AI
- 12.5.7.2 Other AI
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Video Production
- 12.6.7.2 Language Moderation
- 12.6.7.3 Newsroom Analytics
- 12.6.7.4 Real-time OTT Content Moderation
- 12.6.7.5 Gaming Content Optimization
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 UK Artificial Intelligence in Media End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 UK Artificial Intelligence in Media Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 UK Artificial Intelligence in Media Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 UK Artificial Intelligence in Media Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Google LLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Microsoft Corporation
- 18.4 IBM Corporation
- 18.5 Meta
- 18.6 OpenAI
- 18.7 Amazon Web Services (AWS)
- 18.8 Adobe
- 18.9 NVIDIA
- 18.10 Stability AI
- 18.11 Synthesia
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

