
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Electronic Medical Record Market Size 2024 | USD1,857.82 million |
| UK Electronic Medical Record Market, CAGR | 11.28% |
| UK Electronic Medical Record Market Size 2032 | USD4,368.58 million |
Market Overview
The UK Electronic Medical Record Market is projected to grow from USD1,857.82 million in 2024 to an estimated USD4,368.58 million based on 2032, with a compound annual growth rate (CAGR) 11.28% from 2025 to 2032. This expansion reflects increasing digitalization across healthcare providers, driven by government initiatives promoting interoperable health information systems.
Key drivers fueling the UK EMR market include stringent regulatory mandates, rising demand for value-based care, and growing patient expectations for accessible health records. Healthcare organizations invest in advanced functionalities such as telemedicine integration, analytics-driven decision support, and patient portals. Vendors launch user-friendly interfaces and mobile applications to enhance clinician productivity, strengthen care coordination, and improve outcomes. Simultaneously, emerging trends such as integration with AI-powered diagnostics and voice-enabled charting optimize workflows and drive competitive differentiation.
In geographical terms, England dominates market share due to its dense network of acute and community health facilities, followed by Scotland and Wales where regional health boards invest in digital health modernization. Key players such as Cerner Corporation, Epic Systems, Allscripts Healthcare Solutions, and System C Healthcare deliver comprehensive EMR suites. These firms collaborate with local IT service providers and NHS Digital to tailor solutions, strengthen interoperability, and capture growing demand across primary, secondary, and tertiary care settings.
Market Insights
- UK Electronic Medical Record Market reached USD 1,857.82 million in 2024 and will hit USD 4,368.58 million by 2032 with 11.28% CAGR, driven by widespread digitalization.
- Strict government mandates and compliance frameworks compel NHS trusts and private hospitals to adopt EMR solutions to enhance data security and care quality.
- Value-based care funding models push providers to leverage analytics and decision-support modules within EMR platforms to improve outcomes and control costs.
- Stringent data protection rules and fragmented legacy systems complicate interoperability and slow new EMR deployments.
- England dominates uptake through extensive NHS funding and centralized digital health programs that streamline system upgrades.
- Scotland and Wales invest in cloud-based EMR rollouts under regional health strategies to boost care coordination and reduce duplicate testing.
- Northern Ireland prioritizes cross-border data exchange with the Republic of Ireland by implementing unified interoperability standards.
Report Scope
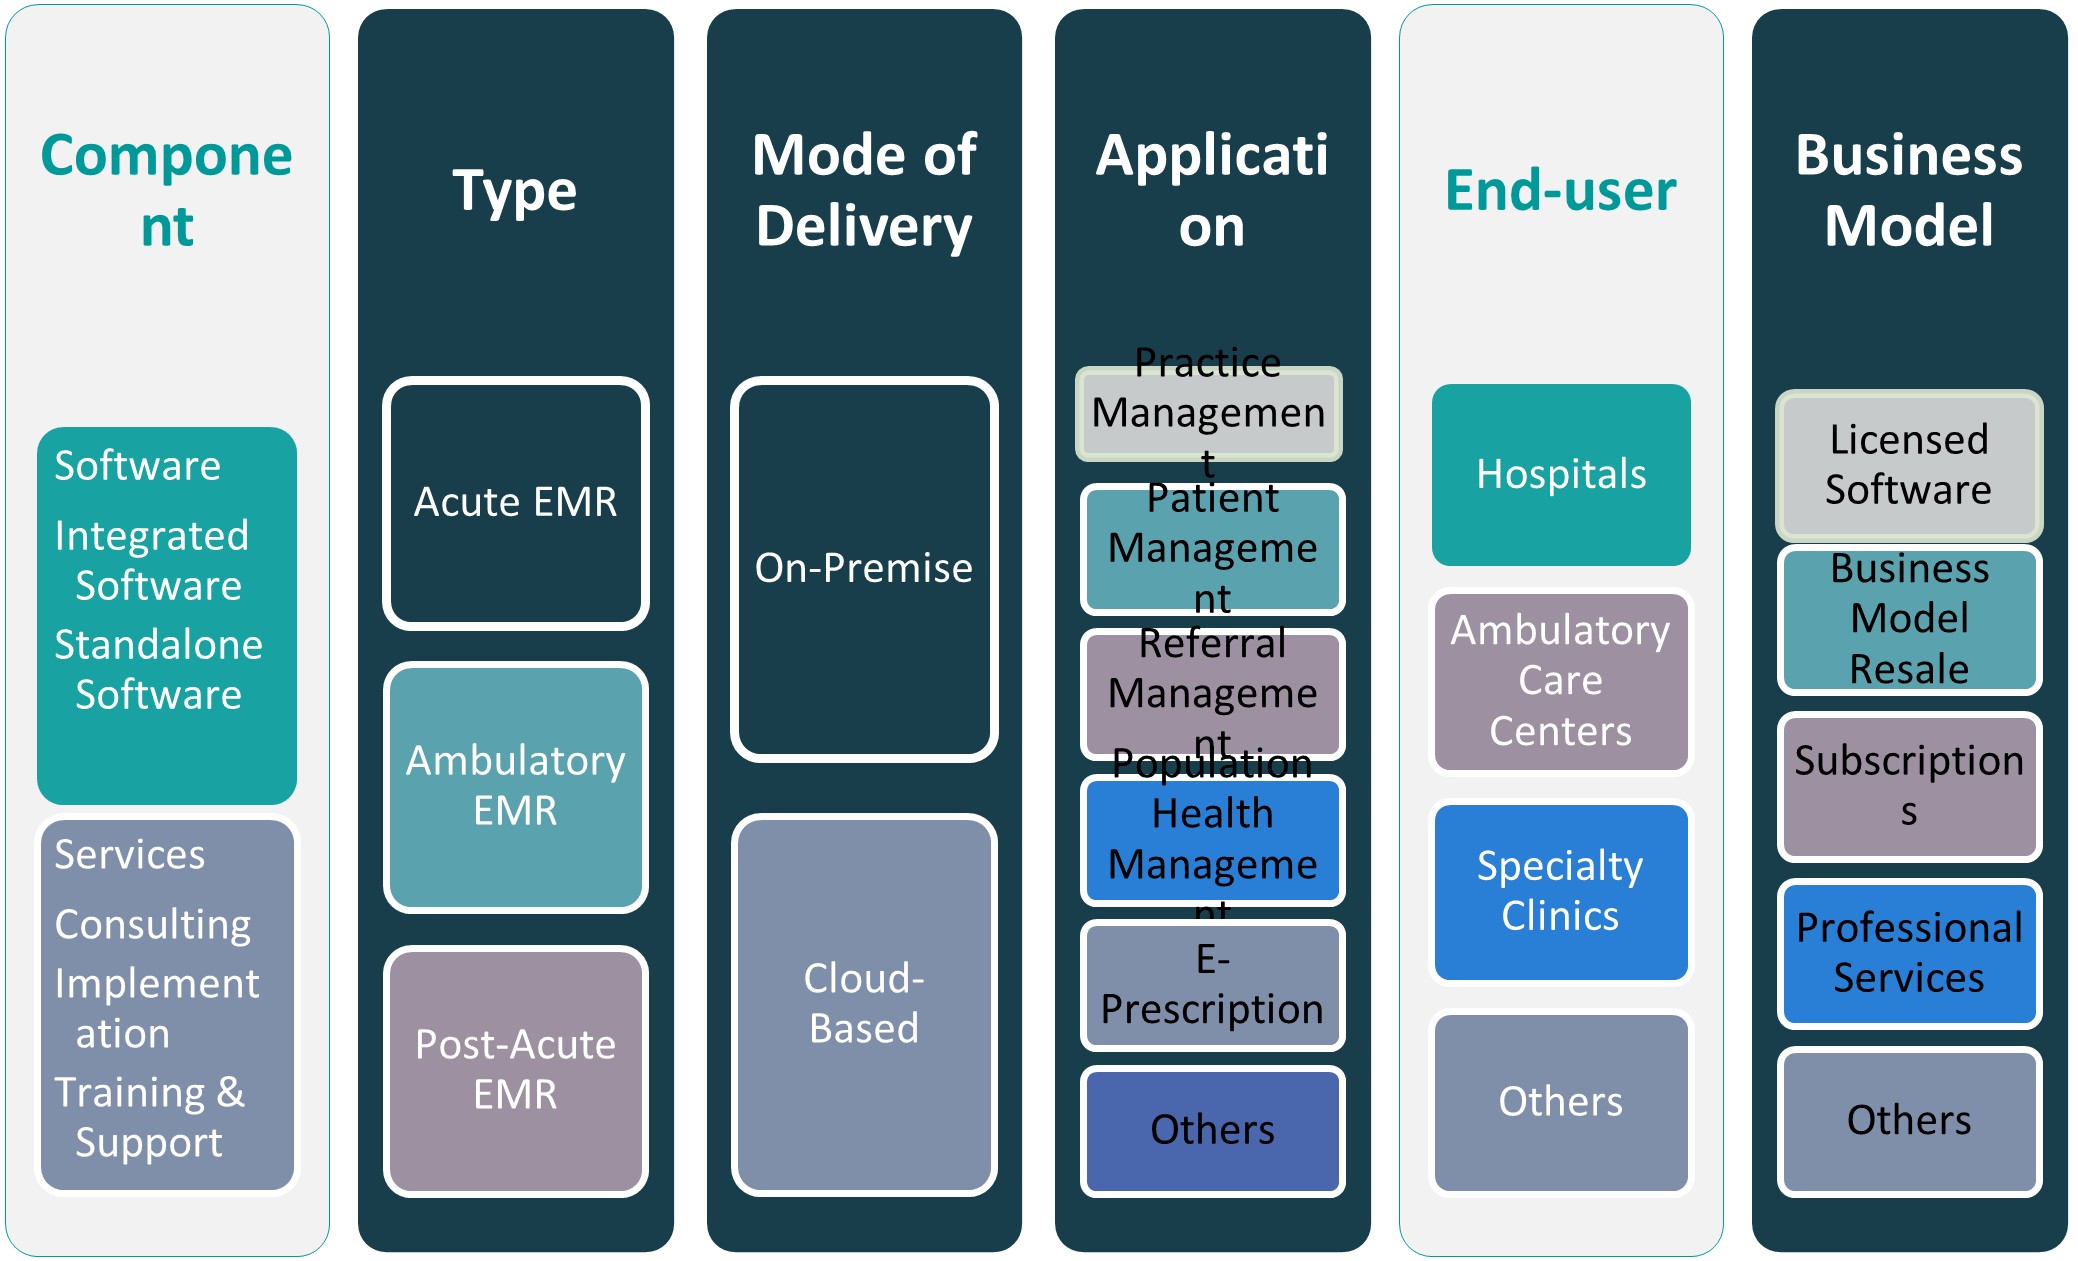
This report segments the UK Electronic Medical Record Market as follows:
Market Drivers
Robust Regulatory and Policy Support Accelerates Digital Health Transition
Governments enforce standards that drive digital record adoption in healthcare. The UK introduced national policies to mandate EMR implementation. The UK Electronic Medical Record Market benefits from compliance with the Data Security and Protection Toolkit and GDPR. It advances quickly when NHS Trusts secure digital transformation funds. Clinicians access training through centrally coordinated initiatives. Payers tie reimbursements to digital maturity metrics.
- For instance, the UK government set a target for 90% of NHS trusts to have electronic health records by 2023, with a goal of achieving 100% adoption by 2025 to enhance patient care and operational efficiency.
Shift Toward Value-Centric Healthcare Funding Models
Healthcare commissioners link funding to patient outcomes and efficiency. The UK Electronic Medical Record Market benefits from cost control and transparent quality metrics. It empowers providers with real time performance tracking to reduce readmissions. Hospitals improve decisions when they analyze data patterns and spot care gaps. Vendors supply analytics modules that deliver actionable insights to clinicians. Policymakers reward institutions that demonstrate improvements under digital health benchmarks.
- For instance, the UK healthcare system has seen a 9.4% increase in government healthcare spending in nominal terms, supporting digital health initiatives and EMR adoption.
Integration of Advanced Technologies Enhances Clinical Workflows
Developers integrate artificial intelligence for predictive diagnostics in EMR platforms. The UK Electronic Medical Record Market adopts interoperability standards to connect health IT systems. It enables seamless data exchange among primary care, hospitals, and community services. Cloud architectures lower infrastructure costs and speed feature upgrades. Providers gain efficiency when voice recognition accelerates documentation tasks. IT teams enforce cybersecurity measures to protect patient information.
Rising Patient Engagement Demands Drive EMR Feature Expansion
Patients demand easy access to health records and appointment tools. The UK Electronic Medical Record Market adapts to support secure online portals and mobile integration. It lets users review test results promptly and share data with specialists. Clinics improve satisfaction when they enable two way messaging in EMR systems. Software designers craft interfaces that simplify navigation and boost accessibility. Health campaigns encourage patients to manage chronic conditions with digital reminders. Public concern over data privacy drives investment in encryption and authentication
Market Trends
Integration of Artificial Intelligence Tools into Clinical Decision Processes
The UK Electronic Medical Record Market adopts AI modules that support diagnostic accuracy and treatment planning. It uses predictive models to identify high-risk patients and recommend care pathways. Clinicians receive real-time alerts when patient data signals urgent concerns. It improves workflow efficiency by cutting manual review tasks. Vendors deliver machine-learning features that detect anomalies in imaging and lab results. It strengthens preventive care when patterns emerge across patient cohorts.
- For instance, NHS England has implemented AI-driven diagnostic tools in over 500 hospitals to enhance early disease detection and improve patient outcomes
Advancement of Cloud-Based and Mobile EMR Solutions to Enhance Patient Engagement
The UK Electronic Medical Record Market shifts toward scalable cloud architectures that lower IT burden and speed deployment. It grants providers secure remote access to records on any device. Mobile apps let patients review test results and schedule appointments without delays. It reduces latency when teams update data across multiple care settings. Software firms implement standardized APIs that enable data exchange among systems. It supports unified care when primary and secondary services collaborate.
- For instance, more than 70% of healthcare providers in the UK have adopted cloud-based EMR systems to streamline patient data management and improve accessibility
Market Challenges
Data Protection Requirements and Interoperability Barriers Impede Rollout
The UK Electronic Medical Record Market faces strict data protection rules that slow deployment. It must comply with GDPR and NHS security standards to maintain patient trust. Organisations struggle to connect diverse IT systems across hospitals and clinics. It fails when proprietary formats block seamless information exchange. Stakeholders demand unified standards to reduce integration errors. Vendors invest in encryption tools and audit frameworks to meet compliance.
- For instance, Cerner Corporation held the largest share of the UK electronic health records market in 2023, followed by Constellation Software, CompuGroup Medical SE & Co, Concentrix, Leidos, and Veradigm
Infrastructure Deficits and Resource Gaps Hinder Deployment
The UK Electronic Medical Record Market requires healthcare organisations to upgrade legacy systems to support modern EMR software. It suffers from budget constraints that limit hardware and software purchases. Providers lack staff with IT and management expertise to lead digital projects. It stalls when training plans fall behind clinical schedules. Executives must align investments with strategic goals to justify costs. Vendors provide support services to overcome resource shortages.
Market Opportunities
Expansion of Telehealth Platforms and Remote Patient Monitoring Drives Market Penetration
Healthcare providers integrate telehealth and remote diagnostics to broaden service delivery. The UK Electronic Medical Record Market benefits when providers link EMR systems with virtual care platforms. It supports patient engagement when digital check-in and device data feed directly into records. Clinics extend their reach when they offer chronic disease management through connected devices. EMR vendors develop secure modules that capture real-time clinical information. It boosts revenue streams by offering subscription-based access to specialized virtual care. Health networks target rural and under-served communities to close care gaps.
Collaboration with Technology Innovators Enhances Interoperability and Analytics Capabilities
Industry players partner with software developers to advance API-based data sharing. The [ UK Electronic Medical Record Market gains momentum when interoperable frameworks reduce integration costs. It drives innovation through analytics tools that predict patient needs and optimize resource allocation. Hospitals adopt modular EMR extensions to tailor functionality for specialist departments. Vendors expand service suites when they add AI-driven decision support features. It unlocks upselling opportunities when updating legacy installations to cloud-native architectures. Trusts and private providers pursue joint ventures to co-develop patient-centric applications.
Market Segmentation Analysis
By Component
The [ UK Electronic Medical Record Market divides into software offerings and service segments. It covers integrated and standalone software solutions that manage patient records and workflows. Consulting services advise on selection and strategy. Implementation teams configure and deploy systems. Training and support staff ensure user proficiency and system uptime.
By Type
The [ UK Electronic Medical Record Market segments by care setting into acute, ambulatory, and post-acute EMR systems. It addresses hospital demands with robust modules and ambulatory centers with streamlined interfaces. Post-acute solutions facilitate care continuity in rehabilitation and long-term care facilities.
Segments
Based on Component
- Software
- Integrated Software
- Standalone Software
- Services
- Consulting
- Implementation
- Training & Support
Based on Type
- Acute EMR
- Ambulatory EMR
- Post-Acute EMR
Based on Mode of Delivery
- On-Premise
- Cloud-Based
Based on Application
- Practice Management
- Patient Management
- Referral Management
- Population Health Management
- E-Prescription
- Others
Based on Business Model
- Licensed Software
- Business Model Resale
- Subscriptions
- Professional Services
- Others
Based on End User
- Hospitals
- Ambulatory Care Centers
- Specialty Clinics
- Others
Based on Region
- England
- Scotland
- Wales
- Northern Irelan
Regional Analysis
England’s Established Health Network Fuels EMR Uptake
England’s NHS Trust network leads digital record implementation across primary and secondary care. The UK Electronic Medical Record Market benefits when large hospital groups allocate funds for EMR system upgrades. It expands rapidly when integrated software modules streamline clinical workflows. Providers access training and support through centralized programs under NHS Digital. It improves clinician efficiency when it consolidates patient history in a unified view. IT departments enforce security protocols to protect sensitive data.
Scotland and Wales Target Digital Modernization in Healthcare Delivery
Scotland and Wales invest in regional digital health strategies to modernize clinical record management. The UK Electronic Medical Record Market gains momentum when health boards grant funding for cloud-based deployments. It improves regional care coordination by connecting hospitals and community services. Clinicians adopt standardized workflows to reduce duplicate tests and errors. IT teams provide localized training to support user adoption. It reduces delays when data flows securely between primary care and specialty clinics.
Northern Ireland Focuses on Cross-Border Data Coordination and Integration
Northern Ireland navigates cross-border healthcare demands with shared patient information protocols. The UK Electronic Medical Record Market adapts to unique legal frameworks that govern data exchange with the Republic of Ireland. It ensures continuity of care when patients cross the border for treatment. Health organizations implement interoperability standards to link diverse EMR platforms. It minimizes administrative burdens by automating referral and discharge summaries. Stakeholders negotiate agreements to harmonize privacy safeguards and technical specifications
Key players
- Epic Systems Corp
- Cerner Corporation
- InPS
- System C & Graphnet Health
- TPP
Competitive Analysis
Competition centers on feature differentiation, integration capabilities, and service models. The UK Electronic Medical Record Market benefits when leading vendors refine module depth and analytics accuracy. Epic Systems offers comprehensive suites with advanced reporting tools. Cerner competes by supplying scalable platforms and robust interoperability frameworks. InPS delivers configurable solutions that match NHS workflows. System C & Graphnet Health collaborate to provide unified records across community and hospital settings. TPP secures share through primary care and ambulatory modules with intuitive interfaces. Vendors form strategic partnerships to expand cloud services and integrate AI-driven decision support. Providers choose EMR platforms based on deployment speed, total cost of ownership, and compliance history. Industry leaders drive market shifts by updating modules and improving user experience. Market rivalry intensifies when new entrants present niche solutions for telehealth and population health management.
Recent Developments
- In March 2025**, Oracle Health introduced its Health Data Intelligence platform, enabling real-time data monitoring, predictive analytics, and next-best-action workflows across NHS deployments.
- On 4 April 2025**, Graphnet Health appointed Liz Slynn as Commercial and Business Development Director.
- In May 2025**, The Phoenix Partnership began collaborative procurement planning with neighbouring trusts under the ICS convergence strategy for 2025/26.
Market Concentration and Characteristics
The UK Electronic Medical Record Market exhibits moderate to high concentration, with global giants and specialized domestic firms controlling a significant share. It features a handful of Tier 1 vendors that deliver comprehensive platforms and analytics modules. Smaller providers target niche segments such as primary care or post-acute care. Competition hinges on interoperability, compliance, and total cost of ownership. Buyers assess vendors based on proven deployment track record and local support capabilities. Partnerships between EMR companies and IT service firms extend market reach. Market barriers include regulatory demands and legacy system replacement costs. Consolidation occurs when leading players acquire niche innovators to broaden offerings within national healthcare networks.
Report Coverage
The research report offers an in-depth analysis based on Type of Cartilage, Treatment Modalities, Treatment Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market
Future Outlook
- Investments in AI-driven analytics will transform EMR functionality, enabling predictive care pathways and risk stratification across patient cohorts. Leading vendors will integrate robust clinical decision support modules that recommend personalized treatment plans and optimize resource allocation
- Adoption of cloud-native EMR architectures will accelerate deployment and reduce capital expenditure for healthcare providers. Cloud-based platforms will deliver elastic scalability, streamlined updates, enhanced disaster recovery capabilities that support distributed clinical teams, data analytics pipelines, and modern telework models.
- Integration of telehealth services with EMR applications will enhance virtual care delivery and continuity across multiple specialties. Providers will leverage unified systems thatcapture remote consultation data, manage diagnostics workflows, schedule follow-ups automatically, and offer secure two-way communication portals.
- Standardized interoperability frameworks will expand cross-platform data exchange and collaboration across primary, acute, and community services. Health systems will deploy APIs and FHIR-based interfaces that automate referrals, synchronize patient records in real time, enable federated queries, and support multi-vendor system orchestration
- Patient engagement tools embedded in EMR systems will increase self-management, satisfaction, and adherence to treatment plans. User-friendly portals and mobile applications will deliver appointment scheduling, secure messaging, digital educational content, medication reminders, and self-reporting features that empower individuals to participate actively in their care.
- Heightened regulatory scrutiny and evolving cybersecurity threats will drive development of advanced data governance and encryption modules. EMR vendors will innovate compliance-driven functionalities that automate audit trails, enforce granular access controls, manage multi-factor authentication, and monitor anomalous user behavior in line with national data protection mandates.
- Growth of niche EMR solutions tailored to specialty care areas will create significant opportunities for SMEs and start-ups. Vendors focusing on mental health, dentistry, oncology, and rehabilitation workflows will introduce specialized features for custom documentation templates, scheduling, regulatory reporting, and analytics that address unique clinical requirements.
- Emergence of outcome-based and subscription pricing models will align vendor incentives with clinical performance and value-based care metrics. Healthcare organizations will adopt service contracts that tie fees to quality benchmarks, user adoption rates, system uptime, and patient satisfaction outcomes, fostering vendor accountability and scalable growth.
- Expansion into population health management will involve integrated registries and AI-driven analytics dashboards within EMR platforms. Public health agencies and provider networks will leverage aggregated longitudinal data to monitor community health trends, manage chronic disease programs, identify high-risk cohorts, and allocate resources based on predictive modeling insights.
- Collaboration between EMR vendors and IoT device manufacturers will enrich clinical data streams with real-time patient monitoring and remote diagnostics. Integration of wearable sensors and home-based monitoring devices will feed continuous vital signs, activity levels, and biometric metrics directly into clinical records for proactive care intervention.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Robust Regulatory and Policy Support
UK government mandates and compliance frameworks, such as the Data Security and Protection Toolkit and GDPR, require NHS trusts and private hospitals to adopt EMR solutions, accelerating digital transformation and ensuring data security and care quality.
Shift Toward Value-Based Care Funding Models
Healthcare commissioners in the UK increasingly link funding to patient outcomes and efficiency, pushing providers to leverage analytics and decision-support modules within EMR platforms to improve outcomes and control costs.
Integration of Advanced Technologies
The adoption of AI-powered diagnostics, voice-enabled charting, and cloud-based architectures enhances clinical workflows, optimizes documentation, and reduces infrastructure costs, making EMR systems more attractive and effective for healthcare providers.
Rising Patient Engagement Demands
Patients in the UK expect easy access to their health records and digital tools for managing appointments and communication, prompting EMR vendors to expand features such as secure online portals and mobile integration, which improves satisfaction and drives adoption.
Expansion of Telehealth and Remote Monitoring
The integration of telehealth platforms and remote patient monitoring with EMR systems enables broader service delivery, especially in rural and underserved areas, supporting market penetration and new revenue streams for providers and vendors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size in 2023, and what are the projections for 2032 along with its CAGR?
What factors drive growth in the UK EMR market?
Which regions in the UK are leading in EMR adoption?
Who are the key players in the UK EMR market?
What are the major trends influencing the UK EMR market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Acute EMR
- 1.2.2 Ambulatory EMR
- 1.2.3 Post-Acute EMR
- 1.3 By End User
- 1.3.1 Hospitals
- 1.3.2 Ambulatory Care Centers
- 1.3.3 Specialty Clinics
- 1.3.4 Others
- 1.4 By Component
- 1.4.1 Software
- 1.4.2 Integrated Software
- 1.4.3 Standalone Software
- 1.4.4 Services
- 1.4.5 Consulting
- 1.4.6 Implementation
- 1.4.7 Training & Support
- 1.5 By Mode of Delivery
- 1.5.1 On-Premise
- 1.5.2 Cloud-Based
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,857.82 million → 2032: USD 4,368.58 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 UK Electronic Medical Record Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 UK Electronic Medical Record Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 UK Electronic Medical Record Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 UK Electronic Medical Record Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 UK Electronic Medical Record Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 UK Electronic Medical Record Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 UK Electronic Medical Record Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 UK Electronic Medical Record Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,857.82 million → 2032: USD 4,368.58 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 UK Electronic Medical Record Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Acute EMR
- 12.3.7.2 Ambulatory EMR
- 12.3.7.3 Post-Acute EMR
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Ambulatory Care Centers
- 12.4.7.3 Specialty Clinics
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Component - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Software
- 12.5.7.2 Integrated Software
- 12.5.7.3 Standalone Software
- 12.5.7.4 Services
- 12.5.7.5 Consulting
- 12.5.7.6 Implementation
- 12.5.7.7 Training & Support
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Mode of Delivery - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 On-Premise
- 12.6.7.2 Cloud-Based
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 UK Electronic Medical Record End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 UK Electronic Medical Record Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 UK Electronic Medical Record Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 UK Electronic Medical Record Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Epic Systems Corp
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Cerner Corporation
- 18.4 InPS
- 18.5 System C & Graphnet Health
- 18.6 TPP (The Phoenix Partnership)
- 18.7 Allscripts Healthcare Solutions
- 18.8 Orion Health
- 18.9 Meditech
- 18.10 Dedalus Group
- 18.11 EMIS Health
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

