
Market Overview:
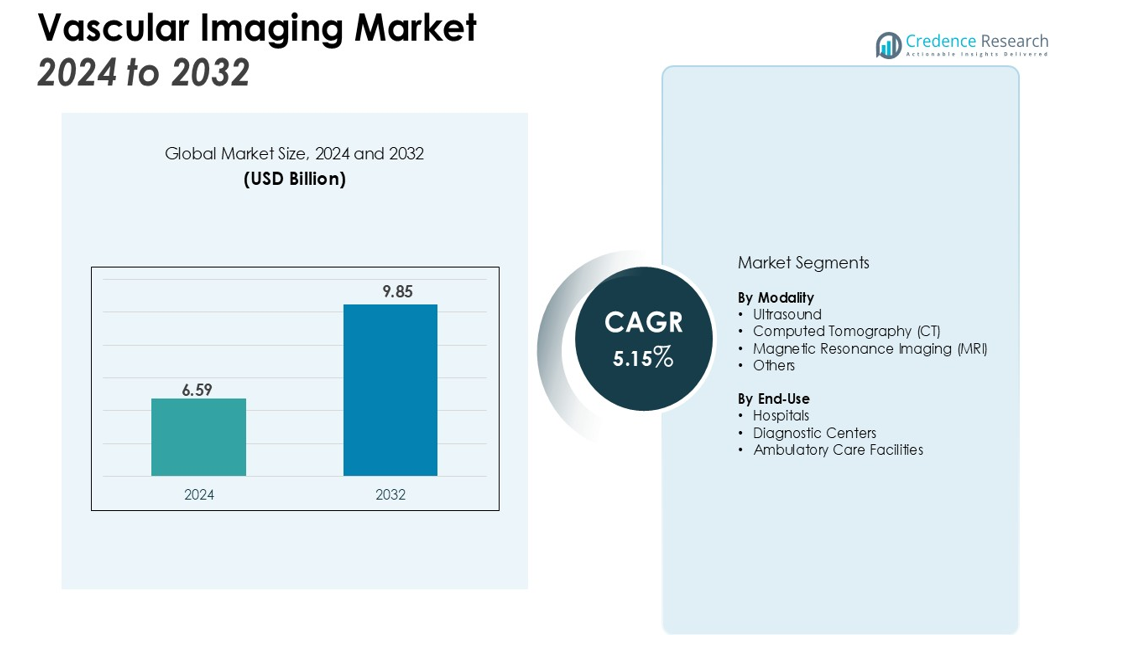
The Vascular Imaging Market size was valued at USD 6.59 billion in 2024 and is anticipated to reach USD 9.85 billion by 2032, at a CAGR of 5.15% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vascular Imaging Market Size 2024 | USD 6.59 billion |
| Vascular Imaging Market, CAGR | 5.15% |
| Vascular Imaging Market Size 2032 | USD 9.85 billion |
Key drivers include the growing geriatric population, rising healthcare expenditures, and increasing incidence of lifestyle-related vascular conditions. The integration of artificial intelligence and machine learning in imaging systems enhances diagnostic accuracy and workflow efficiency, while strong investments in R&D support the development of portable and cost-effective imaging devices. Furthermore, the shift toward preventive healthcare and early disease detection underscores the strategic role of vascular imaging in clinical practices worldwide.
Regionally, North America dominates the market, supported by advanced healthcare infrastructure, high adoption of innovative imaging systems, and strong presence of key industry players. Europe follows with significant demand driven by government-funded healthcare programs and expanding clinical research. Asia-Pacific is expected to witness the fastest growth, attributed to large patient populations, improving healthcare facilities, and rising investment in digital health technologies.
Market Insights:
- The Vascular Imaging Market was valued at USD 6.59 billion in 2024 and will reach USD 9.85 billion by 2032, growing at a CAGR of 5.15%.
- Rising prevalence of cardiovascular diseases and aging populations is driving consistent demand for advanced imaging solutions.
- Integration of AI and machine learning improves diagnostic accuracy, automates workflows, and reduces reporting delays.
- Preventive healthcare models highlight the importance of early diagnosis, boosting investments in vascular imaging infrastructure.
- High system costs and limited access in low-resource regions remain key barriers to market penetration.
- North America leads with 38% share, followed by Europe at 27%, supported by strong infrastructure and adoption rates.
- Asia-Pacific holds 24% share and is the fastest-growing region, while Latin America and Middle East & Africa together account for 11%, offering untapped opportunities.
Market Drivers:
Rising Prevalence of Cardiovascular Diseases and Aging Population
The increasing global burden of cardiovascular diseases is a primary driver of the Vascular Imaging market. A growing aging population contributes to higher risk factors such as hypertension, diabetes, and obesity. Healthcare providers prioritize early detection and monitoring of vascular conditions to improve patient outcomes. This rising demand strengthens adoption of advanced imaging solutions in hospitals and specialty clinics.
- For instance, Philips' Transcend Plus platform for its EPIQ CVx and Affiniti CVx ultrasound systems integrates 26 separate FDA-cleared AI applications to simplify workflows and reduce manual steps for clinicians.
Technological Advancements in Imaging Modalities and Artificial Intelligence Integration
Continuous innovation in imaging modalities supports the market by enhancing precision, speed, and safety. Artificial intelligence integration enables improved diagnostic accuracy, automated image analysis, and reduced reporting time. Vendors invest heavily in AI-driven software and advanced imaging platforms to meet clinical requirements. Vascular Imaging benefits from these advancements by offering more reliable and non-invasive diagnostic tools.
- For instance, Siemens Healthineers' ACUSON Origin ultrasound system incorporates AI technology that delivers more than 5,600 AI-powered measurements for cardiovascular assessments, enhancing workflow efficiency and diagnostic precision.
Shift Toward Preventive Healthcare and Early Diagnosis
Healthcare systems emphasize preventive strategies to reduce long-term treatment costs and improve survival rates. Vascular Imaging plays a vital role in identifying vascular abnormalities before they progress into severe conditions. Patients and providers recognize the value of early diagnosis supported by accurate imaging technologies. This focus increases investments in diagnostic infrastructure across both developed and emerging economies.
Expanding Healthcare Infrastructure and Government Support in Emerging Regions
Improved healthcare facilities in developing markets create significant opportunities for advanced diagnostic tools. Governments allocate funds for modern medical technologies to address rising cases of vascular disorders. Growing awareness among patients encourages demand for accessible diagnostic solutions. The expansion of digital health technologies and tele-radiology services further boosts adoption of Vascular Imaging in underserved regions.
Market Trends:
Integration of Advanced Technologies and AI for Precision Diagnostics
The Vascular Imaging market is witnessing strong adoption of artificial intelligence and machine learning to enhance diagnostic accuracy and efficiency. AI-powered algorithms support clinicians in identifying subtle vascular abnormalities, reducing errors, and improving workflow management. It enables predictive analytics that assist in risk assessment and treatment planning for complex vascular diseases. Cloud-based platforms and advanced software enhance image sharing across healthcare systems, supporting collaboration between specialists. Hybrid imaging solutions that combine modalities such as PET-CT or MRI-ultrasound are gaining traction for delivering detailed vascular insights. These advancements strengthen clinical confidence and create demand for integrated diagnostic systems.
- For instance, the medical imaging company Aidoc has developed an AI platform that includes 17 FDA-cleared algorithms to help physicians by automatically detecting and triaging critical abnormalities from medical scans.
Growing Emphasis on Minimally Invasive and Preventive Healthcare Solutions
Global healthcare systems prioritize non-invasive and preventive methods, fueling demand for advanced imaging procedures. Vascular Imaging supports early detection of aneurysms, arterial blockages, and venous disorders, reducing the need for complex surgical interventions. Patients prefer safer diagnostic options with shorter recovery times, encouraging hospitals to adopt next-generation imaging technologies. Portable and handheld imaging devices expand accessibility in remote and resource-limited settings. It aligns with the increasing focus on personalized healthcare, enabling tailored treatment decisions. Rising investments in tele-radiology and digital imaging networks further extend the reach of vascular diagnostic services across emerging and developed markets.
- For instance, GE HealthCare's Innova IGS 3 interventional system includes a fast-spin rotational angiography feature capable of reaching speeds of 40° per second, which enhances procedural efficiency and detailed imaging.
Market Challenges Analysis:
High Cost of Advanced Imaging Systems and Limited Accessibility
The adoption of Vascular Imaging faces barriers due to the high cost of advanced equipment and supporting infrastructure. Smaller hospitals and clinics in low-resource settings struggle to invest in modern imaging systems. It limits the availability of precise diagnostic tools for large patient populations. Maintenance expenses and specialized training requirements add further financial pressure on healthcare providers. Patients in developing regions often encounter long waiting times or must travel significant distances for vascular diagnostics. These constraints hinder equal access and slow down market expansion.
Regulatory Complexities and Data Management Challenges
Strict regulatory approvals for imaging devices and software create delays in product launches. The Vascular Imaging market must meet rigorous safety and quality standards before clinical use. It requires continuous updates to comply with evolving healthcare regulations across regions. Managing large volumes of imaging data presents further challenges for hospitals and diagnostic centers. Data privacy concerns and interoperability issues between different imaging platforms complicate integration into healthcare workflows. Limited skilled professionals in interpreting advanced imaging results further slows adoption and reduces efficiency in clinical settings.
Market Opportunities:
Expansion of AI-Enabled Imaging and Personalized Healthcare
The Vascular Imaging market has significant opportunities in AI-driven diagnostics and personalized healthcare. Advanced algorithms enhance precision, automate image interpretation, and reduce reporting delays for clinicians. It supports tailored treatment planning by providing detailed insights into patient-specific vascular conditions. Personalized healthcare initiatives increase demand for diagnostic tools that deliver accurate and timely results. Integration of AI with cloud-based platforms further expands access to remote consultations and collaborative analysis. These innovations create strong growth prospects for vendors investing in intelligent imaging solutions.
Growing Demand in Emerging Economies and Preventive Care Models
Emerging economies present large untapped markets for advanced diagnostic technologies. Rising healthcare expenditure and government support accelerate adoption of modern imaging systems in these regions. Vascular Imaging benefits from expanding preventive care programs that prioritize early disease detection. It aligns with the global shift toward cost-effective healthcare and reduced hospitalization. Portable and mobile imaging devices create opportunities in rural and underserved areas, improving diagnostic reach. The combination of infrastructure development and increasing awareness among patients strengthens long-term market growth potential.
Market Segmentation Analysis:
By Modality
The Vascular Imaging market by modality is segmented into ultrasound, computed tomography (CT), magnetic resonance imaging (MRI), and others. Ultrasound leads due to its affordability, non-invasive nature, and wide adoption in routine vascular diagnostics. It remains the preferred choice for detecting arterial blockages, venous disorders, and aneurysms. CT and MRI are gaining strong momentum with superior accuracy, high-resolution imaging, and advanced capabilities for complex vascular assessments. It benefits from technological integration such as AI-driven analysis, improving precision and efficiency across clinical workflows. Growing demand for hybrid modalities combining different imaging techniques supports broader diagnostic applications.
- For instance, DeepHealth, a subsidiary of RadNet, advanced imaging efficiency by connecting more than 300 of its MR, CT, PET/CT, and Ultrasound systems with its TechLive™ remote scanning solution, enabling centralized operation of procedures.
By End-Use
End-use segmentation covers hospitals, diagnostic centers, and ambulatory care facilities. Hospitals dominate with the largest share due to high patient volumes, advanced infrastructure, and strong adoption of cutting-edge imaging platforms. It benefits from well-established reimbursement frameworks that encourage use of advanced diagnostic modalities. Diagnostic centers represent a growing segment, driven by rising demand for outpatient imaging and specialized vascular assessments. Ambulatory care facilities are expanding their role with portable and handheld imaging devices that provide faster and more accessible services. The increasing preference for preventive healthcare accelerates adoption across all end-use segments, reinforcing the importance of vascular diagnostics in diverse care settings.
- For instance, RadNet, Inc. exemplifies the scale of the outpatient imaging sector by performing more than 10 million diagnostic procedures annually across its network of centers.
Segmentations:
By Modality
- Ultrasound
- Computed Tomography (CT)
- Magnetic Resonance Imaging (MRI)
- Others
By End-Use
- Hospitals
- Diagnostic Centers
- Ambulatory Care Facilities
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America and Europe Leading with Advanced Infrastructure and Strong Adoption
North America holds 38% share of the Vascular Imaging market, while Europe accounts for 27%. These regions together represent the largest revenue contribution supported by advanced healthcare systems and high diagnostic adoption. Strong reimbursement policies and widespread use of AI-enabled imaging technologies strengthen regional dominance. It benefits from robust clinical research networks and established presence of leading manufacturers. Government initiatives promoting preventive healthcare further reinforce adoption across hospitals and specialty centers.
Asia-Pacific Emerging as the Fastest-Growing Regional Market
Asia-Pacific holds 24% share of the Vascular Imaging market and is projected to expand rapidly. Large patient populations in China, India, and Japan drive significant demand for advanced diagnostic tools. It gains further momentum from growing healthcare investments and digital health reforms. Regional players collaborate with global firms to provide cost-effective imaging solutions across diverse healthcare settings. Improved awareness of preventive care increases patient demand for early and precise vascular diagnosis. Expansion of urban healthcare facilities positions Asia-Pacific as the fastest-growing regional segment.
Latin America and Middle East & Africa Offering Untapped Growth Potential
Latin America holds 6% share of the Vascular Imaging market, while Middle East & Africa represent 5%. These regions are at an early stage of adoption but display strong potential for growth. Limited diagnostic infrastructure is gradually improving through government initiatives and private investments. It gains traction through mobile imaging units and tele-radiology services reaching underserved populations. Training programs enhance clinical capacity while affordable technologies expand access. Growing burden of cardiovascular diseases supports steady demand in these emerging regions.
Key Player Analysis:
- Samsung Medison Co., Ltd
- GE Healthcare
- Abbott Laboratories
- Koninklijke Philips N.V.
- Siemens Healthineers
- Shimadzu Corporation
- Hologic Inc.
- Hitachi Medical Corporation
- Carestream Health Inc.
Competitive Analysis:
The Vascular Imaging market is highly competitive with global and regional players focusing on innovation, product differentiation, and strategic partnerships. Leading companies invest heavily in research and development to integrate artificial intelligence and advanced software into imaging platforms, enhancing diagnostic accuracy and workflow efficiency. It benefits from collaborations between healthcare providers and technology firms that accelerate adoption of next-generation imaging solutions. Major players also expand their presence through mergers, acquisitions, and distribution agreements to strengthen global reach. Pricing strategies and customer service remain critical differentiators in a market where hospitals and diagnostic centers demand cost-effective yet precise tools. The competitive landscape reflects strong emphasis on portable and non-invasive technologies, addressing the rising demand for accessible and preventive healthcare solutions. This dynamic environment pushes companies to continually improve offerings and sustain their position in a growing global market.
Recent Developments:
- In September 2025, Siemens Healthineers launched its first United States-based Experience Center in Charlotte, North Carolina, to showcase its latest technologies.
- In September 2025, Hitachi Ltd. announced its agreement to acquire Synvert, a German data and artificial intelligence consulting firm, through its U.S. subsidiary, GlobalLogic Inc.
- In January 2025, Siemens Healthineers launched its NAEOTOM Alpha.Prime CT scanner at Arab Health 2025.
Report Coverage:
The research report offers an in-depth analysis based on Modality, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for advanced vascular diagnostics will rise with increasing global cardiovascular cases.
- Artificial intelligence will play a central role in improving accuracy and reducing reporting delays.
- Portable and handheld imaging devices will expand access to underserved and rural populations.
- Cloud-based platforms will support image sharing, collaboration, and tele-radiology across healthcare networks.
- Hybrid imaging systems combining modalities will gain adoption for comprehensive vascular assessments.
- Hospitals will continue to dominate adoption due to infrastructure and integration of advanced platforms.
- Diagnostic centers will grow rapidly, driven by outpatient demand and specialized imaging services.
- Preventive healthcare initiatives will strengthen the role of vascular imaging in early diagnosis.
- Emerging economies will offer strong growth potential supported by investments in healthcare infrastructure.
- Strategic collaborations between technology providers and healthcare institutions will shape the competitive landscape.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Cardiovascular Diseases and Aging Population
The increasing global burden of cardiovascular diseases, coupled with a growing aging population, is driving demand for vascular imaging as early detection and monitoring become critical for improving patient outcomes.
Technological Advancements and AI Integration
Continuous innovation in imaging modalities, especially the integration of artificial intelligence and machine learning, enhances diagnostic accuracy, automates workflows, and reduces reporting delays, making vascular imaging more effective and appealing to healthcare providers.
Shift Toward Preventive Healthcare and Early Diagnosis
Healthcare systems are emphasizing preventive strategies to reduce long-term treatment costs and improve survival rates, leading to increased investments in vascular imaging infrastructure for early identification of vascular abnormalities.
Expanding Healthcare Infrastructure in Emerging Regions
Improved healthcare facilities and government support in developing markets are creating significant opportunities for advanced diagnostic tools, expanding the reach of vascular imaging to underserved populations.
Growing Adoption of Portable and Non-Invasive Imaging Devices
The demand for portable and handheld imaging devices is rising, especially in rural and resource-limited settings, as they provide accessible, non-invasive, and efficient diagnostic solutions for vascular conditions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Vascular Imaging, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Vascular Imaging projected to grow between 2024 and 2032?
Which Vascular Imaging segment held the largest share in 2024?
What are the primary factors fueling the growth of the Vascular Imaging?
Who are the leading companies in the Vascular Imaging?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Hospitals
- 1.2.2 Diagnostic Centers
- 1.2.3 Ambulatory Care Facilities
- 1.3 By Modality
- 1.3.1 Ultrasound
- 1.3.2 Computed Tomography (CT)
- 1.3.3 Magnetic Resonance Imaging (MRI)
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6.59 billion → 2032: USD 9.85 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Vascular Imaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Vascular Imaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Vascular Imaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Vascular Imaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Vascular Imaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Vascular Imaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Vascular Imaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Vascular Imaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6.59 billion → 2032: USD 9.85 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Vascular Imaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Diagnostic Centers
- 12.3.7.3 Ambulatory Care Facilities
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Modality - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Ultrasound
- 12.4.7.2 Computed Tomography (CT)
- 12.4.7.3 Magnetic Resonance Imaging (MRI)
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Vascular Imaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Vascular Imaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Vascular Imaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Vascular Imaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Samsung Medison Co., Ltd
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GE Healthcare
- 18.4 Abbott Laboratories
- 18.5 Koninklijke Philips N.V.
- 18.6 Siemens Healthineers
- 18.7 Shimadzu Corporation
- 18.8 Hologic Inc.
- 18.9 Hitachi Medical Corporation
- 18.10 Carestream Health Inc.
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

