
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Feminine Hygiene Products Market Size 2023 | USD 971.53 million |
| UK Feminine Hygiene Products Market, CAGR | 7.11% |
| UK Feminine Hygiene Products Market Size 2032 | USD 1,803.77 million |
Market Overview:
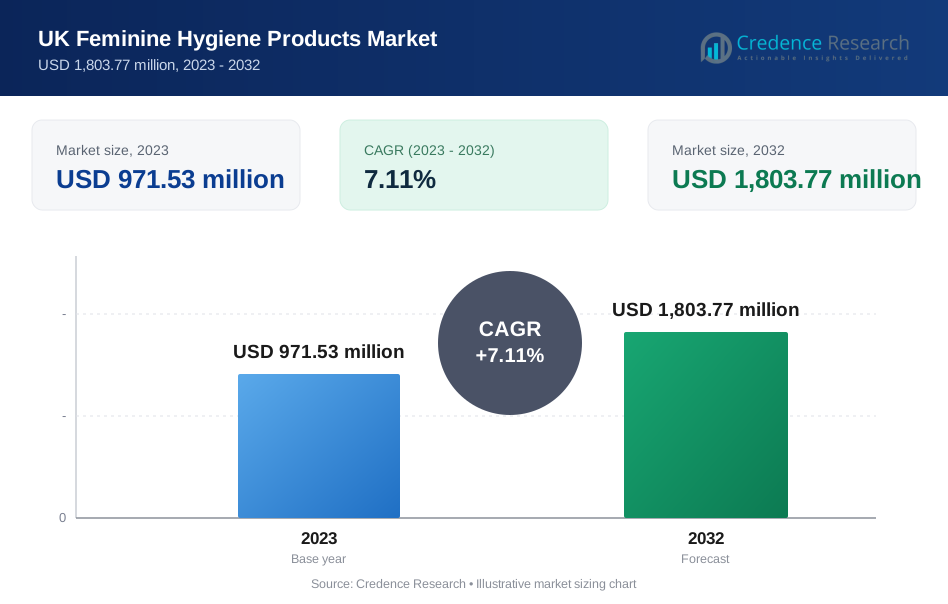
UK Feminine Hygiene Products size was valued at USD 971.53 million in 2023 and is anticipated to reach USD 1,803.77 million by 2032, at a CAGR of 7.11% during the forecast period (2023-2032).
The UK feminine hygiene products market is driven by several key factors. Increasing awareness of menstrual health and hygiene is one of the most significant drivers, with a growing number of consumers prioritizing personal well-being and seeking products that offer comfort and reliability. Additionally, the rising trend toward sustainability is influencing consumer choices, as more individuals opt for eco-friendly alternatives such as organic cotton products, menstrual cups, and reusable pads. This shift is further supported by concerns over environmental impact and waste reduction. Furthermore, government initiatives, including the removal of the "tampon tax" and programs offering free period products in schools and public facilities, have improved accessibility and affordability, making these products more available to a broader population. These factors collectively contribute to the market’s growth trajectory.
The UK is part of the broader European feminine hygiene products market, which continues to grow steadily. In the UK specifically, the market is experiencing a shift, with an increasing focus on sustainability alongside traditional product offerings. The government's policies, such as the removal of taxes on sanitary products and the distribution of free products in public institutions, are playing a critical role in supporting the market’s development. This government support, combined with the growing demand for both convenience and environmentally friendly alternatives, is fostering an evolving market landscape. As consumer preferences continue to prioritize health, sustainability, and accessibility, the UK market is well-positioned to experience continued growth.
Market Insights:
- UK Feminine Hygiene Products size was valued at USD 971.53 million in 2023 and is anticipated to reach USD 1,803.77 million by 2032, at a CAGR of 7.11% during the forecast period (2023-2032).
- The global feminine hygiene products market, valued at USD 23,490.00 million in 2023, is projected to reach USD 43,917.35 million by 2032, growing at a CAGR of 7.2% from 2023 to 2032.
- Consumer preferences are shifting towards sustainable and eco-friendly products, with a significant portion expressing interest in organic and biodegradable alternatives.
- Government initiatives, such as the removal of the "tampon tax" and programs offering free period products in schools and public facilities, have improved accessibility and affordability.
- Companies are increasingly investing in research and development to create products that cater to evolving consumer preferences, including the demand for comfort, convenience, and effectiveness.
- The high cost associated with premium products, especially organic and eco-friendly options, can limit their accessibility, particularly for price-sensitive consumers.
- Despite the increasing availability of feminine hygiene products, period poverty remains a significant challenge in the UK, affecting individuals in lower-income or marginalized communities.
- Cultural and societal stigma surrounding menstruation, although decreasing, remains a challenge in the UK market, potentially deterring individuals from exploring alternative products such as menstrual cups or reusable pads.
Market Drivers:
Rising Awareness of Menstrual Health
One of the most significant drivers for the growth of the UK feminine hygiene products market is the increasing awareness of menstrual health. Over recent years, there has been a shift in societal attitudes towards menstruation, with greater emphasis on education and open discussions around menstrual hygiene. This awareness has resulted in women being more proactive in choosing high-quality hygiene products that ensure comfort and cleanliness during menstruation. As consumers gain more knowledge about the importance of maintaining good menstrual hygiene for overall health, they are more inclined to invest in products that align with these health-conscious choices. This rising awareness is, in turn, expanding the consumer base for feminine hygiene products across the UK.
Demand for Sustainable and Eco-Friendly Products
Environmental concerns have significantly impacted purchasing behaviors in the UK, with an increasing number of consumers prioritizing sustainability. The feminine hygiene products market has seen a growing demand for eco-friendly alternatives, such as organic cotton products, reusable menstrual cups, and biodegradable pads. Consumers are becoming more conscious of the environmental impact of disposable hygiene products and are seeking sustainable options that reduce waste and carbon footprints. For instance, Bodywise (U.K.) Limited offers the Natracare product range, which includes tampons, panty liners, wipes, and pads made with 100% organic cotton, sustainably sourced wood pulp, all certified vegan. The shift towards these eco-conscious products is not only driven by individual choices but also by broader societal trends favoring sustainability, as well as increasing government and corporate initiatives promoting green alternatives. As sustainability continues to be a key factor in purchasing decisions, the demand for these products is expected to grow.
Government Support and Policy Changes
Government initiatives and policy changes have also played a crucial role in driving the growth of the feminine hygiene products market in the UK. For instance, the UK government’s free period product scheme has seen 94% of secondary schools and 90% of post-16 organizations order free period products for students, with 13,822 organizations participating since the scheme began in 2020. In addition, several government programs provide free sanitary products to individuals in schools, public buildings, and other public spaces, further reducing barriers to access. These measures not only support women’s health and well-being but also align with the UK's broader goals of improving menstrual health awareness and combating period poverty. Such policies have provided a favorable market environment, helping to ensure a steady growth trajectory for feminine hygiene products.
Innovation in Product Offerings
The UK feminine hygiene products market is also being driven by continuous innovation in product offerings. Companies are increasingly investing in research and development to create products that cater to evolving consumer preferences, including the demand for comfort, convenience, and effectiveness. Innovations such as ultra-thin pads, organic and chemical-free alternatives, and products designed for different stages of menstruation have diversified the market. Additionally, technological advancements in product design, such as odor-control features and moisture-wicking capabilities, have further enhanced the user experience. As consumer expectations continue to rise, companies that innovate and offer differentiated, high-quality products are likely to benefit from sustained market growth.
Market Trends:
Shift Towards Organic and Natural Products
One of the prominent trends in the UK feminine hygiene products market is the growing demand for organic and natural products. As consumers become more conscious of the ingredients in personal care items, there has been a marked increase in the preference for products free from synthetic chemicals, fragrances, and dyes. For instance, Seventh Generation Inc. and The Honest Company Inc. offer certified organic feminine care products, highlighting their commitment to transparency in ingredient sourcing and eco-friendly packaging. This shift is especially notable among environmentally-conscious consumers who are looking for organic cotton pads, tampons, and other feminine hygiene products. This trend reflects a broader movement toward natural personal care items that are perceived as safer for both the body and the environment. With increasing concerns about the long-term health effects of synthetic materials, the market for organic and chemical-free feminine hygiene products is expected to continue growing.
Rising Popularity of Subscription Services
Another trend shaping the UK feminine hygiene products market is the rise of subscription-based services. Subscription models offer consumers the convenience of receiving regular deliveries of their preferred hygiene products, which has proven popular among busy individuals seeking a hassle-free shopping experience. For instance, companies such as Ohne and TOTM Organics Inc. have launched customizable subscription boxes that allow consumers to receive regular deliveries of their preferred organic pads, tampons, or menstrual cups directly to their doors. These services allow consumers to customize their deliveries, select eco-friendly options, and avoid the inconvenience of running out of essential products. Subscription services also offer an opportunity for brands to build stronger customer loyalty through personalized offerings and timely deliveries. As convenience continues to be a priority, especially in the fast-paced modern lifestyle, this trend is likely to see sustained growth.
Technological Advancements in Product Design
Technological innovations in product design have also become a significant trend in the UK feminine hygiene products market. Companies are increasingly focusing on improving the functionality and comfort of their products through the use of advanced materials and technologies. For instance, pads and tampons are now designed with better absorbent materials, odor-control features, and moisture-wicking capabilities. Additionally, wearable technology such as smart menstrual cups is gaining popularity, providing users with the ability to track their menstrual health through mobile apps. These technological advancements are enhancing the overall user experience, and the market is seeing a rise in demand for products that combine comfort with innovative features that cater to modern needs.
Increased Focus on Inclusivity and Diversity
An emerging trend in the UK feminine hygiene market is the growing focus on inclusivity and diversity. Brands are becoming more attuned to the diverse needs of consumers by offering a wider range of products that cater to various preferences, body types, and menstrual needs. This includes products designed for different flow levels, as well as those that consider the needs of individuals with sensitive skin or allergies. Additionally, there has been a noticeable shift towards marketing strategies that highlight diversity, ensuring that women from all backgrounds feel represented. The increasing recognition of menstruation as a universal experience, along with the growing acceptance of non-binary and transgender individuals, is further influencing this trend. This inclusivity is fostering stronger connections with consumers and encouraging market expansion.
Market Challenges Analysis:
High Product Costs
One of the key restraints in the UK feminine hygiene products market is the high cost associated with premium products, especially organic and eco-friendly options. While there is a growing demand for these products, their higher price points compared to traditional options can limit their accessibility, particularly for price-sensitive consumers. For example, a WaterAid survey in 2024 found that 1 in 4 of UK women and girls reported struggling to afford period products in the last year, and 1 in 5 worried about affording them in the future, highlighting both heightened awareness and ongoing challenges. The cost of raw materials, such as organic cotton, along with the manufacturing processes involved in creating eco-friendly alternatives, contributes to these higher prices. This cost disparity can hinder the widespread adoption of sustainable feminine hygiene products, particularly among lower-income groups, potentially slowing the market’s growth.
Period Poverty and Accessibility Issues
Despite the increasing availability of feminine hygiene products, period poverty remains a significant challenge in the UK. Many individuals still face barriers in accessing basic menstrual products due to financial constraints. Although government initiatives like the provision of free products in schools have helped, period poverty continues to affect certain populations, particularly those in lower-income or marginalized communities. The ongoing issue of accessibility-especially for those who cannot afford or access sanitary products-limits the market's overall growth potential and highlights a need for further policy interventions and social support.
Cultural and Societal Stigma
Cultural and societal stigma surrounding menstruation, although decreasing, remains a challenge in the UK market. Despite increased awareness and open conversations, some women still face embarrassment or discomfort when purchasing feminine hygiene products. This stigma can influence consumer behavior, particularly among younger individuals, and may deter them from exploring alternative products such as menstrual cups or reusable pads. As long as these societal barriers exist, the market for innovative and sustainable products may face slower adoption rates.
Regulatory and Environmental Compliance
The UK feminine hygiene market also faces challenges related to stringent regulatory and environmental compliance. The increasing demand for eco-friendly products puts pressure on manufacturers to meet sustainability standards while maintaining product effectiveness. Additionally, manufacturers must comply with complex regulations regarding product safety and labeling, which can be time-consuming and costly. These regulatory hurdles may limit the pace at which brands can innovate and scale their operations.
Market Opportunities:
The UK feminine hygiene products market presents significant opportunities for growth driven by evolving consumer preferences and increasing demand for sustainable alternatives. As awareness of the environmental impact of traditional sanitary products grows, there is a rising shift toward eco-friendly options, such as organic cotton pads, reusable menstrual cups, and biodegradable products. Brands that focus on developing and promoting sustainable, environmentally conscious products stand to capture the growing market segment of eco-aware consumers. This trend aligns with the broader global movement towards sustainability and offers an opportunity for innovation, especially as consumers seek out products that align with their values of health, comfort, and environmental responsibility. The continued expansion of e-commerce platforms also provides an opportunity to reach a broader audience, making it easier for consumers to access sustainable feminine hygiene products.
Furthermore, there is considerable market potential in the development of subscription-based services for feminine hygiene products. These services cater to consumers seeking convenience and regularity in their purchases while offering a personalized experience. Subscription models also allow brands to establish a direct relationship with customers, build loyalty, and offer tailored products based on individual preferences. This growing demand for convenience and customization presents a key opportunity for companies to capture long-term customer loyalty. Additionally, the rise of innovation in product features, such as smart menstrual cups and wearable technology, offers new opportunities to cater to health-conscious consumers who value advanced functionality and data-driven insights for menstrual health management.
Market Segmentation Analysis:
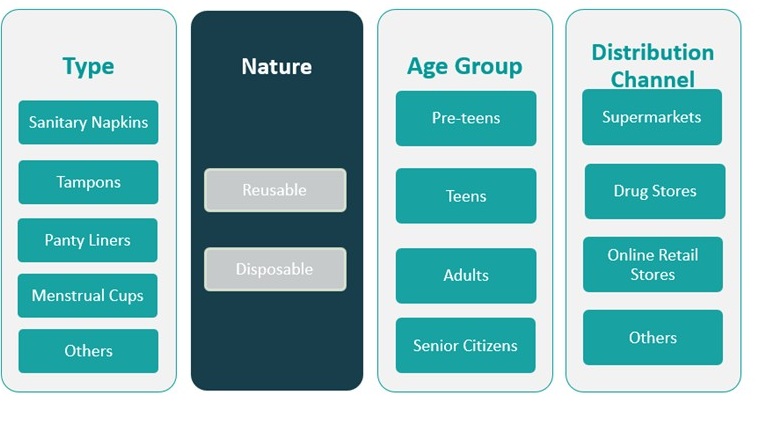
The UK feminine hygiene products market is segmented across various categories, each reflecting distinct consumer preferences and usage patterns.
By type, sanitary napkins dominate the market, driven by their wide availability and ease of use. Tampons and panty liners follow, with tampons particularly popular among active women due to their convenience and comfort. Menstrual cups, although a smaller segment, are gaining traction due to their eco-friendliness and cost-effectiveness, appealing to environmentally conscious consumers. The "others" category includes products like period underwear, which are also gaining popularity due to their comfort and sustainability.
By nature into reusable and disposable products. Disposable products, including sanitary napkins, tampons, and panty liners, remain the dominant segment due to their convenience and widespread availability. However, the reusable segment, including menstrual cups and cloth pads, is witnessing a steady growth driven by the increasing demand for eco-friendly options and cost-saving benefits over time.
By age-group segmentation, adults represent the largest consumer base, with products tailored to different flow levels and preferences. The pre-teens and teens segments are growing, driven by educational initiatives and greater awareness of menstrual health. The senior citizens' segment, though smaller, is also gaining attention due to products designed for comfort and ease of use for women experiencing menopause or post-menopause.
By distribution channel, supermarkets remain the largest point of sale, followed by drug stores and online retail stores, which are gaining prominence due to the convenience and privacy they offer. The "others" segment includes niche channels like health stores and subscription services, catering to specific consumer needs.
Segmentation:
By Type
- Sanitary Napkins
- Tampons
- Panty Liners
- Menstrual Cups
- Others
By Nature
- Reusable
- Disposable
By Age-Group
- Pre-teens
- Teens
- Adults
- Senior Citizens
By Distribution Channel
- Supermarkets
- Drug Stores
- Online Retail Stores
- Others
Regional Analysis:
The UK feminine hygiene products market is segmented into several key regions, each contributing to the overall market share with distinct dynamics. In the past few years, regional variations have become more prominent due to factors such as consumer behavior, regional income levels, and the availability of products. The market is driven by the increasing awareness surrounding menstrual health, sustainability concerns, and the shift toward premium and eco-friendly products.
In England, the largest market share in the UK, the growth of the feminine hygiene products market is fueled by a high level of awareness, disposable income, and a significant urban population. English women are increasingly shifting towards organic and eco-friendly menstrual hygiene solutions, including biodegradable sanitary pads, tampons, and menstrual cups. The rise in online retailing and the presence of a large number of supermarkets contribute further to the region's dominance in market sales, accounting for nearly 50% of the overall UK market share. The convenience of these distribution channels, coupled with growing health consciousness, has led to steady market growth.
In Scotland, the market is also experiencing growth, but at a relatively slower pace compared to England. The adoption of eco-friendly products is on the rise, especially in urban areas like Edinburgh and Glasgow, where sustainable lifestyles are becoming more prevalent. Scotland accounts for approximately 20% of the UK feminine hygiene products market share, driven by increasing educational initiatives and governmental support for menstrual health awareness. Additionally, regional regulations promoting environmental sustainability are encouraging the shift towards reusable products.
In Wales, a moderate yet steady increase in the demand for feminine hygiene products is observed. The market share of Wales stands at around 15%, with rural areas contributing to a slower uptake of premium and organic products. However, the region's urban areas, particularly Cardiff, have seen a rise in awareness campaigns and product availability, fostering growth. Sustainable menstruation products have gained attention, particularly among young women seeking natural alternatives.
Northern Ireland holds the smallest share, approximately 15%, in the UK feminine hygiene products market. However, similar to other regions, the demand for environmentally friendly products is growing. Northern Ireland is showing a gradual shift towards premium hygiene products, but cultural and societal norms still influence the pace of change in consumer behavior. Awareness campaigns and the rising acceptance of modern hygiene products continue to drive modest growth.
Key Player Analysis:
- Johnson & Johnson
- Procter & Gamble
- Kimberly-Clark
- Essity Aktiebolag
- Kao Corporation
- Daio Paper Corporation
- Unicharm Corporation
- Premier FMCG
- Ontex
- Hengan International Group Company Ltd
- Drylock Technologies
- Natracare LLC
- First Quality Enterprises, Inc
- Pearroc
Competitive Analysis:
The UK feminine hygiene products market is highly competitive, with a mix of well-established global brands and emerging eco-conscious players. Leading companies, such as Procter & Gamble (with brands like Always), Kimberly-Clark (with Huggies), and Unilever, dominate the market due to their extensive distribution networks, strong brand recognition, and product variety. These companies continue to innovate, focusing on product quality, comfort, and convenience, while also exploring sustainable options to meet the growing demand for eco-friendly products. In recent years, smaller brands such as TOTM and Mooncup have gained traction by catering to the increasing preference for natural and reusable products. These brands leverage sustainability as their key selling point, appealing to environmentally conscious consumers. The competition is further intensified by new entrants offering subscription services, enhancing customer convenience and loyalty. To maintain market leadership, companies are focusing on technological advancements and sustainable practices to align with consumer preferences and regulatory pressures.
Recent Developments:
- In November 2024, Unicharm Corporation announced its entry into the African market with the launch of Sofy sanitary products in Ghana, Côte d'Ivoire, and Kenya. While this expansion is focused on Africa, it highlights Unicharm’s global growth strategy and commitment to women’s health and hygiene, which may influence future activities in the UK and other regions.
- In October 2024, the Gift Wellness Foundation, in partnership with Qualitas, launched the "Period Angels" initiative in the UK, aiming to eliminate period poverty by 2025. Central to this partnership is the Period Angels app, which connects individuals in need with free menstrual products through local GP practices and community donors. The initiative plans to establish stations nationwide, ensuring access to period essentials for those unable to afford them
- In February 2022, Kimberly-Clark Corporation acquired a majority stake in Thinx Inc., a company specializing in reusable period underwear. Although Kimberly-Clark is a US-based company, it has a significant presence in the UK feminine hygiene market. This acquisition is expected to strengthen its product portfolio and retail partnerships in the UK, particularly in the growing segment of sustainable menstrual products.
Market Concentration & Characteristics:
The UK feminine hygiene products market is moderately concentrated, with a combination of dominant multinational corporations and emerging eco-conscious brands. Leading global players such as Procter & Gamble (Always), Kimberly-Clark (Kotex), and Essity (Libresse) command a significant share of the market. These companies benefit from extensive distribution networks, strong brand recognition, and substantial marketing budgets, enabling them to maintain a competitive edge. However, the market also sees increasing competition from smaller, niche brands that focus on sustainability and natural ingredients, catering to the growing consumer demand for eco-friendly products. Consumer preferences in the UK are evolving, with a noticeable shift towards products that are environmentally friendly and ethically produced. This trend is evident in the rising popularity of reusable menstrual cups, organic cotton pads, and biodegradable products. Brands that align with these values are gaining traction, particularly among younger, environmentally conscious consumers. Additionally, the market is characterized by high brand loyalty, with consumers often remaining committed to their preferred brands. This loyalty presents both opportunities and challenges for companies looking to introduce new products or gain market share.
Report Coverage:
The research report offers an in-depth analysis based on Type, Nature, Age-Group and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is expected to experience steady growth driven by increased consumer demand and evolving market trends.
- There will be a significant shift towards reusable and eco-friendly products as consumers become more environmentally conscious.
- Innovations in product features, such as advanced odor-control technologies and skin-sensitive materials, will enhance user experience and broaden appeal.
- Digital health tools, including period tracking apps and wearable devices, are likely to influence purchasing decisions and product development.
- Subscription-based delivery models are expected to rise in popularity, offering convenience and strengthening brand loyalty among consumers.
- Government initiatives aimed at improving menstrual equity will continue to expand market access and make products more affordable.
- Growing awareness and education surrounding menstrual health will drive demand for a wider variety of feminine hygiene products.
- The market is likely to become more inclusive, with products catering to the needs of transgender and non-binary individuals.
- Economic factors, such as disposable income and cost-of-living pressures, will influence consumer purchasing behavior and product choices.
- The competitive landscape will become more dynamic, with both established brands and new entrants competing to meet evolving consumer preferences.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the UK Feminine Hygiene Products Market?
What factors are driving the growth of the UK Feminine Hygiene Products market?
What are some challenges faced by the UK Feminine Hygiene Products market?
Who are the major players in the UK Feminine Hygiene Products Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Feminine Hygiene Products Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Feminine Hygiene Products Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 971.53 million → 2032: USD 1,803.77 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Feminine Hygiene Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Feminine Hygiene Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Feminine Hygiene Products Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Feminine Hygiene Products Market Drivers
- 3.3 UK Feminine Hygiene Products Market Restraints & Challenges
- 3.4 UK Feminine Hygiene Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Feminine Hygiene Products Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Feminine Hygiene Products Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Feminine Hygiene Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Feminine Hygiene Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Feminine Hygiene Products Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Feminine Hygiene Products market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Feminine Hygiene Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Feminine Hygiene Products Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Feminine Hygiene Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Feminine Hygiene Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Feminine Hygiene Products Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Feminine Hygiene Products Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Feminine Hygiene Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Feminine Hygiene Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Feminine Hygiene Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Feminine Hygiene Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Feminine Hygiene Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Feminine Hygiene Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Feminine Hygiene Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
