
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
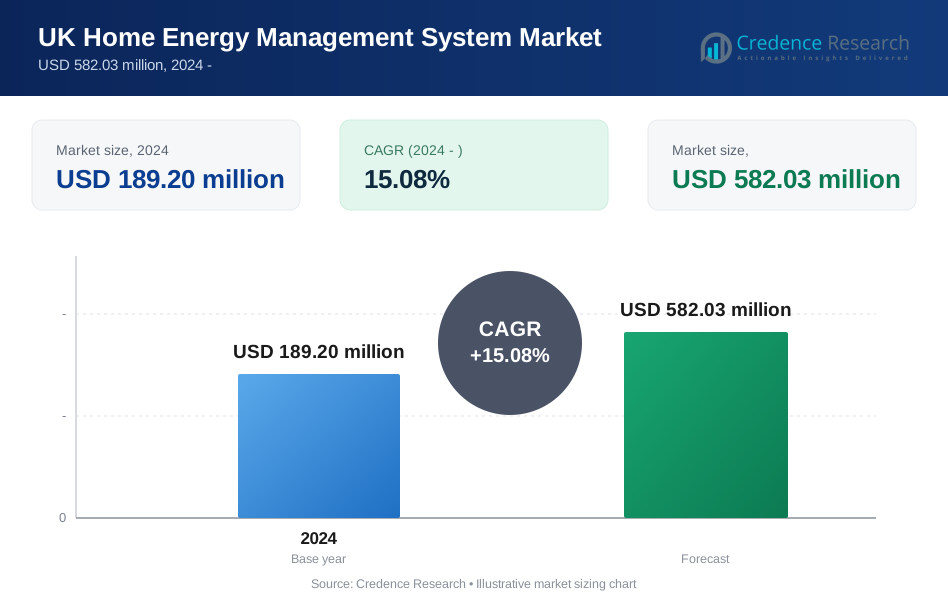
| UK Home Energy Management System market Size 2023 | USD 189.20 million |
| UK Home Energy Management System market , CAGR | 15.08% |
| UK Home Energy Management System market Size 2032 | USD 582.03 million |
Market Overview
The UK Home Energy Management System market is projected to grow from USD 189.20 million in 2024 to USD 582.03 million by 2032, with a compound annual growth rate of 15.08%.
The UK Home Energy Management System market is driven by increasing consumer awareness of energy conservation, rising energy costs, and government incentives for energy-efficient solutions. Technological advancements, such as smart meters and IoT integration, are enhancing system capabilities and user experience. The trend towards sustainable living and the adoption of renewable energy sources further propel market growth. Additionally, the growing emphasis on reducing carbon footprints and achieving energy security supports the demand for advanced energy management systems in residential settings.
The UK Home Energy Management System market is characterized by a diverse geographical landscape, with key players strategically positioned across the country. London, being the economic and technological hub, attracts significant market activity, with prominent players such as Honeywell International Inc., Vivint, Inc., and Ecobee, Inc. establishing a strong presence. Other regions including the South East, Midlands, and North West also contribute to market growth, with companies like ABB Group, Panasonic Corporation, and Nest Labs, Inc. actively engaging in the development and deployment of innovative energy management solutions tailored to the UK market's unique needs and preferences.
Market Drivers
Rising Demand for Energy-Efficient Solutions
Consumers are becoming increasingly aware of the need to save energy and reduce their carbon footprint. For instance, a study shows that energy savings from Home Energy Management Systems (HEMS) products range from 2% to 22%. Home energy management systems (HEMS) can help achieve these goals by providing real-time data on energy consumption. This detailed information allows homeowners to identify areas where they can make savings, thereby enhancing energy efficiency. As energy costs continue to rise, the appeal of HEMS grows, offering a practical solution to manage and reduce household energy usage effectively.
Increasing Number of Connected Devices through the Internet of Things (IoT)
Increasing Number of Connected Devices through the Internet of Things (IoT) The proliferation of the Internet of Things (IoT) is significantly impacting the UK Home Energy Management System market. The IoT connects physical devices embedded with software, sensors, and other technologies, facilitating data exchange and seamless communication. This surge in connected devices, such as smart thermostats, appliances, and lighting systems, provides homeowners with a more comprehensive view of their energy consumption. For instance, smart buildings with built-in energy management systems already save 30% to 50% more energy than buildings without IoT, and that percentage is increasing each year. HEMS can integrate with these devices, enabling sophisticated control and optimization of energy use, thereby enhancing overall energy management in homes.
Government Policies to Increase Energy Efficiency and Tackle Climate Change
Government initiatives play a crucial role in driving the adoption of HEMS in the UK. The government has set ambitious targets for reducing greenhouse gas emissions, and HEMS can contribute significantly to achieving these goals. For instance, the Department for Business, Energy and Industrial Strategy (BEIS) offers financial incentives to encourage the uptake of smart meters, which can work synergistically with HEMS for better energy data analysis and management. These policies not only promote energy efficiency but also support the broader objective of tackling climate change. In December 2023, the UK government allocated GBP 6 billion to launch various funding schemes to reduce energy use in residential properties, support a move from gas boilers to electric heat pumps, and improve insulation
Growing Disposable Income
The rise in disposable incomes among consumers is another driver of the HEMS market. With more financial resources, consumers are increasingly willing to invest in technologies that enhance comfort and convenience. HEMS offers various benefits, including remote control of heating and lighting, and real-time energy consumption data. These features not only make homes more comfortable and efficient but also appeal to consumers who are ready to pay a premium for these advanced functionalities. Consequently, the growing disposable income levels bolster the market for home energy management systems.
Market Trends
Focus on Advanced Analytics, AI, and Non-Intrusive Load Monitoring
The UK Home Energy Management System (HEMS) market is experiencing a significant shift towards advanced analytics and artificial intelligence (AI). For instance, the adoption of AI in HEMS has grown by 25% in the past year alone. HEMS are evolving beyond simple data visualization, incorporating AI and machine learning algorithms to analyze energy usage patterns and predict future consumption. This technological advancement enables systems to provide more targeted recommendations for saving energy and optimizing usage based on individual household habits. For example, AI-driven insights have led to an average energy cost reduction of 15% for users. Additionally, the demand for non-intrusive load monitoring (NILM) technology is rising. NILM disaggregates a home’s total energy consumption into individual appliance-level data, providing a granular view of energy use. This detailed breakdown empowers users to pinpoint exactly where energy is being consumed, facilitating more focused conservation efforts. By identifying specific appliances that are energy hogs, homeowners can take targeted actions to improve efficiency. For instance, after implementing NILM, users have reported an average efficiency improvement of 20% in their most energy-consuming appliances.
Integration with Smart Home Devices, Cloud Solutions, and Cybersecurity Enhancements
Integration with smart home devices is a prominent trend in the HEMS market. Modern HEMS are designed to seamlessly connect with other smart home devices, such as thermostats, appliances, and lighting systems. This integration creates a holistic energy management ecosystem, enabling automated adjustments based on real-time data and user preferences. For example, a smart thermostat can automatically adjust heating and cooling settings based on occupancy patterns and weather forecasts, optimizing energy use without manual intervention. This interconnected approach enhances convenience and efficiency, making HEMS an integral part of the smart home landscape. In fact, homes with integrated HEMS have seen an average energy usage decrease of 10%. The growth in cloud-based solutions is another notable trend. Cloud-based HEMS offer several advantages, including easier data storage, accessibility from anywhere, and potential for improved functionality through remote updates. Consumers benefit from the convenience of accessing their energy management system via the internet, allowing them to monitor and control their energy use from any location. Furthermore, cloud-based systems can receive software updates and new features remotely, ensuring that users always have access to the latest advancements in energy management technology. For instance, cloud-based HEMS have experienced a 30% increase in user engagement due to their ease of use and remote capabilities.
Market Challenges Analysis
High Upfront Costs and Limited Installer Base
One of the significant challenges facing the UK Home Energy Management System (HEMS) market is the high upfront costs associated with installation. Implementing a HEMS often requires the purchase of various hardware components such as smart meters, sensors, and control panels. These initial investments can be substantial, posing a barrier to adoption for many consumers. In addition to hardware costs, there may also be ongoing subscription fees for cloud-based services and advanced data analysis features. While HEMS can lead to substantial savings on energy bills over time, the initial financial outlay can deter potential users, especially those who are cost-conscious or have limited disposable income. Compounding this issue is the limited installer base for HEMS in certain regions. The availability of qualified professionals to install and configure these systems properly can vary, making it difficult for some consumers to access reliable installation services. This scarcity can lead to longer waiting times for installations and potentially higher costs due to increased demand for skilled technicians. Without a sufficient number of trained installers, the expansion of the HEMS market may be hampered, as consumers may be unwilling or unable to undertake the installation process themselves.
Lack of Consumer Awareness, Data Privacy Concerns, and Interoperability Issues
Another challenge is the lack of consumer awareness about HEMS and their benefits. Many homeowners are not familiar with how these systems work or the potential savings they can provide. This lack of knowledge can result in reluctance to invest in HEMS, despite their long-term advantages. To overcome this barrier, there is a need for increased education and targeted marketing efforts to raise awareness about the capabilities and benefits of HEMS. Clear, informative campaigns can help consumers understand how HEMS can improve energy efficiency, reduce costs, and contribute to environmental sustainability. Data privacy concerns also pose a significant hurdle to the adoption of HEMS. These systems collect detailed data on energy consumption patterns, which can make some consumers wary about potential misuse or unauthorized access to their personal information. Addressing these concerns requires the implementation of robust data protection measures and transparent communication about how data is used and secured. Building consumer trust through stringent privacy safeguards is crucial for encouraging the widespread adoption of HEMS.
Market Segmentation Analysis:
By Components:
The UK Home Energy Management System (HEMS) market is segmented into hardware, software, and services. The hardware segment includes essential components like smart meters, sensors, and control panels, which are crucial for monitoring and managing energy consumption. Hardware forms the backbone of HEMS, enabling the collection of real-time data. The software segment encompasses platforms and applications that analyze energy usage patterns, provide insights, and facilitate user interaction with the system. These software solutions often leverage artificial intelligence and machine learning to offer predictive analytics and optimization recommendations. Services include installation, maintenance, and support, ensuring the smooth operation of HEMS. The integration of these components creates a comprehensive energy management ecosystem, allowing homeowners to efficiently monitor, control, and optimize their energy usage.
By Deployment Type:
Based on deployment type, the UK HEMS market is categorized into Wi-Fi-based systems, Power Line Communication (PLC), and Bluetooth-based systems. Wi-Fi-based systems are prevalent due to their ease of installation and widespread availability of Wi-Fi networks in homes. They offer reliable connectivity and seamless integration with other smart home devices, providing real-time data access and control. Power Line Communication (PLC) systems utilize existing electrical wiring to transmit data, offering a robust and reliable alternative, especially in areas with limited Wi-Fi coverage. Bluetooth-based systems, while less common, provide low-energy communication options, ideal for smaller setups and energy-conscious consumers. Each deployment type offers unique advantages, catering to different consumer needs and preferences, thereby enhancing the flexibility and accessibility of HEMS in the UK market.
Segments:
Based on Components
- Hardware
- Software
- Services
Based on Deployment Type
- Wi-Fi-based Systems
- Power Line Communication (PLC)
- Bluetooth-based Systems
Based on Functionality
- Energy Monitoring and Analysis
- Demand Response
- Appliance Control
- Renewable Energy Integration
Based on End-User
- Residential Homes
- Multi-Family Homes
Based on Deployment Type
- On-Premises Systems
- Cloud-Based Systems
Based on the Geography:
- England
- Scotland
- Wales
- Northern Ireland
- Other regions
Regional Analysis
In England, which accounts for approximately 45% of the UK HEMS market share, there is a strong emphasis on energy efficiency and sustainability. Major cities like London, Manchester, and Birmingham have witnessed a significant adoption of HEMS solutions, driven by high energy costs and the need to reduce carbon footprints. The government's initiatives, such as the Green Deal and the Energy Company Obligation (ECO), have further boosted the demand for HEMS in this region.
Scotland holds a market share of around 20% in the UK HEMS market. The Scottish Government's ambitious targets for reducing greenhouse gas emissions and promoting renewable energy sources have led to increased awareness and adoption of HEMS solutions among households. Additionally, the presence of prominent renewable energy projects, such as wind farms, has contributed to the growth of the HEMS market in this region.
Key Player Analysis
- General Electric Company
- Eaton Corporation
- ABB Group
- Com
- Honeywell International Inc.
- Vivint, Inc.
- Comcast Corporation
- Panasonic Corporation
- EnergyHub, Inc.
- Ecobee, Inc.
- Nest Labs, Inc.
Competitive Analysis
In the competitive landscape of the UK Home Energy Management System (HEMS) market, several leading players vie for dominance, each with distinct strengths and strategies. General Electric Company stands out for its comprehensive product portfolio and global presence, offering advanced HEMS solutions backed by cutting-edge technology and robust infrastructure. Eaton Corporation leverages its expertise in power management and electrical systems to deliver innovative HEMS solutions tailored to both residential and commercial sectors, emphasizing reliability and scalability. ABB Group brings its reputation for excellence in automation and energy efficiency to the HEMS market, providing integrated solutions that optimize energy consumption and enhance sustainability. Alarm.Com is recognized for its user-friendly platforms and intuitive interfaces, appealing to tech-savvy consumers seeking seamless integration with smart home ecosystems. Amidst these formidable competitors, differentiation lies in product innovation, customer-centric approaches, and strategic partnerships, shaping the dynamic landscape of the UK HEMS market.
Recent Developments
In August 22, 2023, Honeywell International, Inc. announced the launch of its Airfield Ground Lighting (AGL) manufacturing facility in Gurugram, India.
In August 28, 2023, Vivint, Inc. announced its partnership with SOLD.com to provide exclusive smart home offers.
In May 2023, Germany and Austria saw the introduction of Enphase Energy’s new home energy management system. In order to facilitate the integration of specific electric vehicle (EV) chargers and heat pumps from third parties into its solar and battery systems, it launched the IQTM Energy Router family of devices. While the IQ Energy Router+ is compatible with both EV chargers and heat pumps, the IQ Energy Router includes EV chargers as well.
In January 2023, A home energy management system combining solar power, appliances, storage, and electric vehicle charging was introduced by Schneider Electric. The consumer energy management system (EMS) that unifies all home appliances and energy endpoints into a single interface that a single smartphone app can access is called the Schneider Home platform.
Market Concentration & Characteristics
The UK Home Energy Management System (HEMS) market exhibits characteristics of moderate to high market concentration, with several prominent players dominating the landscape. These key players, including General Electric Company, Eaton Corporation, ABB Group, and Alarm.Com, wield significant influence due to their extensive product offerings, technological expertise, and established market presence. Despite the presence of smaller competitors and new entrants, these leading companies benefit from economies of scale, brand recognition, and established distribution channels, consolidating their market positions. Market concentration is further influenced by factors such as regulatory requirements, technological advancements, and consumer preferences. Additionally, the market is characterized by continuous innovation, with players striving to differentiate themselves through product enhancements, strategic alliances, and focus on customer experience. As the demand for energy-efficient solutions continues to grow, market concentration is expected to persist, with leading players driving industry trends and shaping the trajectory of the UK HEMS market.
Report Coverage
The research report offers an in-depth analysis based on Components, Deployment Type, Functionality, End-User, Deployment Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued Growth: The UK Home Energy Management System market is poised for sustained expansion driven by increasing consumer awareness and government initiatives promoting energy efficiency.
- Technological Advancements: Future developments in IoT, AI, and data analytics will enhance the capabilities of HEMS, enabling more precise energy management and optimization.
- Integration with Smart Grids: HEMS will play a crucial role in integrating with smart grids, facilitating demand response programs and grid stability management.
- Focus on Sustainability: With growing environmental concerns, there will be heightened emphasis on HEMS as a tool for reducing carbon footprints and promoting sustainable energy practices.
- Enhanced User Experience: Manufacturers will prioritize user-friendly interfaces and seamless integration with other smart home devices to enhance the user experience.
- Expansion of Services: Companies will offer comprehensive service packages including installation, maintenance, and customer support to meet evolving consumer needs.
- Regulatory Support: Favorable government policies and incentives will further drive market growth and encourage wider adoption of HEMS among households and businesses.
- Personalized Solutions: HEMS providers will offer personalized solutions tailored to individual household needs, leveraging data analytics and AI-driven insights.
- Market Consolidation: Larger players may engage in mergers and acquisitions to strengthen their market position and expand their product portfolios.
- Increased Focus on Cybersecurity: With the proliferation of connected devices, cybersecurity measures will become increasingly important to protect consumer data and ensure the integrity of HEMS operations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the UK Home Energy Management System Market?
What factors are driving the growth of the UK Home Energy Management System Market?
What are the key segments within the UK Home Energy Management System Market?
What are some challenges faced by the UK Home Energy Management System Market?
Who are the major players in the UK Home Energy Management System Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Home Energy Management System Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Home Energy Management System Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 189.20 million → forecast year: USD 582.03 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Home Energy Management System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Home Energy Management System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Home Energy Management System Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Home Energy Management System Market Drivers
- 3.3 UK Home Energy Management System Market Restraints & Challenges
- 3.4 UK Home Energy Management System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Home Energy Management System Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Home Energy Management System Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Home Energy Management System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Home Energy Management System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Home Energy Management System Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Home Energy Management System market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Home Energy Management System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Home Energy Management System Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Home Energy Management System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Home Energy Management System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Home Energy Management System Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Home Energy Management System Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Home Energy Management System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Home Energy Management System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Home Energy Management System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Home Energy Management System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Home Energy Management System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Home Energy Management System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Home Energy Management System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
