
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
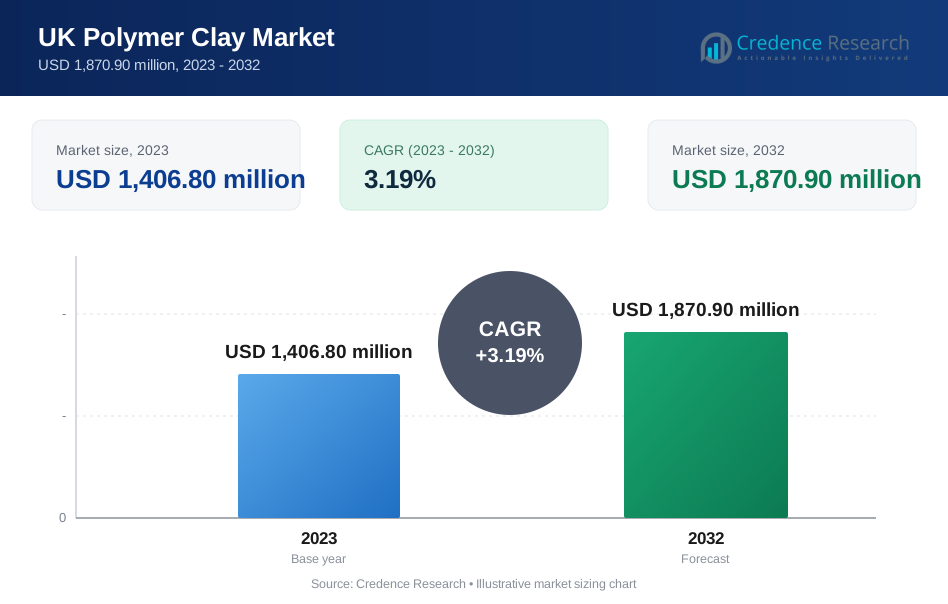
| UK Polymer Clay Market Size 2023 | USD 1,406.80 million |
| UK Polymer Clay Market, CAGR | 3.19% |
| UK Polymer Clay Market Size 2032 | USD 1,870.90 million |
Market Overview
The UK Polymer Clay Market is projected to grow from USD 1,406.80 million in 2023 to an estimated USD 1,870.90 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.19% from 2024 to 2032. This significant growth is driven by the increasing adoption of polymer clay in various applications such as arts and crafts, jewelry making, and educational purposes. The market's expansion is also attributed to the rising popularity of DIY crafts and the growing trend of handmade and personalized products. The forecast period will likely witness sustained demand due to the material's versatility and ease of use, appealing to both hobbyists and professional artists.
Several key drivers and trends are influencing the UK Polymer Clay Market's growth. One major driver is the increasing consumer interest in creative and recreational activities, which has surged, particularly during the COVID-19 pandemic, as more individuals sought home-based hobbies. Additionally, the rise of social media platforms showcasing polymer clay creations has boosted market visibility and consumer engagement. Trends such as the eco-friendly movement have also pushed manufacturers to develop non-toxic, environmentally friendly polymer clay options, aligning with the growing consumer demand for sustainable products. These factors collectively contribute to the market's positive growth trajectory.
Geographically, the UK Polymer Clay Market is distributed across various regions, with significant contributions from urban areas where arts and crafts culture is more prominent. London, in particular, stands out as a major hub due to its vibrant art scene and numerous craft stores. Other regions such as Manchester, Birmingham, and Edinburgh also play crucial roles in the market's expansion. Key players in the market include prominent brands like Sculpey, Fimo, and Kato Polyclay, which dominate due to their extensive product ranges and strong distribution networks. These companies continuously innovate to meet the evolving demands of consumers, thereby maintaining their competitive edge in the market.
Market Drivers
Rising Popularity of DIY and Craft Activities
One of the most significant drivers of the UK Polymer Clay Market is the burgeoning popularity of do-it-yourself (DIY) and craft activities. Over the past decade, there has been a noticeable shift in consumer behavior, with more individuals engaging in creative hobbies as a form of relaxation, self-expression, and personal fulfillment. The rise of social media platforms like Instagram, Pinterest, and YouTube has further amplified this trend. These platforms serve as inspiration hubs, showcasing a plethora of polymer clay projects and tutorials that attract both beginners and seasoned crafters. The COVID-19 pandemic accelerated this trend, as lockdowns and social distancing measures prompted people to seek indoor activities that could be done from home. Polymer clay emerged as a preferred medium due to its versatility, ease of use, and the minimal investment required to get started. As a result, the demand for polymer clay and related supplies surged, contributing to market growth. This increased interest in DIY activities is expected to persist, sustaining the market's expansion in the coming years.
Educational Applications and Benefits
Polymer clay has found a substantial niche within educational settings, serving as a valuable tool for art education and therapy. Schools and educational institutions increasingly incorporate polymer clay into their curricula to enhance students' fine motor skills, creativity, and cognitive development. The tactile nature of polymer clay allows students to explore different textures and shapes, fostering hands-on learning and artistic expression. Moreover, polymer clay is widely used in therapeutic settings to aid in the development of motor skills and provide a calming, stress-relieving activity. Occupational therapists and counselors often utilize polymer clay to help patients improve dexterity, hand-eye coordination, and concentration. The growing recognition of these educational and therapeutic benefits is driving the demand for polymer clay in the UK, contributing to the market's robust growth.
Innovation and Product Diversification
Continuous innovation and product diversification by key market players significantly drive the UK Polymer Clay Market. Leading brands such as Sculpey, Fimo, and Kato Polyclay are at the forefront of developing new polymer clay formulations and introducing a wide variety of colors, finishes, and special effects. These innovations cater to the evolving preferences and creative needs of consumers, from hobbyists to professional artists. For instance, manufacturers have developed polymer clays with unique properties such as glow-in-the-dark, metallic, and translucent finishes. These specialized clays enable users to create more intricate and visually appealing projects, thereby enhancing the overall crafting experience. Additionally, the introduction of eco-friendly and non-toxic polymer clay options aligns with the increasing consumer demand for sustainable products. This continuous stream of new and improved products keeps the market dynamic and attracts a broader customer base.
Robust Distribution Channels and Online Sales
The development of robust distribution channels and the growth of online sales have played a crucial role in driving the UK Polymer Clay Market. Established distribution networks ensure that polymer clay products are readily available in various retail formats, including specialty craft stores, large retail chains, and online platforms. The convenience of purchasing polymer clay online, coupled with the availability of a wide range of products, has made it easier for consumers to access these materials. Online sales have seen substantial growth, particularly during and after the pandemic, as more consumers turned to e-commerce for their shopping needs. Major e-commerce platforms like Amazon, eBay, and dedicated craft websites offer extensive selections of polymer clay products, often accompanied by customer reviews and detailed product descriptions. This accessibility and convenience have significantly boosted market reach and consumer engagement.
Market Trends
Increased Popularity of Polymer Clay Jewelry
The trend of handmade jewelry has significantly boosted the use of polymer clay. Artisans and hobbyists alike are increasingly using polymer clay to create unique, customizable jewelry pieces. This trend is driven by the consumer preference for personalized and handcrafted items, which offer a distinctive appeal compared to mass-produced products. Social media platforms showcasing intricate polymer clay jewelry designs have further fueled this trend, attracting a broad audience interested in crafting their accessories.
Sustainability and Eco-Friendly Products
Sustainability is a major trend across various markets, including polymer clay. Consumers are becoming more environmentally conscious, seeking products that align with their values. In response, manufacturers are developing eco-friendly and non-toxic polymer clay options. These products cater to the demand for sustainable crafting materials, reducing the environmental impact of the production and use of polymer clay. This trend is expected to grow as environmental awareness continues to rise.
Growth of Online Communities and Tutorials
The expansion of online communities and the availability of tutorials have greatly influenced the polymer clay market. Platforms such as YouTube, Instagram, and Pinterest host numerous tutorials and user-generated content, providing inspiration and guidance for both beginners and experienced crafters. These online resources have democratized access to crafting knowledge, making it easier for individuals to start and advance their polymer clay projects. The sense of community and shared learning fosters greater engagement and drives market growth.
Diversification of Polymer Clay Products
Manufacturers are continually innovating to diversify their product offerings. This includes the introduction of polymer clays with special properties, such as glow-in-the-dark, metallic, and translucent finishes. Additionally, there are now polymer clays designed for specific applications, such as sculpting, modeling, and jewelry making. This product diversification caters to a wide range of creative needs and preferences, enhancing the overall appeal of polymer clay to different segments of the market.
Integration with Mixed Media Art
Polymer clay is increasingly being used in mixed media art projects, where it is combined with other materials like resin, metal, and fabrics. This trend allows artists to explore new creative possibilities and create more complex and textured artworks. The versatility of polymer clay makes it an ideal medium for mixed media, supporting its growing popularity among artists looking to expand their artistic expression.
Educational and Therapeutic Uses
The use of polymer clay in educational and therapeutic settings continues to grow. Schools incorporate polymer clay into art education programs to develop students’ fine motor skills and creativity. In therapeutic contexts, polymer clay is used to help individuals improve dexterity, reduce stress, and facilitate expressive therapy. This trend highlights the broader benefits of polymer clay beyond traditional crafting, contributing to its sustained demand.
Customization and Personalization
The trend towards customization and personalization is prominent in the polymer clay market. Consumers increasingly seek products that reflect their personal style and preferences. Polymer clay's malleability and wide range of colors and finishes make it an ideal medium for creating personalized items, from home decor to gifts. This desire for unique, tailor-made products drives the continuous growth and innovation within the market.
Market Restraints and Challenges
Environmental Concerns and Regulatory Compliance
One of the significant challenges facing the UK Polymer Clay Market is the increasing scrutiny over environmental sustainability and regulatory compliance. Polymer clay, typically made from polyvinyl chloride (PVC) and plasticizers, can raise environmental concerns due to its non-biodegradable nature and potential chemical emissions during production and use. As consumers become more environmentally conscious, the demand for eco-friendly alternatives grows. However, developing and producing such sustainable polymer clays can be costly and technically challenging, posing a restraint for manufacturers. Additionally, stringent regulations related to chemical safety and environmental impact require continuous adaptation and compliance, adding to operational costs and complexities.
Competition from Alternative Materials
The polymer clay market faces intense competition from alternative crafting materials such as air-dry clay, epoxy resin, and traditional ceramics. These materials often offer distinct advantages that attract different segments of the crafting community. For instance, air-dry clay does not require baking, making it more convenient for some users, while epoxy resin offers a unique finish and durability. This competition can limit the market share and growth potential of polymer clay, as consumers might opt for alternatives that better meet their specific needs or preferences.
Market Saturation and Limited Consumer Awareness
While polymer clay is popular among certain demographics, there is still a considerable portion of the potential market that remains untapped due to limited consumer awareness. Market saturation in regions with high crafting activity can also pose a challenge, as the growth potential in these areas diminishes over time. Expanding market reach to new demographics and regions requires substantial marketing efforts and resources. Additionally, overcoming the perception of polymer clay as a niche product for hobbyists rather than a versatile material for broader applications remains a significant challenge.
Economic Factors and Disposable Income
The demand for polymer clay is influenced by broader economic conditions and consumer disposable income. During economic downturns or periods of financial uncertainty, consumers are likely to cut back on non-essential expenditures, including hobbies and crafts. This economic sensitivity can lead to fluctuations in market demand, impacting sales and profitability. Manufacturers and retailers need to adopt strategies to manage these fluctuations, such as offering budget-friendly product lines or promoting the value and longevity of polymer clay projects.
Market Segmentation Analysis
By Product Form
Solid polymer clay is the most widely used and recognized form in the market, favored by hobbyists and professionals for its versatility, ease of use, and wide range of colors and finishes. It is primarily used in crafting, jewelry making, and art projects due to its ability to be molded, shaped, and baked into durable and intricate designs. In contrast, liquid polymer clay, while less common, serves specialized applications such as coatings, adhesives, or finishing agents in various projects. Its unique properties, including the creation of detailed surface effects, transparent layers, and strong bonds, are gaining traction among artists looking to enhance their creations with different textures and effects.
By Application
Jewelry making is a primary application driving demand for polymer clay in the UK, thanks to its lightweight, vibrant colors, and moldability, making it ideal for custom pieces and benefiting from the trend of handmade, personalized accessories popular among both hobbyists and professionals. Additionally, polymer clay's safety, non-toxic properties, and ease of shaping make it a favored material for manufacturing toys and novelty items, with growing demand for unique, custom-designed toys and collectible items. In arts and sculpture making, polymer clay is valued for its adaptability and ability to capture fine details, used by artists to create detailed sculptures, art pieces, and decorative items. The crockery and ceramic products segment also benefits from polymer clay's versatility, as it is used to create unique, handcrafted kitchenware and home decor items, appreciated for its durability and aesthetic appeal. Furthermore, the "others" category encompasses applications like educational tools, prototypes, and hobby projects, highlighting polymer clay's flexibility and ease of use in diverse creative endeavors.
By End Use
The UK Polymer Clay Market is segmented into residential, commercial, and industrial end-use categories, each with distinct applications. The residential segment, the largest, is driven by widespread home-based crafting activities, where hobbyists and DIY enthusiasts use polymer clay for personal projects, home decor, and handmade gifts. In the commercial segment, businesses involved in crafting, jewelry making, and toy manufacturing utilize polymer clay for its cost-effectiveness, ease of customization, and suitability for small-scale production runs. The industrial segment leverages polymer clay for prototyping, model making, and industrial design processes, appreciating its ability to simulate various materials and create detailed models.
Segments
Based on Product Form
- Solid Form
- Liquid Form
Based on Application
- Jewelry Making
- Manufacturing of Toys and Novelty Items
- Arts and Sculpture Making
- Crockery and Ceramic Products
- Others
Based on End Use
- Residential
- Commercial
- Industrial
Regional Analysis
London and the South East (35%)
London and the South East dominate the UK Polymer Clay Market, holding approximately 35% of the market share. This region's prominence is attributed to its vibrant arts and crafts culture, supported by numerous craft stores, art schools, and workshops. London, as the cultural and economic hub of the UK, attracts a diverse population with a strong inclination towards creative pursuits. The high disposable income levels and the presence of a thriving market for handmade and bespoke items further bolster demand for polymer clay. Additionally, the region hosts various craft fairs and art exhibitions, fostering a robust community of artists and hobbyists who regularly use polymer clay.
Scotland (15%)
Scotland represents 15% of the market share, with major contributions from cities like Edinburgh and Glasgow. The Scottish market is driven by a strong tradition of craftsmanship and a growing interest in arts and culture. Scotland's scenic landscapes and cultural heritage inspire many artists and crafters, leading to increased use of polymer clay in creating art and decorative items. The region's educational institutions and art organizations also promote the use of polymer clay, supporting market expansion.
Key players
- Polyform Products Company (Sculpey)
- Cernit (Darwi)
- Viva Decor GmbH
- Eberhard Faber GmbH
- Pebeo
- Van Aken International
- Staedtler Mars
- Polyform Products
Competitive Analysis
The UK Polymer Clay Market is highly competitive, with several key players vying for market share through innovation, quality, and brand recognition. Polyform Products Company (Sculpey) and Staedtler Mars are leading the market, known for their extensive product ranges and strong distribution networks. Cernit (Darwi) and Viva Decor GmbH are recognized for their high-quality clays and specialized products, appealing to professional artists and hobbyists alike. Eberhard Faber GmbH and Van Aken International leverage their longstanding reputations in the art supplies market to attract a loyal customer base. Pebeo differentiates itself through its unique product formulations and vibrant color options. Each company focuses on continuous innovation and customer engagement to maintain their competitive edge. The market's growth is driven by these companies' efforts to meet the evolving demands of consumers through product diversification and enhanced accessibility.
Recent Developments
In May 2019, Levine Leichtman introduced its latest range of polymer clay products, featuring Sculpey III, Premo, and a solid clay conditioner. Each product in this line comes in a distinctive color palette, designed to cater to diverse creative needs and preferences. Sculpey III offers versatility for various crafting projects, Premo is known for its durability and professional quality, and the solid clay conditioner enhances clay workability. This launch underscores Levine Leichtman's commitment to innovation and meeting the evolving demands of the polymer clay market.
To meet the growing customer demand, German manufacturer Staedtler Mars GmbH & Co. KG expanded its FIMO line in September 2019 by introducing three new liquid colors: black, silver, and gold. These additions provide artists and crafters with more options for creating detailed and vibrant polymer clay projects. The new liquid colors enhance the FIMO range, allowing for greater creative expression and versatility. Staedtler Mars continues to innovate, ensuring its products meet the highest standards of quality and performance in the polymer clay market.
Market Concentration and Characteristics
The UK Polymer Clay Market is characterized by a moderate to high market concentration, with a few key players dominating the landscape. Companies such as Polyform Products (Sculpey), Staedtler Mars (FIMO), and Cernit (Darwi) hold significant market shares due to their extensive product ranges, strong brand recognition, and robust distribution networks. The market is marked by continuous innovation, with leading manufacturers introducing new formulations and colors to meet evolving consumer preferences. Additionally, the market benefits from a vibrant DIY culture and growing interest in arts and crafts, which drive demand for high-quality polymer clay products.
Report Coverage
The research report offers an in-depth analysis based on Product Form, Application and End Use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UK Polymer Clay Market is expected to maintain steady growth due to increasing consumer interest in arts and crafts, with a projected CAGR of 3.19% from 2024 to 2032.
- Manufacturers will continue to innovate, introducing new formulations and special effect clays to cater to evolving creative needs and preferences of both hobbyists and professional artists.
- The market will see a significant increase in eco-friendly and non-toxic polymer clay products, aligning with the rising consumer demand for sustainable crafting materials.
- Online sales channels will expand further, driven by the convenience of e-commerce and the influence of social media platforms promoting polymer clay projects and tutorials.
- Increased adoption of polymer clay in educational settings for art education and therapeutic purposes will bolster market growth, highlighting its versatility and benefits in skill development.
- The trend of integrating polymer clay with mixed media art will gain momentum, allowing artists to explore new creative avenues and enhance the complexity of their projects.
- The demand for customized and personalized polymer clay items will rise, driven by consumer preferences for unique, tailor-made products in jewelry, home decor, and gifts.
- Manufacturers will focus on penetrating untapped regions within the UK, expanding their market presence beyond major cities to reach new customer demographics and increase market share.
- Advancements in production technology will improve the quality and variety of polymer clay products, making them more accessible and appealing to a broader range of consumers.
- Strategic collaborations and partnerships among key players, educational institutions, and art organizations will drive innovation, market expansion, and enhanced product offerings, ensuring sustained market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Popularity of DIY and Craft Activities
The surge in home-based hobbies and creative pursuits, amplified by social media and the COVID-19 pandemic, has significantly increased demand for polymer clay among hobbyists and crafters in the UK.
Educational and Therapeutic Applications
Polymer clay is increasingly used in schools and therapy settings to develop fine motor skills, creativity, and stress relief, expanding its adoption beyond traditional crafting into educational and healthcare sectors.
Innovation and Product Diversification
Key manufacturers are continuously introducing new formulations, colors, and special effect clays, including eco-friendly and non-toxic options, which attract a broader consumer base and meet evolving creative needs.
Growth of Online Sales and Distribution Channels
The expansion of e-commerce platforms and robust retail networks has made polymer clay products more accessible, enabling consumers across the UK to easily purchase a wide variety of options and driving overall market growth.
Customization and Personalization Trends
The consumer desire for unique, handmade, and personalized products - especially in jewelry and home decor - has fueled demand for polymer clay, which is ideally suited for bespoke and creative projects.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the UK Polymer Clay Market?
What are the main drivers of growth in the UK Polymer Clay Market?
Which regions in the UK have the highest market share for polymer clay?
Who are the key players in the UK Polymer Clay Market?
How has the demand for polymer clay been influenced by online sales?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.2.3 Industrial
- 1.3 By Application
- 1.3.1 Jewelry Making
- 1.3.2 Manufacturing of Toys and Novelty Items
- 1.3.3 Arts and Sculpture Making
- 1.3.4 Crockery and Ceramic Products
- 1.3.5 Others
- 1.4 By Region (UK)
- 1.4.1 London and the South East
- 1.4.2 Scotland
- 1.4.3 Other UK Regions
- 1.5 By Product Form
- 1.5.1 Solid Form
- 1.5.2 Liquid Form
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1,406.80 million → 2032: USD 1,870.90 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 UK Polymer Clay Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 UK Polymer Clay Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 UK Polymer Clay Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 UK Polymer Clay Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 UK Polymer Clay Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 UK Polymer Clay Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 UK Polymer Clay Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 UK Polymer Clay Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1,406.80 million → 2032: USD 1,870.90 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 UK Polymer Clay Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial
- 12.3.7.3 Industrial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Jewelry Making
- 12.4.7.2 Manufacturing of Toys and Novelty Items
- 12.4.7.3 Arts and Sculpture Making
- 12.4.7.4 Crockery and Ceramic Products
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Region (UK) - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 London and the South East
- 12.5.7.2 Scotland
- 12.5.7.3 Other UK Regions
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Form - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Solid Form
- 12.6.7.2 Liquid Form
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 UK Polymer Clay End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 UK Polymer Clay Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 UK Polymer Clay Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 UK Polymer Clay Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Polyform Products Company (Sculpey)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Staedtler Mars (FIMO)
- 18.4 Cernit (Darwi)
- 18.5 Viva Decor GmbH
- 18.6 Eberhard Faber GmbH
- 18.7 Pebeo
- 18.8 Van Aken International
- 18.9 Levine Leichtman
- 18.10 Faber-Castell
- 18.11 Premo
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

