
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
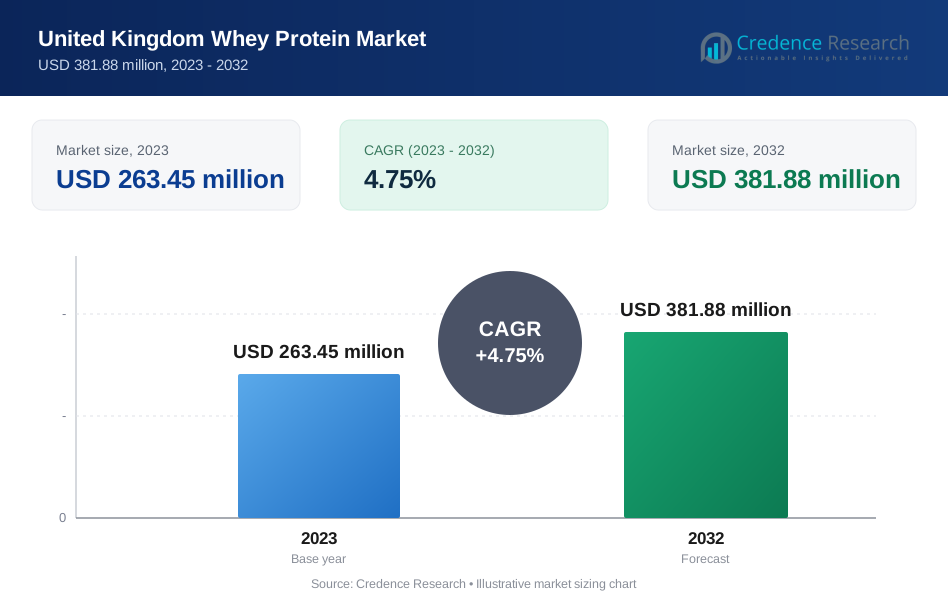
| United Kingdom Whey Protein Market Size 2023 | USD 263.45 Million |
| United Kingdom Whey Protein Market, CAGR | 4.75% |
| United Kingdom Whey Protein Market Size 2032 | USD 381.88 Million |
Market Overview
The United Kingdom Whey Protein Market is projected to grow from USD 263.45 million in 2023 to an estimated USD 381.88 million by 2032, with a compound annual growth rate (CAGR) of 4.75% from 2024 to 2032. This significant growth underscores the increasing demand for whey protein products, driven by rising awareness of health and fitness, coupled with the expanding consumer base seeking dietary supplements for various health benefits. The market's expansion is further fueled by the adoption of whey protein in numerous applications, including functional foods, sports nutrition, and clinical nutrition, providing a steady push to the market size over the forecast period.
Driving the market are key trends such as the escalating popularity of plant-based and animal protein hybrids, increased consumer expenditure on health and wellness products, and innovations in whey protein formulations. The shift towards more sustainable and transparent production processes also reflects growing consumer preferences for products that are ethically produced and environmentally friendly. Moreover, the integration of whey protein into mainstream food items and the increasing trend of home-based fitness regimes are expected to continue propelling the demand for whey protein products across the United Kingdom.
Geographically, the market is witnessing robust growth in major urban centers, where health-conscious populations are concentrated. London, Birmingham, and Manchester are leading in consumption due to their higher population density and greater awareness of health and fitness. Key players in the United Kingdom Whey Protein Market include Glanbia PLC, Arla Foods, and Wheyco GmbH. These companies are actively expanding their market presence by enhancing their production capacities, innovating product offerings, and engaging in strategic partnerships and acquisitions to better serve the diverse needs of their customers and strengthen their market positions.
Market Drivers
Increasing Health and Fitness Consciousness:
The rising awareness among consumers about health and wellness is a major driver of the whey protein market in the UK. As more individuals are focusing on fitness regimes and nutritional diets, the demand for protein supplements has surged. For instance, a survey conducted in 2023 revealed that approximately 70% of UK adults have started or intensified exercise routines since the start of the pandemic. Whey protein, known for its high-quality protein content, is favored for muscle repair, strength enhancement, and overall health improvements. This trend is supported by a growing number of fitness enthusiasts and athletes, but also by the general population becoming more proactive about their health. The expanding gym culture and the popularity of home workout routines, especially highlighted during the COVID-19 pandemic, have further cemented the integral role of whey protein in consumers’ daily lives.
Expanding Applications in Food and Beverage Industry:
Whey protein has found extensive applications beyond traditional sports nutrition, now being incorporated into a broader range of food products. Manufacturers are leveraging whey protein to enhance the nutritional profile of everyday food items such as bread, snacks, and beverages. For example, the sales of whey protein-enriched bread have seen an increase of 15% in the last year. This is aligned with the consumer demand for functional foods that support health without compromising on taste or convenience. Innovation in food technology has facilitated the development of whey protein-enriched products that cater to the busy lifestyles of consumers, thereby broadening the market base and increasing consumption rates.
Shift Towards Plant-based and Animal Protein Hybrids:
In response to the growing demand for sustainable and ethical food options, the market is seeing a rise in hybrid protein products that combine plant and animal sources, including whey protein. These products aim to balance nutritional value with environmental consciousness, appealing to a segment of consumers who are interested in reducing their carbon footprint but are not willing to completely forego animal proteins. The trend towards more environmentally friendly diets that still prioritize high protein intake is driving innovation and adoption of such hybrid products within the UK market.
Government Support and Regulatory Approvals:
The UK government’s initiatives to promote public health through better nutrition have positively impacted the whey protein market. Regulatory bodies have been supportive of fortifying foods with proteins as a strategy to improve national health metrics. Additionally, the approval of novel food sources and ingredients allows for the expansion of the whey protein market by ensuring consumer safety and product efficacy. This regulatory environment not only boosts consumer confidence in whey protein products but also encourages manufacturers to invest in new product development and marketing.
Market Trends
Increased Consumption Among Non-Athletes:
Traditionally associated with athletes and bodybuilders, whey protein is now gaining popularity among the general populace. For instance, a recent survey showed that 30% of working professionals and 20% of the elderly in the UK have started consuming whey protein to improve their health and dietary intake. This trend is expanding the customer base and opening new avenues for product diversification.
Rise in Demand for Organic and Grass-Fed Whey Protein:
Consumers are increasingly opting for organic and grass-fed whey protein products, perceiving them as healthier and more nutritious. This shift is due to a growing awareness of animal welfare and the environmental impact of dairy farming, prompting manufacturers to source whey from organically raised cows.
Innovations in Flavor and Format:
The UK market is experiencing a surge in innovative whey protein products with varied flavors and convenient consumption formats such as ready-to-drink shakes and single-serving packets. For example, the sales of ready-to-drink whey protein shakes have seen an increase of 25% in the last year. These innovations cater to the busy lifestyles of consumers who demand both convenience and taste without compromising on nutritional value.
Integration with Personalized Nutrition Plans:
Personalized nutrition is becoming a key trend, with consumers seeking tailored dietary supplements based on their specific health needs and fitness goals. Companies are leveraging data analytics and AI to offer customized whey protein formulations, enhancing customer satisfaction and loyalty.
Growth in E-commerce Sales:
The rise of online shopping has significantly impacted the whey protein market. E-commerce platforms provide easy access to a wide range of products, competitive pricing, and detailed product information, which helps in informed decision-making. This trend is particularly strengthened by the shift in consumer behavior due to the COVID-19 pandemic.
Sustainability Initiatives:
There is a growing trend toward sustainability in the whey protein market, with companies increasingly investing in sustainable production practices. This includes reducing carbon footprints, using eco-friendly packaging, and ensuring ethical sourcing. These practices not only appeal to environmentally conscious consumers but also align with global sustainability goals.
Collaborations and Partnerships:
Companies in the UK whey protein market are actively engaging in collaborations and partnerships with gyms, wellness centers, and sports clubs to widen their distribution networks and enhance brand visibility. These partnerships are vital for tapping into niche markets and catering directly to the health and fitness community.
Market Restraints and Challenges
High Cost of Production:
The production of whey protein involves complex and resource-intensive processes, including the extraction and purification of protein from whey, which can significantly drive up costs. These higher production costs are often passed onto consumers, making whey protein products less accessible to a broader audience, particularly in economically sensitive times.
Market Saturation:
With numerous players entering the whey protein market, there has been an increase in product offerings. This saturation can lead to intense competition, which may pressure companies to reduce prices or increase marketing expenditures to maintain their market share. Such conditions can strain profit margins and potentially stifle innovation as companies may focus more on price competition rather than product development.
Regulatory and Dietary Restrictions:
The whey protein market is subject to stringent regulations that govern food safety and labeling. Navigating these regulatory frameworks can be challenging for manufacturers, especially those new to the market or looking to innovate with new products. Additionally, dietary restrictions and the increasing prevalence of lactose intolerance or dairy sensitivities among consumers can limit the market for whey-based products, pushing demand towards non-dairy protein alternatives.
Consumer Perception and Misinformation:
Despite the benefits of whey protein, there exists skepticism and misinformation about its health implications. Some consumers believe that excessive protein intake, particularly from supplements like whey, might cause health issues such as kidney damage or bone loss. Addressing these misconceptions through education and transparent marketing is crucial but remains a challenge.
Environmental and Ethical Concerns:
The environmental impact of dairy farming, which includes high water usage and greenhouse gas emissions, is increasingly scrutinized by environmentally conscious consumers. Ethical concerns regarding animal welfare in dairy farming also influence consumer choices, especially among younger demographics. Companies must address these concerns by adopting more sustainable and ethical practices, which can involve additional costs and operational changes.
Impact of Alternative Proteins:
The rise of plant-based and alternative proteins poses a significant challenge to the whey protein market. As consumers become more health-conscious and environmentally aware, there is a noticeable shift towards plant-based diets, which can detract from the demand for animal-derived proteins like whey.
Market Segmentation Analysis
By Product Type
Whey Protein Concentrate (WPC), favored for its affordability and higher fat and lactose content, is ideal for general wellness and muscle building. Whey Protein Isolate (WPI), with its high protein and minimal fat and lactose, is popular among those with lactose intolerance and those seeking lean muscle growth. Whey Protein Hydrolysate (WPH), which is predigested and faster absorbing, is preferred for medical applications and by serious athletes for its rapid muscle recovery benefits.
By Application
The United Kingdom Whey Protein Market's application segment is led by sports nutrition, with athletes and bodybuilders utilizing whey protein for muscle recovery and performance enhancement. Dietary supplements also play a significant role, contributing to everyday health and dietary completeness. Additionally, whey protein is integrated into functional foods for added health benefits and is a key ingredient in infant formula due to its nutritional qualities that support infant growth. Furthermore, its use in bakery, confectionery, and beverages is expanding as manufacturers innovate with whey protein in new food and beverage categories.
By Price Range
The United Kingdom Whey Protein Market caters to various consumer segments through a tiered pricing strategy. The premium segment targets consumers willing to invest in high-quality, often organic or grass-fed whey protein. The mid-range segment appeals to the mainstream market by balancing quality and affordability, making it accessible to a broader audience. The economy segment attracts price-sensitive customers by offering basic whey protein options, ensuring that a wider demographic can benefit from protein supplements despite budget constraints.
By End-user
Athletes and bodybuilders are the primary consumers of whey protein, using it to support intense training regimens. Health-conscious consumers also increasingly incorporate whey protein into their diets for its overall health benefits. The elderly population uses whey protein to maintain muscle mass and improve general health, while children benefit from its inclusion in select nutritional products. Additionally, various other consumer groups seek whey protein for its specific health advantages.
By Distribution Channel
The distribution channels for whey protein in the United Kingdom are diverse and evolving. Online retail is growing rapidly due to its convenience and competitive pricing. Specialty stores offer specialized products with knowledgeable staff, while supermarkets and hypermarkets provide accessibility and variety. Convenience stores cater to on-the-go consumers, and drugstores and pharmacies are increasingly stocking whey protein products to align with health-focused offerings. This variety in distribution channels ensures that whey protein products are widely available to meet the needs of different consumer segments.
Segments
Based on Product Type
- Whey Protein Concentrate (WPC)
- Whey Protein Isolate (WPI)
- Whey Protein Hydrolysate (WPH)
Based on Application
- Sports Nutrition
- Dietary Supplements
- Functional Foods
- Infant Formula
- Bakirey & Confectionery, Beverages, Others
Based on Price Range
- Premium
- Mid-range
- Economy
Based on End-user
- Athletes & Bodybuilders
- Health-Conscious Consumers
- Elderly Population
- Children
Based on Distribution Channel
- Online Retail
- Specialty Stores
- Supermarkets/Hypermarkets
- Convenience Stores
- Drugstores/Pharmacies, Others
Regional Analysis
London (35% Market Share):
London holds the largest market share, primarily due to its high population density and the presence of a cosmopolitan consumer base with a strong focus on health and fitness. The region benefits from extensive distribution networks and the availability of specialty stores and gyms where whey protein products are prominently featured. Additionally, London's dynamic economic environment supports a higher purchasing power for premium and mid-range whey protein products.
Scotland and Wales (10% each):
Both regions exhibit strong market growth, supported by a rising awareness of nutritional supplements and an increasing number of health-centric food outlets. Scotland, with its robust gym culture in cities like Glasgow and Edinburgh, shows a keen interest in sports nutrition, while Wales sees a steady demand for dietary supplements among its aging population.
Northern Ireland (5%):
Although holding the smallest market share, Northern Ireland is rapidly catching up, with increasing health awareness and the integration of global health trends into local practices. The region's market is expanding through both traditional retail and a growing online presence, encouraging broader accessibility and consumer education about the benefits of whey protein.
Key players
- Glanbia PLC
- Arla Foods
- Fonterra Co-operative Group
- Myprotein
- Optimum Nutrition
- MuscleTech
- Bio-Synergy Ltd
- USN UK
- The Hut Group (THG)
- BULK POWDERS
Competitive Analysis
The United Kingdom Whey Protein Market is characterized by intense competition among well-established players and emerging entities. Key players like Glanbia PLC and Arla Foods dominate due to their extensive product portfolios and robust distribution networks. Innovation in product formulation and marketing strategies plays a pivotal role in maintaining market positions. Companies such as Myprotein and Optimum Nutrition focus on targeting niche markets with specialized products, enhancing their visibility and appeal. Additionally, the presence of local brands like Bio-Synergy Ltd and BULK POWDERS demonstrates the importance of tailored nutritional offerings and local consumer engagement. Competitive pricing, quality assurance, and brand loyalty are critical factors influencing consumer preferences in this competitive landscape.
Recent Developments
In February 2024, the UK-based sports nutrition company SCI-MX expanded its product range by introducing a new clear whey protein isolate. This addition underscores the brand's commitment to enhancing its high-protein offerings to meet the evolving needs of fitness enthusiasts and athletes. The clear whey protein isolate stands out for its clarity in solution, making it an appealing choice for consumers seeking a refreshing alternative to traditional, milky protein shakes. This innovative product aims to cater to a growing market segment that prioritizes both nutritional value and ease of consumption in their fitness supplements.
In February 2024, Unilever's Breyers brand, renowned for its ice cream, collaborated with Perfect Day, a provider of animal-free dairy proteins. They launched Breyers Lactose-Free Chocolate ice cream in the United States, utilizing Perfect Day’s innovative whey protein created through precision fermentation. This partnership highlights a significant step towards sustainable product development in the food industry. The new ice cream caters to lactose-intolerant consumers and those seeking environmentally friendly dairy alternatives, offering the same creamy texture and taste of traditional ice cream without the lactose.
In January 2024, Israeli startup Imagindairy made a significant advancement by acquiring industrial-scale precision fermentation production lines at a strategic location near Israel. This development paves the way for the launch of its animal-free whey protein products in the US market within the year. Imagindairy's move into large-scale production demonstrates its commitment to meeting the growing demand for sustainable and ethical alternatives to traditional dairy products. The company's innovative approach in using precision fermentation to produce whey protein aligns with global trends towards environmentally friendly and humane food production methods.
Market Concentration and Characteristics
The United Kingdom Whey Protein Market is moderately concentrated, characterized by the presence of a few major players alongside several smaller competitors. Leading companies like Glanbia PLC, Arla Foods, and Myprotein significantly influence market dynamics through extensive product lines, strong brand loyalty, and widespread distribution networks. These key players invest heavily in research and development to innovate new formulations and product enhancements that meet the evolving health and fitness preferences of consumers. Additionally, the market features a range of specialized products tailored to diverse consumer needs, from high-performance athletes to health-conscious individuals, further defining the competitive landscape. This concentration allows for stable pricing and quality assurance but also encourages continuous innovation and customer-focused strategies to maintain and grow market share.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Price Range, End-user and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The United Kingdom Whey Protein Market is expected to continue its growth trajectory, driven by increasing health consciousness and a growing fitness industry.
- Companies will likely expand whey protein applications beyond sports nutrition to include elder care and general wellness, catering to an aging population.
- Innovation in flavors and formats will persist, with clear protein drinks and plant-based hybrid proteins becoming more prevalent.
- Sustainability will become a key competitive factor, with companies investing in environmentally friendly production practices and sourcing.
- Customized whey protein products tailored to individual dietary needs and health goals will gain popularity, leveraging advancements in technology.
- The trend towards hybrid protein products will grow, appealing to consumers looking for balanced dietary options that also support environmental sustainability.
- Online sales channels will expand, driven by consumer preferences for convenience and a wider selection of products.
- Regulatory frameworks will tighten, focusing on product transparency and safety, compelling companies to adopt stricter quality control measures.
- Strategic partnerships with fitness centers and health clinics will enhance market penetration and consumer outreach.
- As demand for non-dairy alternatives rises, whey protein manufacturers may explore innovations that mimic the properties of whey without the dairy, catering to vegan and lactose-intolerant markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the United Kingdom Whey Protein Market?
What are the main drivers of the whey protein market in the UK?
Which regions in the UK show the highest consumption of whey protein?
How are sustainability trends impacting the whey protein market?
What types of whey protein products are most popular?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 United Kingdom Whey Protein Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 United Kingdom Whey Protein Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 263.45 million → 2032: USD 381.88 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 United Kingdom Whey Protein Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. United Kingdom Whey Protein Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 United Kingdom Whey Protein Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 United Kingdom Whey Protein Drivers
- 3.3 United Kingdom Whey Protein Restraints & Challenges
- 3.4 United Kingdom Whey Protein Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 United Kingdom Whey Protein Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 United Kingdom Whey Protein Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, United Kingdom Whey Protein category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 United Kingdom Whey Protein Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. United Kingdom Whey Protein Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2023)
- 5.1.2 Export Volume by Destination Country (2023) (Where Applicable)
- 5.1.3 Import Value by Source Country (2023)
- 5.1.4 Import Volume by Source Country (2023) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to United Kingdom Whey Protein in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 United Kingdom Whey Protein Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 United Kingdom Whey Protein Share Analysis – 2023
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 United Kingdom Whey Protein Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in United Kingdom Whey Protein (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in United Kingdom Whey Protein
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. United Kingdom Whey Protein – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. United Kingdom Whey Protein – Priority Domestic Market 1
Chapter 10. United Kingdom Whey Protein – Priority Domestic Market 2
Chapter 11. United Kingdom Whey Protein – Priority Domestic Market 3
Chapter 12. United Kingdom Whey Protein – Priority Domestic Market 4
Chapter 13. United Kingdom Whey Protein Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
