
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| United States Automotive Smart Keys Market Size 2023 | USD 3,644.40 million |
| United States Automotive Smart Keys Market, CAGR | 8.80% |
| United States Automotive Smart Keys Market Size 2032 | USD 7,788.21 million |
Market Overview
United States Automotive Smart Keys Market size was valued at USD 3,644.40 million in 2023 and is anticipated to reach USD 7,788.21 million by 2032, at a CAGR of 8.80% during the forecast period (2023-2032).
The United States automotive smart keys market is driven by the growing demand for advanced vehicle security systems and the rising adoption of connected car technologies. Consumers increasingly prefer keyless entry and push-start systems for their convenience and enhanced safety features. Automakers are integrating smart key systems as standard or premium offerings in mid-range and high-end vehicles, further accelerating market growth. Additionally, the surge in electric and hybrid vehicle production supports the adoption of smart key technology due to its compatibility with modern vehicle architectures. Trends such as biometric authentication, smartphone-enabled access, and the integration of IoT and AI are reshaping user experiences and boosting the appeal of smart keys. Moreover, regulatory emphasis on vehicle security standards is prompting manufacturers to adopt robust and innovative smart key solutions. These factors collectively contribute to the market’s strong growth trajectory, with technological innovation continuing to be a key differentiator among leading industry players.
The United States automotive smart keys market demonstrates strong geographical variation, with higher adoption rates in technologically progressive regions such as the Western and Southern states, where consumer demand for connected and secure mobility solutions is robust. Urban areas with a high concentration of electric and luxury vehicles tend to lead in the integration of advanced smart key technologies. Meanwhile, the Midwest remains a key manufacturing hub, supporting OEMs with production capabilities and R&D initiatives. The market is highly competitive, with key players including Huf Hülsbeck & Fürst GmbH & Co, Continental AG, ZF Friedrichshafen AG, HELLA GmbH & Co. KGaA, Hyundai Mobis, Denso Corporation, Valeo SA, and Robert Bosch GmbH. These companies are focusing on innovation, biometric security features, and smartphone-enabled systems to enhance user experience. Strategic collaborations between OEMs and technology firms continue to shape the competitive landscape, driving product development and regional market expansion across the country.
Market Insights
- The United States automotive smart keys market was valued at USD 3,644.40 million in 2023 and is projected to reach USD 7,788.21 million by 2032, growing at a CAGR of 8.80% from 2023 to 2032.
- The Global Automotive Smart Keys market was valued at USD 12,499.00 million in 2023 and is projected to reach USD 26,481.41 million by 2032, growing at a CAGR of 8.70% from 2023 to 2032.
- Growing demand for enhanced vehicle security and convenience is a major driver of market growth.
- Increasing adoption of electric and luxury vehicles is boosting the integration of smart key systems.
- Biometric authentication, mobile app-based access, and IoT-enabled smart keys are shaping market trends.
- Key players such as Continental AG, Denso Corporation, Hyundai Mobis, and Valeo SA are actively investing in R&D and product innovation.
- High costs of implementation and rising cybersecurity threats pose restraints to market expansion.
- Western and Southern U.S. regions lead in adoption due to higher tech integration and consumer demand, while the Midwest supports strong manufacturing and OEM presence.
Report Scope
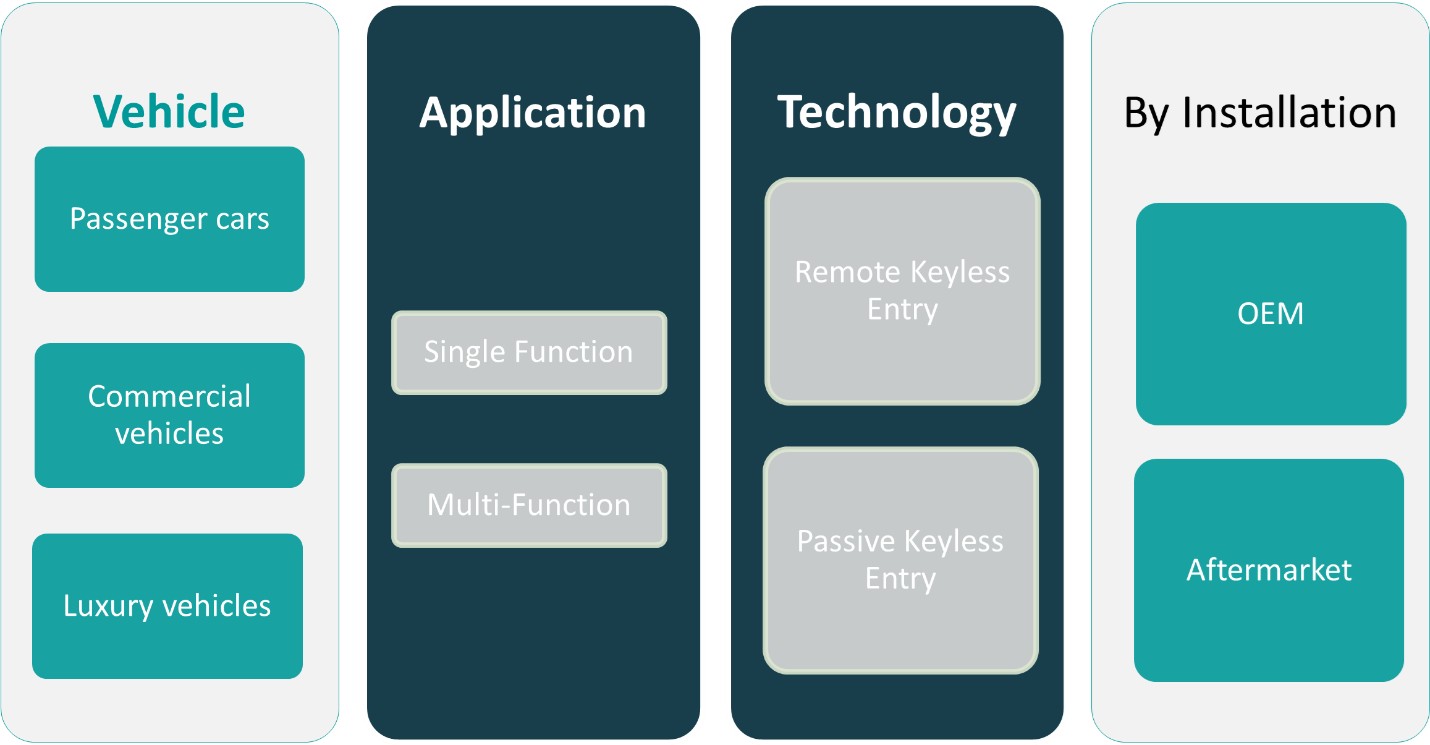
This report segments the United States Automotive Smart Keys Market as follows:
Market Drivers
Growing Demand for Enhanced Vehicle Security
One of the primary drivers of the United States automotive smart keys market is the increasing emphasis on vehicle security. For instance, a report by the National Highway Traffic Safety Administration (NHTSA) highlights the effectiveness of encrypted communication and rolling codes in reducing vehicle theft incidents. As incidents of vehicle theft and unauthorized access continue to rise, consumers are prioritizing advanced security features in their automotive purchases. Smart key systems provide enhanced protection by offering encrypted communication between the key fob and the vehicle, reducing the risk of theft through traditional lock-and-key methods. Features such as rolling codes, proximity detection, and biometric authentication are becoming standard in smart key offerings, ensuring only authorized users can access or start the vehicle. This demand for safer and more secure vehicle access systems significantly propels the growth of the smart keys market in the U.S.
Rising Consumer Preference for Convenience and Connectivity
Modern consumers increasingly seek convenience, seamless experiences, and technological integration in their vehicles. Smart keys, which enable keyless entry, push-button start, and remote access, align perfectly with these evolving preferences. In urban areas, where efficiency and time management are crucial, smart keys offer quick and effortless access to vehicles, eliminating the need to fumble for traditional keys. Furthermore, smartphone-compatible smart key systems that allow remote vehicle control through mobile apps are gaining popularity. These systems offer functionalities such as climate control activation, geofencing, and remote locking/unlocking, which enhance the overall user experience. As automotive technology evolves to match the digital lifestyles of consumers, the adoption of smart keys continues to rise accordingly.
Integration of Advanced Technologies in Automobiles
Technological advancements in automotive manufacturing and design are fueling the demand for smart key systems. For instance, a report by the International Energy Agency (IEA) highlights the role of smart keys in storing driver preferences such as seat positions and climate settings, which automatically adjust upon entry. Automakers are increasingly adopting Internet of Things (IoT), Artificial Intelligence (AI), and machine learning technologies in their vehicles to provide more intelligent and personalized driving experiences. Smart keys play a pivotal role in these ecosystems, acting as a gateway to many of the vehicle’s digital features. Additionally, electric and hybrid vehicle manufacturers favor smart key systems due to their compatibility with digital dashboards and smart charging systems. As vehicle architecture becomes more sophisticated, smart keys evolve as an integral component of the connected car experience.
Automotive Industry Growth and OEM Adoption
The continued growth of the U.S. automotive industry, particularly in the electric and luxury vehicle segments, has led to widespread adoption of smart key systems by Original Equipment Manufacturers (OEMs). Automakers are incorporating smart keys not only as a value-added feature but also as a standard offering in many new models to stay competitive. This trend is especially prominent among premium and mid-range vehicles, where consumers expect high levels of innovation and convenience. Additionally, OEMs are collaborating with technology providers to develop next-generation smart key solutions that support over-the-air (OTA) updates and enhanced user control. Government regulations supporting vehicle safety and security also encourage OEMs to integrate smart key technologies, further driving market expansion across the United States.
Market Trends
Shift Toward Keyless and Remote Access Solutions
One of the most prominent trends in the U.S. automotive smart keys market is the growing shift from traditional mechanical keys to keyless and remote access systems. For instance, a report by the National Highway Traffic Safety Administration (NHTSA) highlights the increasing adoption of proximity-based smart keys, which allow drivers to unlock and start their vehicles without removing the key fob from their pocket or bag. As car manufacturers compete to offer more intuitive and user-friendly experiences, keyless entry and push-button start have become standard features in many mid-range and premium models. This trend is expected to continue, driven by rising customer expectations for seamless vehicle access and operation.
Integration of Biometric and Mobile-Based Smart Key Technologies
The U.S. market is also witnessing a growing trend in the integration of biometric technologies and smartphone-enabled smart keys. Automakers and tech firms are investing in fingerprint, facial recognition, and voice authentication systems to enhance vehicle security and personalization. These biometric smart key systems not only provide an added layer of security but also support user-specific profiles for seat adjustments, climate control, and infotainment settings. In parallel, mobile-based smart keys that enable vehicle access through dedicated smartphone apps are gaining traction. These solutions are particularly attractive for shared mobility services and fleet operators, as they allow for easy and secure digital key sharing and remote vehicle management.
Growing Demand for Connected and Personalized Driving Experiences
As connected car technology continues to advance, smart keys are evolving to play a central role in enhancing personalized driving experiences. For instance, a report by the International Energy Agency (IEA) highlights the integration of smart keys into vehicle digital ecosystems, enabling functions such as remote engine start and geolocation tracking. Consumers now expect their vehicles to recognize and adapt to their preferences, and smart keys serve as the key enabler of this personalization. Automakers are leveraging data analytics and IoT connectivity to offer features that adjust vehicle settings automatically based on the user’s behavior and routines, making smart keys a vital component in the future of automotive innovation.
OEM Partnerships and Innovation-Driven Market Growth
Automotive manufacturers are forming strategic partnerships with technology providers to develop advanced smart key solutions that meet evolving consumer demands. These collaborations are focused on delivering innovative features such as cloud-based key management, over-the-air (OTA) updates, and integration with digital assistants. The growing emphasis on digital transformation within the automotive industry is encouraging OEMs to adopt scalable and secure smart key technologies. Additionally, the competitive landscape is fostering rapid innovation, with companies differentiating their offerings through design, functionality, and user experience. These efforts are significantly shaping the trajectory of the smart keys market in the United States.
Market Challenges Analysis
High Costs and Integration Complexities
One of the key challenges facing the United States automotive smart keys market is the high cost associated with the development, integration, and maintenance of advanced smart key systems. These systems require sophisticated hardware components such as sensors, transceivers, and secure microcontrollers, along with software that ensures encrypted communication and compatibility with a vehicle’s electronic control units (ECUs). As a result, production costs for smart key systems are significantly higher compared to traditional mechanical keys. This cost barrier can limit adoption, particularly among price-sensitive consumers and in entry-level vehicle segments. Additionally, the complexity involved in integrating smart keys with a vehicle’s broader electronic architecture can increase production timelines and necessitate specialized technical expertise. This challenge is especially pronounced for automakers transitioning from conventional key systems or developing new electric vehicle models with entirely digital interfaces.
Security Vulnerabilities and Cybersecurity Threats
Another pressing challenge for the smart keys market is the growing concern over cybersecurity threats and potential vulnerabilities in smart key systems. For instance, a study by the Consumer Technology Association (CTA) emphasizes the adoption of fingerprint and facial recognition systems to enhance vehicle security and personalization. While smart keys enhance convenience and vehicle access, they also introduce new points of entry for cyberattacks. Incidents of relay attacks, where criminals amplify the smart key signal to gain unauthorized access to a vehicle, have raised awareness about potential security gaps. As vehicles become more connected, smart key systems must defend against increasingly sophisticated hacking methods, including code interception, cloning, and software exploitation. Ensuring secure encryption protocols and regularly updating security frameworks are critical, but these measures add to development complexity and operational costs. Furthermore, a lack of standardized cybersecurity regulations across the automotive industry can result in inconsistent levels of protection across different manufacturers and models. Addressing these concerns is essential to maintaining consumer trust and sustaining the growth of smart key adoption in the United States.
Market Opportunities
The United States automotive smart keys market presents substantial opportunities driven by the rapid digital transformation of the automotive industry and increasing consumer demand for innovative, connected solutions. As vehicles become more technologically advanced, the role of smart keys is evolving beyond basic access and ignition functions to encompass a broader range of integrated features. Automakers have the opportunity to differentiate their offerings through enhanced smart key capabilities such as biometric authentication, mobile app-based control, and cloud-connected services. These innovations can enhance user experience, improve vehicle security, and support personalization, making them attractive value propositions for consumers across all vehicle segments. Furthermore, the growing adoption of electric and autonomous vehicles creates new opportunities for smart key systems that can integrate seamlessly with advanced infotainment systems, driver-assist features, and remote vehicle management platforms.
In addition to technological advancement, the rise of shared mobility services and fleet management solutions is opening new avenues for smart key applications. Digital keys that can be issued, managed, and revoked remotely offer fleet operators and mobility service providers a more efficient and secure method for managing vehicle access. This is particularly relevant in urban environments, where car-sharing and rental services are gaining popularity. The ongoing shift toward sustainability and smart cities further supports the growth of digitally managed mobility solutions. Moreover, original equipment manufacturers (OEMs) can capitalize on strategic partnerships with technology companies to co-develop next-generation smart key systems, enhancing product offerings while reducing time-to-market. As consumers increasingly prioritize convenience, connectivity, and security, the automotive smart keys market in the United States stands to benefit from robust innovation and expanding use cases across both personal and commercial vehicle applications.
Market Segmentation Analysis:
By Vehicle:
The United States automotive smart keys market can be segmented by vehicle type into passenger cars, commercial vehicles, and luxury vehicles. Among these, passenger cars represent the largest market share, driven by increasing consumer demand for comfort, convenience, and enhanced vehicle security. As keyless entry and push-button start systems become more standard in mid-range models, manufacturers are scaling smart key integration across various passenger car segments. Commercial vehicles are also witnessing a gradual uptake in smart key technology, particularly in fleets used for logistics, ride-sharing, and service operations, where digital key management offers operational efficiency and theft prevention. However, the luxury vehicles segment is at the forefront of innovation, often introducing the latest smart key features first-such as biometric access, mobile-based unlocking, and personalized user profiles. The premium focus on technology and security in luxury brands contributes significantly to advancing the smart keys market, influencing broader adoption across other vehicle categories as features trickle down to mass-market models.
By Application:
Based on application, the market is segmented into single-function and multi-function smart keys. Single-function smart keys, typically offering basic keyless entry or push-start capability, continue to be widely used in entry-level and some mid-tier vehicles. While they remain cost-effective, their growth is limited by the increasing consumer preference for more integrated solutions. Multi-function smart keys are gaining significant traction due to their ability to control a range of vehicle functions-such as trunk access, remote start, climate control, and even infotainment settings. These keys are especially popular in high-end vehicles, aligning with the trend toward connected, personalized, and secure mobility. Multi-functionality is also becoming a strategic differentiator for automakers seeking to elevate user experience and brand value. As digital lifestyles evolve, consumers increasingly expect smart keys that do more than open doors, creating strong momentum for the expansion of multi-functional systems across all vehicle segments in the U.S. market.
Segments:
Based on Vehicle:
- Passenger cars
- Commercial vehicles
- Luxury vehicles
Based on Application:
- Single Function
- Multi-Function
Based on Technology:
- Remote Keyless Entry
- Passive Keyless Entry
Based on Distribution Channel:
- OEM
- Aftermarket
Based on the Geography:
- Western United States
- Midwestern United States
- Southern United States
- Northeastern United States
Regional Analysis
Western United States
The Western United States holds the largest share of the U.S. automotive smart keys market, accounting for approximately 32% of the total market. This region, encompassing states like California, Washington, and Oregon, leads in smart key adoption due to its early adoption of advanced vehicle technologies and a strong presence of electric and luxury vehicle manufacturers. California, in particular, acts as a hub for innovation, driven by its environmentally conscious consumers, technology-focused automotive brands, and favorable regulatory landscape. The widespread adoption of electric vehicles (EVs) and plug-in hybrids in the West fuels the demand for smart keys that integrate with digital vehicle platforms. Additionally, consumer preferences in this region lean heavily toward convenience, connectivity, and security-all factors that drive smart key penetration. Proximity to major tech companies also supports strategic partnerships between OEMs and technology providers, further enhancing the region's leadership position in the market.
Midwestern United States
The Midwestern United States represents approximately 24% of the automotive smart keys market. Known as the heartland of automotive manufacturing, the Midwest is home to major production facilities of leading U.S. automakers. While the region traditionally focused on mass-market vehicles, the growing integration of smart technologies in domestic manufacturing lines is accelerating the adoption of smart keys. OEMs in Michigan, Ohio, and Illinois are increasingly embedding smart access solutions across a broader range of vehicle models to stay competitive. Moreover, the presence of skilled automotive engineers and strong industrial infrastructure supports research and development initiatives focused on connected vehicle technologies. Although consumer demand for high-tech features may not match that of coastal regions, steady growth in vehicle upgrades and increasing awareness of smart key benefits are contributing to a gradual increase in regional adoption.
Southern United States
The Southern United States accounts for approximately 26% of the national market share for automotive smart keys. This region, including Texas, Florida, and Georgia, is witnessing rising demand due to its strong population growth, high vehicle ownership rates, and expansion of urban and suburban transportation networks. The region also hosts several automotive assembly plants, especially for foreign automakers, who are increasingly equipping their vehicles with smart key technologies as part of their U.S. market strategies. The popularity of SUVs, trucks, and mid-range vehicles in the South contributes to smart key integration, particularly as OEMs push to standardize keyless systems across diverse vehicle platforms. In addition, the growing tech adoption in southern metropolitan areas is fueling consumer interest in multi-functional smart keys that align with connected lifestyles.
Northeastern United States
The Northeastern United States holds a smaller but significant share of around 18% in the automotive smart keys market. States such as New York, Massachusetts, and Pennsylvania feature dense urban environments and tech-savvy consumers who are inclined toward innovative automotive solutions. While vehicle ownership rates in the Northeast are relatively lower due to strong public transportation infrastructure, the vehicles that are owned often lean toward higher-end or technologically advanced models. This supports strong demand for luxury and multi-function smart key systems. Moreover, stringent safety and emissions regulations in the region push automakers to invest in next-generation vehicle features, including advanced security and access control systems. The Northeast also serves as a strategic market for testing premium automotive technologies, further sustaining demand for smart keys.
Key Player Analysis
- Huf Hülsbeck & Fürst GmbH & Co
- Continental AG
- ZF Friedrichshafen AG
- HELLA GmbH & Co. KGaA
- Hyundai Mobis
- Silca Group
- Tokai Rika Co.
- Denso Corporation
- ALPHA Corporation
- Valeo SA
- Robert Bosch GmbH
Competitive Analysis
The competitive landscape of the United States automotive smart keys market is characterized by the presence of several global and regional players competing through innovation, technology integration, and strategic partnerships. Leading companies such as Huf Hülsbeck & Fürst GmbH & Co, Continental AG, ZF Friedrichshafen AG, HELLA GmbH & Co. KGaA, Hyundai Mobis, Silca Group, Tokai Rika Co., Denso Corporation, ALPHA Corporation, Valeo SA, and Robert Bosch GmbH are at the forefront of this dynamic industry. These players focus on delivering high-performance smart key solutions that offer enhanced vehicle access, security, and user convenience. To maintain a competitive edge, companies are investing heavily in R&D, developing smart key systems with multi-functionality, biometric verification, and smartphone compatibility. Collaborations with automotive OEMs enable them to embed these solutions across diverse vehicle platforms, from economy to luxury segments. Additionally, many key players are leveraging their global expertise to adapt technologies to U.S. market demands, especially with the growing adoption of electric and connected vehicles. Despite strong competition, differentiation is achieved through product innovation, design, and integration with broader in-vehicle technologies. As vehicle access solutions evolve toward digital and cloud-based ecosystems, these companies are expected to play a pivotal role in shaping the future of smart mobility in the U.S. market.
Recent Developments
- In January 2025, Honda Lock, now owned by MinebeaMitsumi, expanded its product line to include advanced keyless entry systems with mobile connectivity and IoT features, aligning with the automotive industry's trend towards electrification and automation.
- In December 2024, Hyundai Mobis announced plans to expand its card-type smart key to major Hyundai models like the Santa Fe and Tucson. This key uses UWB for enhanced functionality and wireless charging capabilities.
- In April 2024, Continental developed a smart device-based access solution for Mercedes-Benz E-Class cars. This system utilizes ultra-wideband (UWB) technology, transceivers, and intelligent software to enhance security and convenience for luxury vehicles.
- In December 2023, Huf introduced a groundbreaking smart key that combines UWB, BLE, and NFC technologies in compliance with Car Connectivity Consortium (CCC) standards. This innovation enhances anti-theft security and convenience while allowing integration with "Phone as a Key" systems.
Market Concentration & Characteristics
The United States automotive smart keys market exhibits a moderately high level of market concentration, with a few dominant global players holding significant influence over technology standards, innovation, and OEM partnerships. Companies such as Continental AG, Denso Corporation, Hyundai Mobis, and Valeo SA play a central role in shaping the competitive dynamics through their extensive product portfolios, R&D capabilities, and long-standing relationships with leading automakers. The market is characterized by rapid technological advancement, a strong focus on security and connectivity features, and increasing integration of smart key systems with vehicle infotainment and telematics platforms. While larger players lead in innovation and scalability, smaller firms contribute niche solutions and customization. The industry also demonstrates high entry barriers due to the need for advanced engineering, compliance with automotive safety standards, and seamless integration with electronic control units. These characteristics underscore a competitive yet innovation-driven market environment with growing demand for advanced, multi-functional smart key solutions.
Report Coverage
The research report offers an in-depth analysis based on Vehicle, Application, Technology, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of smart key systems will continue to grow across all vehicle segments, including entry-level models.
- Automakers will increasingly integrate biometric authentication for enhanced vehicle security.
- Smartphone-based digital keys will become more widespread, supporting remote access and personalization.
- OEMs and tech firms will expand partnerships to develop connected and cloud-enabled smart key platforms.
- The rise of electric and autonomous vehicles will accelerate the demand for advanced smart key technologies.
- Over-the-air (OTA) updates for smart key software will become a standard offering.
- Consumers will expect seamless integration of smart keys with infotainment and navigation systems.
- Fleet operators and mobility services will adopt digital key management for efficiency and safety.
- Cybersecurity measures will strengthen in response to rising threats targeting smart key systems.
- The market will remain innovation-driven, with continuous R&D investment from key players.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Enhanced Vehicle Security Requirements
Rising incidents of vehicle theft and unauthorized access have led consumers and automakers to prioritize advanced security features, such as encrypted communication and rolling codes, making smart keys a preferred solution for secure vehicle access.
Consumer Demand for Convenience and Connectivity
Modern buyers increasingly expect seamless, keyless entry and push-start systems, as well as smartphone-enabled access, driving automakers to integrate smart key systems as standard or premium features across a wider range of vehicles.
Growth in Electric and Luxury Vehicle Segments
The surge in electric and hybrid vehicle production, along with the premiumization of mid-range and luxury vehicles, supports the adoption of smart key technology due to its compatibility with digital vehicle architectures and advanced infotainment systems.
Technological Innovation and Integration
Ongoing advancements in IoT, AI, and biometric authentication are enabling smart keys to offer multi-functionality, personalization, and integration with broader connected car ecosystems, making them increasingly attractive to both consumers and OEMs.
OEM and Technology Partnerships
Strategic collaborations between automakers and technology firms are accelerating the development and deployment of next-generation smart key solutions, including cloud-based management and over-the-air updates, further expanding market reach and capabilities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the United States Automotive Smart Keys market?
What factors are driving the growth of the United States Automotive Smart Keys market?
What are some challenges faced by the United States Automotive Smart Keys market?
Who are the major players in the United States Automotive Smart Keys market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vehicle
- 1.2.1 Passenger cars
- 1.2.2 Commercial vehicles
- 1.2.3 Luxury vehicles
- 1.3 By Technology
- 1.3.1 Remote Keyless Entry
- 1.3.2 Passive Keyless Entry
- 1.4 By Application
- 1.4.1 Single Function
- 1.4.2 Multi-Function
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 3,644.40 million → 2032: USD 7,788.21 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 United States Automotive Smart Keys Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 United States Automotive Smart Keys Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 United States Automotive Smart Keys Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 United States Automotive Smart Keys Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 United States Automotive Smart Keys Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 United States Automotive Smart Keys Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 United States Automotive Smart Keys Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 United States Automotive Smart Keys Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 3,644.40 million → 2032: USD 7,788.21 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 United States Automotive Smart Keys Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vehicle - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Passenger cars
- 12.3.7.2 Commercial vehicles
- 12.3.7.3 Luxury vehicles
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Remote Keyless Entry
- 12.4.7.2 Passive Keyless Entry
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Single Function
- 12.5.7.2 Multi-Function
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 United States Automotive Smart Keys End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 United States Automotive Smart Keys Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 United States Automotive Smart Keys Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 United States Automotive Smart Keys Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Continental AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Denso Corporation
- 18.4 Hyundai Mobis
- 18.5 Valeo SA
- 18.6 Robert Bosch GmbH
- 18.7 Huf Hülsbeck & Fürst GmbH & Co
- 18.8 ZF Friedrichshafen AG
- 18.9 HELLA GmbH & Co. KGaA
- 18.10 Silca Group
- 18.11 Tokai Rika Co.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

