
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
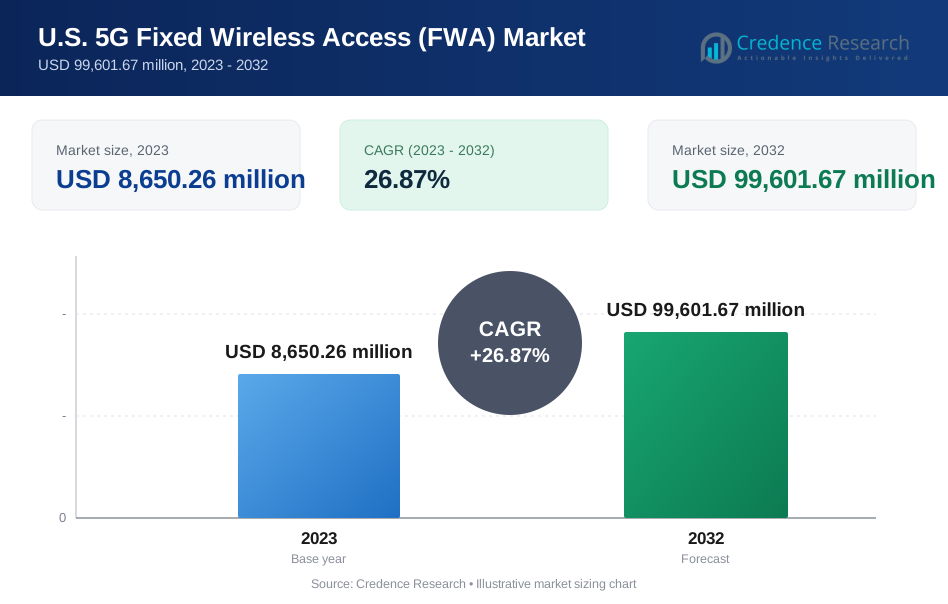
| U.S. 5G Fixed Wireless Access (FWA) Market Size 2023 | USD 8,650.26 million |
| U.S. 5G Fixed Wireless Access (FWA) Market, CAGR | 26.87% |
| U.S. 5G Fixed Wireless Access (FWA) Market Size 2032 | USD 99,601.67 million |
Market Overview
The U.S. 5G Fixed Wireless Access (FWA) Market is projected to grow from USD 8,650.26 million in 2023 to an estimated USD 99,601.67 million by 2032, with a compound annual growth rate (CAGR) of 26.87% from 2024 to 2032. The growing demand for high-speed internet and the increasing adoption of 5G technology across urban and rural regions are the primary drivers behind this rapid market expansion.
Several key factors are driving the growth of the U.S. 5G FWA market, including the surge in mobile data traffic, the increasing need for high-speed internet, and the enhanced performance and lower latency offered by 5G networks. In addition, the U.S. government's efforts to enhance rural connectivity and reduce the digital divide through the implementation of 5G infrastructure are contributing to the market's growth. The adoption of 5G FWA is also supported by technological advancements in network equipment and the decreasing cost of hardware.
Geographically, the U.S. market is witnessing significant growth in both urban and rural areas, with urban regions expected to lead the adoption due to higher demand for high-speed internet and 5G services. Key players in the U.S. 5G FWA market include Verizon Communications, T-Mobile US, and AT&T, all of which are investing heavily in the deployment of 5G infrastructure to capture a larger share of this rapidly expanding market.
Market Insights
- The U.S. 5G Fixed Wireless Access (FWA) market is expected to grow from USD 8,650.26 million in 2023 to USD 99,601.67 million by 2032, with a CAGR of 26.87%.
- Key drivers include rising demand for high-speed internet, government initiatives for rural broadband, and the increasing adoption of 5G technology.
- The development of 5G infrastructure, including advancements in network equipment and reduced hardware costs, is fueling market growth.
- Challenges include limited spectrum availability in rural areas and the high infrastructure costs associated with deploying 5G FWA networks.
- Government programs, such as the Rural Digital Opportunity Fund, are promoting 5G FWA adoption, particularly in underserved regions.
- Urban areas lead in market share due to high demand, while rural regions present growth opportunities, driven by government-backed initiatives.
- Key market players such as Verizon, AT&T, and T-Mobile are heavily investing in 5G infrastructure to capture a larger share of the rapidly growing market.
Market Drivers
Increasing Demand for High-Speed Internet and Connectivity
The demand for high-speed internet services is growing rapidly across the U.S., driven by the increasing need for reliable, fast, and uninterrupted connectivity. For instance, a report from OpenVault indicates that average monthly broadband consumption in the U.S. has more than doubled over the past five years, increasing from 270 GB in 2018 to 641 GB in late 2023. This surge reflects the growing reliance on high-speed internet for various activities, as evidenced by the fact that about one-third of subscribers are now provisioned for gigabit speeds, marking a significant shift towards faster internet options. As more devices become interconnected through the Internet of Things (IoT), and as industries such as education, healthcare, and entertainment shift toward digital platforms, high-speed internet has become a necessity rather than a luxury. Traditional broadband networks, such as DSL and cable, struggle to keep up with the growing data demands of consumers and businesses. This gap has led to an increasing adoption of 5G Fixed Wireless Access (FWA) as a solution that offers higher speeds, lower latency, and greater bandwidth. 5G networks enable faster download and upload speeds compared to 4G LTE, making FWA a more viable alternative to traditional wired broadband services. With 5G FWA, users in urban and remote areas can access ultra-high-speed internet without the need for physical infrastructure like fiber cables, thus increasing the appeal of 5G as a modern, scalable solution to meet the surging demand for internet connectivity.
Government Initiatives and Investments in 5G Infrastructure
Government support plays a critical role in the growth of the U.S. 5G FWA market. The federal government, through initiatives such as the National Broadband Plan and the Rural Digital Opportunity Fund (RDOF), is heavily investing in the expansion of broadband networks to underserved and rural areas. According to Federal Communications Commission (FCC) data from June 2021, approximately 97.6% of the American population had access to fixed broadband connections capable of at least 25 Mbps download speeds. These initiatives aim to bridge the digital divide and ensure that all U.S. citizens have access to high-speed internet. With a strong push from the government for 5G infrastructure deployment, the U.S. is seeing a growing number of 5G base stations and towers being built in both urban and rural locations. These investments not only benefit consumers but also create favorable conditions for businesses and service providers to launch FWA services. As 5G technology continues to be rolled out, FWA solutions are becoming increasingly available to more households and businesses, particularly in regions that were once underserved by traditional broadband providers. Additionally, state and local governments are also offering incentives to encourage the deployment of 5G FWA, further driving market growth.
Cost-Effectiveness of 5G FWA Compared to Traditional Broadband
One of the significant advantages of 5G Fixed Wireless Access is its cost-effectiveness, both for service providers and end-users. Traditional broadband solutions, such as fiber optic and cable, require significant infrastructure investments in the form of laying cables and digging trenches, which can be costly and time-consuming. In contrast, 5G FWA eliminates the need for expensive physical infrastructure by transmitting data wirelessly, allowing service providers to roll out networks faster and more economically. This is particularly advantageous in rural and underserved areas where deploying fiber cables can be a logistical and financial challenge. For consumers, 5G FWA often results in lower installation and service costs, as well as faster service activation times. The technology’s scalability also ensures that it can be rapidly expanded as demand grows, further lowering the costs associated with infrastructure development. This makes 5G FWA an attractive alternative for users in both rural and urban areas who need reliable and affordable high-speed internet access.
Advancements in 5G Technology and Network Infrastructure
Technological advancements in 5G networks and infrastructure are another key driver of the U.S. 5G FWA market. With the evolution of 5G technology, users can expect faster data transmission speeds, lower latency, and improved reliability compared to previous wireless standards. The improved performance of 5G is a significant factor in the adoption of 5G FWA, as it can provide a superior experience to traditional broadband services. Moreover, as Pew Research found that around 80% of U.S. adults subscribe to high-speed internet at home; this figure underscores the essential nature of reliable connectivity in both urban and rural settings. The rollout of millimeter-wave (mmWave) spectrum for 5G is increasing the capacity and coverage of 5G networks, enabling service providers to deliver faster speeds and greater network efficiency. The development of new network technologies, such as Massive MIMO (Multiple Input, Multiple Output) and beamforming, is enhancing the ability to transmit data more efficiently over long distances, further expanding coverage area for 5G FWA. These innovations are creating more robust 5G networks that are better suited to meet consumer and business needs, driving adoption of FWA solutions across the country. Furthermore, as 5G technology continues to mature, increased availability of 5G-enabled devices will contribute to greater demand for FWA services.
Market Trends
Increased Investment in 5G Network Infrastructure
One of the most significant trends in the U.S. 5G Fixed Wireless Access (FWA) market is the accelerated investment in 5G network infrastructure by telecommunications companies and service providers. Major players such as Verizon, AT&T, and T-Mobile are investing billions of dollars into deploying 5G networks, with a strong focus on expanding coverage across urban and rural areas. For instance, AT&T has reported that its nationwide 5G network now covers over 210 million people and passes more than 26 million locations, demonstrating a significant commitment to expanding its 5G footprint. Similarly, Verizon's aggressive strategy includes acquiring 3,511 licenses at a recent auction, amounting to a substantial financial commitment aimed at enhancing its 5G capabilities. T-Mobile, leveraging its acquisition of Sprint, has positioned itself as a formidable competitor in the market, actively expanding its 5G network to ensure comprehensive coverage across urban and rural areas. This shift toward robust 5G infrastructure is facilitating the rapid adoption of FWA solutions. 5G FWA offers an alternative to fiber-optic broadband in areas where deploying physical cables is cost-prohibitive. Telecommunications companies are building out 5G towers, small cells, and edge computing infrastructure to ensure that both urban and rural areas have access to high-speed wireless broadband. These investments are not only supporting the expansion of 5G coverage but also enabling enhanced performance characteristics such as lower latency, faster speeds, and higher bandwidth, which are crucial for delivering quality FWA services. Moreover, the growing number of 5G-enabled devices is pushing service providers to continue expanding and upgrading their 5G infrastructure to meet rising demand, thus fostering further growth in the FWA market.
Adoption of mmWave Spectrum for Enhanced Speed and Capacity
The adoption of the millimeter-wave (mmWave) spectrum is a key trend currently driving the U.S. 5G Fixed Wireless Access market. The mmWave spectrum, which offers higher frequency bands for 5G networks, is capable of delivering faster data speeds and higher capacity compared to lower-frequency bands. For example, Verizon has achieved average download speeds of 437.5 Mbps using mmWave technology, showcasing its potential for delivering high-speed services essential for 5G FWA solutions. While lower frequencies provide better coverage and penetration, mmWave allows for high-speed, high-capacity wireless communication, which is crucial for 5G FWA services that require faster download and upload speeds. Telecom operators in the U.S. are increasingly leveraging mmWave spectrum to expand the reach and capacity of their 5G networks, thus enabling them to offer enhanced FWA services to consumers. The use of mmWave enables providers to deliver gigabit speeds, making it a powerful alternative to traditional broadband solutions like cable or fiber. The growing demand for bandwidth-intensive applications, such as 4K video streaming, online gaming, and remote work, has further fueled the need for the expanded use of mmWave in the FWA market. This trend is contributing to the enhanced competitiveness of 5G FWA as a viable and superior alternative to traditional fixed broadband services, particularly in dense urban environments where the need for high-speed, high-capacity networks is most critical.
Government Support and Rural Broadband Initiatives
Another important trend shaping the U.S. 5G Fixed Wireless Access market is the growing government support for expanding broadband access to rural and underserved areas. In an effort to bridge the digital divide, the U.S. government has launched various initiatives to promote the deployment of 5G networks, particularly in regions where traditional broadband infrastructure is sparse or nonexistent. Programs such as the Rural Digital Opportunity Fund (RDOF) and the Infrastructure Investment and Jobs Act (IIJA) are designed to accelerate the rollout of high-speed internet across the country, with a focus on rural areas. As part of these efforts, the government is providing financial incentives to telecommunications companies to deploy 5G and FWA solutions in hard-to-reach regions. The growing adoption of 5G FWA is a direct result of these initiatives, which aim to ensure that all U.S. citizens have access to reliable and affordable high-speed internet. With government funding supporting broadband infrastructure development, telecommunications companies are increasingly expanding their 5G FWA offerings to serve areas that have been historically underserved or overlooked by traditional broadband providers. As a result, rural areas that were once at a disadvantage when it came to high-speed internet access are benefiting from the deployment of 5G FWA, enabling them to access similar speeds and capabilities as urban regions.
Integration of Advanced Technologies for Improved Performance
The integration of advanced technologies is another prominent trend in the U.S. 5G Fixed Wireless Access market. To maximize the performance of 5G FWA, operators are incorporating cutting-edge innovations such as Massive MIMO (Multiple Input, Multiple Output) technology, beamforming, and network slicing. These technologies enhance the capacity and efficiency of 5G networks, allowing service providers to offer more reliable and high-performance FWA solutions.Massive MIMO is particularly important in densely populated urban areas where managing large numbers of connections simultaneously is essential. By using numerous antennas to send and receive data streams simultaneously, Massive MIMO improves overall network capacity and coverage of 5G networks. Beamforming ensures that signals are directed specifically towards devices, enhancing both coverage and signal quality. Additionally, network slicing enables operators to create customized virtual networks tailored to specific use cases—ensuring that 5G FWA services meet diverse customer demands across residential, business, and industrial segments.The convergence of these technologies is enhancing scalability, flexibility, and reliability within the realm of 5G FWA solutions—making it a more attractive option for consumers and businesses alike.
Market Challenges
Limited Coverage and Spectrum Availability
One of the primary challenges facing the U.S. 5G Fixed Wireless Access (FWA) market is the limited coverage and availability of the necessary spectrum. While 5G offers significant advantages in terms of speed and capacity, the ability to effectively deploy and expand 5G FWA services across the country is constrained by the availability of spectrum, especially in rural and remote areas. While the millimeter-wave (mmWave) spectrum enables high-speed data transfer, its range and penetration capabilities are limited compared to lower frequencies, making it more suitable for urban environments. This results in challenges for telecom operators to extend 5G FWA services to rural and suburban regions, where infrastructure is sparse, and demand is often lower. To overcome this challenge, service providers must invest in network densification, including the installation of small cells and additional base stations, which can be costly and time-consuming. The limited availability of spectrum for 5G also creates competition among telecom companies, which can drive up costs and delay the rollout of 5G infrastructure, impacting the speed at which 5G FWA services are made available to consumers.
High Infrastructure Costs and Deployment Challenges
Despite being a more cost-effective solution than traditional wired broadband, 5G Fixed Wireless Access still presents significant infrastructure deployment challenges. Establishing 5G networks, particularly in rural and underserved areas, requires substantial investments in base stations, towers, small cells, and fiber backhaul infrastructure. These costs are particularly high in sparsely populated regions where the demand for services may not justify the large capital expenditures needed for network expansion. Furthermore, the complexity of deploying 5G infrastructure, which often requires regulatory approvals, permits, and coordination with local governments, can slow down the rollout process. Additionally, while FWA can be a faster and more affordable alternative to fiber or cable broadband, it still requires substantial upfront investments from telecom providers, which may face financial constraints or be reluctant to invest heavily in areas with uncertain returns. As a result, service providers must balance the financial risks of deploying 5G infrastructure with the potential for long-term growth, creating challenges in meeting the demand for high-speed internet in all regions of the U.S.
Market Opportunities
Expansion into Rural and Underserved Areas
One of the most significant market opportunities in the U.S. 5G Fixed Wireless Access (FWA) market lies in expanding service coverage to rural and underserved areas. As traditional broadband providers continue to face challenges in deploying fiber-optic infrastructure in less densely populated regions, 5G FWA presents an attractive alternative for delivering high-speed internet. The U.S. government’s efforts to bridge the digital divide, through initiatives such as the Rural Digital Opportunity Fund (RDOF) and the Infrastructure Investment and Jobs Act (IIJA), are accelerating the adoption of 5G FWA by providing financial incentives for service providers to extend coverage to these areas. With the ability to deliver fast and reliable internet without the need for costly physical infrastructure, 5G FWA offers a scalable and cost-effective solution for rural broadband, creating significant growth potential for telecom operators targeting these regions.
Integration with Emerging Technologies and Use Cases
Another key opportunity in the U.S. 5G FWA market is its integration with emerging technologies and the growing demand for data-intensive applications. The proliferation of smart homes, remote work, telehealth, and IoT devices is increasing the demand for high-speed, low-latency connectivity, which 5G FWA is well-positioned to deliver. Furthermore, advancements in network technologies such as edge computing, AI-driven network optimization, and network slicing open up opportunities for telecom providers to offer customized solutions for various sectors, including healthcare, education, and entertainment. By leveraging these technologies, service providers can enhance their FWA offerings, drive new revenue streams, and meet the evolving needs of both residential and business customers.
Market Segmentation Analysis
By Offering
The U.S. 5G Fixed Wireless Access (FWA) market is driven by two key segments: hardware and services. The hardware segment includes essential components such as 5G routers, gateways, base stations, antennas, and small cells, which are crucial for the deployment of 5G networks. As telecom operators expand their infrastructure, the demand for advanced hardware that supports mmWave and sub-6 GHz frequency bands is expected to grow significantly. On the other hand, the services segment covers the delivery of 5G FWA broadband services, including installation, maintenance, and management of systems. Service providers are focusing on offering competitive subscription plans, improved customer support, and value-added services like network optimization and IoT integration to enhance user experience. The growth of both segments is closely tied to the ongoing expansion of 5G infrastructure and the increasing demand for reliable, high-speed internet.
By Operating
The U.S. 5G Fixed Wireless Access (FWA) market operates across three key frequency bands: Sub-6 GHz, 24-39 GHz, and Above 39 GHz. Sub-6 GHz frequencies provide broad coverage, balancing range and speed, making them ideal for suburban and rural areas that require wider coverage and penetration. The 24-39 GHz mid-band spectrum offers higher capacity and faster speeds than Sub-6 GHz, making it well-suited for urban environments with high demand for fast connectivity. Finally, the Above 39 GHz, or millimeter-wave (mmWave) spectrum, delivers the fastest speeds and highest capacity, making it essential for dense urban areas where high bandwidth is necessary to support large data volumes, driving the growth of advanced 5G FWA services.
Segments
Based on Offering
- Hardware
- Services
Based on Operating Frequency
- Sub 6GHz
- 24-39 GHz
- Above 39GHz
Based on Application
- Residential
- Commercial
- Industrial
- Government
Regional Analysis
Urban Region (50%):
The urban region holds the largest share of the U.S. 5G FWA market, accounting for nearly 50% of the total market share. This high concentration is driven by the dense population, high demand for fast, reliable internet, and advanced infrastructure in urban areas. Cities such as New York, Los Angeles, and Chicago are at the forefront of 5G FWA adoption, where telecom operators are deploying millimeter-wave (mmWave) spectrum to offer high-capacity services. In urban regions, FWA is seen as an ideal solution to meet the demand for bandwidth-heavy applications like 4K streaming, cloud computing, and enterprise solutions. The rapid rollout of 5G networks in these areas has created a competitive environment for service providers, further fueling the market's expansion.
Rural Region (20%):
Rural areas account for approximately 20% of the U.S. 5G FWA market share, but this region presents one of the most significant growth opportunities for the market. Traditional wired broadband infrastructure is often limited or non-existent in rural regions, making FWA a viable and cost-effective solution for providing high-speed internet. The U.S. government’s investments through programs such as the Rural Digital Opportunity Fund (RDOF) and the Infrastructure Investment and Jobs Act (IIJA) have accelerated the rollout of 5G networks in underserved regions. Telecom companies are prioritizing rural areas for 5G FWA deployment to bridge the digital divide and provide equitable access to fast internet services. As the rollout of 5G infrastructure progresses, rural areas are expected to experience robust growth in FWA adoption, driven by both public initiatives and increasing consumer demand.
Key players
- AT&T
- Huawei Technologies Co., Ltd.
- Telefonaktiebolaget LM
- US Cellular
- Ericsson
- Nokia
- Samsung
- Inseego Corp.
- Qualcomm Technologies, Inc.
- Intel Corporation
- MediaTek Inc.
Competitive Analysis
The U.S. 5G Fixed Wireless Access (FWA) market is highly competitive, with leading telecom operators, technology providers, and semiconductor companies vying for market share. AT&T and US Cellular are dominant players in the telecom sector, driving the deployment of 5G FWA solutions across urban and rural regions. Ericsson, Nokia, and Huawei are key suppliers of 5G network equipment, enabling telecom operators to expand their 5G infrastructure. Samsung and Inseego are prominent in providing 5G-enabled routers and devices, which are integral to FWA solutions. Qualcomm Technologies and MediaTek are essential contributors in semiconductor technology, powering the 5G devices used in FWA services. Intel's presence in the semiconductor industry also bolsters the FWA ecosystem. As the market grows, competition will intensify, with companies focusing on innovation, network coverage, and strategic partnerships to secure long-term market leadership.
Recent Developments
- In May 2024, AT&T and Cisco introduced a new digital buying experience for businesses to deploy 5G FWA easily, featuring the Cisco Meraki MG52 and MG52E Cellular Gateways, which are the first true 5G Standalone capable FWA devices with cloud-managed eSIM technology.
- In June 2024, Ericsson released its Mobility Report, highlighting the growing number of service providers offering 5G FWA services. The report indicated that approximately 53% of surveyed communication service providers now include a 5G FWA offering, marking a significant increase from the previous year.
- In October 2024, Nokia announced enhancements to its Fixed Wireless Access portfolio aimed at improving connectivity in rural areas. These enhancements leverage advanced 5G technology to provide better coverage and capacity for underserved communities.
- In April 2024, Samsung launched its new line of 5G FWA solutions designed for enterprise customers, emphasizing high-speed connectivity and low latency. These products are aimed at enhancing business operations in areas lacking traditional broadband infrastructure.
- In February 2024, US Cellular announced the expansion of its 5G FWA services to additional markets across the Midwest, aiming to enhance connectivity options for rural customers.
- In July 2024, MediaTek introduced a new chipset designed for high-performance 5G FWA devices, supporting advanced features that improve user experience in both urban and rural deployments.
- In August 2024, Huawei launched a new range of FWA products tailored for the North American market, focusing on integration with existing telecommunications infrastructure to enhance service delivery.
- In September 2024, Telia announced partnerships with local U.S. providers to expand its 5G FWA offerings, targeting both urban centers and rural communities in need of better internet access.
Market Concentration and Characteristics
The U.S. 5G Fixed Wireless Access (FWA) market is characterized by moderate to high market concentration, with several key players dominating the landscape. Major telecom operators like AT&T, Verizon, and T-Mobile are at the forefront, driving the adoption and expansion of 5G FWA services across urban, semi-urban, and rural areas. These companies are supported by network equipment providers such as Ericsson, Nokia, and Huawei, which supply the necessary infrastructure for 5G deployment. Additionally, semiconductor companies like Qualcomm, Intel, and MediaTek play a crucial role in providing the technology that powers 5G devices and routers. The market is competitive, with service providers and equipment manufacturers focusing on innovation, improved service quality, and network expansion to meet the growing demand for high-speed, reliable internet. As telecom operators increase their investments in 5G infrastructure, the market is expected to see further consolidation, with a few large players holding significant market shares while smaller companies work on niche offerings and technological advancements.
Report Coverage
The research report offers an in-depth analysis based on Offering, Operating Frequency, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market
Future Outlook
- The U.S. 5G FWA market is expected to experience robust growth, driven by the increasing demand for high-speed internet. With a projected compound annual growth rate (CAGR) of 26.87%, the market is poised to expand significantly by 2032.
- Government initiatives, such as the Rural Digital Opportunity Fund, will play a pivotal role in expanding FWA coverage to underserved areas. These efforts aim to reduce the digital divide and provide equitable access to high-speed broadband.
- The growing deployment of mmWave spectrum will enhance network capacity and speed, making 5G FWA more viable for high-density urban areas. The continued roll-out of mmWave will improve service quality and user experience.
- Telecom companies are likely to increase investments in 5G infrastructure, including small cells, towers, and base stations, to support the growing demand for FWA services. This will lead to faster and more extensive deployment of 5G networks.
- As 5G technology evolves, advancements such as network slicing, Massive MIMO, and edge computing will further optimize FWA performance. These technologies will enable better network efficiency and faster service delivery.
- The proliferation of IoT devices and smart home technologies will drive the demand for higher bandwidth, further boosting the need for reliable 5G FWA services. These devices require seamless connectivity, which 5G FWA can effectively support.
- The adoption of 5G FWA will accelerate in suburban and semi-urban regions, where traditional broadband infrastructure is limited. The convenience and cost-effectiveness of FWA will make it a preferred option for these areas.
- With the growing number of players in the 5G FWA market, competition will intensify. Telecom companies will differentiate themselves through pricing strategies, service quality, and enhanced customer support to capture market share.
- Telecom operators and technology providers will increasingly form strategic partnerships to enhance their 5G FWA offerings. Collaborations will focus on network infrastructure, device compatibility, and service optimization to expand market reach.
- The industry will focus on sustainability in 5G FWA deployments, with emphasis on energy-efficient network infrastructure and eco-friendly devices. Telecom providers will adopt green practices to meet regulatory requirements and improve their environmental footprint.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the U.S. 5G Fixed Wireless Access (FWA) market in 2023 and 2032?
What is the expected compound annual growth rate (CAGR) of the U.S. 5G FWA market?
What are the primary drivers of the U.S. 5G FWA market growth?
Which regions are experiencing the highest growth in the U.S. 5G FWA market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. 5G Fixed Wireless Access (FWA) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. 5G Fixed Wireless Access (FWA) Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 8,650.26 million → 2032: USD 99,601.67 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. 5G Fixed Wireless Access (FWA) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. 5G Fixed Wireless Access (FWA) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. 5G Fixed Wireless Access (FWA) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. 5G Fixed Wireless Access (FWA) Market Drivers
- 3.3 U.S. 5G Fixed Wireless Access (FWA) Market Restraints & Challenges
- 3.4 U.S. 5G Fixed Wireless Access (FWA) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. 5G Fixed Wireless Access (FWA) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. 5G Fixed Wireless Access (FWA) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. 5G Fixed Wireless Access (FWA) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. 5G Fixed Wireless Access (FWA) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. 5G Fixed Wireless Access (FWA) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. 5G Fixed Wireless Access (FWA) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. 5G Fixed Wireless Access (FWA) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. 5G Fixed Wireless Access (FWA) Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. 5G Fixed Wireless Access (FWA) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. 5G Fixed Wireless Access (FWA) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. 5G Fixed Wireless Access (FWA) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. 5G Fixed Wireless Access (FWA) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. 5G Fixed Wireless Access (FWA) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. 5G Fixed Wireless Access (FWA) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. 5G Fixed Wireless Access (FWA) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. 5G Fixed Wireless Access (FWA) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. 5G Fixed Wireless Access (FWA) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. 5G Fixed Wireless Access (FWA) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. 5G Fixed Wireless Access (FWA) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
