
Market Overview:
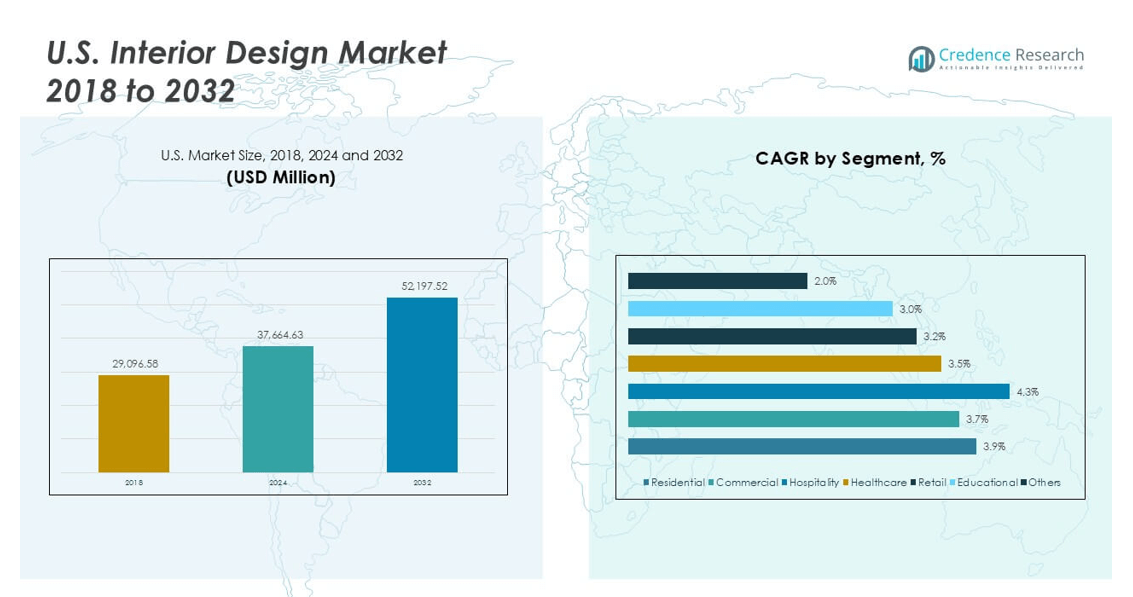
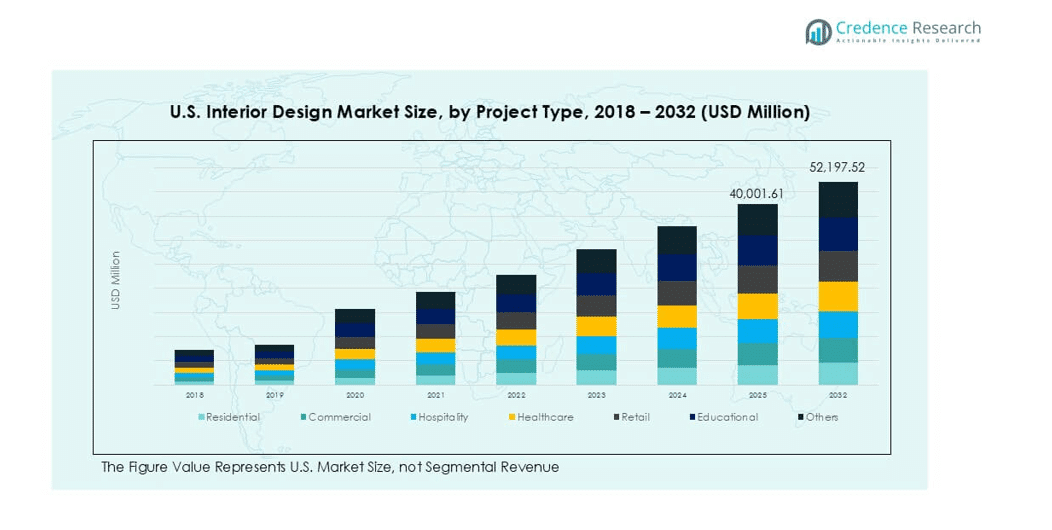
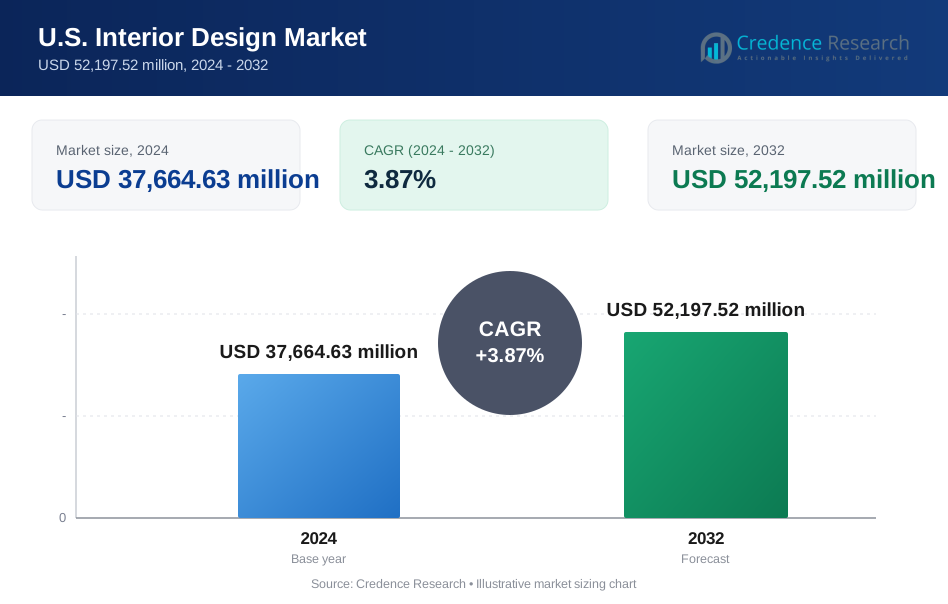
The U.S. interior design market size was valued at USD 29,096.58 million in 2018, reaching USD 37,664.63 million in 2024, and is anticipated to attain USD 52,197.52 million by 2032, growing at a CAGR of 3.87% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Interior Design Market Size 2024 | USD 37,664.63 million |
| U.S. Interior Design Market, CAGR | 3.87% |
| U.S. Interior Design Market Size 2032 | USD 52,197.52 million |
The U.S. interior design market is led by top firms such as Gensler, HOK, Perkins and Will, CannonDesign, and Corgan. These companies dominate high-value commercial, corporate, and institutional projects through advanced design capabilities and large client networks. Gensler remains the market leader, recognized for its extensive portfolio across office, hospitality, and retail sectors. HOK and Perkins and Will emphasize sustainable and technology-driven design approaches, while CannonDesign and Corgan focus on healthcare and educational spaces. Regionally, the South leads with a 34% market share, driven by rapid urbanization and residential growth, followed by the West at 24%, Northeast at 23%, and Midwest at 19%.
Market Insights
- The U.S. interior design market was valued at USD 37,664.63 million in 2024 and is projected to reach USD 52,197.52 million by 2032, growing at a CAGR of 3.87%.
- Market growth is driven by rising residential renovation, corporate workspace modernization, and hospitality expansion across major urban centers.
- Sustainable design trends, smart-home integration, and 3D visualization tools are reshaping design processes and customer engagement across the residential and commercial sectors.
- Gensler, HOK, Perkins and Will, CannonDesign, and Corgan dominate the competitive landscape, leveraging BIM and digital design platforms to secure large-scale projects.
- Regionally, the South leads with 34% share due to urban expansion and new housing, followed by the West at 24%, Northeast at 23%, and Midwest at 19%; the residential segment holds the largest 41% share of total market revenue.
Market Segmentation Analysis:
By Project Type
The residential segment held the dominant share of the U.S. interior design market in 2024, accounting for over 41% of total revenue. Growth is fueled by rising home renovation spending, luxury housing projects, and the popularity of smart and sustainable interiors. Demand for personalized designs and multifunctional spaces drives extensive adoption among urban homeowners. The commercial and hospitality segments also expand steadily, supported by investments in coworking spaces, hotels, and restaurants that prioritize aesthetic branding and customer experience enhancement.
- For instance, in June 2022, IKEA launched "Kreativ" in the U.S., an AI-powered, mixed-reality design platform accessed through the IKEA app and website. It uses AI and computer vision to create editable 3D replicas of customers' rooms, allows them to erase existing furniture, and place IKEA products virtually.
By Service Type
Interior decoration emerged as the leading service type, capturing nearly 38% of the U.S. market in 2024. The dominance stems from increasing residential remodeling activities and preference for custom furniture, artwork, and finishes that reflect modern or minimalist styles. Interior design consulting and space planning services are also witnessing rapid growth due to corporate emphasis on functional workspace layouts and energy efficiency. Furniture and lighting design services gain traction as commercial and hospitality establishments adopt contemporary design solutions integrating IoT-enabled systems and sustainable materials.
- For instance, Herman Miller has deployed smart furniture solutions, such as its Live OS platform, to corporate offices, embedding IoT sensors to optimize workspace ergonomics and usage analytics.
By Budget Range
Projects in the $10,000–$50,000 range represented the largest share of the U.S. interior design market, accounting for around 33% in 2024. This range appeals to middle-income homeowners and small businesses seeking affordable yet high-quality design solutions. Increasing renovation in suburban housing and boutique commercial spaces strengthens this segment’s position. Higher budget categories, particularly those exceeding $250,000, are growing as luxury homebuilders, corporate offices, and hotels demand bespoke interiors featuring premium finishes, advanced lighting, and smart automation systems to enhance functionality and aesthetics.
Key Growth Drivers
Rising Home Renovation and Remodeling Activities
Increasing home renovation projects remain a major growth driver for the U.S. interior design market. Homeowners are investing in modern, functional, and energy-efficient interiors to enhance comfort and property value. The surge in remote work has led to a growing demand for home office setups, modular furniture, and space optimization solutions. According to the Joint Center for Housing Studies, Americans spent over USD 481 billion on home improvements in 2023. Additionally, the adoption of sustainable materials, eco-friendly lighting, and smart-home integrations fuels steady revenue growth in the residential interior design segment.
- For instance, Lowe's sells a wide variety of smart lighting and appliance systems, allowing customers to purchase and install them to improve residential energy efficiency.
Commercial and Hospitality Sector Expansion
Rising investments in commercial infrastructure and hospitality projects significantly boost market demand. Corporations are modernizing offices with ergonomic designs and biophilic elements to enhance employee well-being and productivity. The U.S. hotel and tourism industry’s expansion drives strong design activity in luxury hotels, restaurants, and resorts focusing on immersive guest experiences. Retail spaces are also embracing experiential designs that combine aesthetic appeal and brand storytelling. These initiatives create continuous opportunities for professional designers specializing in commercial and hospitality interiors.
- For instance, Gensler completed more than 3,200 commercial interior projects across the U.S., including office redesigns with energy-saving HVAC and lighting systems.
Technological Advancements in Design and Visualization
The growing use of digital design tools and visualization technologies enhances project efficiency and accuracy. Designers are adopting Building Information Modeling (BIM), augmented reality (AR), and 3D rendering platforms to provide real-time design previews and reduce project delays. Clients benefit from interactive visualizations that streamline decision-making and customization. For instance, virtual walkthroughs allow instant assessment of layout, color, and lighting configurations. Technology integration also reduces material waste, improves cost estimation, and promotes sustainable construction practices. These innovations strengthen client-designer collaboration and drive overall market modernization.
Key Trends & Opportunities
Adoption of Sustainable and Eco-Friendly Design Practices
The growing focus on sustainability presents strong opportunities for interior designers in the U.S. market. Consumers increasingly prefer designs that incorporate recycled materials, low-VOC paints, and energy-efficient lighting systems. Developers and commercial owners are pursuing LEED and WELL certifications to meet green building standards. This shift is supported by federal and state incentives encouraging low-carbon construction and renovation. Interior design firms offering sustainable product sourcing, waste minimization, and circular design services gain a competitive edge in this evolving market landscape.
- For instance, in 2024, Perkins & Will continued its long-standing commitment to sustainable design, working on numerous LEED-certified projects, focusing on using sustainable materials, and creating energy-efficient layouts.
Rising Demand for Smart and Connected Interiors
The integration of smart-home technologies into interior spaces has become a leading trend. Automated lighting, temperature control, and voice-activated systems are transforming residential and commercial interiors into intelligent environments. The U.S. smart-home penetration rate exceeded 40% in 2024, driving demand for design solutions that accommodate digital connectivity. Interior designers now collaborate with technology integrators to ensure seamless system installation and aesthetic alignment. This trend creates new revenue streams for firms specializing in tech-integrated layouts and connected furnishings.
Key Challenges
High Project Costs and Budget Constraints
The rising cost of raw materials, custom furniture, and skilled labor continues to challenge market growth. Budget limitations often restrict homeowners and small businesses from engaging professional design services. Inflation in construction materials such as wood, metal, and textiles further increases overall project costs. Designers face pressure to deliver high-quality outcomes within tight financial parameters, leading to compromises in customization and sustainability. Balancing affordability and premium aesthetics remains a persistent challenge for service providers across the sector.
Shortage of Skilled Workforce and Design Professionals
The U.S. interior design industry faces a talent shortage, particularly in specialized areas such as lighting design, sustainable architecture, and digital visualization. Educational programs are struggling to meet rising industry demand for multidisciplinary designers skilled in both creativity and technology. Many firms experience delays due to limited availability of qualified professionals, impacting project timelines and profitability. The challenge intensifies as design complexity increases with digital and environmental considerations. Addressing skill development through training and academic partnerships remains essential for sustaining long-term industry growth.
Regional Analysis
Northeast
The Northeast region accounted for around 23% share of the U.S. interior design market in 2024. Growth is driven by high renovation spending in states such as New York, Massachusetts, and Pennsylvania. Urban homeowners increasingly seek modern and sustainable design solutions that maximize limited space. The region’s strong commercial base, particularly in office and retail design, supports steady demand for professional services. Additionally, luxury residential developments and heritage property refurbishments in metropolitan areas like Boston and New York City continue to attract top design firms specializing in bespoke interior projects.
Midwest
The Midwest captured nearly 19% market share in 2024, supported by steady construction and remodeling across Illinois, Michigan, and Ohio. The region benefits from growing investments in suburban housing and mid-scale commercial projects. Affordable housing programs and revitalization of industrial spaces into modern offices fuel interior design adoption. Homeowners prioritize functional layouts, energy-efficient lighting, and ergonomic furnishings. The presence of regional design studios and rising DIY awareness contribute to expanding client bases. Midwestern cities such as Chicago and Minneapolis show rising demand for mixed-use interior projects combining residential and office spaces.
South
The South held the largest share at 34% in 2024, dominating the U.S. interior design market. Rapid urbanization, population growth, and rising residential construction across Texas, Florida, and Georgia drive market leadership. The region’s expanding hospitality and commercial infrastructure further strengthens design demand. Luxury homes and large-scale corporate projects increasingly adopt modern and sustainable interiors. Strong presence of design firms offering turnkey solutions supports continued growth. Growing consumer preference for spacious layouts, vibrant aesthetics, and smart-home integration makes the South a major hub for innovation in interior design.
West
The West region accounted for about 24% share in 2024, led by strong design demand from California, Washington, and Colorado. The region benefits from a high concentration of high-income consumers and sustainable design practices. California’s emphasis on green building standards and eco-conscious materials drives innovation in residential and commercial interiors. Technology firms in Silicon Valley and entertainment hubs like Los Angeles also boost demand for creative, modern office spaces. The presence of leading design schools and studios contributes to steady project inflow, reinforcing the West’s role as a trendsetter in design aesthetics and sustainability.
Market Segmentations:
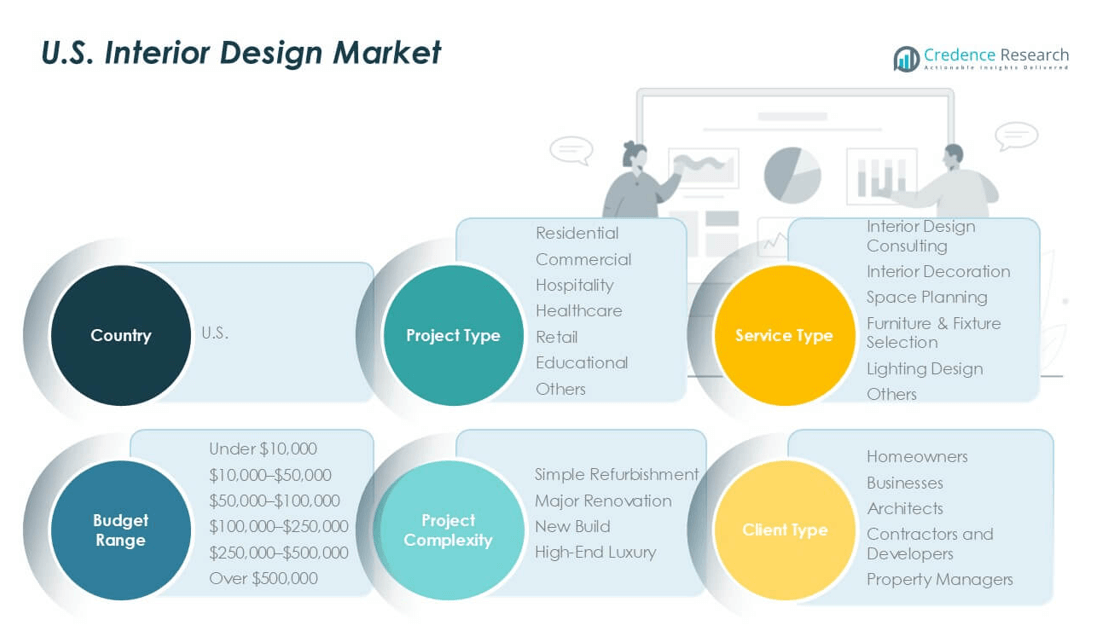
By Project Type
- Residential
- Commercial
- Hospitality
- Healthcare
- Retail
- Educational
- Others
By Service Type
- Interior Design Consulting
- Interior Decoration
- Space Planning
- Furniture & Fixture Selection
- Lighting Design
- Others
By Budget Range
- Under $10,000
- $10,000–$50,000
- $50,000–$100,000
- $100,000–$250,000
- $250,000–$500,000
- Over $500,000
By Project Complexity
- Simple Refurbishment
- Major Renovation
- New Build
- High-End Luxury
By Client Type
- Homeowners
- Businesses
- Architects
- Contractors and Developers
- Property Managers
By Geography
- Northeast
- Midwest
- South
- West
Competitive Landscape
The U.S. interior design market features a highly competitive landscape with a mix of global design firms, regional studios, and independent consultants. Leading companies such as Gensler, HOK, Perkins and Will, CannonDesign, and Corgan dominate through large-scale commercial, corporate, and institutional projects. These firms leverage advanced design technologies like Building Information Modeling (BIM) and 3D visualization to enhance project precision and client collaboration. Mid-sized firms and boutique studios focus on niche segments, including luxury residential design, sustainable interiors, and adaptive reuse projects. Strategic partnerships with furniture manufacturers, construction firms, and technology providers strengthen service integration and expand client reach. Companies increasingly emphasize sustainability, wellness design, and digital innovation to align with evolving client expectations and green building standards. Continuous investments in talent, design research, and smart-building integration are key differentiators that enable leading players to maintain market leadership and secure long-term contracts across residential and commercial sectors.
Key Player Analysis
- Gensler
- CannonDesign
- Corgan
- HOK
- Perkins and Will
Recent Developments
- In September 2024, Creaticity partnered with Konfor Furniture, a Turkish brand, to introduce premium space-saving designs tailored for urban Indian homes. This collaboration focuses on affordable luxury furniture that blends European elegance with Indian sensibilities.
- In September 2024, HomeLane acquired DesignCafe in a landmark deal through a 100% share swap. This acquisition was accompanied by Rs 225 crore in fresh funding from investors like Hero Enterprise. The merger positions HomeLane as a leader in India’s home interiors market.
- In June 2023, Asian Paints launched its “Beautiful Homes Studio” and the “Soft Decor 2023 Collection,” marking a significant step in luxury interior design. This initiative aims to redefine home aesthetics by offering a curated blend of premium design services and products tailored to modern consumer preferences.
- In May 2022, the interior design startup Havenly, known for its digital services, expanded into physical spaces with its new IRL services. This initiative allows Havenly's designers to visit clients' homes in person, conduct measurements, and ensure alignment with the client's vision before delivering a virtual design via digital layouts and 3D renderings.
- In March 2022, Modsy, a prominent female-led online interior design company, introduced a groundbreaking virtual remodeling service. This innovative offering uses 3D technology to enable customers to visualize and virtually explore every aspect of their remodeling project.
Report Coverage
The research report offers an in-depth analysis based on Project Type, Service Type, Budget Range, Project Complexity, Client Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Growing demand for sustainable and eco-friendly materials will shape future design preferences.
- Smart-home technologies will become integral to both residential and commercial design projects.
- Virtual reality and 3D visualization tools will enhance client engagement and decision-making.
- Increased adoption of modular and flexible layouts will support remote and hybrid work models.
- Luxury and high-end interior projects will expand in major metropolitan areas.
- The hospitality sector will prioritize experiential and wellness-focused design concepts.
- Green building certifications will influence material selection and design compliance.
- Integration of AI-driven design analytics will improve project efficiency and customization.
- Collaboration between architects, contractors, and designers will strengthen turnkey service demand.
- Rising urban development in southern and western states will continue to drive market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Home Renovation and Remodeling Activities
Increasing investments by homeowners in modernizing and upgrading interiors, driven by remote work trends and a desire for energy-efficient, comfortable living spaces, are fueling demand for interior design services across the U.S.
Commercial and Hospitality Sector Expansion
Ongoing investments in office modernization, coworking spaces, hotels, and restaurants are boosting demand for professional interior design, as businesses seek to enhance brand identity, employee well-being, and guest experiences.
Technological Advancements in Design and Visualization
The adoption of digital tools such as BIM, 3D rendering, and AR/VR platforms is streamlining design processes, improving client engagement, and enabling more precise, customized interior solutions.
Adoption of Sustainable and Eco-Friendly Design Practices
Growing consumer and regulatory emphasis on sustainability is driving demand for interiors that incorporate recycled materials, energy-efficient lighting, and green certifications, positioning eco-friendly design as a key market growth lever.
Integration of Smart and Connected Interiors
The increasing penetration of smart-home technologies and IoT-enabled systems in both residential and commercial spaces is creating new opportunities for interior designers to deliver tech-integrated, future-ready environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. interior design market?
At what Compound Annual Growth Rate is the U.S. Interior Design market projected to grow between 2025 and 2032?
What are the key factors driving market growth?
Which regions dominate the U.S. interior design market?
What are the main challenges facing the U.S. interior design market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Budget Range
- 1.2.1 Under $10,000
- 1.2.2 $10,000–$50,000
- 1.2.3 $50,000–$100,000
- 1.2.4 $100,000–$250,000
- 1.2.5 $250,000–$500,000
- 1.2.6 Over $500,000
- 1.3 By Project Type
- 1.3.1 Residential
- 1.3.2 Commercial
- 1.3.3 Hospitality
- 1.3.4 Healthcare
- 1.3.5 Retail
- 1.3.6 Educational
- 1.3.7 Others
- 1.4 By Service Type
- 1.4.1 Interior Design Consulting
- 1.4.2 Interior Decoration
- 1.4.3 Space Planning
- 1.4.4 Furniture & Fixture Selection
- 1.4.5 Lighting Design
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 37,664.63 million → 2032: USD 52,197.52 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Interior Design Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Interior Design Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Interior Design Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Interior Design Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Interior Design Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Interior Design Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Interior Design Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Interior Design Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 37,664.63 million → 2032: USD 52,197.52 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Interior Design Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Budget Range - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Under $10,000
- 12.3.7.2 $10,000–$50,000
- 12.3.7.3 $50,000–$100,000
- 12.3.7.4 $100,000–$250,000
- 12.3.7.5 $250,000–$500,000
- 12.3.7.6 Over $500,000
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Project Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.7.3 Hospitality
- 12.4.7.4 Healthcare
- 12.4.7.5 Retail
- 12.4.7.6 Educational
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Service Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Interior Design Consulting
- 12.5.7.2 Interior Decoration
- 12.5.7.3 Space Planning
- 12.5.7.4 Furniture & Fixture Selection
- 12.5.7.5 Lighting Design
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Interior Design Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 U.S. Interior Design Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 U.S. Interior Design Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Gensler
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 HOK
- 17.4 Perkins and Will
- 17.5 CannonDesign
- 17.6 Corgan
- 17.7 IA Interior Architects
- 17.8 Stantec
- 17.9 Nelson Worldwide
- 17.10 HKS
- 17.11 SmithGroup
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

