
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| U.S. Managed Services Market Size 2023 | USD 89,635.08 million |
| U.S. Managed Services Market, CAGR | 7.12% |
| U.S. Managed Services Market Size 2032 | USD 166,430.68 million |
Market Overview
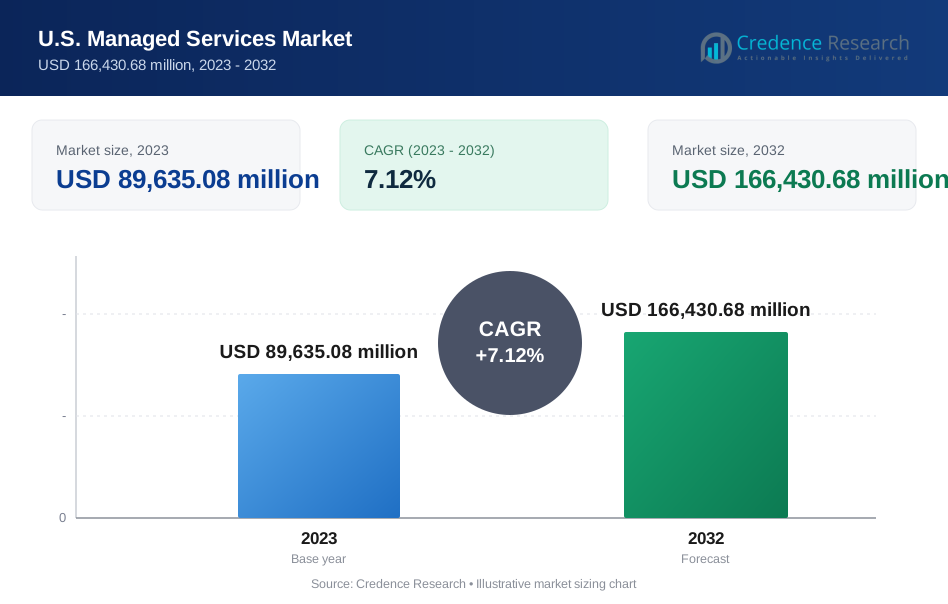
The U.S. Managed Services Market is projected to grow from USD 89,635.08 million in 2023 to USD 166,430.68 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.12%.
The U.S. managed services market is driven by the growing demand for cost-effective IT solutions, with businesses seeking to reduce operational costs while ensuring scalability and efficiency. The increasing adoption of cloud computing, along with the rise in cybersecurity threats, has fueled the need for managed services to safeguard data and maintain business continuity. Furthermore, the shift towards remote work and the need for efficient IT management across distributed environments have contributed to market growth. Key trends include the integration of Artificial Intelligence (AI) and automation in managed services, enhancing operational efficiency and providing proactive solutions. The rise of data analytics and the Internet of Things (IoT) also drives the demand for managed services, as businesses seek to leverage these technologies for better decision-making and performance optimization. The ongoing digital transformation across industries continues to be a significant trend, supporting the expansion of the managed services market.
The U.S. managed services market is characterized by strong regional growth, driven by the increasing demand for cloud computing, cybersecurity, and IT infrastructure management across various sectors. Key players in the market include industry giants like IBM Corporation, Microsoft Corporation, and Cisco Systems, Inc., who lead with their comprehensive service offerings in managed IT infrastructure, network solutions, and cybersecurity. Other significant players such as Google LLC, DXC Technology, and Cognizant provide specialized services ranging from cloud computing to data analytics, further contributing to market expansion. Additionally, regional players like GTT Communications, Lumen Technologies, and Secureworks offer targeted solutions catering to specific business needs, while smaller firms like MetTel and Ascend Technologies provide customized services. As businesses in the U.S. continue to embrace digital transformation, these key players play a critical role in driving innovation and delivering tailored managed services to meet evolving demands.
Market Insights
- The U.S. managed services market is valued at USD 89,635.08 million in 2023 and is projected to reach USD 1,66,430.68 million by 2032, growing at a CAGR of 7.12%.
- Increased demand for cloud-based solutions and digital transformation is driving market growth.
- The integration of AI and automation in managed services is enhancing efficiency and service delivery.
- Cybersecurity concerns are prompting businesses to seek advanced security solutions, boosting demand for managed security services.
- Key players include IBM, Microsoft, Cisco, Google, DXC Technology, and Cognizant, with competition focused on innovation and service diversification.
- The Western U.S. leads in market share, driven by its technology-centric economy, while the Southern and Northeastern U.S. are also growing markets.
- Challenges include pricing pressure from increased competition and the complexity of managing diverse IT environments across industries.
Market Drivers
Increasing Demand for Cost-Effective IT Solutions
One of the primary drivers of the U.S. managed services market is the growing demand for cost-effective IT solutions. Businesses are increasingly seeking to minimize operational costs while maintaining high-quality service and scalability. By outsourcing IT management, companies can reduce the need for in-house staff, thus saving on salaries, training, and infrastructure investments. For instance, a survey by Deloitte found that 59% of U.S. businesses are outsourcing IT services to reduce costs and improve efficiency. Managed services offer a predictable pricing model, allowing businesses to budget more effectively while accessing expert IT resources without the high capital expenditure associated with traditional IT departments.
Rise in Cybersecurity Threats
The escalation of cybersecurity threats has significantly influenced the U.S. managed services market. As cyberattacks become more sophisticated and frequent, businesses require advanced security measures to protect sensitive data and ensure business continuity. Managed service providers (MSPs) offer robust cybersecurity solutions, including threat detection, vulnerability management, and compliance with data protection regulations. For instance, the 2024 Report on the Cybersecurity Posture of the United States highlighted that U.S. organizations face an average of 1,300 weekly cyberattacks, emphasizing the need for advanced cybersecurity measures. With MSPs providing around-the-clock monitoring, businesses can better mitigate risks, safeguard critical systems, and avoid costly security breaches, making cybersecurity a top priority for managed services adoption.
Growth of Cloud Computing and Remote Work
The widespread adoption of cloud computing and the shift towards remote work have further propelled the demand for managed services in the U.S. Cloud-based solutions allow businesses to scale operations rapidly, while remote work introduces new complexities in IT management. Managed services provide essential support, including cloud infrastructure management, data storage, backup, and remote IT assistance. As businesses increasingly rely on cloud platforms, MSPs enable them to optimize their cloud environments and maintain operational efficiency across distributed teams, driving sustained growth in the managed services market.
Digital Transformation and Technological Advancements
Ongoing digital transformation across industries is a key factor driving the U.S. managed services market. As businesses adopt emerging technologies such as Artificial Intelligence (AI), automation, and the Internet of Things (IoT), the complexity of IT management increases. Managed services providers help companies integrate these technologies seamlessly, ensuring optimal performance and reducing downtime. Additionally, MSPs offer services such as data analytics and system optimization, empowering businesses to make data-driven decisions and enhance their competitive edge, further fueling the market's growth.
Market Trends
Integration of Artificial Intelligence (AI) and Automation
A key trend in the U.S. managed services market is the increasing integration of Artificial Intelligence (AI) and automation into service offerings. AI technologies are being used to enhance service delivery by enabling predictive maintenance, automated troubleshooting, and more accurate decision-making. Automation tools help streamline routine tasks, reducing human error and increasing operational efficiency. Managed service providers (MSPs) are leveraging AI-driven solutions to provide proactive services, offering faster resolution times and optimizing resource management, which leads to improved customer satisfaction and reduced operational costs.
Growing Demand for Cloud-Based Managed Services
As more businesses move their operations to the cloud, there is a rising demand for cloud-based managed services. Companies are increasingly relying on cloud infrastructure for scalability, flexibility, and cost efficiency. MSPs are responding to this shift by offering comprehensive cloud management services, including cloud migration, cloud security, and ongoing support for hybrid and multi-cloud environments. This trend allows businesses to focus on core operations while leaving the complexities of cloud infrastructure management to expert service providers, further driving the growth of managed services.
Focus on Cybersecurity Solutions
With the increase in cybersecurity threats, there is a strong trend towards MSPs providing advanced cybersecurity solutions. Businesses are becoming more aware of the risks associated with data breaches, ransomware, and other cyber threats. For instance, the 2024 Report on the Cybersecurity Posture of the United States highlighted that U.S. organizations face an average of 1,300 weekly cyberattacks, emphasizing the need for advanced cybersecurity measures. As a result, MSPs are enhancing their service offerings with cybersecurity services such as threat detection, risk assessment, vulnerability management, and compliance support. Many service providers are now integrating security-as-a-service solutions, providing 24/7 monitoring and rapid response to cyber incidents, helping businesses to mitigate potential risks and meet regulatory requirements.
Emphasis on Data Analytics and Business Intelligence
The growing importance of data analytics and business intelligence is another significant trend in the U.S. managed services market. Businesses are increasingly leveraging data to drive decision-making, improve customer experiences, and optimize operations. MSPs are offering data analytics and business intelligence services, helping organizations collect, analyze, and derive actionable insights from their data. This trend enables businesses to enhance their competitive advantage by making data-driven decisions while ensuring that data management, storage, and processing are efficiently handled by trusted managed service providers.
Market Challenges Analysis
Increasing Competition and Price Pressure
A significant challenge facing the U.S. managed services market is the growing competition among service providers, which has led to price pressure. As the market becomes more saturated, businesses have more options to choose from, making it difficult for managed service providers (MSPs) to differentiate themselves. In order to stay competitive, MSPs are often forced to lower their prices, which can impact their profitability. Additionally, new entrants offering similar services at lower rates further intensify the competition. This pricing pressure may also lead to a reduction in the quality of services offered, as some providers might cut corners to maintain their market share, ultimately affecting customer satisfaction and retention.
Complexity of IT Environments and Evolving Technology Needs
Another key challenge is the increasing complexity of IT environments and the constant evolution of technology needs. As businesses continue to adopt newer technologies like Artificial Intelligence (AI), the Internet of Things (IoT), and advanced data analytics, the demands placed on managed service providers are growing. For instance, a report highlighted that the complexity of IT environments in large organizations is increasing, with many companies managing thousands of interconnected applications and databases. MSPs must continuously upgrade their knowledge and capabilities to keep up with these rapid changes, which requires significant investment in training, research, and development. Additionally, businesses often operate in hybrid environments, which combine on-premise systems with cloud infrastructure, further complicating IT management. Providers must offer seamless integration and support for these increasingly complex systems, creating an ongoing challenge to maintain high service standards while meeting diverse and dynamic client needs.
Market Opportunities
The U.S. managed services market presents significant opportunities driven by the increasing demand for digital transformation and cloud-based solutions. As businesses continue to migrate to cloud platforms, there is a growing need for specialized services to manage and optimize these environments. Managed service providers (MSPs) can capitalize on this opportunity by offering comprehensive cloud management, security, and data migration services. Furthermore, businesses across various industries are seeking to leverage the benefits of hybrid and multi-cloud infrastructures, presenting MSPs with the opportunity to offer tailored solutions that meet the unique needs of each organization. This trend is expected to continue as more businesses move toward flexible and scalable cloud environments to enhance operational efficiency.
Another key opportunity for growth lies in the increasing focus on cybersecurity. With the rising frequency and sophistication of cyberattacks, businesses are prioritizing the protection of their digital assets. MSPs can tap into this market by providing advanced cybersecurity services, including continuous monitoring, threat detection, risk management, and compliance assistance. Offering cybersecurity-as-a-service is becoming a crucial part of many MSP portfolios, providing businesses with the expertise and resources to safeguard sensitive data and ensure business continuity. Additionally, as the adoption of IoT, AI, and machine learning continues to rise, MSPs can expand their offerings by integrating these technologies into their managed services, helping businesses optimize operations, improve decision-making, and stay competitive in an increasingly data-driven market. These trends present a wealth of opportunities for MSPs to expand their service offerings and capture a larger share of the growing market.
Market Segmentation Analysis:
By Service Type:
The U.S. managed services market can be segmented by service type into several key areas, each catering to specific business needs. The Managed IT Infrastructure & Data Center segment is vital, as businesses seek outsourced services for the management of their data centers and IT infrastructure, reducing operational costs while improving scalability. Managed Network services, which include network monitoring and optimization, are increasingly essential for businesses to ensure seamless connectivity and performance. Another critical segment, Managed Communication & Collaboration, addresses the need for reliable and secure communication tools such as video conferencing, email management, and collaborative platforms. The Managed Information segment focuses on data management, storage, and processing, while Managed Security services are in high demand due to increasing cybersecurity threats, offering advanced protection against data breaches and cyberattacks. The Others segment includes specialized services that cater to niche markets, such as cloud migration and disaster recovery solutions. These service types are essential as businesses look for comprehensive IT solutions that ensure efficiency, security, and scalability.
By Deployment Type:
In terms of deployment type, the U.S. managed services market is split into On-premise and Cloud solutions. The On-premise segment remains crucial for organizations that prefer to keep their infrastructure within their own premises due to regulatory requirements or security concerns. These businesses typically require on-site managed services for their IT systems, networks, and security. However, the Cloud segment is experiencing rapid growth as businesses increasingly adopt cloud-based solutions for scalability, flexibility, and cost efficiency. Cloud deployments enable organizations to offload their infrastructure management to third-party providers, reducing the need for in-house IT resources while ensuring access to the latest technologies. As businesses increasingly embrace cloud-first strategies, the demand for managed cloud services such as data storage, disaster recovery, and cloud security continues to rise, driving the expansion of this segment. The shift towards cloud deployments is expected to dominate the market, offering businesses more agile, cost-effective, and scalable solutions.
Segments:
Based on Service Type:
- Managed IT Infrastructure & Data Center
- Managed Network
- Managed Communication & Collaboration
- Managed Information
- Managed Security
- Others
Based on Deployment Type:
- On-premise
- Cloud
Based on Enterprise Size:
- Large Enterprises
- SME’s
Based on End User:
- IT & Telecom
- BFSI
- Manufacturing
- Retail
- Government
- Others
Based on the Geography:
- Western United States
- Midwestern United States
- Southern United States
- Northeastern United States
Regional Analysis
Western United States
The Western United States holds the largest market share, accounting for approximately 35% of the total market. The Western United States is a critical hub for the managed services market, primarily due to its strong technology infrastructure and high concentration of businesses in the tech, entertainment, and healthcare sectors. The demand for cloud-based services, particularly cloud infrastructure management and managed IT services, is considerable, as businesses seek scalability and flexibility. In addition, the managed security market is thriving in the region as companies face increasing cybersecurity threats. With major cities like San Francisco, Los Angeles, and Seattle driving innovation, businesses in the Western U.S. are early adopters of cutting-edge technologies such as Artificial Intelligence (AI) and machine learning, further propelling the demand for advanced managed services.
Midwestern United States
The Midwestern United States represents a growing market for managed services, contributing approximately 25% to the overall market share. This region is characterized by a strong presence of manufacturing, healthcare, and financial services sectors, all of which increasingly rely on managed services for operational efficiency and security. The adoption of cloud technologies is steadily increasing in the Midwest, though on-premise solutions still hold significant importance for many businesses due to industry-specific requirements. The demand for managed services is expected to rise as businesses modernize their IT infrastructure and embrace digital transformation. Moreover, MSPs in the Midwest are leveraging emerging technologies to provide tailored solutions for these traditional industries, driving market growth.
Southern and Northeastern United States
The Southern United States and Northeastern United States are both key players in the managed services market, with the Southern U.S. holding about 20% of the market share and the Northeastern U.S. contributing roughly 20% as well. The Southern U.S. is witnessing a surge in demand for managed services, especially in sectors such as energy, agriculture, and logistics, which rely heavily on efficient IT management and security solutions. The Northeastern U.S., with its large financial services sector and academic institutions, is also a significant market for managed services. The region has seen substantial investments in cybersecurity and IT infrastructure management, with businesses in finance and education adopting cloud-based solutions to stay competitive. Both regions continue to experience growth in demand for managed network services, managed security, and cloud services as organizations focus on digital transformation and business continuity.
Key Player Analysis
- IBM Corporation
- Microsoft Corporation
- Cisco Systems, Inc.
- Google LLC
- DXC Technology
- GTT Communications
- Lumen Technologies
- Cognizant
- Secureworks
- Hughes Network System
- MetTel
- Intact Technology
- Corsica Technologies
- EXC Managed Services
- Ascend Technologies
- Others
Competitive Analysis
The U.S. managed services market is highly competitive, with several leading players driving innovation and shaping industry trends. IBM Corporation, Microsoft Corporation, Cisco Systems, Inc., Google LLC, DXC Technology, GTT Communications, Lumen Technologies, Cognizant, Secureworks, Hughes Network System, MetTel, Intact Technology, Corsica Technologies, EXC Managed Services, and Ascend Technologies are key players in this space. Companies in the market focus on providing managed IT infrastructure, cloud services, cybersecurity, and network management to cater to the growing demand for digital transformation. Competition is primarily driven by service differentiation, with providers focusing on specialized services to meet the unique needs of various industries, such as finance, healthcare, and manufacturing. Leading players emphasize innovation through the integration of advanced technologies like Artificial Intelligence (AI), machine learning, and automation to enhance service delivery and improve efficiency. Cloud-based solutions, particularly in the areas of data storage, disaster recovery, and business continuity, have become critical offerings in the competitive landscape. Additionally, as businesses increasingly prioritize cybersecurity, providers are developing robust, integrated security solutions to protect sensitive data and networks. With the increasing complexity of IT environments, companies must invest in scalable and customizable solutions to attract and retain clients. Moreover, pricing strategies are an important factor, as many players look to offer cost-effective solutions without compromising on service quality. The competitive dynamics in this market continue to evolve, as firms focus on expanding their portfolios and building long-term customer relationships.
Recent Developments
- In January 2024, Accenture acquired NaviSite to strengthen its managed services offerings, particularly in application and infrastructure management. The acquisition will enhance Accenture’s ability to assist US and Canadian clients in modernizing their digital infrastructure, focusing on AI, cloud, and data-driven solutions for digital transformation.
- In September 2024, TCS launched two AI-powered cybersecurity solutions - Managed Detection and Response (MDR) and Secure Cloud Foundation - in collaboration with Google Cloud. The MDR service was intended to offer continuous, managed threat detection and response, while Secure Cloud Foundation aimed to enhance cloud security posture and governance across hybrid environments. Both solutions leverage Google Cloud’s security tools to provide proactive enterprise protection.
- In June 2024, DXC Technology and Dell partnered to establish Enterprise Intelligence Services (EIS). This service aimed to improve managed services by combining artificial intelligence, data analytics, and cloud technology. EIS’s multi-cloud strategy was expected to help organizations streamline operations, make smarter decisions, and improve customer experiences, proving DXC’s position as the leader in managed multi-cloud solutions.
- In October 2023, technology services provider Logicalis launched an Intelligent Connectivity suite that includes solutions such as SASE, SSE, SD-WAN, and Private 5G powered by Cisco Systems, Inc. This will enable Logicalis customers to access digitally managed services developed using Cisco technology and supported by the Logicalis Digital Fabric Platform.
- In September 2023, communications & technology solution provider Cloud5 Communications launched its new managed services division. The division is designed to support the IT-related requirements & challenges in various markets, such as the hospitality industry, student housing, and senior living, among others. This division will assist consumers in efficiently managing IT operations, technology infrastructures, and security.
- In May 2023, Alfar Capital and Walter Capital Partners completed the acquisition of MSP Corp, a managed IT service provider in Canada. The MSP Corp would merge with Groupe Access, an MSP of IT and cybersecurity solutions. The acquisition would help company to deliver cutting-edge solutions and strengthen its position in Canada.
- In January 2023, Rackspace Technology, a multi-cloud technology solutions provider, launched Rackspace Technology Modern Operations, a managed service for public cloud for customers across Azure, AWS, and GCP. The service will provide benefits including 24x7x365 managed support, cloud expertise, cloud resiliency, and innovation with cloud services which help the company’s customers manage complex cloud environments.
Market Concentration & Characteristics
The U.S. managed services market is characterized by moderate concentration, with a mix of large, well-established players and numerous smaller, niche providers. Large companies, often with global reach, dominate the market, offering comprehensive, end-to-end solutions across various industries, including cloud computing, cybersecurity, and IT infrastructure management. These major players leverage their vast resources, advanced technologies, and established customer bases to maintain a competitive edge. However, the market also includes a significant number of smaller, specialized managed service providers (MSPs) that focus on specific sectors or offer tailored solutions, which helps foster innovation and flexibility. Market characteristics reflect a shift toward highly scalable, cloud-based services, with increasing demand for managed security and network solutions as organizations face growing cybersecurity threats. Automation, artificial intelligence (AI), and machine learning are becoming integral to service offerings, enabling providers to improve operational efficiency and enhance service delivery. As businesses increasingly adopt digital transformation strategies, the demand for managed services is expected to continue growing, with providers needing to adapt to the evolving technology landscape. Additionally, there is an ongoing trend toward service diversification, with MSPs offering specialized solutions such as disaster recovery, compliance assistance, and data analytics. This dynamic and competitive environment encourages both innovation and collaboration, driving the evolution of managed services in the U.S. market.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Deployment Type, Enterprise Size, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The U.S. managed services market is expected to continue its growth, driven by increasing demand for cloud-based solutions and digital transformation.
- Cybersecurity services will remain a key focus area, with organizations prioritizing protection against data breaches and cyberattacks.
- The integration of AI and automation in managed services will enhance operational efficiency and service delivery, driving market growth.
- Businesses will increasingly adopt managed security services to safeguard sensitive data and ensure compliance with regulatory requirements.
- Cloud computing will dominate, with more companies shifting to cloud-based infrastructure management and data storage solutions.
- Managed network services will see greater demand as organizations seek optimized and secure network solutions to support remote work and digital operations.
- The shift towards subscription-based models will provide businesses with more flexible and cost-effective managed service offerings.
- Small and medium-sized enterprises (SMEs) will increasingly turn to managed service providers to access enterprise-grade IT solutions without significant investment.
- The demand for specialized managed services, such as disaster recovery and compliance management, will grow across various industries.
- Key players will continue to innovate through partnerships, acquisitions, and investments in emerging technologies to stay competitive in a rapidly evolving market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Managed Services market?
What factors are driving the growth of the U.S. Managed Services market?
What are the key segments within the U.S. Managed Services market?
Who are the major players in the U.S. Managed Services market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Managed Services Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 U.S. Managed Services Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 89,635.08 million → 2032: USD 166,430.68 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Managed Services Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Managed Services Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Managed Services Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 U.S. Managed Services Drivers
- 3.3 U.S. Managed Services Restraints & Challenges
- 3.4 U.S. Managed Services Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Managed Services Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Managed Services Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Managed Services category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Managed Services Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. U.S. Managed Services Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2023)
- 5.1.2 Export Volume by Destination Country (2023) (Where Applicable)
- 5.1.3 Import Value by Source Country (2023)
- 5.1.4 Import Volume by Source Country (2023) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to U.S. Managed Services in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Managed Services Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 U.S. Managed Services Share Analysis – 2023
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 U.S. Managed Services Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Managed Services (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in U.S. Managed Services
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. U.S. Managed Services – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. U.S. Managed Services – Priority Domestic Market 1
Chapter 10. U.S. Managed Services – Priority Domestic Market 2
Chapter 11. U.S. Managed Services – Priority Domestic Market 3
Chapter 12. U.S. Managed Services – Priority Domestic Market 4
Chapter 13. U.S. Managed Services Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
