
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| U.S. Nasal Spray Market Size 2024 | USD 10425 Million |
| U.S. Nasal Spray Market, CAGR | 6.6% |
| U.S. Nasal Spray Market Size 2032 | USD 17383.35 Million |
Market Overview:
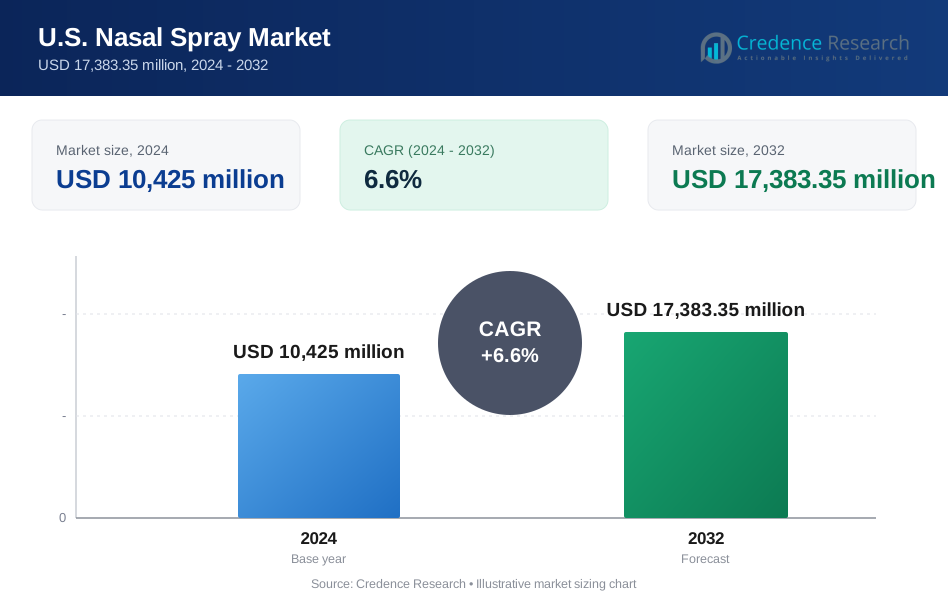
The U.S. Nasal Spray Market is projected to grow from USD 10425 million in 2024 to an estimated USD 17383.35 million by 2032, with a compound annual growth rate (CAGR) of 6.6% from 2024 to 2032.
Key drivers fueling the growth of the U.S. nasal spray market include the surging incidence of respiratory conditions such as seasonal allergies, sinusitis, and asthma, which affect millions across the country annually. The convenience factor of nasal sprays, offering rapid symptom relief and direct drug delivery to the affected area, has significantly enhanced their appeal over traditional oral medications. Innovations in drug formulations, particularly in areas like corticosteroids, decongestants, and antihistamines, have made nasal sprays a preferred choice among consumers seeking fast-acting relief. Additionally, the growing trend toward self-medication and the widespread availability of OTC options have bolstered consumer demand. Recent advancements in nasal spray applications, such as delivering vaccines, pain relief, and other systemic treatments via the nasal route, are expanding their use beyond respiratory care, offering further growth opportunities for pharmaceutical companies.
From a regional perspective, the U.S. nasal spray market exhibits varying growth patterns. The Northeast and West Coast regions lead the market, largely due to higher population densities, greater healthcare access, and increased exposure to environmental allergens like pollen and pollution. These areas also tend to have a higher incidence of chronic respiratory conditions, driving demand for both OTC and prescription nasal sprays. The Midwest and Southern regions are emerging as significant markets as well, driven by growing consumer awareness and the rising prevalence of respiratory issues. Expanding healthcare infrastructure in these regions, coupled with a broader range of OTC options in retail and online markets, supports strong growth potential. Overall, the U.S. nasal spray market is set to experience robust growth across both urban and rural areas, with heightened demand expected in metropolitan regions.
Market Drivers:
Increasing Prevalence of Respiratory Disorders:
One of the primary drivers of the U.S. nasal spray market is the rising prevalence of respiratory disorders, including allergic rhinitis, sinusitis, asthma, and nasal congestion. These conditions affect millions of Americans each year, and the increasing urbanization and industrialization in many parts of the U.S. have worsened air quality, contributing to the rise of these health issues. Environmental allergens such as pollen, dust, and pollution are prevalent in both urban and rural areas, leading to a higher incidence of respiratory conditions. Nasal sprays offer a convenient, fast-acting solution for relieving symptoms, making them a preferred choice for patients and healthcare providers alike.
Growing Consumer Preference for Self-Medication:
The trend toward self-medication is another significant driver of the U.S. nasal spray market. As consumers increasingly seek quick and accessible treatment options for common ailments, over-the-counter (OTC) nasal sprays have gained popularity. These products are easily available in pharmacies, supermarkets, and online platforms, offering individuals the flexibility to manage mild to moderate symptoms without the need for a doctor’s prescription. For instance, in September 2024, FluMist, a needle-free nasal spray, was approved to be self-administered by adults up to 49 years of age or administered by a parent/caregiver to children as young as 2 years old. In addition, the non-invasive nature of nasal sprays and their ease of use make them an attractive option for patients seeking immediate relief from conditions like nasal congestion, sinus pressure, or allergies. This shift toward self-care and consumer autonomy has fueled the demand for a broader range of OTC nasal spray options, encouraging pharmaceutical companies to invest in expanding their product portfolios.
Advances in Drug Formulations and Delivery Methods:
Technological advancements in drug formulations and nasal delivery methods have further driven the growth of the U.S. nasal spray market. Innovations such as corticosteroids, antihistamines, decongestants, and saline-based sprays have improved the efficacy and safety profiles of nasal spray products. For example, researchers at Brigham and Women's Hospital have developed a pathogen capture and neutralizing spray (PCANS) that coats the nasal cavity, capturing large respiratory droplets and effectively neutralizing almost 100% of all viruses and bacteria tested, including Influenza, SARS-CoV-2, RSV, adenovirus, and K Pneumonia. Additionally, the development of preservative-free formulations has addressed concerns related to potential irritation from long-term use. These advancements have allowed nasal sprays to offer more targeted and sustained relief for various respiratory and non-respiratory conditions. Furthermore, ongoing research into using nasal sprays for systemic drug delivery, such as vaccines, pain management, and neurological treatments, is expanding the potential applications of nasal spray technology, opening up new growth avenues for the market.
Expanding Healthcare Access and Rising Awareness:
Improved access to healthcare services, coupled with rising awareness of respiratory conditions and their treatments, is also a key market driver. As healthcare infrastructure continues to expand in both urban and rural areas of the U.S., more individuals have access to treatments such as nasal sprays. This is particularly true in regions with a high incidence of allergies and respiratory issues, where awareness campaigns have helped educate the public on the benefits of early diagnosis and treatment. Moreover, the increasing availability of nasal sprays through various distribution channels, including e-commerce, has made these products more accessible to a broader population, further boosting market growth. As a result, the U.S. nasal spray market is expected to continue expanding in the coming years, driven by these interconnected factors.
Market Trends:
Rise of Over-the-Counter (OTC) Nasal Sprays:
A prominent trend in the U.S. nasal spray market is the growing popularity of over-the-counter (OTC) products. As consumers increasingly prefer self-medication for mild to moderate respiratory issues, the demand for non-prescription nasal sprays has surged. This trend is fueled by the convenience and accessibility of OTC nasal sprays, which allow individuals to address symptoms like nasal congestion, allergies, and sinus discomfort without the need for a doctor's visit. The rise of e-commerce and retail pharmacy chains has further facilitated the widespread availability of these products. For instance, according to a study published in The Lancet Respiratory Medicine, OTC nasal sprays reduced the duration and severity of respiratory infections by around 20%, and also limited the number of days with severe symptoms and time off work.
Increasing Focus on Non-Drug Nasal Spray Options:
In recent years, there has been an increasing shift toward non-drug nasal spray formulations, reflecting consumer demand for more natural, less invasive treatments. Saline-based nasal sprays and those containing natural ingredients, such as essential oils and herbal extracts, have gained popularity as safe, daily-use options for maintaining nasal hygiene and relieving mild congestion. These products are often marketed as preventive solutions rather than therapeutic treatments, catering to health-conscious consumers who are looking for alternatives to medications. The trend toward non-drug nasal sprays is further amplified by growing awareness of the potential side effects of long-term use of medicated nasal sprays, such as rebound congestion. As a result, manufacturers are expanding their portfolios to include preservative-free, natural, and chemical-free nasal spray options.
Technological Advancements in Nasal Spray Devices:
Another key trend in the U.S. nasal spray market is the increasing integration of technology into nasal spray devices. Pharmaceutical companies are focusing on improving the design and functionality of nasal spray delivery systems to enhance the user experience and ensure precise dosing. This includes the development of metered-dose sprays that offer better control over medication delivery, reducing the risk of overuse or underuse. For instance, Aptar Pharma has introduced the APF Futurity™ nasal spray pump, which is the first fully recyclable nasal spray pump for preservative-free applications on the market. In addition, smart nasal sprays equipped with digital features, such as sensors and connectivity to mobile apps, are emerging in the market. These devices can track usage patterns, provide reminders for medication adherence, and even monitor symptom relief, offering a more personalized approach to nasal spray therapy. Such innovations are expected to drive growth as consumers seek more sophisticated and user-friendly treatment options.
Expanding Applications Beyond Respiratory Care:
The U.S. nasal spray market is also experiencing a trend toward expanding applications beyond traditional respiratory care. While nasal sprays are widely used for treating allergies, colds, and sinusitis, recent advancements in drug delivery technology have led to the exploration of nasal sprays for systemic treatments. For instance, nasal sprays are being developed for the administration of vaccines, pain management, and even neurological treatments, as the nasal route allows for quick absorption into the bloodstream. This expansion into new therapeutic areas is expected to open up significant growth opportunities for pharmaceutical companies. As research and development efforts continue to explore the full potential of nasal sprays as a drug delivery mechanism, the market is likely to see diversification in the types of conditions these products can address.
Market Restraints and Challenges:
Side Effects and Risk of Overuse:
One of the key restraints in the U.S. nasal spray market is the potential for side effects and the risk of overuse, particularly with medicated nasal sprays. Products containing decongestants, for example, can lead to a condition known as rebound congestion when used for extended periods. This causes nasal passages to become more congested after the medication wears off, leading to a cycle of dependence on the spray. Additionally, long-term use of corticosteroid-based nasal sprays can result in side effects such as nosebleeds, dryness, and irritation. These risks make healthcare professionals and consumers more cautious about frequent or prolonged use, which can limit the market's growth potential.
Regulatory Hurdles:
The U.S. nasal spray market also faces challenges in navigating complex regulatory frameworks. The approval process for new nasal spray products, especially those containing novel drug formulations or delivery mechanisms, can be lengthy and costly. Regulatory bodies such as the U.S. Food and Drug Administration (FDA) require extensive clinical trials to ensure safety and efficacy, which can delay product launches and increase development costs. For companies seeking to introduce innovative nasal spray applications, such as systemic drug delivery, navigating these regulatory pathways can be particularly challenging. This can act as a deterrent for smaller companies or startups entering the market, thereby limiting innovation and competition.
Consumer Misinformation and Lack of Awareness:
A further challenge in the U.S. nasal spray market is the issue of consumer misinformation and lack of awareness regarding the proper use of nasal sprays. Many consumers are unaware of the risks associated with overuse or incorrect usage of these products. Moreover, despite the growing market, some segments of the population remain unfamiliar with the benefits of nasal sprays compared to other treatment options. This lack of awareness can hinder the market’s full potential, particularly in regions where education and outreach efforts are limited.
Market Segmentation Analysis:
By Product Type, steroid sprays hold a significant share due to their effectiveness in treating inflammation and allergies, making them the preferred option for chronic conditions like allergic rhinitis. Antihistamine sprays are also widely used for nasal allergies, while decongestant sprays are popular for providing quick relief from nasal congestion. The "Others" category includes saline and non-drug formulations that are gaining traction among consumers seeking natural alternatives.
By Type, the market is divided into prescription and over-the-counter (OTC) nasal sprays. OTC sprays dominate the market, driven by consumer preference for self-medication and ease of access. However, prescription nasal sprays are critical for managing more severe conditions, especially in cases requiring corticosteroids or specialized treatments.
By Indication, allergic rhinitis and nasal congestion are the leading segments, reflecting the high prevalence of allergies and respiratory conditions in the U.S. Nasal allergies also contribute significantly to demand, as patients seek immediate and effective symptom relief.
By Distribution Channel, retail pharmacies hold the largest market share due to their wide accessibility. Hospital pharmacies play a key role for prescription products, while online pharmacies are rapidly growing, driven by convenience and the rise of e-commerce, offering consumers easy access to both OTC and prescription nasal sprays.
Segmentation:
By Product Type:
- Steroid Sprays
- Antihistamine Sprays
- Decongestant Sprays
- Others
By Type:
- Prescription
- Over-the-Counter
By Indication:
- Allergic Rhinitis
- Nasal Allergies
- Nasal Congestion
- Others
By Distribution Channel:
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
Regional Analysis:
Northeast Region
The Northeast region holds a significant share of the U.S. nasal spray market, driven by the high prevalence of respiratory issues and allergies, exacerbated by urbanization and fluctuating weather patterns. Cities such as New York, Boston, and Philadelphia face higher pollen counts and pollution, contributing to the increased use of nasal sprays for both allergy and congestion relief. This region also benefits from a well-developed healthcare infrastructure and widespread access to both prescription and over-the-counter (OTC) nasal sprays. The Northeast accounts for approximately 25% of the overall U.S. nasal spray market, making it one of the key regions for both consumer and prescription-driven sales.
West Coast Region
The West Coast region, including California, Washington, and Oregon, captures a substantial portion of the nasal spray market, contributing nearly 22% of the market share. The coastal geography, coupled with seasonal changes in air quality due to wildfire smoke and pollution, results in a higher demand for respiratory treatments such as nasal sprays. Major metropolitan areas like Los Angeles, San Francisco, and Seattle have higher population densities, further driving demand. Additionally, the region has seen growth in consumer interest in preservative-free and natural nasal spray products, aligning with the West Coast’s broader emphasis on health-conscious lifestyles and wellness trends.
Midwest Region
The Midwest region contributes around 18% to the U.S. nasal spray market, with a growing demand driven by seasonal allergies and cold winters, which often lead to an increase in respiratory issues. States such as Illinois, Michigan, and Ohio have substantial consumer bases that rely on nasal sprays for relief from sinus congestion and allergic rhinitis. While the Midwest has fewer densely populated areas compared to the Northeast or West Coast, its significant suburban and rural populations increasingly use nasal sprays due to improved healthcare accessibility and heightened awareness of OTC treatment options. Retail pharmacies and online platforms are key distribution channels for this region.
Southern Region
The Southern region, including states like Texas, Florida, and Georgia, accounts for about 20% of the U.S. nasal spray market. The region's warm, humid climate, combined with high pollen counts, contributes to a high prevalence of allergic rhinitis and sinusitis, particularly during spring and summer. Urban centers such as Houston, Miami, and Atlanta see strong demand for nasal sprays, both prescription and OTC, as patients seek relief from seasonal allergies. The region's expanding healthcare infrastructure and increasing awareness of allergy treatments have also boosted market growth. Furthermore, the availability of nasal sprays in large retail chains across the South has made these products more accessible to a broader population.
Key Player Analysis:
- AstraZeneca
- Bausch Health Companies Inc.
- Bayer AG
- Cipla
- EMERGENT
- GLENMARK PHARMACEUTICALS LTD.
- GSK plc.
- Hikma Pharmaceuticals PLC
- Johnson & Johnson Services
- Merck & Co.
- NeilMed Pharmaceuticals Inc.
- Neurelis
- Novartis AG
- Pfizer Inc.
- Sanofi
- The Procter & Gamble Company
- Viatris Inc.
Competitive Analysis:
The U.S. nasal spray market is highly competitive, with several key players vying for market share. Major pharmaceutical companies, such as GlaxoSmithKline, AstraZeneca, Pfizer, and Sanofi, dominate the market through their established brands and extensive distribution networks. These companies leverage their strong research and development capabilities to continuously innovate and expand their product portfolios, particularly in medicated nasal sprays. In addition to large pharmaceutical firms, several smaller companies and generics manufacturers compete by offering more affordable, over-the-counter (OTC) options, increasing price competition within the market. The competitive landscape is also shaped by increasing consumer demand for non-drug formulations and natural products, leading companies like Xlear and NeilMed to gain traction with saline-based and preservative-free nasal sprays. Overall, innovation, brand recognition, and regulatory approvals remain critical factors that influence market position in this competitive environment.
Recent Developments:
- In February 2024, Lupin, a pharmaceutical company, introduced Cyanocobalamin Nasal Spray (500 mcg/spray) in the U.S., a generic equivalent to Nascobal Nasal Spray (500 mcg/spray) by Par Pharmaceutical, Inc.
- In March 2023, Pfizer, Inc. received U.S. Food and Drug Administration (FDA) approval for ZAVZPRET (zavegepant), the first and only calcitonin gene-related peptide (CGRP) receptor antagonist nasal spray for the acute treatment of migraines, with or without aura, in adults.
- In August 2022, Hikma Pharmaceuticals PLC launched RYALTRIS (olopatadine hydrochloride and mometasone furoate nasal spray) in the U.S. to treat symptoms of seasonal allergic rhinitis (SAR) in adults and pediatric patients aged 12 and older.
Market Concentration & Characteristics:
The U.S. nasal spray market is moderately concentrated, dominated by a few large pharmaceutical companies, including GlaxoSmithKline, AstraZeneca, and Sanofi, which hold significant market shares due to their strong product portfolios and extensive distribution networks. These companies benefit from established brand recognition, robust R&D capabilities, and regulatory expertise, enabling them to maintain leadership positions. However, the market also features competition from smaller players and generic manufacturers, particularly in the over-the-counter (OTC) segment, where price sensitivity is higher. Key market characteristics include a strong focus on innovation, with continuous advancements in drug formulations and delivery mechanisms. Additionally, the market is shaped by increasing consumer preference for non-drug, preservative-free, and natural nasal spray products. Regulatory compliance plays a critical role in market dynamics, as companies navigate stringent FDA requirements for approval. This blend of competition and regulatory oversight drives the market’s evolution, with a balance between established leaders and emerging players.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type, By Type, By Indication and By Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The U.S. nasal spray market is expected to witness robust growth driven by increasing prevalence of respiratory disorders like allergies and sinusitis.
- Advancements in drug formulations and delivery technologies, such as preservative-free sprays and metered-dose devices, will continue to attract consumer interest.
- Growing demand for over-the-counter (OTC) nasal sprays will remain a key driver, fueled by consumer preference for self-medication and convenience.
- Prescription nasal sprays targeting chronic conditions like allergic rhinitis and nasal polyps will see steady growth due to their effectiveness in long-term management.
- Expanding applications of nasal sprays for non-respiratory treatments, such as vaccines and pain relief, will open new market opportunities.
- Rising awareness of non-drug alternatives, including saline sprays and natural products, will cater to the increasing health-conscious consumer base.
- E-commerce and online pharmacies will play an increasingly critical role in distribution, offering easier access to both OTC and prescription products.
- Urban areas with higher air pollution and allergen exposure will continue to drive regional market growth, particularly in the Northeast and West Coast.
- Innovation in smart nasal spray devices with digital features will enhance patient compliance and personalized treatment options.
- Regulatory challenges and concerns about side effects from prolonged use of medicated sprays will remain key factors shaping market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the U.S. nasal spray market?
What are the key drivers of the U.S. nasal spray market?
Which regions lead the U.S. nasal spray market?
What are the biggest challenges for the nasal spray market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Nasal Spray Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. Nasal Spray Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 10,425 million → 2032: USD 17,383.35 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Nasal Spray Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Nasal Spray Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Nasal Spray Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. Nasal Spray Market Drivers
- 3.3 U.S. Nasal Spray Market Restraints & Challenges
- 3.4 U.S. Nasal Spray Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Nasal Spray Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Nasal Spray Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Nasal Spray category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Nasal Spray Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. Nasal Spray Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. Nasal Spray market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Nasal Spray Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. Nasal Spray Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. Nasal Spray Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Nasal Spray (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. Nasal Spray Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. Nasal Spray Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. Nasal Spray Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. Nasal Spray Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. Nasal Spray Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. Nasal Spray Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. Nasal Spray Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. Nasal Spray Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. Nasal Spray Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
