
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Pea Proteins Market Size 2024 | USD 650.6 million |
| U.S. Pea Proteins Market, CAGR | 12.36% |
| U.S. Pea Proteins Market Size 2032 | USD 1652.53 million |
Market Overview:
The U.S. Pea Proteins Market is projected to grow from USD 650.6 million in 2024 to an estimated USD 1,652.53 million by 2032, with a compound annual growth rate (CAGR) of 12.36% from 2024 to 2032.
The U.S. pea protein market is experiencing robust growth due to several key drivers. Increasing consumer demand for plant-based proteins is largely fueled by health-conscious individuals seeking alternatives that support muscle building, weight management, and overall wellness. Pea protein, being hypoallergenic, appeals to people with dietary restrictions, including those with gluten or soy allergies, further broadening its consumer base. Additionally, sustainability concerns are prompting more environmentally aware consumers to opt for plant-based proteins over animal-derived alternatives, as pea protein has a lower ecological footprint. Advancements in food processing technology have also enhanced the taste, texture, and functionality of pea protein, making it more versatile in a wide range of food products such as meat substitutes, dairy alternatives, and snacks.
Regionally, the U.S. is a dominant player in the North American pea protein market, driven by the presence of a well-established food industry and robust food processing sector. The demand for pea protein is particularly high in the U.S. due to increasing consumer awareness of health, sustainability, and dietary inclusivity. The country's efficient supply chain infrastructure ensures a steady and reliable supply of pea protein, supporting the growing market demand. The combination of a strong agricultural base, a sophisticated food manufacturing sector, and consumer preferences for plant-based, health-oriented products positions the U.S. as a leader in the market.
Market Insights:
- The U.S. Pea Proteins Market is projected to grow from USD 695.61 million in 2024 to USD 1,777.26 million by 2032, reflecting a CAGR of 12.44%.
- The market is fueled by increasing consumer demand for plant-based proteins, driven by health-conscious individuals seeking alternatives to animal proteins.
- Pea protein’s hypoallergenic properties make it an ideal choice for individuals with gluten or soy allergies, expanding its appeal to a wider consumer base.
- Environmental sustainability concerns are accelerating the shift toward pea protein as it has a lower ecological footprint compared to animal-based proteins.
- Advancements in food processing technologies have improved the taste, texture, and functionality of pea protein, making it more versatile across various food products.
- Regional growth in the U.S. is uneven, with North America holding the largest market share, driven by a strong food industry and consumer preference for plant-based diets.
- Supply chain disruptions, competitive pricing pressures, and regulatory uncertainties pose challenges, but they also present opportunities for innovation and market diversification.
Report scope
This reports segments are U.S. Pea Proteins Market as Follows;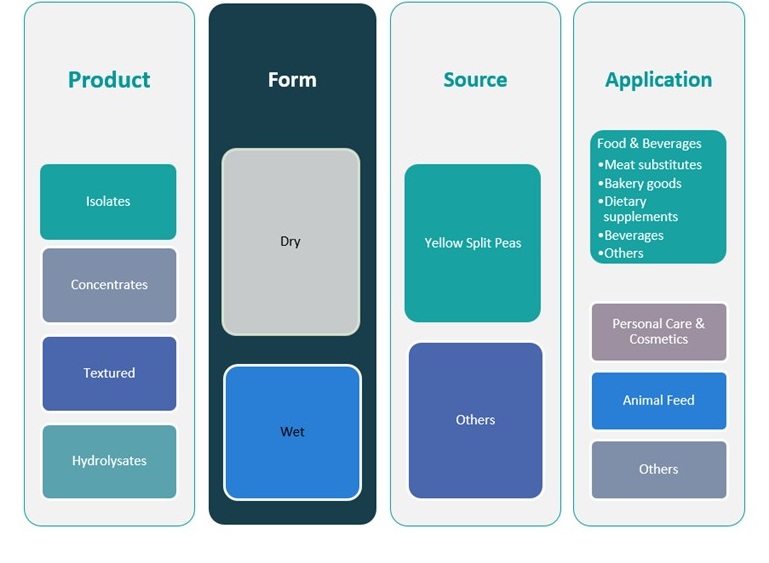
Market Drivers:
Health and Wellness Trends
One of the most significant drivers of growth in the U.S. pea protein market is the increasing consumer focus on health and wellness. As more individuals adopt plant-based diets for their numerous health benefits, including lower cholesterol levels, improved digestion, and enhanced heart health, pea protein has become a popular alternative to animal-derived proteins. The demand for functional foods and protein-rich snacks continues to rise, as consumers increasingly recognize the importance of protein in their daily diets for muscle building, satiety, and overall well-being. For example, companies like Puris have developed high-quality pea protein ingredients used in plant-based meats and beverages, showcasing its versatility in functional food applications. The growing trend toward plant-based protein sources aligns with the broader movement toward healthier, more sustainable eating habits, making pea protein an appealing option for health-conscious consumers.
Dietary Inclusivity and Allergen-Free Alternatives
Pea protein’s hypoallergenic properties further contribute to its growing demand. Unlike other plant-based proteins such as soy or wheat, pea protein is gluten-free and does not trigger common allergies, making it suitable for a wide range of dietary needs. This inclusivity is particularly important as the prevalence of food sensitivities continues to rise. With a growing number of consumers seeking alternatives to dairy, gluten, and soy-based products, pea protein serves as an excellent solution for individuals following specialized diets. As a result, pea protein is increasingly being used in a variety of food products, such as meat substitutes, dairy alternatives, and protein bars, further driving market growth.
Environmental Sustainability
Sustainability concerns are becoming a primary focus for many consumers, driving a shift toward more environmentally friendly food sources. Pea protein stands out as a sustainable alternative to animal-based proteins, requiring fewer natural resources such as water, land, and energy to produce. Its cultivation also results in lower greenhouse gas emissions, making it an attractive option for environmentally conscious consumers. As the food industry embraces sustainable practices, companies are incorporating pea protein into their product offerings to meet the growing demand for eco-friendly food options. This emphasis on sustainability is expected to continue fueling the growth of the pea protein market, as more individuals seek to reduce their environmental impact through the foods they consume.
Advancements in Food Technology
Advancements in food processing technologies have played a crucial role in expanding the use of pea protein in various applications. Improvements in extraction techniques have enhanced the taste, texture, and functionality of pea protein, allowing it to mimic the properties of animal-based proteins more effectively. For instance, advanced methods employed by companies like Benson Hill focus on breeding yellow peas with higher nutritional density and better flavor profiles using AI-powered platforms. These innovations have enabled manufacturers to incorporate pea protein into a wide array of food products, ranging from plant-based meat alternatives to dairy-free beverages and snacks. The growing versatility of pea protein, combined with increased consumer acceptance and demand for plant-based foods, positions it as a key ingredient in the future of food. As food technology continues to evolve, the scope for pea protein to replace traditional animal proteins in everyday food products will likely expand, further driving market growth.
Market Trends:
Product Innovation and Diversification
The U.S. pea protein market is witnessing a trend toward continuous product innovation and diversification. Manufacturers are developing new pea protein-based products to cater to a broader consumer base, including those seeking gluten-free, vegan, or allergen-free options. For instance, companies like Lightlife Foods have expanded their product lines to include plant-based burgers made with pea protein, aiming to provide meat alternatives that appeal to both vegetarians and flexitarians. This diversification not only meets the evolving preferences of consumers but also positions pea protein as a versatile ingredient in various food applications.
Strategic Partnerships and Collaborations
Strategic partnerships and collaborations are playing a pivotal role in the growth of the pea protein market. Companies are joining forces to enhance product offerings and expand market reach. For example, Lightlife Foods partnered with Bowlero Corporation to introduce plant-based burgers at bowling venues, increasing the accessibility of pea protein products to a wider audience. Such collaborations enable brands to leverage each other's strengths, resulting in innovative products that meet the demands of health-conscious consumers.
Expansion of Production Capabilities
To meet the rising demand for pea protein, companies are investing in expanding their production capabilities. For instance, Lightlife Foods, for instance, broke ground on a new food processing plant in Shelbyville, Indiana, with an investment of $310 million. This facility is expected to double the production capacity of plant-based meats, including those made with pea protein, to 60 million pounds annually. Such investments are crucial to ensure a steady supply of pea protein products, supporting the market's growth and the increasing consumer shift toward plant-based diets.
Integration of Pea Protein in Mainstream Products
Pea protein is increasingly being integrated into mainstream food products, reflecting its growing acceptance among general consumers. Major food manufacturers are incorporating pea protein into various items, from snacks to beverages, to meet the demand for protein-enriched foods. This trend aligns with the broader "protein mania" observed in grocery stores, where protein-enhanced products have become ubiquitous across all food categories. The inclusion of pea protein in everyday products signifies its transition from a niche ingredient to a mainstream component in the food industry.
Market Challenges Analysis:
Supply Chain Disruptions
The U.S. pea protein market has encountered significant supply chain challenges, particularly following the imposition of steep tariffs on Chinese imports in 2023. Chinese producers, who previously supplied over 96% of pea protein imports to major U.S. manufacturers, faced antidumping duties of 270% and countervailing duties of 340%. These measures led to price increases and prompted manufacturers to seek alternative protein sources, such as soy and rice.
Competitive Pricing Pressures
Domestic pea protein producers are undercut by low-priced Chinese imports, creating pricing challenges. In 2022, five U.S. purchasers of pea protein sourced 96.6% from China, with import costs averaging 52.3% below domestic prices. This disparity has led to reduced profit margins for U.S. producers, hindering their ability to compete effectively in the market.
Regulatory and Trade Uncertainties
The ongoing investigations by the U.S. International Trade Commission (ITC) and the Department of Commerce into allegations of Chinese dumping and subsidies have introduced a degree of uncertainty. Pending final determinations and potential imposition of import duties create challenges for producers in planning and forecasting, affecting long-term strategic decisions within the industry.
Quality and Safety Concerns
Recent studies have raised concerns about heavy metal contamination in protein powders, including those derived from peas. For instance, the Clean Label Project's study revealed that a significant percentage of protein powders, particularly plant-based ones, exceeded safety thresholds for lead, with pea-based powders showing significantly higher levels than whey-based products. Such findings pose potential health risks and may influence consumer perceptions and demand.
Market Opportunities:
The U.S. Pea Proteins Market presents significant growth opportunities, driven by the increasing consumer shift toward plant-based diets and rising health-consciousness. With the growing demand for vegan, vegetarian, and gluten-free options, pea protein offers a versatile and hypoallergenic alternative to animal-based proteins, catering to consumers with dietary restrictions. As plant-based food products, including meat substitutes, dairy alternatives, and protein-enriched snacks, continue to gain popularity, there is a considerable opportunity for market expansion. Furthermore, advancements in food processing technologies have improved the taste, texture, and functionality of pea protein, making it more appealing to a broader range of consumers. This progress, coupled with the increasing demand for sustainable and environmentally friendly ingredients, positions pea protein as a key player in the market for plant-based protein solutions.
In addition to the food and beverage sector, the U.S. Pea Proteins Market holds potential in personal care and cosmetics. Pea protein's moisturizing and strengthening properties are being increasingly utilized in hair care and skin care products, creating new avenues for growth. The animal feed sector is also expanding, with pea protein serving as an eco-friendly alternative to traditional animal feed ingredients. The growing trend toward sustainable agriculture and plant-based diets further fuels the demand for pea protein in this sector. Additionally, as research and development continue to improve the nutritional profile and functional properties of pea protein, new applications and markets are likely to emerge, enhancing the growth prospects for manufacturers and investors alike.
Market Segmentation Analysis:
By Product Segment:
The U.S. Pea Proteins Market includes isolates, concentrates, textured, and hydrolysates. Isolates lead the market due to their high protein content, ideal for protein-enriched foods and beverages. Concentrates are more cost-effective, used in snacks and bakery products. Textured pea proteins are popular in meat substitutes, providing a meat-like texture. Hydrolysates are utilized in dietary supplements for better digestibility.
By Application Segment:
The Food & Beverages segment dominates, with applications in meat substitutes, bakery goods, dietary supplements, and beverages. Personal Care & Cosmetics is growing due to pea protein’s moisturizing and strengthening benefits. The Animal Feed segment is expanding with plant-based feed alternatives. Others include niche applications in functional foods and pharmaceuticals.
By Form Segment:
Dry pea protein is widely used due to its longer shelf life and easy storage, ideal for powders and snacks. Wet pea proteins are used in ready-to-consume products like beverages and ready meals, where texture and consistency are essential.
By Source Segment:
Yellow Split Peas are the primary source of pea protein due to their high yield and protein content. Other pea varieties are used in specialty products, offering unique nutritional profiles for niche markets.
Segmentation:
By Product Segment:
- Isolates
- Concentrates
- Textured
- Hydrolysates
By Application Segment:
- Food & Beverages
- Meat substitutes
- Bakery goods
- Dietary supplements
- Beverages
- Others
- Personal Care & Cosmetics
- Animal Feed
- Others
By Form Segment:
- Dry
- Wet
By Source Segment:
- Yellow Split Peas
- others
Regional Analysis:
The U.S. Pea Proteins market is experiencing significant growth, driven by increasing consumer demand for plant-based protein sources. The market is segmented by regions, with each showcasing unique growth trajectories influenced by factors such as consumer preferences, industry trends, and regional economic conditions.
North America dominates the U.S. Pea Proteins market, accounting for the largest market share. The growing trend toward plant-based diets, driven by health-conscious consumers, and increasing vegan and vegetarian populations have been pivotal in shaping the demand for pea protein. Additionally, North America benefits from well-established production and distribution channels, fostering a stable supply chain. The region’s substantial investments in the food and beverage industry further contribute to the expansion of pea protein applications in plant-based foods, snacks, and supplements. As of the latest data, North America holds an estimated market share of 45% in the U.S. Pea Proteins market.
The Western U.S. is a key player within North America, particularly with its strong food innovation hubs in states like California and Oregon. These areas lead in the development and incorporation of plant-based proteins in various products, including dairy alternatives, meat substitutes, and protein-enriched foods. The region’s proximity to both agricultural resources and the trend-setting food industry also contributes to the increasing adoption of pea proteins.
The Midwest is another growing region for the U.S. Pea Proteins market, with states like Illinois, Iowa, and Nebraska playing an integral role in the production of peas. This region contributes significantly to the supply chain, with many pea farms supporting the production of pea protein isolates and concentrates. The Midwest’s agricultural infrastructure, combined with the expanding interest in sustainable and alternative protein sources, has boosted the demand for pea proteins in the region, contributing to its growing market share of approximately 25%.
In contrast, the Southern U.S. is witnessing a slower, but steady adoption of pea proteins, driven primarily by increasing awareness of plant-based food options. The region's food industry is diversifying, with greater incorporation of plant-based ingredients into mainstream products. The Southern U.S. holds a smaller market share of around 15%, but it is expected to witness steady growth due to shifting consumer attitudes and regional demand for health-conscious alternatives.
The Eastern U.S. is another significant market, contributing roughly 15% to the overall U.S. Pea Proteins market. States such as New York, New Jersey, and Pennsylvania are home to a rising number of health-conscious consumers and businesses focused on plant-based innovations, resulting in gradual market expansion.
Key Player Analysis:
- The Scoular Company
- DuPont de Nemours, Inc.
- Ingredion Incorporated
- Archer Daniels Midland Company
- Cargill, Incorporated
Competitive Analysis:
The U.S. Pea Proteins market is highly competitive, with key players focusing on product innovation, strategic partnerships, and expanding production capacities to cater to growing consumer demand for plant-based proteins. Major companies such as Cargill, Ingredion Incorporated, and Roquette Frères lead the market, leveraging their extensive distribution networks and established supply chains. These players focus on improving product quality and variety, offering pea protein isolates, concentrates, and textured pea proteins to meet diverse consumer needs across food and beverage, nutraceuticals, and animal feed sectors. Additionally, emerging players are making significant strides by offering specialized formulations and eco-friendly production processes, aiming to differentiate themselves in the market. The competitive landscape is marked by investments in research and development, with companies exploring sustainable sourcing and technological advancements to enhance the nutritional profile and functional properties of pea proteins. This dynamic competition is expected to drive market growth and innovation.
Recent Developments:
- In July 2024, Ingredion Incorporated launched Vitessence Pea 100 HD, a new pea protein enhanced for cold-pressed bars in the U.S. and Canada markets. This innovative protein solution helps maintain softness throughout the shelf life of cold-pressed bars while delivering superior texture and taste.
- In February 2024, Roquette, a leading ingredients company, launched four new multi-functional pea proteins as part of its NUTRALYS® plant protein range. The new products, NUTRALYS® Pea F853M (isolate), NUTRALYS® H85 (hydrolysate), NUTRALYS® T Pea 700FL (textured), and NUTRALYS® T Pea 700M (textured), are designed to improve taste, texture, and creativity in plant-based food and high-protein nutritional products.
- In November 2024, Burcon NutraScience Corporation formed an alliance with a strategic investor group to acquire and operate a commercial protein production facility. The acquisition of the chosen target facility is expected to close during the first quarter of 2025. This alliance aims to expand Burcon's production capabilities to include its entire portfolio of plant-based protein ingredient.
Market Concentration & Characteristics:
The U.S. Pea Proteins market exhibits moderate to high concentration, with a few key players dominating the landscape. Leading companies, such as Cargill, Ingredion Incorporated, and Roquette Frères, hold significant market share, benefiting from established distribution networks, strong brand presence, and robust R&D capabilities. However, the market also features a growing number of smaller, niche players focusing on specialized pea protein products and sustainable production methods, which contributes to increasing market fragmentation. The market is characterized by strong competition and innovation, with companies investing in the development of new formulations to meet consumer demand for clean-label, plant-based protein alternatives. Additionally, the growing focus on sustainability and traceability in the supply chain is shaping the industry. The increasing adoption of plant-based diets and the expansion of pea protein applications across multiple sectors such as food and beverages, nutraceuticals, and animal feed are key drivers of market growth.
Report Coverage:
The research report offers an in-depth analysis based on By Product Segment, By Application Segment, By Form Segment and By Source Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The U.S. Pea Proteins market will continue to expand as demand for plant-based protein alternatives rises, fueled by health-conscious consumers.
- Increasing awareness of sustainability and environmental impact will drive greater adoption of pea proteins as a eco-friendlier option compared to animal-based proteins.
- Innovations in pea protein formulations will enhance product versatility, supporting applications across various sectors, including food, beverages, and nutraceuticals.
- The rise of plant-based diets, particularly vegan and vegetarian lifestyles, will further accelerate market growth.
- Advancements in production technologies will improve cost-efficiency, leading to more competitive pricing and wider market accessibility.
- The food and beverage industry will incorporate pea proteins into a broader range of products, such as meat substitutes, dairy alternatives, and protein-enriched snacks.
- Regional agricultural growth in the Midwest will increase domestic production and supply, enhancing market stability.
- Strategic partnerships and acquisitions among key players will drive innovation and expand distribution channels.
- Consumer preference for clean-label products will push companies to offer pea protein options with minimal processing and additives.
- Increased investment in research and development will foster continued improvements in the taste, texture, and nutritional profile of pea proteins.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Pea Proteins Market?
What factors are driving the growth of the U.S. Pea Proteins Market?
What are the key segments within the U.S. Pea Proteins Market?
who are the major players in the U.S. Pea Proteins Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Pea Proteins Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 U.S. Pea Proteins Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 650.6 million → 2032: USD 1652.53 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Pea Proteins Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Pea Proteins Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Pea Proteins Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 U.S. Pea Proteins Drivers
- 3.3 U.S. Pea Proteins Restraints & Challenges
- 3.4 U.S. Pea Proteins Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Pea Proteins Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Pea Proteins Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Pea Proteins category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Pea Proteins Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. U.S. Pea Proteins Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2024)
- 5.1.2 Export Volume by Destination Country (2024) (Where Applicable)
- 5.1.3 Import Value by Source Country (2024)
- 5.1.4 Import Volume by Source Country (2024) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to U.S. Pea Proteins in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Pea Proteins Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 U.S. Pea Proteins Share Analysis – 2024
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 U.S. Pea Proteins Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Pea Proteins (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in U.S. Pea Proteins
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. U.S. Pea Proteins – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. U.S. Pea Proteins – Priority Domestic Market 1
Chapter 10. U.S. Pea Proteins – Priority Domestic Market 2
Chapter 11. U.S. Pea Proteins – Priority Domestic Market 3
Chapter 12. U.S. Pea Proteins – Priority Domestic Market 4
Chapter 13. U.S. Pea Proteins Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
