
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Powder Metallurgy Market Size 2024 | USD 793.92 million |
| U.S. Powder Metallurgy Market, CAGR | 6.82% |
| U.S. Powder Metallurgy Market Size 2032 | USD 1,345.71 million |
Market Overview:
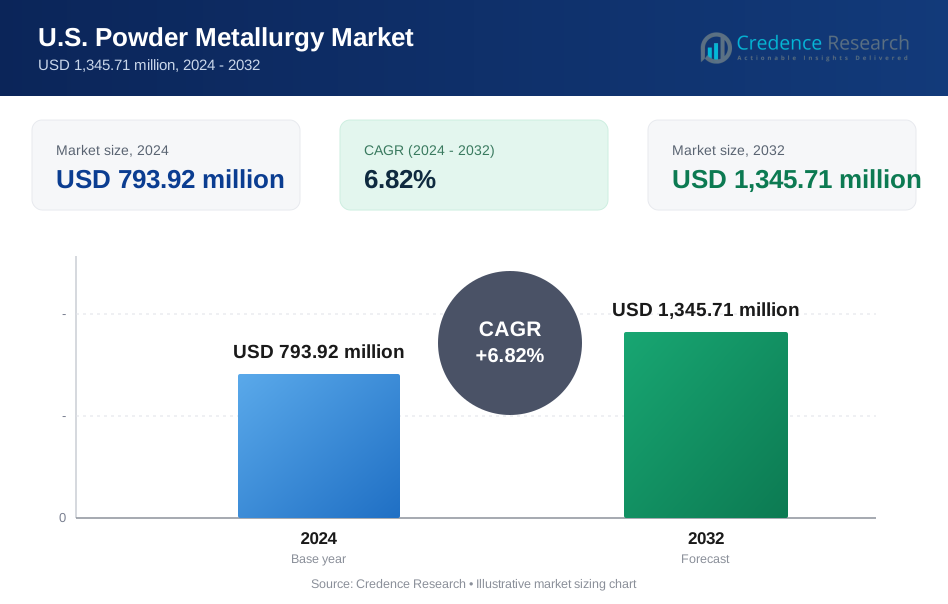
The U.S. Powder Metallurgy Market is projected to grow from USD 793.92 million in 2024 to an estimated USD 1,345.71 million by 2032, with a compound annual growth rate (CAGR) of 6.82% from 2024 to 2032.
Several factors are propelling the growth of the powder metallurgy market in the U.S. The automotive industry, in particular, has been a significant driver, utilizing powder metallurgy to produce lightweight and durable components that enhance fuel efficiency and performance. Additionally, the aerospace and defense sectors have increasingly adopted powder metallurgy techniques to manufacture complex parts with high precision, contributing to the market's expansion. The medical and dental fields also leverage powder metallurgy for crafting intricate surgical instruments and implants, further bolstering market demand. Advancements in material science and innovations in processing techniques are enhancing the overall quality and versatility of powder metallurgy products. Moreover, growing environmental concerns are encouraging the adoption of sustainable manufacturing practices, further boosting the application of powder metallurgy across industries.
Regionally, North America, with the U.S. at its core, holds a dominant position in the powder metallurgy market. This dominance is attributed to the region's robust manufacturing infrastructure, technological advancements, and the presence of key industry players. The U.S. market benefits from substantial investments in research and development, fostering innovation in powder metallurgy processes and applications. Moreover, the integration of additive manufacturing technologies has opened new avenues for market growth, enabling the production of complex geometries and customized solutions across various sectors. Strategic collaborations and partnerships between leading companies and research institutions are further accelerating innovation in the sector. Additionally, government initiatives supporting advanced manufacturing processes are contributing to the sustained growth of the U.S. powder metallurgy market.
Market Insights:
- The U.S. Powder Metallurgy Market is projected to grow from USD 793.92 million in 2024 to USD 1,345.71 million by 2032, registering a CAGR of 6.82% during the forecast period.
- The automotive industry is a major growth driver, utilizing powder metallurgy for producing lightweight and durable components that enhance fuel efficiency and support the development of electric vehicles (EVs).
- The aerospace and defense sectors are increasingly adopting powder metallurgy techniques to manufacture high-strength, precision components, meeting stringent performance and durability standards.
- Continuous advancements in processes such as hot isostatic pressing (HIP) and metal injection molding (MIM) are enhancing product quality, reliability, and broadening application areas across industries.
- The industry faces key challenges such as supply chain disruptions, high initial capital investments, and competition from traditional manufacturing methods like casting and machining.
- Growing environmental concerns are driving the adoption of sustainable manufacturing practices, promoting material efficiency, and reducing industrial waste.
- The U.S. benefits from robust manufacturing infrastructure, significant R&D investments, and strategic collaborations, positioning it for sustained growth within the North American powder metallurgy market.
Market Drivers:
Technological Advancements in Additive Manufacturing
The U.S. powder metallurgy market has experienced significant growth due to advancements in additive manufacturing (AM) technologies. AM, commonly known as 3D printing, enables the production of complex geometries and customized components with high precision. This capability has attracted various industries, including aerospace, automotive, and healthcare, to adopt AM for manufacturing lightweight and efficient parts. For instance, in healthcare, 4D printers are being used to create adaptive implants that respond to bodily stimuli, such as stents and heart valves, offering personalized solutions for patients. The increasing number of 3D printing patents and the emergence of startups specializing in AM have further propelled the market's expansion.
Rising Demand in the Automotive Industry
The automotive sector remains a pivotal driver for the U.S. powder metallurgy market. For instance, manufacturers are increasingly utilizing powder metallurgy to produce components such as gears, bearings, and pistons, which contribute to vehicle weight reduction and enhanced fuel efficiency. The shift towards electric vehicles (EVs) has also opened new avenues for powder metallurgy applications, as EVs require specialized components that can be efficiently produced using this technology. The ability to achieve complex shapes and maintain material properties makes powder metallurgy an ideal choice for automotive manufacturers aiming to meet stringent performance and environmental standards.
Expansion in Aerospace and Defense Applications
The aerospace and defense industries have increasingly adopted powder metallurgy techniques to manufacture high-strength, lightweight components capable of withstanding extreme conditions. Materials such as titanium alloys, processed through powder metallurgy, are used to produce critical aircraft parts, including turbine blades and structural components. The precision and material efficiency offered by powder metallurgy align with the industry's requirements for performance and cost-effectiveness. For instance, ArcelorMittal has developed an industrial-scale atomizer to create steel powders for aerospace applications, highlighting the industry's focus on innovative materials. As defense budgets and commercial aerospace demand continue to rise, the reliance on powder metallurgy for component manufacturing is expected to grow correspondingly.
Advancements in Powder Metallurgy Processes
Continuous improvements in powder metallurgy processes, such as hot isostatic pressing (HIP) and metal injection molding (MIM), have enhanced the quality and performance of manufactured components. These advancements allow for better control over material properties, leading to parts with superior mechanical characteristics and reliability. The development of new alloy compositions and refined powder production techniques has expanded the range of applications for powder metallurgy. Industries seeking efficient manufacturing methods for complex and high-performance parts are increasingly turning to these advanced powder metallurgy processes, thereby driving market growth. For example, advancements in atomization processes have significantly improved the efficiency and quality of spherical powder production, which is crucial for various industrial applications.
Market Trends:
Integration of Additive Manufacturing
The U.S. powder metallurgy market is witnessing a significant trend in the integration of additive manufacturing (AM) technologies. AM, commonly known as 3D printing, allows for the production of complex geometries and customized components with high precision. For instance, metal 3D printing processes like Selective Laser Melting (SLM) utilize finely ground metal powders to create lightweight and high-performance parts for industries such as aerospace and automotive. This capability has opened new avenues for powder metallurgy applications, particularly in industries such as aerospace, automotive, and healthcare. The synergy between powder metallurgy and AM not only enhances design flexibility but also reduces material wastage, aligning with sustainability goals. As AM technologies continue to evolve, their adoption within powder metallurgy processes is expected to increase, driving innovation and efficiency in component manufacturing.
Emphasis on Lightweight Materials
There is a growing emphasis on developing lightweight materials within the U.S. powder metallurgy market. Industries such as automotive and aerospace are increasingly seeking materials that can reduce the overall weight of components without compromising strength and durability. For example, titanium alloys processed via techniques such as two-step sintering (TSS) exhibit improved mechanical properties and corrosion resistance, making them ideal for applications requiring high performance and durability. Powder metallurgy facilitates the production of such materials, including advanced aluminum and titanium alloys, which are essential for improving fuel efficiency and performance. This trend towards lightweighting is anticipated to drive further advancements in powder metallurgy techniques, enabling the creation of components that meet stringent industry requirements.
Expansion in Medical Applications
The medical sector is emerging as a significant area of growth for the U.S. powder metallurgy market. The ability to produce biocompatible implants and intricate surgical instruments using powder metallurgy processes has led to increased adoption in medical applications. The precision and customization offered by powder metallurgy are particularly beneficial for patient-specific implants, enhancing treatment outcomes. For example, Metal Injection Molding (MIM) is used to manufacture implants with complex shapes that are difficult to achieve through traditional methods, enhancing patient comfort and treatment effectiveness. As the demand for minimally invasive surgical procedures and personalized medicine rises, the application of powder metallurgy in the medical field is expected to expand, offering new opportunities for market growth.
Focus on Sustainable Manufacturing
Sustainable manufacturing practices are becoming increasingly important in the U.S. powder metallurgy market. The inherent efficiency of powder metallurgy processes, which generate minimal waste compared to traditional manufacturing methods, aligns with environmental sustainability goals. For example, recycled metal powders are increasingly being used in additive manufacturing processes like Direct Metal Laser Sintering (DMLS), reducing environmental impact while maintaining quality standard. This focus on sustainability is driving both regulatory support and consumer preference for products manufactured through eco-friendly processes. As environmental considerations continue to influence manufacturing strategies, powder metallurgy's role in sustainable production is poised to strengthen, supporting the industry's long-term growth.
Market Challenges Analysis:
Supply Chain Disruptions
The U.S. powder metallurgy industry has encountered significant challenges due to global supply chain disruptions. Factors such as the COVID-19 pandemic, shortages of semiconductor microchips, and container scarcities have adversely affected the timely procurement of raw materials and the distribution of finished products. These disruptions have led to production delays and increased operational costs, hindering the industry's overall efficiency.
High Initial Capital Investment
Implementing advanced powder metallurgy technologies necessitates substantial initial capital investments. The costs associated with specialized equipment and the development of new materials can be prohibitive, particularly for small and medium-sized enterprises. This financial barrier limits the widespread adoption of innovative powder metallurgy processes, thereby constraining market growth.
Competition from Alternative Manufacturing Technologies
The powder metallurgy sector faces stiff competition from alternative manufacturing methods, such as casting and machining. These traditional techniques often offer cost advantages and established processes, making them preferable for certain applications. This competition poses a challenge to the broader adoption of powder metallurgy solutions, especially in industries where cost reduction is a primary concern.
Environmental and Health Considerations
The powder metallurgy industry must address environmental and health concerns related to the use of metal powders and energy-intensive processes. Handling fine metal powders poses health risks to workers, necessitating stringent safety protocols. Additionally, the energy consumption during sintering processes contributes to the industry's environmental footprint, prompting the need for more sustainable practices.
Market Opportunities:
The U.S. powder metallurgy market is poised for significant growth, driven by the increasing adoption of advanced manufacturing technologies. Notably, additive manufacturing (AM), or 3D printing, has revolutionized the production of complex and customized components across various industries, including aerospace, automotive, and healthcare. This synergy between powder metallurgy and AM not only enhances design flexibility but also reduces material wastage, aligning with sustainability goals. As AM technologies continue to evolve, their integration within powder metallurgy processes is expected to drive innovation and efficiency in component manufacturing.
Moreover, the automotive sector's emphasis on lightweight and fuel-efficient vehicles presents substantial opportunities for powder metallurgy applications. The ability to produce high-strength, lightweight components is crucial for electric vehicles (EVs), which require specialized parts to optimize performance and range. Powder metallurgy facilitates the production of such components, positioning it as a key technology in the advancement of EVs. Additionally, the aerospace and defense industries' demand for materials that can withstand extreme conditions further underscores the potential of powder metallurgy. By enabling the manufacturing of high-strength, lightweight components, powder metallurgy meets the stringent requirements of these sectors, thereby expanding its market presence.
Market Segmentation Analysis:
The U.S. powder metallurgy market is segmented based on material, application, end-use industry, and process, each contributing uniquely to the market's growth and diversification.
By Material Segment, the market is divided into ferrous metals, non-ferrous metals, and others. Ferrous metals, including iron and steel, dominate the segment due to their extensive use in automotive and industrial machinery. Non-ferrous metals, such as aluminum, titanium, and copper, are gaining traction owing to their lightweight properties and high strength, making them ideal for aerospace and electrical applications. The "others" category includes specialized alloys, addressing niche requirements across various industries.
By Application Segment, automotive leads in terms of market share, driven by the demand for lightweight, durable components to enhance fuel efficiency. The aerospace segment is also expanding, leveraging powder metallurgy for complex, high-precision parts. Industrial machinery utilizes powder metallurgy for robust components, while electrical and electronics industries are adopting it for advanced material solutions. The "others" segment includes medical and energy applications, offering additional growth avenues.
By End-Use Industry Segment, transportation remains the dominant sector due to the widespread adoption of powder metallurgy in automotive and aerospace manufacturing. The consumer goods sector is gradually embracing this technology for durable and efficient product designs. The industrial segment continues to be a strong market driver, with powder metallurgy playing a crucial role in heavy machinery and equipment production.
By Process Segment, blending, compaction, and sintering are fundamental processes shaping the market. Blending ensures uniform material properties, compaction improves part density, and sintering enhances the mechanical strength of components. Advancements in these processes are further enhancing product quality and expanding industrial applications.
Segmentation:
By Material Segment
- Ferrous Metals
- Non-Ferrous Metals
- Others
By Application Segment
- Automotive
- Aerospace
- Industrial Machinery
- Electrical & Electronics
- Others
By End-Use Industry Segment
- Transportation
- Consumer Goods
- Industrial
By Process Segment
- Blending
- Compaction
- Sintering
Regional Analysis:
The U.S. powder metallurgy market holds a significant position within the global landscape, driven by its advanced manufacturing capabilities and diverse industrial applications. As of 2023, North America accounted for approximately 38% of the global powder metallurgy market share, with the United States contributing a substantial portion of this figure.
Regional Market Distribution
Within the United States, the powder metallurgy industry is geographically dispersed, with notable concentrations in the Midwest and Northeast regions. States such as Michigan, Ohio, and Pennsylvania have historically been centers for manufacturing and metalworking, providing a robust infrastructure for powder metallurgy operations. These regions benefit from a skilled workforce, established supply chains, and proximity to key automotive and industrial clients.
Industry Applications and Growth Drivers
The automotive sector remains a primary consumer of powder metallurgy components in the U.S., driven by the demand for lightweight and efficient parts. The aerospace and defense industries also contribute significantly to market growth, utilizing powder metallurgy for complex and high-performance components. Additionally, advancements in additive manufacturing and metal injection molding have expanded the applications of powder metallurgy across various sectors, including medical and dental fields.
Future Outlook
The U.S. powder metallurgy market is poised for continued growth, supported by ongoing technological advancements and the diversification of applications. Investments in research and development, coupled with the integration of sustainable manufacturing practices, are expected to enhance the competitiveness of U.S. manufacturers in the global arena. As industries increasingly seek efficient and cost-effective production methods, powder metallurgy is likely to play a pivotal role in meeting these evolving demands.
Key Player Analysis:
- GKN Powder Metallurgy
- Carpenter Technology Corporation
- Rio Tinto Metal Powders
- ATI Specialty Materials
- Advanced Materials Technologies
- American Axle & Manufacturing Holdings, Inc.
- Ametek Specialty Metal Products
- Höganäs AB
- Praxair Surface Technologies, Inc.
- Kennametal Inc.
Competitive Analysis:
The U.S. powder metallurgy market is characterized by the presence of several prominent companies that contribute to its competitive landscape. Notable industry players include Carpenter Technology Corporation, and Molyworks Materials Corporation, all based in the United States. These companies are recognized for their significant contributions to the development and application of powder metallurgy technologies. For instance, Allegheny Technologies Incorporated (ATI) is another prominent U.S. player in the powder metallurgy sector. It offers advanced powder metal solutions, particularly for aerospace and defense applications, emphasizing superior cleanliness, homogeneous microstructure, and limitless alloying possibilities. In addition to domestic firms, the U.S. market also features international companies such as Sandvik AB from Sweden and Höganäs AB, which have established a strong presence through their advanced material solutions and extensive product portfolios. The competitive dynamics of the U.S. powder metallurgy market are influenced by factors such as technological innovation, product quality, and strategic partnerships. Companies that invest in research and development to enhance material properties and manufacturing processes are better positioned to meet the evolving demands of industries like automotive, aerospace, and medical devices. Collaborations between powder metallurgy firms and end-user industries further drive market competitiveness by fostering the development of tailored solutions and expanding application areas.
Recent Developments:
- In Dec 2024 United States Metal Powders Inc. (USMP) announced plans for a new aluminum powder manufacturing line at its Ampal Inc subsidiary in Palmerton, Pennsylvania. Scheduled to commence full production by mid-2025, this line will produce both nodular and spherical aluminum powders. The expansion reflects USMP’s commitment to growth and supply chain reliability while leveraging state-of-the-art technology for safety and quality.
- In January 2025, American Axle & Manufacturing (AAM), headquartered in Detroit, Michigan, announced an agreement to acquire Dowlais Group plc, the parent company of GKN Automotive and GKN Powder Metallurgy, in a deal valued at $1.44 billion. This strategic acquisition aims to create a leading driveline and metal-forming supplier for the global automotive industry, enhancing AAM's product portfolio and global reach.
- In November 2024, GKN Hoeganaes, a division of GKN Powder Metallurgy, announced its support for First Phosphate in the development of Lithium Iron Phosphate (LFP) cathode active material. This collaboration aims to advance the production of sustainable and efficient battery materials for the growing electric vehicle market.
Market Concentration & Characteristics:
The U.S. powder metallurgy market exhibits a moderately concentrated landscape, characterized by the presence of several key players who dominate the industry. Notable companies such as Carpenter Technology Corporation, Höganäs AB, GKN Powder Metallurgy, and Sandvik AB hold significant market shares, leveraging their extensive experience, technological advancements, and comprehensive product portfolios. This concentration allows these leading firms to influence market trends, pricing strategies, and technological developments within the sector. Despite this concentration, the market remains competitive, with numerous small to medium-sized enterprises (SMEs) contributing to innovation and specialized applications. These SMEs often focus on niche markets or customized solutions, fostering a dynamic environment that encourages technological advancements and diversification of applications. The industry's characteristics include a strong emphasis on research and development, particularly in areas like additive manufacturing and sustainable practices, to meet evolving demands from sectors such as automotive, aerospace, and medical devices.
Report Coverage:
The research report offers an in-depth analysis based on By Material Segment, By Application Segment, By End-Use Industry Segment and By Process Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The U.S. powder metallurgy market is projected to witness steady growth, driven by increasing demand in the automotive and aerospace sectors.
- Advancements in additive manufacturing are expected to expand the market's application scope, enabling the production of complex and customized components.
- Growing emphasis on lightweight materials will drive demand for powder metallurgy in industries aiming to enhance fuel efficiency and performance.
- The shift towards electric vehicles will open new opportunities for powder metallurgy in producing specialized and efficient automotive components.
- Continuous investments in research and development will foster innovation in alloy compositions and manufacturing processes.
- The medical sector will offer growth prospects as the demand for biocompatible implants and precision surgical instruments increases.
- Integration of sustainable manufacturing practices will enhance market competitiveness by reducing waste and promoting material efficiency.
- Strategic collaborations between manufacturers and end-use industries will accelerate the development of customized solutions.
- Technological advancements in metal injection molding and sintering processes will improve product quality and broaden industrial applications.
- Expanding applications in defense and industrial machinery will further reinforce the market’s long-term growth trajectory.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Powder Metallurgy Market?
What are the key segments within the U.S. Powder Metallurgy Market?
What are some challenges faced by the U.S. Powder Metallurgy Market?
Who are the major players in the U.S. Powder Metallurgy Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Powder Metallurgy Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. Powder Metallurgy Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 793.92 million → 2032: USD 1,345.71 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Powder Metallurgy Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Powder Metallurgy Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Powder Metallurgy Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. Powder Metallurgy Market Drivers
- 3.3 U.S. Powder Metallurgy Market Restraints & Challenges
- 3.4 U.S. Powder Metallurgy Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Powder Metallurgy Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Powder Metallurgy Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Powder Metallurgy category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Powder Metallurgy Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. Powder Metallurgy Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. Powder Metallurgy market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Powder Metallurgy Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. Powder Metallurgy Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. Powder Metallurgy Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Powder Metallurgy (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. Powder Metallurgy Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. Powder Metallurgy Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. Powder Metallurgy Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. Powder Metallurgy Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. Powder Metallurgy Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. Powder Metallurgy Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. Powder Metallurgy Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. Powder Metallurgy Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. Powder Metallurgy Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
