
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| U.S. Reusable Water Bottles Market Size 2023 | USD 1,688.85 Million |
| U.S. Reusable Water Bottles Market, CAGR | 5.28% |
| U.S. Reusable Water Bottles Market Size 2032 | USD 2,701.62 Million |
Market Overview
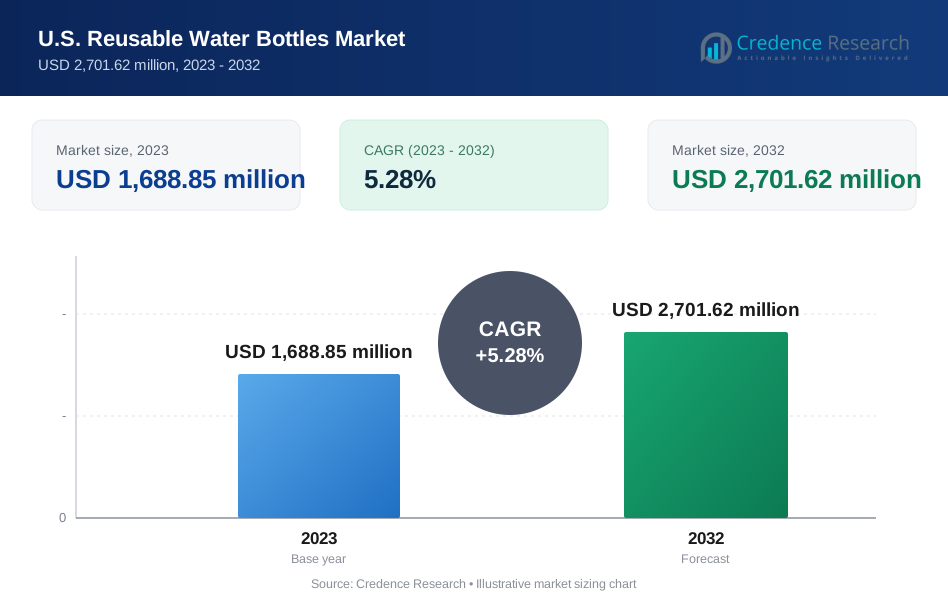
The U.S. Reusable Water Bottles Market is projected to grow from USD 1,688.85 million in 2023 to an estimated USD 2,701.62 million by 2032, demonstrating a steady compound annual growth rate (CAGR) of 5.28% from 2024 to 2032. This notable expansion underscores a significant shift in consumer behavior toward sustainable and eco-friendly products. As the awareness regarding environmental issues like plastic pollution intensifies, consumers are increasingly adopting reusable water bottles. This trend is further supported by the growing health consciousness among Americans who are turning to reusable options to avoid the chemicals often found in single-use plastic bottles.
Several drivers and trends are propelling the U.S. Reusable Water Bottles Market forward. Increasing environmental awareness among consumers, coupled with government initiatives aimed at reducing plastic waste, are major driving forces. The market is also witnessing a surge in innovation with manufacturers introducing bottles featuring smart technology, such as built-in purification systems and hydration tracking. These innovations enhance the functionality of water bottles, making them more appealing to health-conscious and tech-savvy consumers. Additionally, the rise in outdoor activities and fitness trends continues to boost the demand for durable and portable water bottles.
Geographically, the market is segmented across various regions, with the West Coast leading in terms of sales due to its active lifestyle culture and high environmental awareness. Key players in the U.S. Reusable Water Bottles Market include Contigo, Thermos LLC, and CamelBak Products, LLC. These companies are known for their innovation, quality, and sustainability practices. They are actively investing in eco-friendly materials and technologies to maintain their competitive edge and appeal to environmentally conscious consumers. As these trends continue, the market is expected to see robust growth across various states, supported by a network of influential manufacturers and an increasingly eco-aware customer base.
Market Drivers
Environmental Awareness and Anti-Plastic Sentiment:
A pivotal driver for the U.S. Reusable Water Bottles Market is the heightened environmental awareness among consumers. As the detrimental impacts of plastic pollution become more visible-particularly in oceans and other natural habitats-there is a growing movement against single-use plastics. Reusable water bottles offer a sustainable alternative that reduces waste and environmental impact. This shift is supported by various environmental campaigns and educational programs that emphasize the importance of reducing plastic waste, thereby encouraging consumers to make more environmentally responsible choices. For instance, 67% of global consumers say that environmental health and how their choices impact the planet is important to them .
Health Consciousness Among Consumers:
Health concerns related to the chemicals in plastic containers, such as BPA and phthalates, have spurred interest in reusable water bottles. These chemicals are suspected of having harmful effects on human health, including hormonal disruptions and increased cancer risk. As a result, health-conscious consumers are increasingly turning to reusable water bottles made from safer materials like stainless steel, glass, and BPA-free plastics. This shift is not only a matter of environmental concern but also of personal health, making it a compelling market driver. For instance, 64% of Americans say they prefer paper food packaging over plastic or Styrofoam, and 48% try to reduce their use of plastic items such as straws, cups, or bags.
Technological Advancements and Product Innovation:
The market for reusable water bottles is also driven by continuous product innovation and the integration of technology. Modern reusable water bottles come with a variety of features such as built-in filters, insulation for temperature control, and even smart technology that tracks hydration levels or syncs with fitness apps. These innovations make reusable water bottles more appealing and functional for a broad range of consumers, from tech enthusiasts to outdoor adventurers, further propelling market growth.
Lifestyle Trends Toward Mobility and Fitness:
As more individuals engage in active lifestyles, including outdoor activities, gym routines, and sports, the demand for convenient, portable hydration solutions is on the rise. Reusable water bottles cater to this need effectively, offering durable and easy-to-carry designs that fit well with an active lifestyle. Additionally, the aesthetic aspect of reusable water bottles, with customizable options and stylish designs, aligns with contemporary lifestyle trends, making them a popular accessory among consumers of all ages.
Market Trends
Sustainability in Material Use:
There is a significant shift towards the use of eco-friendly materials in the production of reusable water bottles. Materials such as stainless steel, glass, and BPA-free plastics are preferred for their durability and non-toxic properties. Moreover, the innovation extends to the use of biodegradable materials and plant-based plastics, which further minimize the environmental footprint of these products. For instance, 67% of businesses have begun to use more eco-friendly materials, such as recycled substances and products that generate lower emissions.
Smart Technology Integration:
Incorporating technology into reusable water bottles is a trend gaining momentum. Features such as hydration trackers, which remind users to drink water, and temperature control technology are becoming increasingly popular. These smart bottles can connect to smartphones and other devices, making them an integral part of a health-conscious lifestyle.
Customization and Personalization:
Personalization options such as color choices, designs, and the ability to add personal logos or messages are trending. This customization appeals particularly to younger demographics who value individuality and self-expression in the products they purchase. For instance, personalized water bottle orders have increased by 40% in the last two years.
Increased Portability and Convenience:
As consumers lead increasingly mobile lifestyles, there is a growing demand for water bottles that are easy to carry and use. Features such as collapsible designs, integrated carrying straps, and carabiner clips for easy attachment to bags are becoming standard. These features enhance the practicality of reusable water bottles for everyday use, travel, and sports.
Fashion and Aesthetics:
Reusable water bottles are not just practical-they're also becoming a fashion statement. Trendy designs and collaborations with artists and designers have made these bottles both functional and stylish accessories. This trend is particularly strong among younger consumers who look for products that reflect their personal style and values.
Health and Safety Features:
With growing health awareness, consumers are looking for water bottles that offer health benefits beyond hydration. Features such as alkaline water filters that improve the quality of tap water and UV light sterilization to keep the water free from pathogens are attracting health-focused consumers.
Multi-Functional Designs:
There is an emerging trend towards multi-functional water bottles that offer more than just hydration. Examples include bottles with built-in storage compartments for keys, money, or small snacks. This multifunctionality is particularly appealing to people who appreciate minimalism and efficiency in their accessories.
Market Restraints and Challenges
Competition from Low-Cost Alternatives:
One of the significant challenges facing the U.S. Reusable Water Bottles Market is the competition from cheaper, disposable water bottles. Despite the environmental impact, single-use plastic bottles remain popular due to their convenience and lower upfront costs. Convincing consumers to invest in a more expensive, albeit sustainable, option can be challenging, especially in segments of the market that are highly price-sensitive.
Market Saturation:
The market for reusable water bottles is becoming increasingly saturated with numerous products and brands. This saturation can make it difficult for new entrants to establish a foothold and for existing players to maintain or grow their market share. Differentiation becomes a challenge as consumers face an overwhelming array of choices, potentially leading to decision fatigue.
Maintenance and Hygiene Concerns:
Reusable water bottles require regular cleaning to prevent the growth of bacteria and mold, which can be a significant deterrent for some consumers. The need for frequent maintenance can be perceived as inconvenient compared to the ease of using disposable bottles. Overcoming this perception by enhancing the user-friendliness and maintenance features of reusable bottles is a challenge for manufacturers.
Regulatory and Safety Standards:
Compliance with stringent regulatory and safety standards can pose challenges, especially for new market entrants. The materials used in water bottles, such as plastics and metals, must be certified safe for consumer health, which can involve complex and costly testing processes. Changes in regulations can also lead to sudden adjustments in manufacturing processes, impacting the overall market dynamics.
Environmental Impact of Production:
Although reusable water bottles are marketed as eco-friendly products, the environmental impact of their production, including the use of resources and energy, can still be significant. Consumers and advocacy groups are increasingly scrutinizing the entire lifecycle of products. Manufacturers must address these concerns by adopting more sustainable production practices, which can involve significant investment and innovation.
Impact of Economic Downturns:
Economic downturns can lead to reduced consumer spending on non-essential goods, including reusable water bottles. In times of economic uncertainty, consumers may prioritize basic needs and delay purchases of items considered luxury or non-essential, which can affect sales volumes.
Market Segmentation Analysis
By Material Type
Glass bottles, favored for their aesthetic appeal and non-reactive nature, ensure that they do not impart flavors or chemicals into water, making them popular among health-conscious consumers who prioritize purity, despite their fragility and higher cost limiting broader appeal. Stainless steel bottles, known for their durability and excellent insulation properties, are ideal for active consumers, providing robust growth due to their practicality and the demand for lifestyle-supporting products. Plastic bottles remain popular for their lightweight and versatile designs, sustained by advances in BPA-free materials, offering affordability and accessibility. Silicon bottles, flexible, lightweight, and durable, are particularly appealing to travelers and sports enthusiasts for their collapsibility and portability. Lastly, newer materials like biodegradable plastics and composites are gaining traction as consumers seek more sustainable, functional alternatives.
By Distribution Channel
The U.S. Reusable Water Bottles Market leverages various distribution channels to reach diverse consumer segments effectively. Specialty stores focusing on sporting goods, outdoor equipment, or health and wellness products cater to demographics seeking high-quality and specialized options. Convenience stores provide quick and accessible purchasing opportunities, although their variety may be more limited. Supermarkets and hypermarkets play a crucial role due to their extensive reach and ability to showcase a wide range of brands and types, allowing consumers to compare products conveniently. Additionally, online platforms and direct-to-consumer channels are gaining prominence, driven by the rise of e-commerce, offering extensive customization options and detailed product information directly to consumers.
Segments
Based on Material Type
- Glass
- Stainless Steel
- Plastic
- Silicon
- Others
Based on Distribution Channel
- Specialty Stores
- Convenience Stores
- Supermarkets and Hypermarkets
- Others
Regional Analysis
West Coast (30%):
The West Coast, particularly states like California, Oregon, and Washington, holds the largest share of the U.S. Reusable Water Bottles Market. This region's strong environmental consciousness, coupled with a highly active lifestyle culture, significantly contributes to the high adoption rate of reusable water bottles. The presence of numerous outdoor enthusiasts, health-conscious populations, and tech-savvy consumers also drives innovation and sales in this area.
Northeast (25%):
The Northeast, including New York, New Jersey, and Massachusetts, accounts for a quarter of the market. This region's dense urban centers promote the usage of reusable water bottles among commuters and professionals who prioritize convenience and sustainability. The high level of environmental regulation and initiatives promoting waste reduction further enhance the market's growth in this region.
South (15%):
The Southern states, including Texas, Florida, and Georgia, contribute to 15% of the national market. The adoption rate here is influenced by the region’s growing interest in health and fitness, although the overall environmental awareness may be less pronounced compared to other regions. The expanding urban populations and increasing number of health-oriented programs and facilities are likely to propel the market forward.
Key players
- Smith Corporation
- Newell Brands, Inc.
- Vista Outdoor, Inc. (CamelBak Products LLC)
- Groupe SEB
- Tupperware Brands Company
- SIGG Switzerland Bottles AG (Zhejiang Haers Vacuum Containers Co., Ltd.)
- Klean Kanteen
- Hydaway LLC
- Bulletin Bottle
Competitive Analysis
The competitive landscape of the U.S. Reusable Water Bottles Market is marked by a diverse mix of players, each bringing unique strengths to the table. A. O. Smith Corporation and Groupe SEB offer technologically advanced products, enhancing user convenience and product appeal. Newell Brands and Vista Outdoor (CamelBak Products LLC) dominate with robust distribution networks and brand recognition. Tupperware Brands and Klean Kanteen leverage their reputation for quality and sustainability. Niche players like SIGG Switzerland Bottles and Hydaway LLC differentiate through design innovation and compact solutions, appealing to specific consumer segments. Bulletin Bottle focuses on customization and promotional products, capturing a unique market niche. This varied competitive environment fosters continual innovation and diverse product offerings, addressing a broad spectrum of consumer needs and preferences.
Recent Developments
In April 2023, Nalgene transitioned its reusable bottle production to Eastman’s Tritan Renew, a certified 50% recycled material determined using the mass balance technique. This shift from copolyester to Tritan Renew, initiated in 2020 and completed by January 2023, allowed the company to repurpose over 2.35 million pounds of plastic waste. This change underscores Nalgene’s commitment to sustainability and reducing environmental impact through innovative material use.
In February 2023, SIGG Switzerland AG participated in the ABN AMRO Open tennis tournament, held at Rotterdam Ahoy in Rotterdam, providing all players with reusable drinking bottles made from Tritan Renew. This material is highly impact and scratchresistant and is certified by the ISCC (International Sustainability and Carbon Certification), demonstrating SIGG's dedication to sustainability and promoting ecofriendly practices at highprofile events.
In December 2022, Klean Kanteen, alongside MiiR, Stanley, and YETI, formed the Drinkware CoLab to reduce carbon emissions in their supply chains. This initiative supports the Outdoor Industry Association’s (OIA) goal of becoming the first climatepositive industry by 2030. As members of OIA’s Climate Action Corps, these brands are committed to achieving netpositive environmental impacts, surpassing netzero targets and driving industrywide sustainability efforts.
In August 2022, S’well introduced its Elements Collection, featuring three highgloss bottles named ‘Blue Marble,’ ‘Charcoal Granite,’ and ‘Opal Marble.’ These bottles, designed with earthy tones, are doublewalled and stainless steel insulated, keeping beverages cold for 24 hours and hot for 12 hours. The design ensures condensationfree surfaces, dripfree sipping, and a wide mouth for easy ice addition, combining functionality with aesthetic appeal.
In June 2022, Klean Kanteen launched its Rise drinkware collection, available for retail in January 2023. The collection includes five sizes and shapes of BPAfree drinkware, crafted from 90% postconsumer recycled 18/8 stainless steel. Featuring doublewalled construction and Klean Kanteen Climate Lock vacuum insulation, the collection offers enhanced durability and stability with impactresistant base caps, reflecting the brand’s focus on sustainable and resilient design.
In June 2022, Tupperware Brands Corporation collaborated with Vera Bradley, a U.S.based fashion company, to release a limitededition collection of reusable ECO+ water bottles, snack sets, and sandwich keepers. The line features three distinct patterns: Daisy Smile, Falling Daisies, and Sunflower collections, merging sustainability with fashionable design, and appealing to environmentally conscious consumers seeking stylish, reusable product.
Market Concentration and Characteristics
The U.S. Reusable Water Bottles Market is moderately concentrated, with a mix of wellestablished brands and emerging players. Key characteristics of the market include a strong focus on sustainability, innovation, and healthconscious products. Major players like Newell Brands, CamelBak Products LLC, and Klean Kanteen dominate the market with extensive distribution networks and continuous product innovation. The market also features a significant level of product differentiation, with companies offering a variety of materials, designs, and technological integrations to cater to diverse consumer preferences. Overall, the market's concentration and dynamic nature drive competitiveness and continuous evolution in product offerings.
Report Coverage
The research report offers an indepth analysis based on Material Type and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is anticipated to continue its steady growth trajectory, supported by increasing environmental awareness and consumer demand for sustainable products.
- Innovations such as smart hydration tracking and builtin filtration systems are expected to become more prevalent, enhancing product functionality and appeal.
- Continued development of ecofriendly materials, including biodegradable plastics and advanced composites, will likely drive market evolution and consumer adoption.
- The trend toward personalized and customizable water bottles will gain momentum, catering to consumers' desires for unique and individualized products.
- Products emphasizing health benefits, such as BPAfree materials and antimicrobial properties, will see increased demand as health consciousness grows.
- Online sales and directtoconsumer models are expected to expand, offering consumers more convenient access to a variety of reusable water bottles.
- The entry of new players and continuous innovation by established brands will intensify competition, driving further advancements in product quality and design.
- Enhanced government regulations and incentives promoting the use of sustainable products will bolster market growth and encourage consumer adoption.
- Companies will increasingly adopt sustainable practices throughout their supply chains, reflecting corporate responsibility and appealing to ecoconscious consumers.
- As awareness and education about environmental issues grow, a broader demographic, including younger and older consumers, will adopt reusable water bottles, expanding the market base.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the U.S. Reusable Water Bottles Market?
What factors are driving the growth of the reusable water bottles market?
Which materials are preferred for reusable water bottles?
What role do specialty stores play in the market?
Who are the key players in the U.S. Reusable Water Bottles Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1,688.85 million → 2032: USD 2,701.62 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Reusable Water Bottles Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Reusable Water Bottles Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Reusable Water Bottles Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Reusable Water Bottles Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Reusable Water Bottles Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Reusable Water Bottles Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Reusable Water Bottles Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Reusable Water Bottles Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1,688.85 million → 2032: USD 2,701.62 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Reusable Water Bottles Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Reusable Water Bottles Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 U.S. Reusable Water Bottles Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 U.S. Reusable Water Bottles Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
