
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Serverless Computing Market Size 2024 | USD 2677.98 Million |
| U.S. Serverless Computing Market, CAGR | 13.2% |
| U.S. Serverless Computing Market Size 2032 | USD 7220.65 Million |
Market Overview:
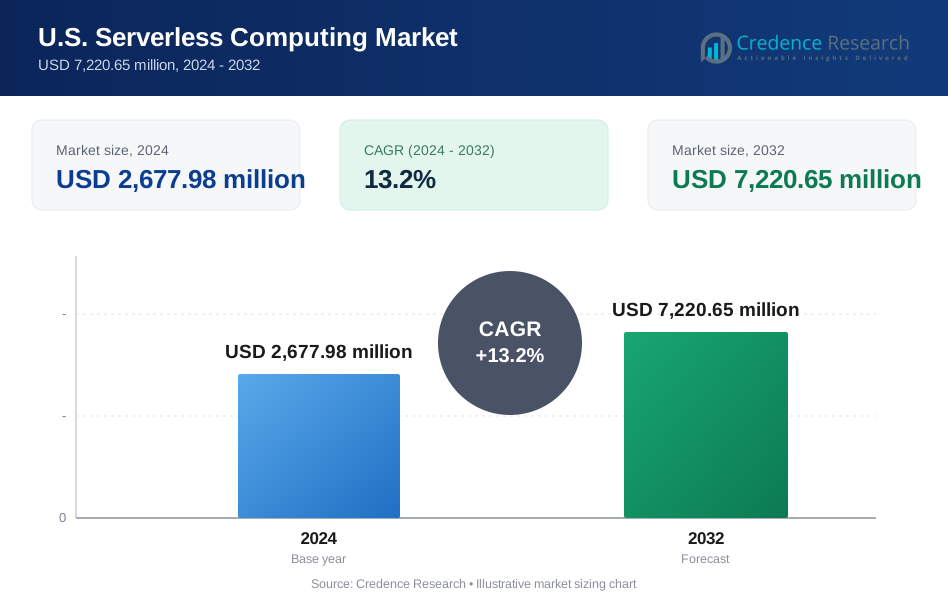
The U.S. Serverless Computing Market is projected to grow from USD 2677.98 million in 2024 to an estimated USD 7220.65 million by 2032, with a compound annual growth rate (CAGR) of 13.2% from 2024 to 2032.
The primary driver of the U.S. serverless computing market is the rising adoption of cloud computing and microservices-based architectures. Enterprises are increasingly leveraging serverless models to optimize performance, reduce infrastructure management overhead, and enhance operational efficiency. The demand for real-time data processing, API management, and automated scalability is further fueling market growth. Additionally, the increasing reliance on AI, machine learning, and IoT applications is driving the need for event-driven serverless computing frameworks, enabling organizations to build responsive and cost-effective solutions. The widespread adoption of DevOps practices and continuous integration/continuous deployment (CI/CD) pipelines is also encouraging the shift towards serverless computing platforms. Moreover, the growing focus on cost optimization and the elimination of server provisioning complexities are prompting enterprises to migrate towards serverless infrastructure. The increasing availability of Function-as-a-Service (FaaS) offerings from major cloud providers is also accelerating market adoption.
The U.S. serverless computing market is witnessing robust growth across key regions, with Silicon Valley and other major tech hubs leading adoption. States such as California, Texas, and Washington are at the forefront, driven by the presence of leading cloud service providers, tech startups, and enterprise IT firms. The East Coast, particularly New York and Massachusetts, is experiencing increasing adoption in financial services, healthcare, and retail industries, where serverless architectures are being utilized to support data-driven decision-making. Additionally, the Midwest and Southern states are witnessing rising investments in cloud computing infrastructure, enabling small and medium-sized enterprises (SMEs) to leverage serverless solutions for enhanced business agility. The expansion of cloud data centers across these regions is further facilitating the adoption of serverless computing by reducing latency and improving service availability.
Market Insights:
- The U.S. serverless computing market is projected to grow from USD 2,677.98 million in 2024 to USD 7,220.65 million by 2032, with a CAGR of 13.2%, driven by increasing cloud adoption and demand for scalable solutions.
- Cloud-native architectures and microservices adoption are accelerating the shift toward serverless computing, enabling businesses to enhance efficiency, reduce infrastructure management, and optimize operational costs.
- The integration of AI, machine learning, and IoT is fueling demand for event-driven serverless frameworks, allowing enterprises to process large volumes of data in real-time with cost-effective scalability.
- The rising adoption of DevOps and CI/CD practices is promoting seamless application deployment and automation, enhancing agility in software development and improving time-to-market.
- Challenges such as latency issues, security vulnerabilities, and vendor lock-in risks remain key concerns, requiring improved performance optimization, compliance solutions, and interoperability frameworks.
- Public cloud dominates the market, but private and hybrid cloud adoption is growing, particularly in highly regulated industries such as finance and healthcare.
- Silicon Valley and other major tech hubs lead market growth, while the East Coast, Midwest, and Southern states witness rising investments in cloud computing infrastructure, supporting serverless adoption across various industries.
Market Drivers:
Rising Adoption of Cloud Computing and Microservices
The increasing shift towards cloud-native architectures is a primary driver of the U.S. serverless computing market. Organizations are transitioning from traditional server-based models to cloud computing, leveraging serverless frameworks for enhanced scalability and cost efficiency. Serverless computing eliminates the need for infrastructure management, allowing enterprises to focus on application development and innovation. The adoption of microservices architecture further supports this transition by enabling businesses to deploy independent, event-driven functions that optimize resource utilization and improve system responsiveness. For instance, Amazon Redshift Serverless has introduced a higher base capacity of up to 1024 RPUs, doubling the previous maximum of 512 RPUs. This enhancement allows for improved performance in handling complex queries and write-intensive workloads, with benefits such as reduction in elapsed time and better performance in concurrent query execution.
Growing Demand for Cost-Effective and Scalable Solutions
Enterprises across various industries are adopting serverless computing to achieve cost optimization and operational efficiency. The pay-as-you-go pricing model allows businesses to pay only for the computing resources they consume, significantly reducing infrastructure costs. This eliminates the financial burden associated with provisioning and maintaining physical or virtual servers. For instance, Azure SQL Database Serverless automatically scales compute resources based on workload demand, billing per second of compute used. This approach optimizes price-performance and simplifies performance management, particularly for databases with intermittent usage patterns. Additionally, serverless architectures provide automatic scalability, allowing applications to dynamically adjust computing power based on workload fluctuations. This flexibility is particularly beneficial for businesses with variable or unpredictable demand, ensuring optimal performance without over-provisioning resources.
Increasing Integration of AI, Machine Learning, and IoT
The expansion of artificial intelligence (AI), machine learning (ML), and the Internet of Things (IoT) is driving the demand for serverless computing solutions. These technologies require real-time data processing capabilities, which serverless architectures efficiently support. Organizations implementing AI-driven applications and IoT ecosystems benefit from the event-driven nature of serverless computing, allowing seamless execution of complex workloads without manual intervention. The ability to process large volumes of data in a cost-efficient manner further enhances its adoption in sectors such as healthcare, finance, and industrial automation. As AI and IoT applications continue to evolve, serverless computing is expected to play a crucial role in supporting next-generation intelligent systems. For instance, iRobot uses AWS Lambda and AWS IoT to manage its IoT platform, handling increased traffic during holidays without manual infrastructure scaling. This setup enables iRobot to focus on innovation rather than infrastructure management, ensuring seamless customer experiences.
Growing Adoption of DevOps and CI/CD Practices
The increasing adoption of DevOps methodologies and continuous integration/continuous deployment (CI/CD) pipelines is accelerating the shift toward serverless computing. Organizations are prioritizing agile development processes that emphasize automation, rapid iterations, and efficient resource management. Serverless platforms integrate seamlessly with CI/CD workflows, enabling developers to deploy applications faster while ensuring scalability and reliability. The ability to automatically manage infrastructure components and execute code in response to specific events aligns with modern DevOps strategies. As enterprises continue to streamline software development lifecycles, serverless computing is expected to become an integral part of digital transformation initiatives. For instance, CyberArk leveraged AWS serverless technologies to accelerate its development process, reducing the time to launch new services from 18 weeks to just 3 hours. This was achieved by adopting a serverless-first approach, simplifying cloud resource management and enhancing developer agility.
Market Trends:
Expansion of Multi-Cloud and Hybrid Cloud Strategies
Enterprises in the U.S. are increasingly adopting multi-cloud and hybrid cloud environments, driving the expansion of serverless computing solutions. Organizations are leveraging serverless architectures across multiple cloud service providers to avoid vendor lock-in and enhance resilience. For instance, AWS provides solutions for hybrid and multicloud environments, enabling businesses to extend AWS cloud operations across different platforms for secure and seamless management, compliance, and observability. Hybrid cloud models, which combine on-premises infrastructure with public cloud services, are also gaining traction as businesses seek greater flexibility in managing workloads. This trend is prompting cloud providers to enhance interoperability and develop serverless solutions that seamlessly integrate across different platforms, enabling businesses to deploy applications in diverse environments.
Advancements in Edge Computing and Serverless Integration
The integration of serverless computing with edge computing is transforming how organizations process data closer to its source. With the rise of Internet of Things (IoT) devices, 5G networks, and real-time analytics, enterprises are utilizing edge-based serverless frameworks to minimize latency and optimize performance. Edge serverless solutions allow applications to execute functions closer to users, reducing the reliance on centralized cloud data centers. For example, AWS, STMicroelectronics, and LACROIX are collaborating to enhance edge AI capabilities, enabling devices to operate more autonomously and securely with no sensitive data transfer. This approach is particularly beneficial for industries such as healthcare, autonomous vehicles, and smart cities, where real-time decision-making is crucial. As demand for low-latency computing grows, edge-enabled serverless architectures are expected to gain widespread adoption.
Rising Popularity of Function-as-a-Service (FaaS) Offerings
The increasing adoption of Function-as-a-Service (FaaS) is a key trend in the U.S. serverless computing market. Businesses are embracing FaaS platforms to develop and deploy event-driven applications without managing underlying infrastructure. AWS Lambda, for instance, is a leading FaaS platform that allows developers to execute individual functions in response to specific triggers, enhancing operational efficiency and simplifying application scaling. The ability to execute individual functions in response to specific triggers enhances operational efficiency and simplifies application scaling. Leading cloud providers, including AWS Lambda, Google Cloud Functions, and Microsoft Azure Functions, continue to introduce new capabilities, such as advanced debugging tools, enhanced security measures, and broader language support. This evolution is driving greater adoption of serverless computing across diverse industry verticals, including financial services, e-commerce, and media streaming.
Emphasis on Security and Compliance in Serverless Architectures
As enterprises increasingly rely on serverless computing, concerns regarding security and regulatory compliance are gaining prominence. Organizations are implementing enhanced security frameworks to protect serverless applications from unauthorized access, misconfigurations, and runtime vulnerabilities. Cloud providers are introducing built-in security features such as automated encryption, identity and access management (IAM) controls, and serverless security monitoring tools. Additionally, businesses operating in regulated industries, including healthcare and finance, are prioritizing compliance with industry standards such as HIPAA and PCI DSS. For healthcare organizations, ensuring HIPAA compliance is paramount. Serverless architectures must implement robust security controls to protect patient data, including access controls, data encryption, and regular security audits to verify compliance. The growing focus on security and compliance is shaping the development of serverless platforms, ensuring robust protection for mission-critical applications.
Market Challenges Analysis:
Latency and Performance Limitations
Despite its advantages, serverless computing faces challenges related to latency and performance variability. Cold start delays, which occur when serverless functions take time to initialize after being idle, can impact application responsiveness. This issue is particularly problematic for real-time applications, such as financial transactions and high-frequency trading, where low latency is critical. Additionally, since serverless platforms are fully managed by cloud providers, businesses have limited control over performance optimization, making it difficult to predict execution times and ensure consistent service levels.
Security and Compliance Concerns
Security remains a significant challenge in the adoption of serverless computing, as applications rely heavily on third-party cloud providers. The shared responsibility model means businesses must ensure proper configurations to prevent security breaches, such as unauthorized access or data leaks. Serverless architectures also increase the attack surface, with potential risks related to insecure APIs, misconfigured permissions, and dependency vulnerabilities. Moreover, industries with strict compliance requirements, such as healthcare and finance, face difficulties in ensuring regulatory adherence when using multi-tenant serverless environments.
Vendor Lock-in and Integration Challenges
The reliance on proprietary serverless frameworks from cloud providers like AWS, Microsoft Azure, and Google Cloud presents vendor lock-in risks for enterprises. Migrating serverless applications between different cloud environments can be complex due to differences in execution models, APIs, and tooling. Businesses that invest heavily in a single provider’s ecosystem may find it challenging to switch providers without significant redevelopment efforts. Additionally, integrating serverless applications with existing on-premises systems or hybrid cloud environments can be difficult, requiring specialized solutions to ensure seamless interoperability.
Limited Observability and Debugging Complexity The serverless computing model abstracts infrastructure management, but this creates challenges in monitoring and debugging applications. Traditional performance monitoring tools often lack visibility into serverless functions, making it difficult to diagnose issues and optimize execution times. Debugging distributed applications running on serverless platforms requires advanced tools and expertise, increasing operational complexity. As enterprises scale their serverless workloads, the need for improved observability solutions becomes critical to maintaining application reliability and performance.
Market Opportunities:
The U.S. serverless computing market presents significant opportunities as businesses increasingly adopt cloud-native technologies to enhance agility, cost efficiency, and scalability. The growing demand for real-time data processing, AI-driven automation, and IoT integration is driving enterprises to embrace serverless architectures. As industries such as healthcare, finance, retail, and media seek to optimize operations, serverless computing enables organizations to develop and deploy applications with minimal infrastructure management. The rapid expansion of edge computing further amplifies opportunities, as serverless frameworks integrated with edge networks enhance performance and reduce latency. Additionally, the rise of low-code and no-code development platforms is fueling adoption among small and medium-sized enterprises (SMEs), allowing businesses with limited technical expertise to leverage serverless capabilities.
The increasing focus on serverless security and compliance solutions presents another key opportunity in the market. As organizations navigate data privacy regulations and industry-specific compliance requirements, demand for enhanced serverless monitoring, security automation, and policy-driven governance tools is rising. Additionally, advancements in Function-as-a-Service (FaaS) platforms and multi-cloud interoperability are expanding opportunities for enterprises looking to adopt hybrid cloud and multi-cloud strategies. Cloud providers are introducing enhanced serverless frameworks, supporting new programming languages and extending integration capabilities to facilitate seamless adoption across diverse industries. As more enterprises prioritize digital transformation and shift to cloud-first strategies, the serverless computing market in the U.S. is poised for continued expansion, presenting significant growth potential for technology providers, developers, and enterprises alike.
Market Segmentation Analysis:
The U.S. serverless computing market is segmented by service model, deployment model, organization size, and end-user industry, each contributing to market growth and adoption.
By service model, Function-as-a-Service (FaaS) dominates due to its ability to execute event-driven applications without infrastructure management, enabling real-time scalability. Backend-as-a-Service (BaaS) is also gaining traction, particularly in mobile and web application development, as businesses leverage managed backend services for data storage, authentication, and cloud integration.
By deployment model, public cloud holds the largest share, driven by enterprises seeking cost efficiency and high availability. Private cloud adoption is increasing among industries with stringent security and compliance requirements, such as healthcare and finance. Hybrid cloud is emerging as a preferred option for businesses balancing on-premises control and cloud scalability, enabling seamless workload distribution.
By organization size, large enterprises lead adoption due to their ability to integrate serverless computing with DevOps, AI, and big data analytics. However, SMEs are rapidly embracing serverless solutions, benefiting from cost reduction, simplified infrastructure management, and enhanced application scalability.
By end-user industry, the IT & telecommunication sector drives demand as businesses shift to cloud-native development. The BFSI industry leverages serverless for real-time fraud detection and risk assessment. Healthcare is expanding adoption for patient data analytics and telemedicine applications, while retail & e-commerce utilize serverless computing for dynamic customer engagement and personalized experiences. The others category includes manufacturing and logistics, where serverless enhances automation and IoT-driven operations.
Segmentation:
By Service Model
- Function-as-a-Service (FaaS)
- Backend-as-a-Service (BaaS)
By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
By Organization Size
- Small and Medium-sized Enterprises (SMEs)
- Large Enterprises
By End-User Industry
- BFSI (Banking, Financial Services, and Insurance)
- IT & Telecommunication
- Healthcare
- Retail & E-commerce
- Others
Regional Analysis:
West Coast Leading Adoption with Strong Market Share
The West Coast holds the largest share of the U.S. serverless computing market, accounting for approximately 35% of total market revenue. This dominance is driven by the presence of leading cloud service providers, technology firms, and startups in California, Washington, and Oregon. Silicon Valley continues to be a key innovation hub, with major cloud vendors such as Amazon Web Services (AWS), Microsoft Azure, and Google Cloud spearheading advancements in serverless computing. The high concentration of enterprises in software development, AI, and big data analytics further fuels adoption in this region. Additionally, the growing demand for real-time application deployment, scalable cloud solutions, and AI-driven automation is accelerating the expansion of serverless computing across industries, including media streaming, gaming, and e-commerce.
East Coast Driving Growth in Financial Services and Healthcare
The East Coast holds a significant market share of approximately 28%, with adoption primarily driven by the financial services, healthcare, and retail sectors. States such as New York, Massachusetts, and Virginia are leading investments in cloud-based infrastructure and serverless computing solutions to enhance operational efficiency and compliance with regulatory standards. The financial sector in New York City is leveraging serverless computing for real-time transaction processing, fraud detection, and risk assessment models, while healthcare organizations in Massachusetts are utilizing serverless frameworks for patient data analytics and telemedicine applications. The presence of key data centers and increasing government-backed cloud initiatives further contribute to the region’s growing adoption of serverless technologies.
Midwest Experiencing Steady Growth with Expanding Cloud Infrastructure
The Midwest region accounts for 20% of the U.S. serverless computing market, supported by the growing expansion of cloud data centers and the rising adoption of serverless solutions in manufacturing, logistics, and agritech. States such as Illinois, Ohio, and Minnesota are witnessing increased investment in multi-cloud and hybrid cloud strategies, allowing businesses to modernize their IT infrastructure with cost-effective serverless models. As enterprises in the Midwest shift toward digital transformation, the demand for serverless computing in supply chain optimization, predictive maintenance, and IoT-driven automation is growing. Cloud providers are also focusing on enhancing serverless interoperability and edge computing capabilities, positioning the region for further market expansion.
Southern States Gaining Momentum with SME Adoption
The Southern region holds a 17% market share, with Texas, Florida, and Georgia emerging as key growth areas. The increasing adoption of serverless computing by small and medium-sized enterprises (SMEs) and startups is driving market expansion in this region. Texas, in particular, is home to a growing tech ecosystem, with businesses leveraging serverless frameworks for mobile app development, customer engagement platforms, and AI-powered analytics. Additionally, the energy and telecommunications industries in the South are integrating serverless computing to improve operational efficiency and reduce infrastructure costs. With cloud providers expanding data center operations in Austin, Atlanta, and Miami, the Southern region is expected to witness accelerated adoption of serverless solutions in the coming years.
Key Player Analysis:
- Amazon Web Services (AWS)
- Microsoft Azure
- Google Cloud Platform
- IBM Cloud
- Oracle Cloud
- VMware
- Cloudflare Workers
- SAP Cloud Platform
- Red Hat OpenShift
- Salesforce
Competitive Analysis:
The U.S. serverless computing market is highly competitive, with major cloud providers Amazon Web Services (AWS), Microsoft Azure, and Google Cloud dominating the landscape. AWS Lambda leads the market with its extensive ecosystem, seamless integration with AWS services, and advanced automation capabilities. Microsoft Azure Functions competes by offering strong enterprise adoption, hybrid cloud support, and deep integration with Microsoft’s developer tools. Google Cloud Functions is gaining traction with its focus on AI, machine learning, and real-time analytics. Beyond these key players, companies such as IBM Cloud, Oracle Cloud, and Cloudflare Workers are expanding their serverless offerings to capture niche markets, particularly in hybrid cloud and edge computing solutions. For instance, Cloudflare Workers is a serverless platform that leverages edge computing to provide instant data access and processing. Cloudflare’s D1 serverless database, enables developers to store and query data at the edge, reducing latency and improving performance for real-time applications. Startups and open-source platforms are also entering the market, providing specialized serverless tools for DevOps, security, and multi-cloud strategies. As demand for cost efficiency, scalability, and automation grows, competition will intensify, driving further innovation in serverless computing solutions.
Recent Developments:
- In April 2024, Cloudflare announced the acquisition of Baselime, a serverless observability startup. This acquisition aims to improve the developer experience by providing actionable alerts, AI-driven debugging assistants, and enhanced query engines for serverless platforms. The integration of Baselime's technology into Cloudflare's platform will enable developers to optimize performance, investigate bugs, and identify issues in serverless applications more effectively.
- Microsofthas expanded its serverless offerings with the integration of Neon Serverless Postgres as an Azure Native Integration. Announced on December 3, 2024, this integration combines the flexibility of Neon's serverless Postgres database service with Azure's robust cloud infrastructure. This partnership enhances the developer experience by providing instant provisioning, efficient scaling, and integrated workflows, particularly beneficial for AI developers seeking scalable and cost-efficient database solutions.
- In March 2025, Amazon Web Services expanded the availability of Amazon OpenSearch Serverlessto the AWS US West (N. California) and Europe (Stockholm) regions. This expansion allows users to run search and analytics workloads without managing infrastructure, using OpenSearch Compute Units (OCUs) for cost control.
- In December 2024, Microsoft Azure introduced serverless GPUsin Azure Container Apps, utilizing NVIDIA A100 and T4 GPUs for scalable AI inferencing and ML tasks. This enhancement provides flexible deployment, scale-to-zero capabilities, and seamless Azure integration.
Market Concentration & Characteristics:
The U.S. serverless computing market is highly concentrated, with a few dominant cloud providers—Amazon Web Services (AWS), Microsoft Azure, and Google Cloud—controlling a significant share of the market. These companies offer comprehensive serverless platforms with integrated development tools, automation capabilities, and enterprise-grade security features. Their extensive cloud infrastructure, global data centers, and strategic partnerships position them as market leaders, limiting the entry of smaller competitors. Despite this concentration, the market is characterized by rapid innovation, increasing adoption of multi-cloud and hybrid cloud strategies, and growing demand for edge computing integration. The rise of Function-as-a-Service (FaaS) and event-driven architectures is reshaping software development, making serverless computing a key component of modern IT strategies. Additionally, emerging vendors and open-source initiatives are introducing specialized serverless solutions, particularly in DevOps, API management, and AI-driven automation, fostering a dynamic and evolving competitive landscape.
Report Coverage:
The research report offers an in-depth analysis based on service model, deployment model, organization size, and end-user industry, It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The S. serverless computing market is projected to grow at a steady pace, driven by increasing adoption of cloud-native development and microservices architectures.
- Advancements in AI and machine learning will enhance serverless capabilities, enabling more efficient real-time data processing and automation.
- Multi-cloud and hybrid cloud adoption will rise, as enterprises seek flexibility and avoid vendor lock-in, driving demand for cross-platform serverless solutions.
- Edge computing integration will accelerate, reducing latency and enhancing performance for IoT, 5G, and real-time applications.
- Security and compliance innovations will strengthen serverless adoption, with enhanced encryption, access controls, and regulatory compliance solutions.
- Serverless cost optimization tools will gain traction, helping businesses manage resource allocation and optimize computing expenses.
- Expansion of Function-as-a-Service (FaaS) offerings will drive adoption, with broader language support and improved developer tools.
- SME adoption will increase, supported by low-code/no-code serverless platforms that simplify application development.
- Industry-specific serverless solutions will emerge, catering to healthcare, finance, retail, and telecom sectors.
- Strategic investments and acquisitions by cloud providers will shape market consolidation, fostering continuous innovation and expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Serverless Computing Market?
What factors are driving the growth of the U.S. Serverless Computing Market?
What are the key segments within the U.S. Serverless Computing Market?
What are some challenges faced by the U.S. Serverless Computing Market?
Who are the major players in the U.S. Serverless Computing Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Serverless Computing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. Serverless Computing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,677.98 million → 2032: USD 7,220.65 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Serverless Computing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Serverless Computing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Serverless Computing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. Serverless Computing Market Drivers
- 3.3 U.S. Serverless Computing Market Restraints & Challenges
- 3.4 U.S. Serverless Computing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Serverless Computing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Serverless Computing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Serverless Computing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Serverless Computing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. Serverless Computing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. Serverless Computing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Serverless Computing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. Serverless Computing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. Serverless Computing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Serverless Computing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. Serverless Computing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. Serverless Computing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. Serverless Computing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. Serverless Computing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. Serverless Computing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. Serverless Computing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. Serverless Computing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. Serverless Computing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. Serverless Computing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
