
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
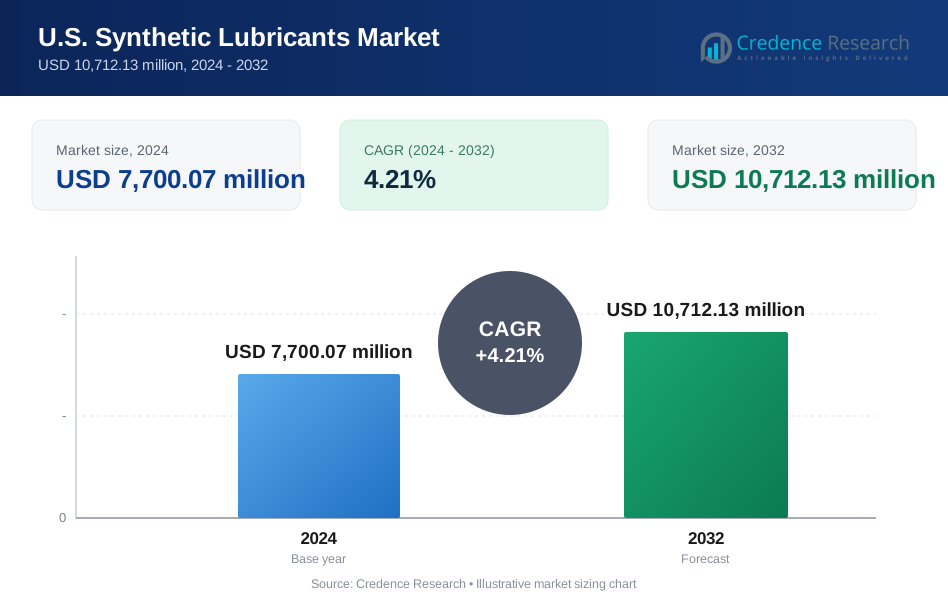
| U.S. Synthetic Lubricants Market Size 2024 | USD 7,700.07 million |
| U.S. Synthetic Lubricants Market, CAGR | 4.21% |
| U.S. Synthetic Lubricants Market Size 2032 | USD 10,712.13 million |
Market Overview
The U.S. Synthetic Lubricants Market is projected to grow from USD 7,700.07 million in 2024 to an estimated USD 10,712.13 million by 2032, with a compound annual growth rate (CAGR) of 4.21% from 2025 to 2032. This growth reflects the increasing demand for high-performance lubricants across various industries, driven by advancements in technology and rising consumer preferences for longer-lasting, more efficient products.
Key drivers of this market include the rising demand for energy-efficient products, a shift toward longer oil change intervals, and the growing trend of environmentally-friendly lubricants. Additionally, advancements in formulation technology are leading to the development of more efficient synthetic lubricants that cater to specific industrial and automotive needs. The increasing adoption of electric vehicles (EVs) and stricter environmental regulations are also contributing to the market's growth, creating opportunities for manufacturers to develop products that meet sustainability standards.
Geographically, North America holds a significant share of the U.S. Synthetic Lubricants Market, with the U.S. being the dominant player. The market is highly competitive, with key players such as ExxonMobil, Chevron, Royal Dutch Shell, and BP driving innovation and product development. These companies focus on enhancing performance characteristics and sustainability to meet the evolving demands of the market.
Market Insights
- The U.S. Synthetic Lubricants Market is projected to grow from USD 7,700.07 million in 2024 to USD 10,712.13 million by 2032, with a CAGR of 4.21% from 2025 to 2032, driven by increasing demand across automotive, industrial, and aerospace sectors.
- Key drivers include the rising demand for energy-efficient products, longer oil change intervals, and a growing preference for environmentally-friendly lubricants.
- Advancements in lubricant formulations are creating more efficient and sustainable synthetic oils, catering to specific industrial and automotive needs.
- The high cost of synthetic lubricants compared to conventional oils and strong competition from semi-synthetic and mineral oils pose challenges to market growth.
- The U.S. holds the largest share of the North American market, with key regions including the Midwest, South, and Northeast driving demand due to industrial activities and automotive manufacturing.
- The rise in electric and hybrid vehicles is creating new opportunities for specialized synthetic lubricants for EV motors and transmissions.
- Major market players such as ExxonMobil, Chevron, AMSOIL, and Valvoline continue to innovate and expand product offerings to meet the evolving demands for high-performance and sustainable lubricants.
Market Drivers
Rising Demand for High-Performance Lubricants in the Automotive Sector
The automotive sector remains a significant driver for the growth of the U.S. synthetic lubricants market. Over the past few decades, there has been a marked shift towards high-performance lubricants that deliver superior efficiency, reduced friction, and increased engine longevity. Traditional mineral oils are being replaced by synthetic lubricants, which offer better stability and performance under high-temperature conditions. With the growing trend of longer oil change intervals and advancements in automotive technology, synthetic lubricants are becoming essential to meeting these evolving demands. These lubricants provide extended operational life and can withstand more extreme driving conditions, such as those encountered by vehicles in heavy-duty applications.For instance, synthetic lubricants are being increasingly adopted in high-performance vehicles due to their ability to withstand extreme driving conditions, such as those encountered by vehicles in heavy-duty applications. This includes their use in engines and transmissions to improve fuel efficiency and reduce emissions. As a result, automotive manufacturers and consumers alike are increasingly opting for synthetic lubricants to ensure vehicle reliability and improve fuel efficiency. The rise in the production and adoption of electric vehicles (EVs) also plays a role in driving this demand, as synthetic lubricants are essential for EV systems to operate more efficiently. With increasing vehicle production and more stringent environmental regulations, the automotive industry's shift towards synthetic lubricants is expected to continue, boosting market growth.
Environmental Concerns and Stricter Regulations
Environmental concerns regarding pollution and resource conservation have significantly influenced the demand for synthetic lubricants. Conventional mineral oils are known to contain harmful additives and degrade more rapidly than synthetic alternatives. As awareness grows about the environmental impact of lubricants, manufacturers and consumers are increasingly turning to synthetic options that offer better performance and reduced environmental footprint. Synthetic lubricants are designed to have longer service intervals, resulting in fewer oil changes and less waste. Furthermore, they tend to produce fewer emissions, contributing to cleaner air and a reduction in the overall environmental impact of industrial and automotive operations.For example, synthetic lubricants are designed to have longer service intervals, resulting in fewer oil changes and less waste. This aligns with environmental regulations aimed at reducing pollution and conserving resources, as seen in the U.S. government's stricter environmental standards for industrial operations. These regulations encourage the use of lubricants that meet higher performance standards while adhering to eco-friendly guidelines. As a result, industries are now more inclined to switch to synthetic lubricants that help meet sustainability objectives, and this shift is further catalyzing the market's expansion.
Technological Advancements and Product Innovations
The ongoing technological advancements in the formulation and production of synthetic lubricants have been pivotal in shaping the U.S. synthetic lubricants market. These innovations have enabled the development of lubricants that are not only more efficient but also more specialized for a variety of applications across industries such as automotive, aerospace, and manufacturing. The continuous improvement of synthetic lubricant formulations has resulted in products that provide enhanced performance, increased durability, and reduced energy consumption. For example, advanced additives and base oils used in synthetic lubricants improve their ability to reduce wear and tear, maintain a consistent viscosity under extreme temperatures, and prevent oxidation.For instance, advancements in synthetic lubricant formulations have led to the development of biodegradable and non-toxic lubricants. These innovations have made synthetic lubricants more appealing to industries seeking to minimize their ecological footprint, such as the aerospace and automotive sectors. The expansion of research and development (R&D) activities by major lubricant manufacturers has also led to the creation of specialized products designed to cater to the needs of electric vehicles, hybrid engines, and high-performance industrial machinery. These innovations have widened the application scope of synthetic lubricants and fostered increased market demand across diverse sectors.
Growth in Industrial Applications and Manufacturing Sectors
The increasing demand for synthetic lubricants is also driven by their growing applications across various industrial sectors. The manufacturing, aerospace, and construction industries require high-performance lubricants to support heavy machinery and ensure the efficient operation of production equipment. Synthetic lubricants offer superior performance in extreme conditions, such as high pressure, elevated temperatures, and high-speed machinery operations. Their ability to maintain optimal lubrication even under challenging conditions is crucial for industries that rely on complex machinery for production.For example, in the aerospace industry, synthetic lubricants are essential for the efficient functioning of turbines, engines, and other critical components. Their enhanced thermal stability, low volatility, and resistance to degradation ensure the longevity and reliability of aerospace systems, where failure is not an option. Similarly, in the manufacturing sector, synthetic lubricants are increasingly being used in cutting, shaping, and metalworking operations to improve machine performance and prevent wear and tear. These industries are under constant pressure to improve operational efficiency and reduce maintenance costs, and synthetic lubricants are seen as a valuable solution. As industrial sectors continue to evolve and scale, the demand for high-quality lubricants capable of meeting advanced technical requirements is expected to drive continued growth in the synthetic lubricants market.
Market Trends
Shift Towards Bio-based and Eco-friendly Synthetic Lubricants
A significant trend in the U.S. synthetic lubricants market is the growing demand for bio-based and environmentally friendly lubricants. With increasing awareness of climate change, sustainability, and environmental impact, consumers and industries alike are prioritizing products that are biodegradable, non-toxic, and have a minimal environmental footprint. Conventional lubricants often contain harmful chemicals that pose risks to both the environment and human health. In contrast, bio-based synthetic lubricants, which are derived from renewable resources such as vegetable oils, are gaining traction due to their reduced environmental impact and safer disposal options. Many key players in the synthetic lubricants market are focusing on the development of greener alternatives that comply with stricter environmental regulations and meet the sustainability goals set by various industries. As a result, the market is seeing an increase in the production and adoption of lubricants that not only perform well but also contribute to reducing carbon footprints. Furthermore, several companies are introducing eco-friendly lubricants that offer enhanced lubrication performance, longer service intervals, and reduced emissions, making them ideal for industries looking to meet sustainability targets while improving operational efficiency. This shift towards bio-based and environmentally responsible lubricants is likely to continue as environmental concerns become a primary driver of consumer and corporate behavior.
Technological Advancements in Lubricant Formulations
Advancements in technology are continuously shaping the U.S. synthetic lubricants market. New innovations in lubricant formulations are significantly improving the performance characteristics of synthetic oils, driving growth in multiple sectors, particularly automotive, aerospace, and manufacturing. Modern synthetic lubricants are being designed to provide superior protection against wear, corrosion, and friction, even under extreme operating conditions such as high temperatures or heavy loads. One of the most notable trends is the development of multi-functional lubricants that can serve diverse applications, offering improved engine efficiency, fuel economy, and longer service life. These formulations utilize advanced additives, high-quality base oils, and cutting-edge technologies to enhance key attributes such as viscosity, stability, and resistance to degradation. For instance, advancements in nanoparticle and nanotechnology have led to the development of lubricants with improved anti-wear and anti-friction properties, increasing the longevity of machinery and reducing the need for frequent maintenance. The ongoing R&D efforts by lubricant manufacturers are further expanding the range of synthetic lubricants designed for specific applications such as electric vehicles (EVs) and hybrid engines. These technological advancements are creating a more diverse and competitive market, encouraging the development of specialized products for different industries.
Integration of Synthetic Lubricants in Electric and Hybrid Vehicles
The rise of electric vehicles (EVs) and hybrid vehicles is another key trend driving growth in the U.S. synthetic lubricants market. As the automotive industry shifts towards cleaner, more energy-efficient vehicles, synthetic lubricants are increasingly becoming the preferred choice due to their superior performance, energy-saving potential, and reduced environmental impact. While traditional internal combustion engine (ICE) vehicles rely on lubricants to minimize friction between engine parts, electric vehicles (EVs) require lubricants for other systems such as gearboxes, electric motors, and cooling systems. Unlike traditional lubricants used in ICE vehicles, EV lubricants need to offer enhanced thermal stability, low viscosity, and resistance to oxidation, as they are exposed to different operating conditions. These specialized lubricants ensure the efficient performance of EV components, prolong the life of critical parts, and improve overall energy efficiency. Moreover, as hybrid vehicles (which combine internal combustion engines and electric motors) continue to gain popularity, there is growing demand for synthetic lubricants that can function effectively in both systems. The shift towards EVs and hybrids is pushing manufacturers to innovate and create lubricants that cater to the unique requirements of these vehicles, and this trend is expected to continue as the adoption of electric mobility accelerates.
Increase in Preventive Maintenance Practices Across Industries
Another noteworthy trend in the U.S. synthetic lubricants market is the growing emphasis on preventive maintenance practices across various industries, particularly in manufacturing, aerospace, and heavy machinery sectors. As industries increasingly focus on reducing downtime, improving machine reliability, and lowering maintenance costs, the adoption of synthetic lubricants has become a key strategy in achieving these goals. Synthetic lubricants are known for their superior performance under extreme conditions, including high temperatures, heavy loads, and high-pressure environments, making them ideal for industrial applications that rely on heavy machinery and complex systems. Their longer service intervals, greater thermal stability, and reduced friction contribute to fewer equipment breakdowns, reduced energy consumption, and extended asset life. Industries are realizing the long-term cost benefits of using high-performance synthetic lubricants, which help minimize wear and tear on machinery, leading to fewer repairs and longer equipment lifespans. Moreover, the use of synthetic lubricants allows for the optimization of operational efficiency, which is a crucial factor in industries such as aerospace, manufacturing, and construction, where uptime is critical. As a result, many industrial operators are increasingly integrating synthetic lubricants into their maintenance strategies to maximize the efficiency of their machinery, reduce maintenance costs, and improve overall operational productivity.
Market Challenges
High Cost of Synthetic Lubricants
One of the significant challenges faced by the U.S. synthetic lubricants market is the higher cost compared to conventional lubricants. Synthetic oils are produced using more advanced and complex manufacturing processes, which increases their production costs. These higher costs are often passed on to the consumers, making synthetic lubricants more expensive than their mineral oil counterparts. While synthetic lubricants offer enhanced performance and longer service life, the initial price premium can deter price-sensitive consumers, especially in industries with tight operating budgets or in the automotive aftermarket segment, where cost considerations play a significant role in purchasing decisions. Additionally, many small- and medium-sized businesses may not see the immediate value in investing in synthetic lubricants due to the higher upfront cost, despite the long-term savings on maintenance and operational efficiency. Overcoming this price barrier remains a challenge for manufacturers, who need to communicate the long-term benefits of synthetic lubricants to customers while also exploring ways to reduce production costs through innovation and economies of scale.
Competition from Conventional and Semi-Synthetic Lubricants
Another challenge to the growth of the synthetic lubricants market is the strong competition from conventional and semi-synthetic lubricants. While synthetic lubricants offer superior performance in terms of durability, efficiency, and environmental impact, many businesses and consumers still opt for conventional and semi-synthetic alternatives due to their relatively lower cost and sufficient performance for most standard applications. Conventional lubricants continue to dominate sectors where the requirements for high-performance oils are not as stringent, such as in older vehicles and machinery. Furthermore, semi-synthetic lubricants, which combine both mineral oils and synthetic base oils, offer a compromise between cost and performance, making them an appealing choice for those looking for more affordable options with improved performance over conventional oils. The prevalence of these alternatives challenges synthetic lubricant manufacturers to prove the added value of their products, particularly as consumers and businesses weigh cost against performance benefits.
Market Opportunities
Growing Demand for Electric Vehicles (EVs) and Hybrid Vehicles
The rapid expansion of the electric vehicle (EV) and hybrid vehicle market presents a significant opportunity for the U.S. synthetic lubricants market. As the automotive industry continues to shift towards cleaner and more energy-efficient vehicles, the demand for specialized lubricants is increasing. Synthetic lubricants play a crucial role in optimizing the performance of electric motors, gearboxes, and other critical components in EVs. These vehicles require lubricants with enhanced thermal stability, reduced viscosity, and improved oxidation resistance. The growing adoption of electric and hybrid vehicles, coupled with government incentives promoting clean energy and sustainability, offers a promising avenue for lubricant manufacturers to develop tailored solutions that meet the unique needs of these vehicles. As the EV market continues to grow, the demand for high-performance synthetic lubricants is expected to increase, creating a lucrative opportunity for manufacturers to expand their product portfolios and tap into this emerging segment.
Advancements in Industrial Applications and Preventive Maintenance Practices
The increasing adoption of preventive maintenance strategies across various industrial sectors, including aerospace, manufacturing, and construction, creates a significant market opportunity for synthetic lubricants. Industrial machinery and equipment require lubricants that can perform under extreme conditions, such as high pressures, temperatures, and heavy loads, all of which synthetic lubricants excel at. As businesses continue to focus on minimizing downtime and maximizing operational efficiency, the demand for high-performance synthetic lubricants is growing. The extended service life, enhanced efficiency, and reduced maintenance costs associated with synthetic lubricants position them as a valuable solution in industries that rely on heavy machinery. As industries invest in maintenance strategies aimed at reducing wear and tear on equipment, the U.S. synthetic lubricants market stands to benefit from increased demand in these high-value industrial applications.
Market Segmentation Analysis
By Type
The synthetic lubricants market is categorized into Polyalphaolefins (PAO), Esters, and Polyalkylene Glycols (PAG). PAO dominates the market due to its superior oxidative stability, excellent viscosity index, and high thermal performance, making it suitable for a wide range of automotive and industrial applications. Esters, known for their biodegradability and high lubricity, are increasingly adopted in applications demanding environmental compliance and superior high-temperature stability. PAGs are gaining traction, especially in industrial applications, due to their excellent water solubility, high lubricating properties, and resistance to thermal degradation. The continued development of advanced formulations within these types is expected to further enhance their adoption across various industries.
By Product Type
The market is further segmented by product type into Engine Oils, Heat Transfer Fluids (HTF), Transmission Fluids, Metalworking Fluids, and Others. Engine oils hold the largest market share, driven by the automotive sector's demand for high-performance lubricants that enhance engine efficiency and longevity. Heat Transfer Fluids (HTF) are essential in industrial processes that require precise temperature control, contributing to their steady demand. Transmission fluids are critical for automotive and heavy machinery applications, ensuring smoother operation and reduced wear. Metalworking fluids are increasingly used in manufacturing sectors for lubrication, cooling, and protection of metal parts during machining processes. The "Others" segment includes niche applications such as greases and compressor oils, contributing to the market’s diversification.
Segments
Based on Type
- PAO
- Esters
- PAG
Based on Product Type
- Engine Oil
- Heat Transfer Fluids (HTF)
- Transmission Fluids
- Metalworking Fluids
- Others
Based on End User
- Power Generation
- Automotive and Other Transportation
- Metallurgy and Metalworking
- Chemical Manufacturing
- Others
Based on Region
- Midwest
- South
- Northeast
- West
Regional Analysis
Northeast Region (23%)
The Northeast region holds a significant share of the U.S. synthetic lubricants market, contributing approximately 23% to the overall market. This region is home to several key industries, including power generation, automotive, and chemical manufacturing, which are major consumers of synthetic lubricants. The presence of major cities with strong automotive manufacturing facilities, along with a growing trend towards environmentally sustainable practices, drives demand for high-performance lubricants in these sectors. Additionally, stringent environmental regulations in states like New York and Massachusetts are pushing industries toward using eco-friendly synthetic lubricants, further propelling market growth in this region.
Midwest Region (30%)
The Midwest region is the largest contributor to the U.S. synthetic lubricants market, accounting for around 30% of the market share. This region is a hub for automotive and heavy machinery manufacturing, making it a key area for synthetic lubricant demand. The automotive sector, with its increasing focus on high-performance oils for internal combustion engines and the growing adoption of electric vehicles (EVs), significantly drives lubricant consumption. Additionally, industries such as metalworking and manufacturing, which require lubricants for machinery and industrial equipment, further contribute to the Midwest’s market dominance. The Midwest’s strong manufacturing infrastructure continues to be a major driver for the growth of synthetic lubricants.
Key players
- ExxonMobil Corporation
- Chevron Corporation
- AMSOIL Inc.
- Evonik Industries AG
- Valvoline Inc
Competitive Analysis
The U.S. synthetic lubricants market is highly competitive, with major players such as ExxonMobil Corporation, Chevron Corporation, AMSOIL Inc., Evonik Industries AG, and Valvoline Inc. leading the way. ExxonMobil and Chevron dominate the market with extensive product portfolios, offering high-performance lubricants for various sectors, including automotive and industrial applications. AMSOIL Inc. has carved a niche with its synthetic oils, particularly in the automotive aftermarket, capitalizing on its reputation for high-quality products and extended oil change intervals. Evonik Industries AG, while a smaller player, focuses on innovative chemical additives that enhance the performance of synthetic lubricants. Valvoline Inc., known for its wide distribution and strong presence in the automotive sector, continues to expand its offerings with an emphasis on sustainability and eco-friendly lubricants. These players remain competitive by focusing on product innovation, technological advancements, and strategic partnerships to meet growing market demands and consumer preferences for high-quality, sustainable lubricants.
Recent Developments
- In November 2024, LANXESS launched an environmentally sustainable refrigeration lubricant, Everest ESR 220, which is not specifically U.S.-focused but indicates the company's commitment to sustainable synthetic lubricants globally.
- In August 2023, Valvoline Global introduced a new portfolio of ValvolineTM 4-stroke Full Synthetic Premium Motor Oil for marine and powersports applications, showcasing innovation in synthetic lubricants.
- In April 2023, Chevron demonstrated a new gasoline blend with more than 50% renewable content, highlighting its focus on lower-carbon fuels, which could influence future lubricant innovations.
Market Concentration and Characteristics
The U.S. synthetic lubricants market is moderately concentrated, with several key players dominating the market, including ExxonMobil Corporation, Chevron Corporation, AMSOIL Inc., Evonik Industries AG, and Valvoline Inc. These companies possess extensive research and development capabilities, large-scale production facilities, and strong distribution networks that allow them to maintain significant market shares. The market is characterized by a high level of competition, with companies focusing on product innovation, performance enhancements, and sustainability to meet the evolving needs of automotive, industrial, and consumer sectors. Additionally, there is a growing trend toward eco-friendly and high-performance lubricants, which has prompted key players to adapt their offerings to align with consumer preferences for longer-lasting, energy-efficient, and environmentally responsible products. As a result, the market continues to evolve, with both established brands and emerging players competing to capture a share of the expanding demand for synthetic lubricants.
Report Coverage
The research report offers an in-depth analysis based on Type, Product Type, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- As industries continue to prioritize efficiency and longevity, the demand for high-performance synthetic lubricants is expected to rise, particularly in the automotive and manufacturing sectors.
- The shift toward electric and hybrid vehicles will drive the demand for specialized synthetic lubricants, with a focus on electric motor oils and efficient gear lubricants designed for these vehicles.
- With growing environmental awareness, the market will see an increased shift towards bio-based and biodegradable lubricants, as industries and consumers seek eco-friendly alternatives to traditional oils.
- Advances in nanotechnology and synthetic base oil formulations will result in even higher-performing lubricants, meeting the needs of industries requiring extreme temperature and pressure resistance.
- Synthetic lubricants will continue to gain traction in industrial applications such as metalworking, power generation, and aerospace, where high performance and reliability are critical.
- As industries increasingly adopt preventive maintenance practices to reduce downtime, demand for synthetic lubricants will grow, as they extend the service life of machinery and equipment.
- Stricter regulations on emissions and sustainability will drive the development and adoption of synthetic lubricants that help industries comply with environmental standards and improve energy efficiency.
- The chemical and petrochemical industries will continue to rely on synthetic lubricants to improve process efficiency and extend the life of machinery used in these high-demand sectors.
- The aftermarket automotive sector will see a steady increase in the demand for synthetic lubricants as consumers continue to seek high-quality oils that offer better performance and longer intervals between oil changes.
- While the U.S. remains the dominant player, regional demand for synthetic lubricants will grow as manufacturers and industries in smaller markets increasingly adopt these high-performance oils.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the U.S. Synthetic Lubricants Market in 2023 and 2032?
What are the key drivers of the U.S. Synthetic Lubricants Market?
Which industries are driving the growth of the synthetic lubricants market?
Who are the leading players in the U.S. Synthetic Lubricants Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Synthetic Lubricants Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. Synthetic Lubricants Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 7,700.07 million → 2032: USD 10,712.13 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Synthetic Lubricants Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Synthetic Lubricants Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Synthetic Lubricants Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. Synthetic Lubricants Market Drivers
- 3.3 U.S. Synthetic Lubricants Market Restraints & Challenges
- 3.4 U.S. Synthetic Lubricants Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Synthetic Lubricants Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Synthetic Lubricants Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Synthetic Lubricants category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Synthetic Lubricants Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. Synthetic Lubricants Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. Synthetic Lubricants market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Synthetic Lubricants Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. Synthetic Lubricants Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. Synthetic Lubricants Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Synthetic Lubricants (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. Synthetic Lubricants Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. Synthetic Lubricants Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. Synthetic Lubricants Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. Synthetic Lubricants Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. Synthetic Lubricants Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. Synthetic Lubricants Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. Synthetic Lubricants Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. Synthetic Lubricants Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. Synthetic Lubricants Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
