
Replacement buyers set the pace for U.S. tire demand
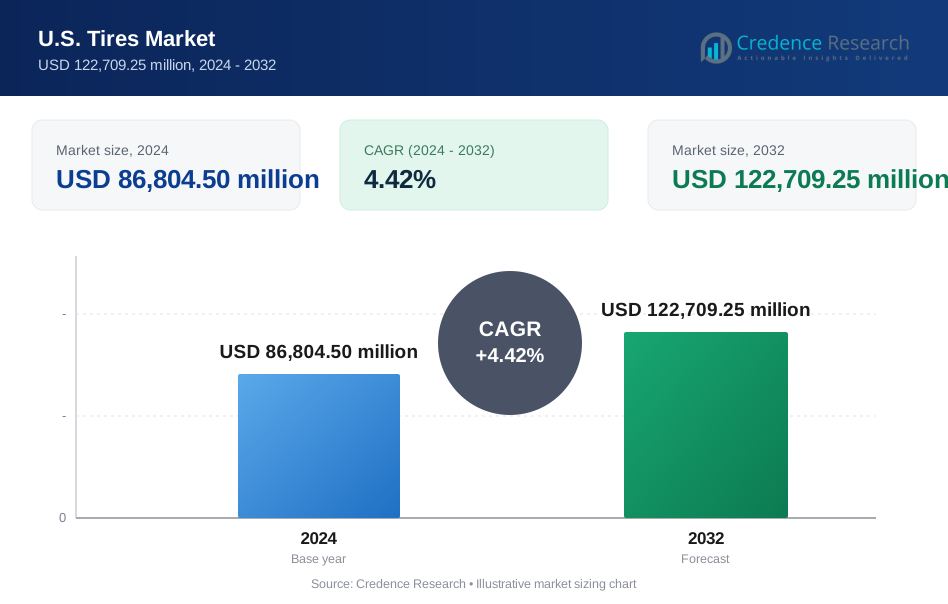
The U.S. tires market was valued at USD 70.80 billion in 2025 and is projected to increase from USD 73.93 billion in 2026 to USD 109.11 billion by 2035, registering a CAGR of 4.42% during 2026–2035. Demand rests mainly on replacement purchases from an aging vehicle fleet, because replacement shipments far exceed original equipment units each year. The South held the largest regional share at 39.5% in 2025, supported by a population of about 133.8 million and a dense base of tire plants. The South is also the fastest-growing region at 4.70% a year, as residents and new factories continue moving there. Section 232 duties of 25% on imported passenger, light truck and truck tires, phased in during May and November 2025, reshaped pricing and sourcing across the supply chain. As a result, value is expected to outpace volume, since the U.S. Tire Manufacturers Association expects unit shipments to slip in 2026 while price and product mix move higher.
What does the U.S. tire market include, and who buys these tires?
The report counts new tires sold in the United States for passenger cars, light trucks, trucks and buses, motorcycles and special vehicles, valued at end-buyer prices. Buyers include automakers purchasing original equipment, motorists replacing worn tires through dealers and online sellers, and commercial fleets buying on contract. Both radial and bias constructions are counted, although radial designs dominate on-highway vehicles.
Retreaded tires, aircraft tires, wheels and standalone repair or maintenance services are excluded from the estimate. The value chain runs from natural and synthetic rubber suppliers to domestic plants and importers, then through distributors, dealers and online platforms to fleets and motorists.
U.S. Tires Market Insights
- The U.S. tires market reaches USD 109.11 billion by 2035 from USD 70.80 billion in 2025, growing at 4.42% a year through price and product mix more than unit volume.
- The South led regional demand with 39.5% of 2025 value, reflecting the largest population of any Census region and heavy tire-plant investment across Tennessee and South Carolina.
- Replacement demand held 90.0% of 2025 value, and USTMA counted 284.3 million replacement shipments that year against 52.1 million original equipment units.
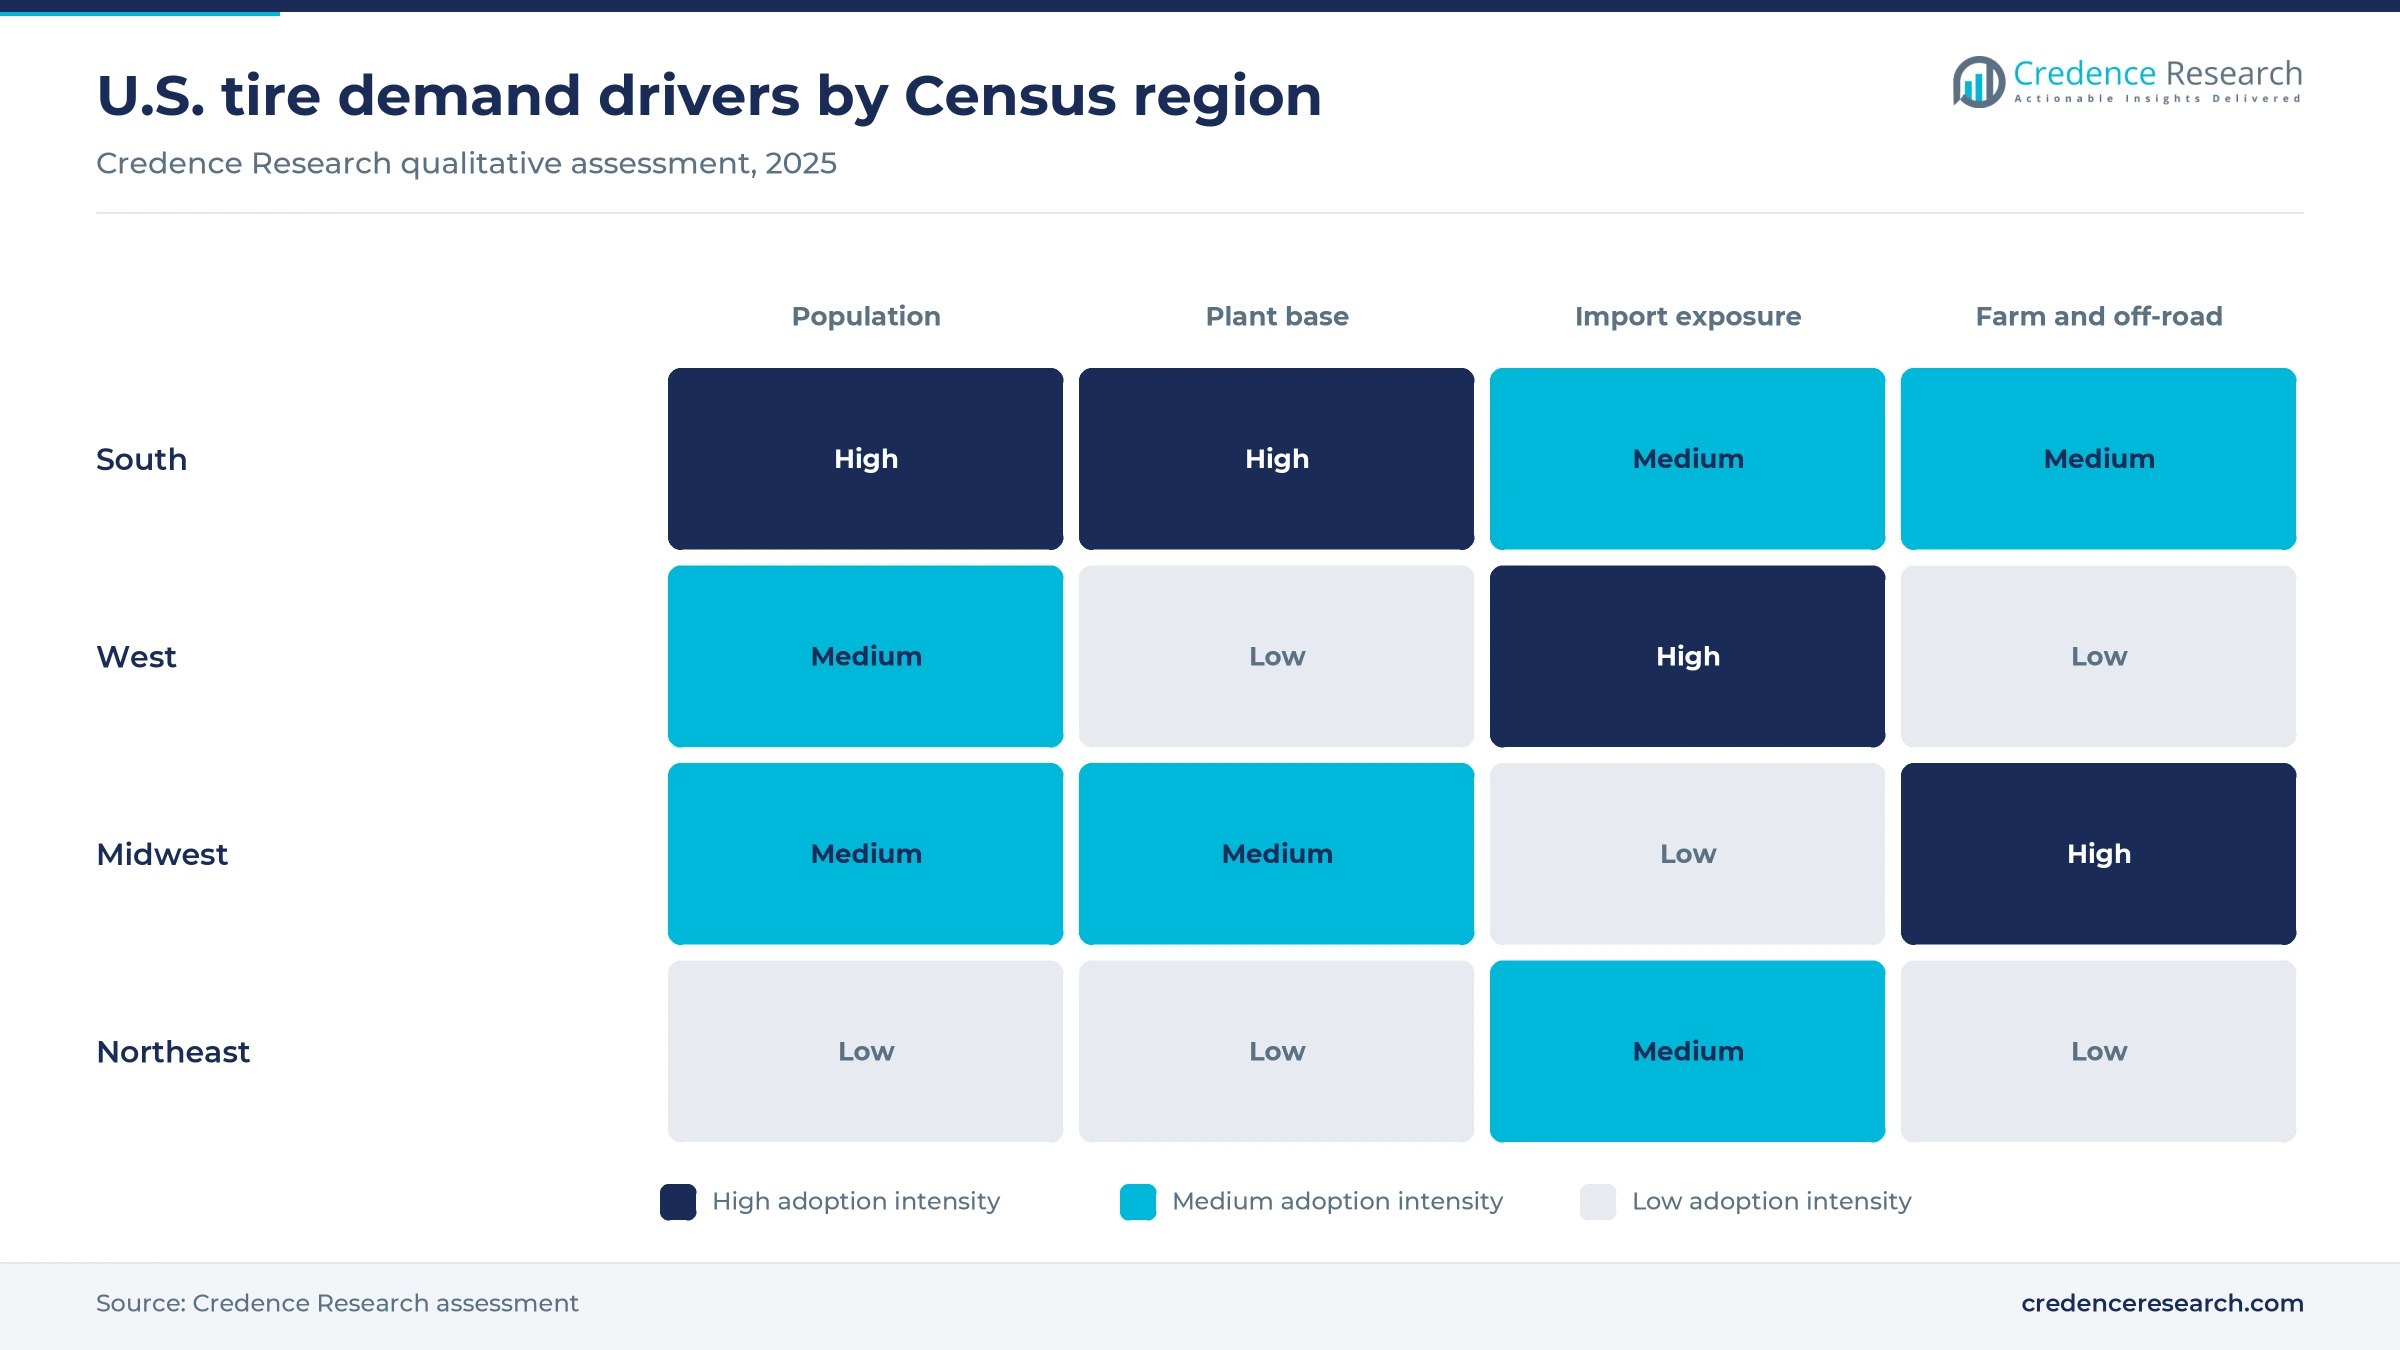
- Import duties of 25% took effect on passenger tires in May 2025 and on truck tires in November 2025, pushing suppliers to raise prices and localize output.
- Competition increasingly turns on local capacity, as Hankook expands Clarksville, Tennessee, while Bridgestone and Sumitomo closed older American plants in 2024 and 2025 and Yokohama closed Salem in March 2026.
Passenger tires and replacement sales hold top shares
Why do passenger car tires lead while light truck tires grow fastest?
Based on vehicle type, the market is categorized into passenger car, light truck, truck and bus, special vehicle and motorcycle tires. Passenger Car Tires led with 62.5% of 2025 value because USTMA counted 221.9 million replacement and 41.3 million original equipment passenger units that year. Light Truck Tires grow fastest at 5.25% a year, as S&P Global Mobility reported that passenger cars fell below 100 million of about 289 million vehicles in operation. That mix moves spending toward larger and costlier fitments across the fleet. Special vehicle supply also changed when Yokohama bought the Goodyear off-the-road tire business in February 2025.
Why does replacement dominate tire spending in the United States?
Based on demand, the market is categorized into replacement and OEM sales. Replacement led with 90.0% of 2025 value because shipment data from USTMA shows 284.3 million replacement units against 52.1 million original equipment units. Replacement also grows fastest at 4.45% a year, as S&P Global Mobility put the average light vehicle age at 12.8 years and the passenger car average at 14.5 years. OEM volume remains steadier and depends on automaker schedules, although USTMA expects truck fitments to climb 6.2% in 2026 even while passenger fitments ease.
How are dealers and online sellers dividing tire sales?
Based on distribution channel, the market is categorized into dealer and exclusive outlets, online sellers and others. Dealer/Exclusive Outlets led with 67.0% of 2025 value because installation still anchors the purchase, and Goodyear reported about 505 company-owned retail outlets in the Americas for 2025. Online grows fastest at 6.89% a year, as Tire Review reported the online share of replacement sales reaching 14% in the year to February 2023, compared with 9% in 2019. Other channels include mass merchants, warehouse clubs and fleet supply contracts.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Vehicle Type | Passenger Car Tires | 62.5% | Light Truck Tires | 5.25% |
| By Demand | Replacement | 90.0% | Replacement | 4.45% |
| By Distribution Channel | Dealer/Exclusive Outlets | 67.0% | Online | 6.89% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Older vehicles and import duties lift tire spending
An older fleet and record mileage keep wearing tires out
Tire demand follows miles driven and vehicle age more closely than new-car sales. S&P Global Mobility reported about 289 million vehicles in operation, an average light vehicle age of 12.8 years and a scrappage rate that held at 4.5%. Older vehicles typically need several more tire sets before they leave the road, so a longer service life adds replacement cycles. Federal Highway Administration data published through the Federal Reserve shows a 12-month total of about 3.34 trillion vehicle miles through August 2026. That mileage translated into 221.9 million replacement passenger shipments in 2025, the largest single category that USTMA tracks. In turn, passenger car tires still anchor the market at 62.5% of 2025 value.
Freight fleets now buy far more replacement truck tires
Commercial fleets add a higher-value layer of demand because each truck tire costs several times more than a passenger fitment. European Rubber Journal reported replacement truck shipments of 24.7 million units in 2025, compared with 18.9 million in 2019, a gain that far outpaced original equipment. Bridgestone is also investing USD 550 million to expand its Warren County, Tennessee, truck and bus radial plant, which Modern Tire Dealer lists at 9,400 tires a day at full capacity. Hankook plans to add about 1 million truck and bus radial tires a year at Clarksville by the end of 2026. These commitments show how suppliers read long-run fleet demand, even though near-term orders have softened.
Import duties and price increases raise average tire value
Duties have become a direct driver of market value because imports supplied a record 63.4% of tires sold in 2024, according to Transport Topics. The same publication reported Yokohama raising prices by up to 10% from May 2025 and Sumitomo Rubber North America lifting consumer prices by up to a quarter. Tyrepress reported that the new duty on passenger tires applied from May 3, 2025, while JD Supra reported that truck tires faced the same rate from Nov. 1, 2025. The Bureau of Labor Statistics producer price index for tires stood at 196.9 in August 2026, on a 1982 base of 100. Consequently, market value can keep growing even while units stay broadly flat.
New vehicle fitments and heavier electric models reshape OE
New vehicle output still sets the specification that drivers later replace, so original equipment influences far more than its own volume. S&P Global Mobility recorded more than 16 million new registrations in 2024, the first time above that level since 2019. Sales of electric vehicles reached 7.8% of new cars in 2025, according to Kelley Blue Book, with the share peaking above 10% in the third quarter before falling to 5.8% in the fourth after the USD 7,500 federal credit ended in September. Yokohama also reported stronger North American original equipment sales in February 2026, driven by premium SUVs and crossovers. These larger, heavier vehicles typically need higher load ratings and bigger rims, lifting value per tire.
Domestic capacity and retail scale are changing supply
Shift of tire output toward newer, larger American plants
Suppliers are closing older factories and concentrating output in larger, more automated sites. Modern Tire Dealer reported that Bridgestone closed its LaVergne, Tennessee, plant in July 2025, removing 3,100 truck tires a day and 700 jobs, with volume moving to Warren County. Sumitomo Rubber ended tire making at Tonawanda, New York, in November 2024 and cut 1,550 positions, according to the Associated Press. Yokohama closed Salem, Virginia, on March 18, 2026, according to WDBJ7, ending a site rated at 25,700 passenger tires a day. Meanwhile, Hankook aims to double Clarksville passenger and light truck capacity to 10 million tires a year, according to European Rubber Journal. Together these moves favor the South, where most of the new capacity is being built.
Rise of national tire and service chains through acquisitions
Retail is consolidating because scale improves purchasing terms and installation coverage. Modern Tire Dealer reported in August 2026 that Mavis had completed its USD 700 million purchase of Pep Boys, adding nearly 800 stores and creating a network above 4,400 service centers across the United States and Canada. The same report said the deal gives Mavis a much larger footprint in the Western United States. Earlier, Discount Tire added 25 Dunn Tire locations in New York and Pennsylvania in September 2023. Goodyear also runs about 180 company-owned commercial truck service locations in the Americas alongside its consumer stores. Consequently, independent dealers face larger rivals with stronger buying power in most metropolitan areas.
Opportunity in connected tires for trucks and autonomous freight
Fleets offer a clear opening for tire makers that can sell data and uptime along with rubber. In August 2025, Goodyear and PlusAI agreed to explore how SightLine tire intelligence could support autonomous trucks, according to Tire Technology International. SightLine tracks tire health, road surface conditions and friction, and Automotive Fleet reported in 2021 that Goodyear planned to include tire intelligence in all new tires by 2027. Modern Tire Dealer reported that the USD 550 million Warren County expansion will allow RFID-tagged truck and bus radial production. Automotive Fleet also cited initial results showing the technology can reduce stopping distance loss by 30%, and the 180 commercial truck service locations Goodyear runs give it a ready channel for fleet software.
Opportunity in recycling, retreading and recovered materials
End-of-life tires are becoming a supply opportunity as federal rules loosen around recovery. The Environmental Protection Agency proposed in March 2026 to treat scrap tires burned in cement kilns as non-waste fuel, including previously abandoned tires. EPA's proposal cites U.S. Tire Manufacturers Association data showing that 264 million tires reached end of life in 2023, with 207 million recycled or used as fuel, leaving about 57 million without a recorded market. Cement plants took 43 million tires, pulp and paper mills 31 million and electric utilities 11 million. That volume supports wider use of reclaimed rubber and ground rubber, and companies with collection networks can build added income from it. Fleets can also lower disposal cost by keeping sound casings in service for longer periods.
Duties, softer volumes and plant costs test suppliers
Heavy import reliance exposes buyers to tariff costs
The 2024 import share of 63.4% leaves most supply exposed to the 25% Section 232 duty, which applies on top of existing duties, according to Tyrepress. Retail buyers and fleets absorb much of this cost through higher shelf and contract prices. Titan International also warned in its 2025 annual filing that shifting tariff rules after a February 2026 Supreme Court ruling leave costs uncertain. Importers can respond by qualifying goods under USMCA or moving sourcing to domestic plants.
Unit shipments are softening across replacement categories
USTMA projected 330.3 million units for 2026 in its latest forecast, according to Tire Review, below the 336.3 million shipped in 2025 and a drop of 6.0 million tires. The association now expects replacement truck shipments to fall 7.1% to 22.9 million, and replacement passenger shipments to fall 1.6%. Goodyear reported Americas replacement volume of 63.7 million units in 2025, compared with 66.6 million in 2024. Suppliers therefore carry idle capacity and must defend margins through mix and price discipline.
High plant costs force closures and regional job losses
Older American factories have struggled to compete on cost against newer domestic and imported supply. Sumitomo Rubber said spending at its century-old Tonawanda site could not offset growing losses, and it found no buyer before cutting 1,550 positions, according to the Associated Press. Yokohama said Salem was not well equipped for its required product mix, according to Modern Tire Dealer. These exits remove local supply, disrupt nearby communities and shift freight costs onto dealers in the Northeast and Mid-Atlantic.
End-of-life tire management remains a costly obligation
Scrap handling adds cost because end markets for used tires remain limited and regional. USTMA data cited by EPA show about 21% of the 2023 end-of-life total had no recorded recycling or fuel outlet, and about 48 million tires still sat in abandoned piles. State programs, haulers and dealers carry most of this burden through disposal fees and compliance work. EPA comments on the proposed scrap tire rule closed in May 2026, so the final cost effect remains unsettled for operators.
The South leads on population and plant investment
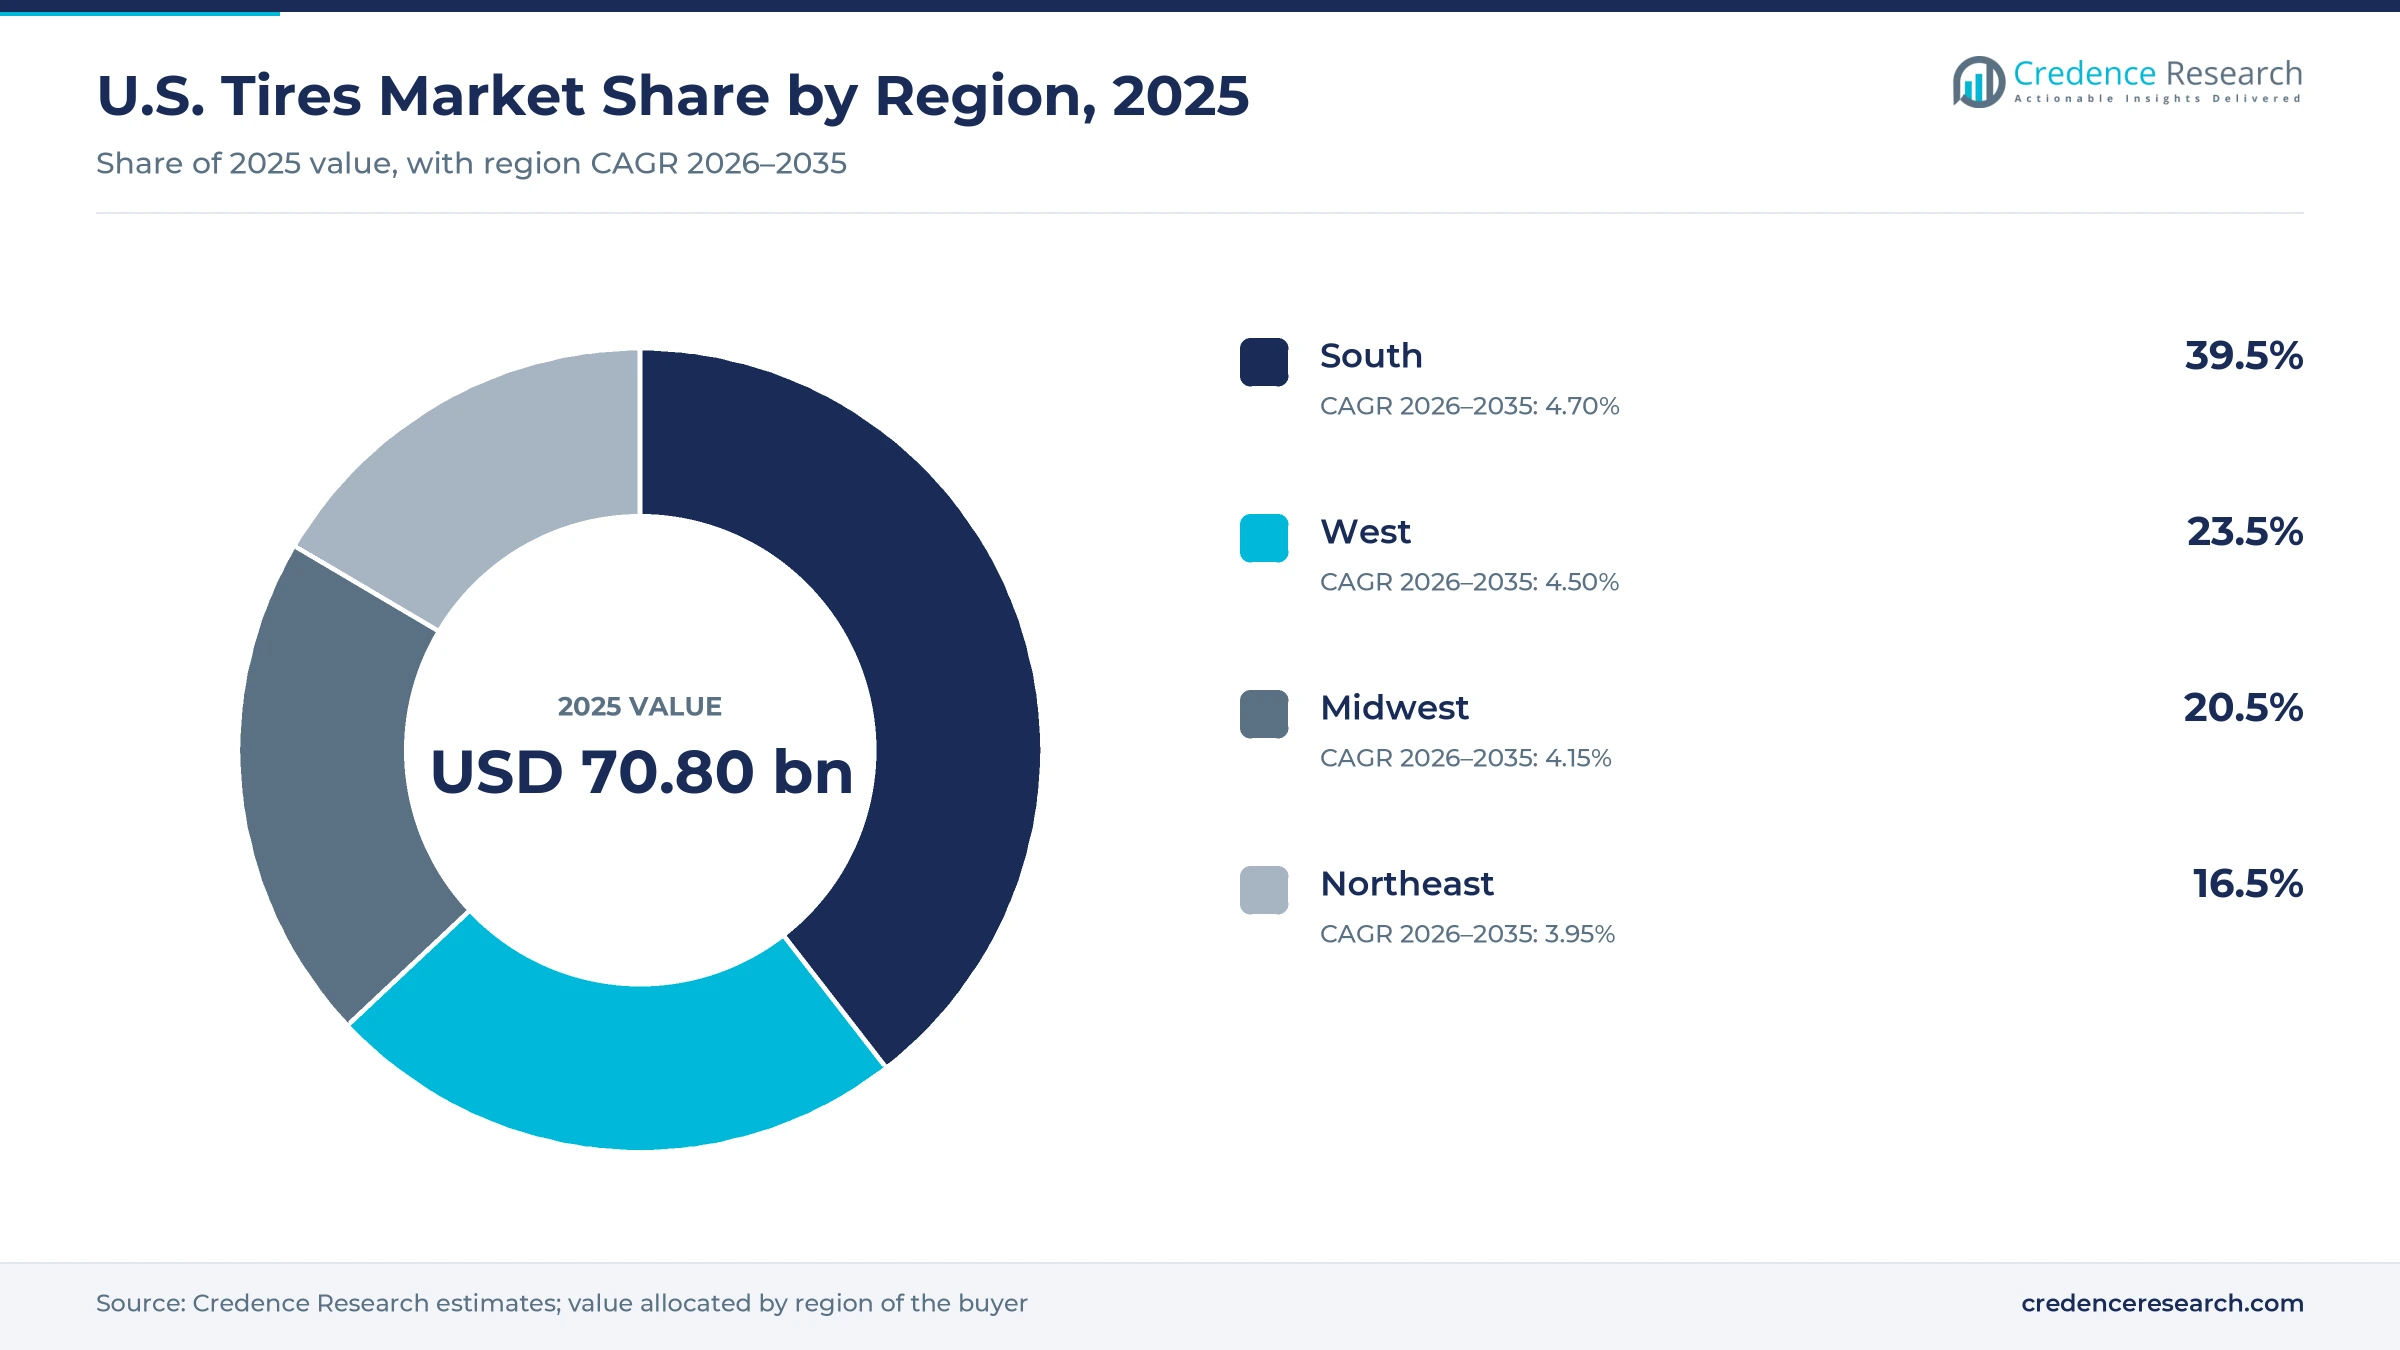
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| South | 27.97 | 39.5% | 4.70% |
| West | 16.64 | 23.5% | 4.50% |
| Midwest | 14.51 | 20.5% | 4.15% |
| Northeast | 11.68 | 16.5% | 3.95% |
South leads on population and tire-plant investment
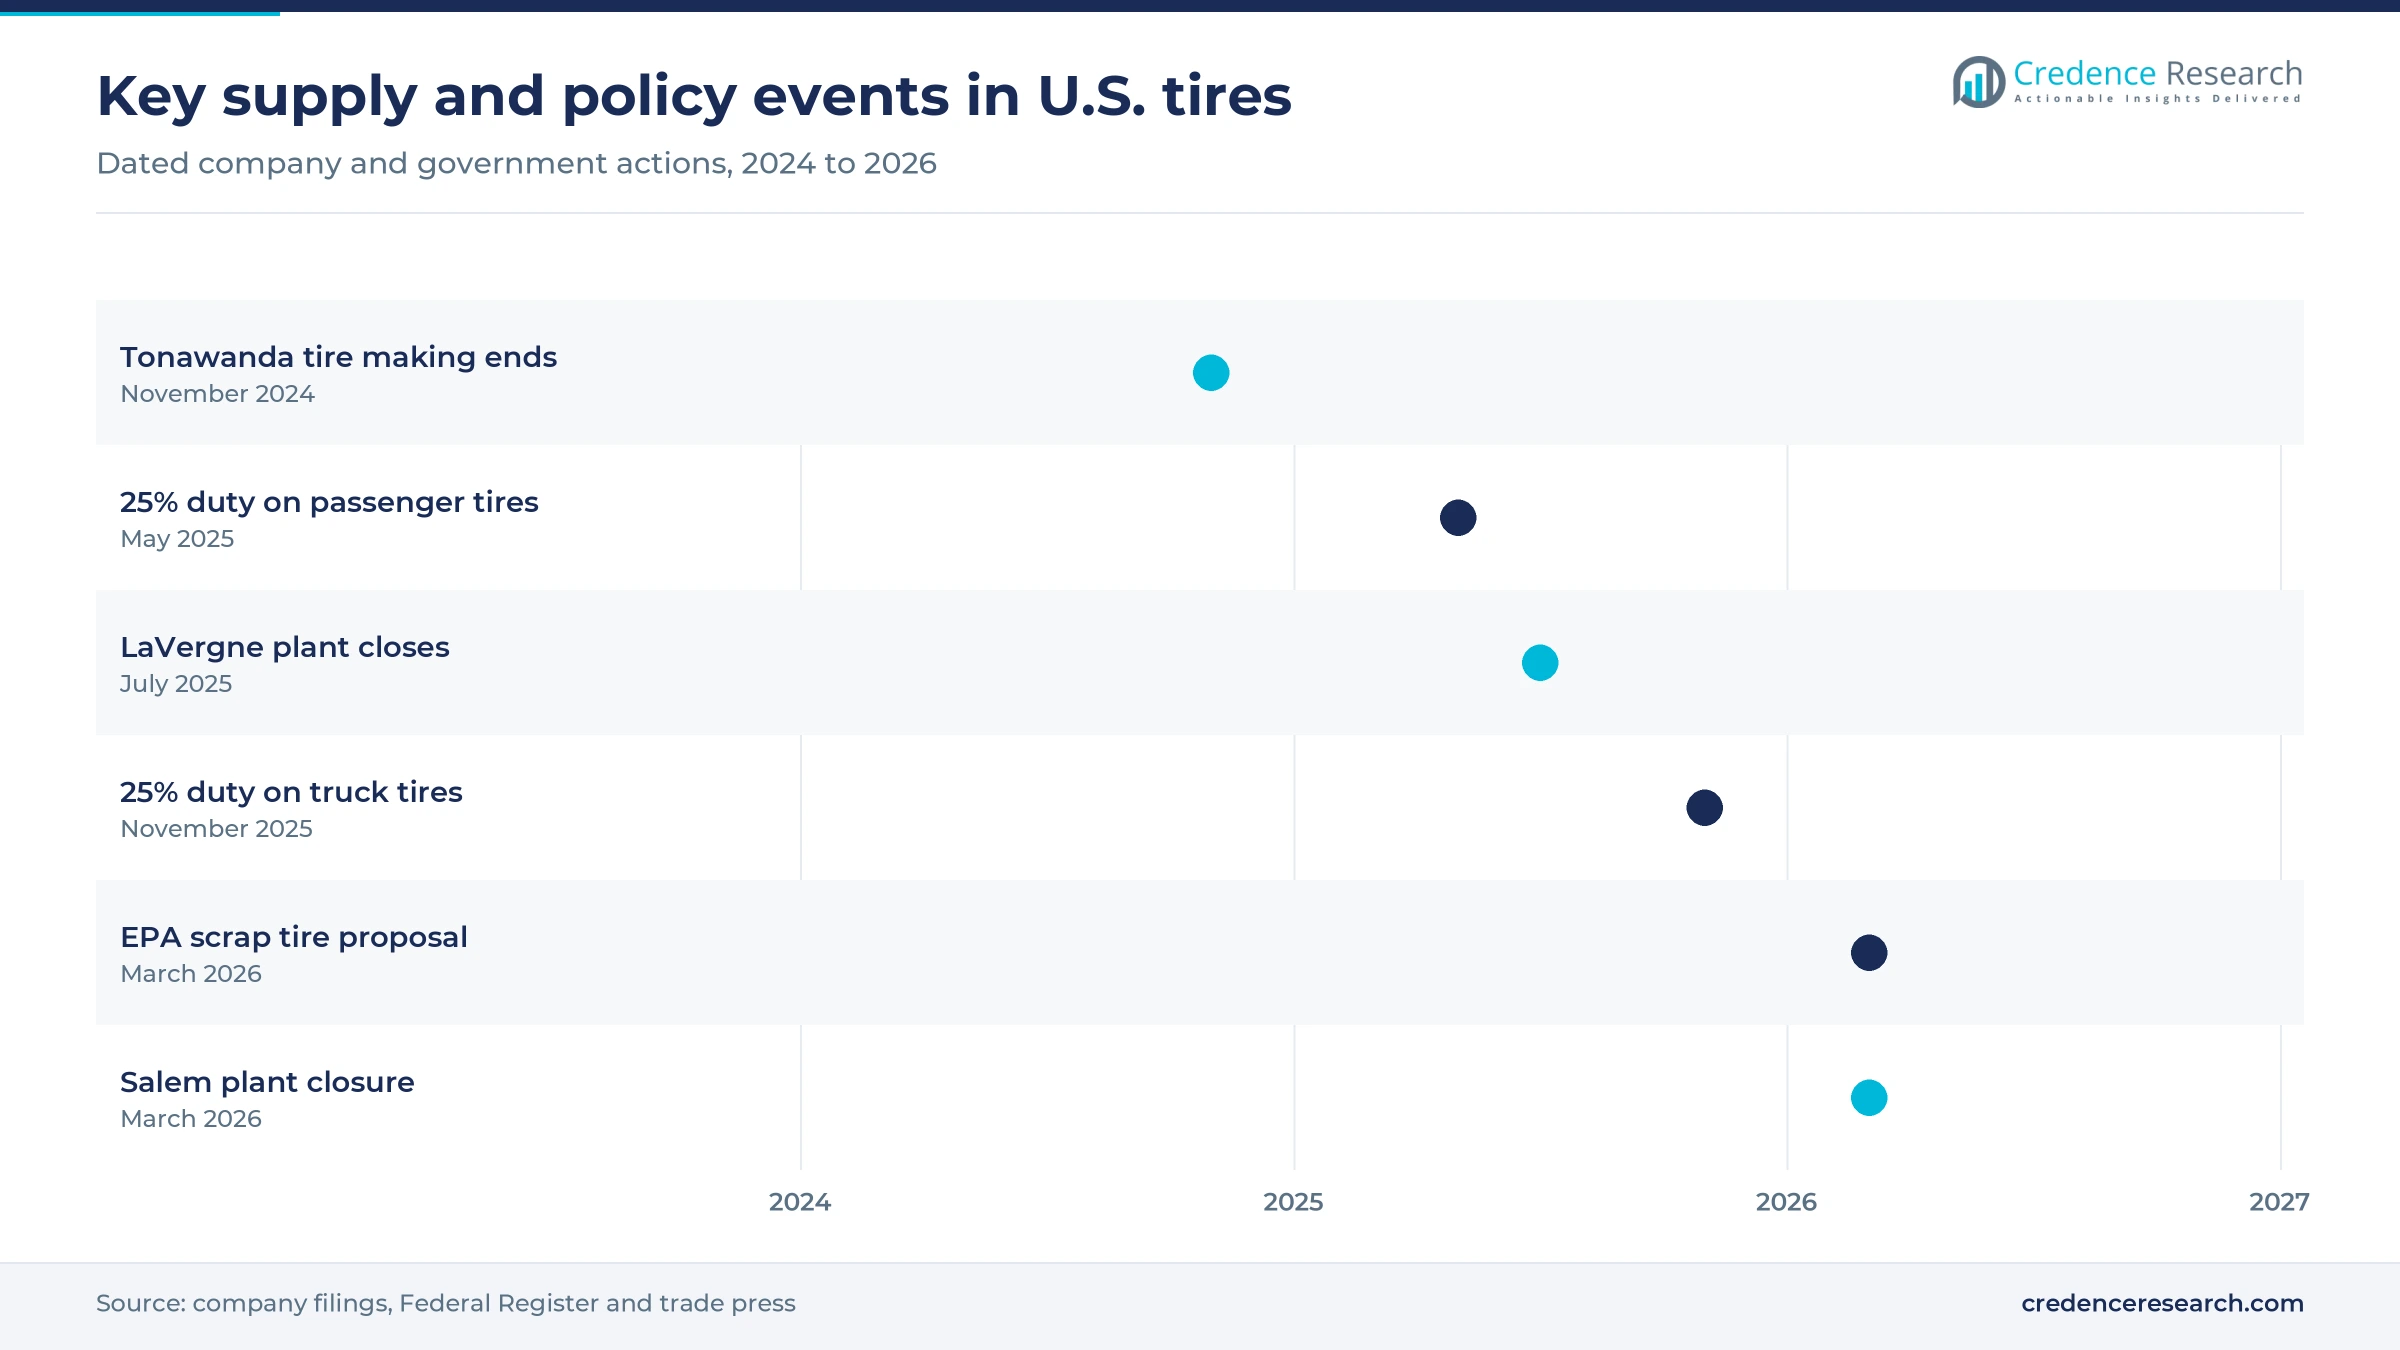
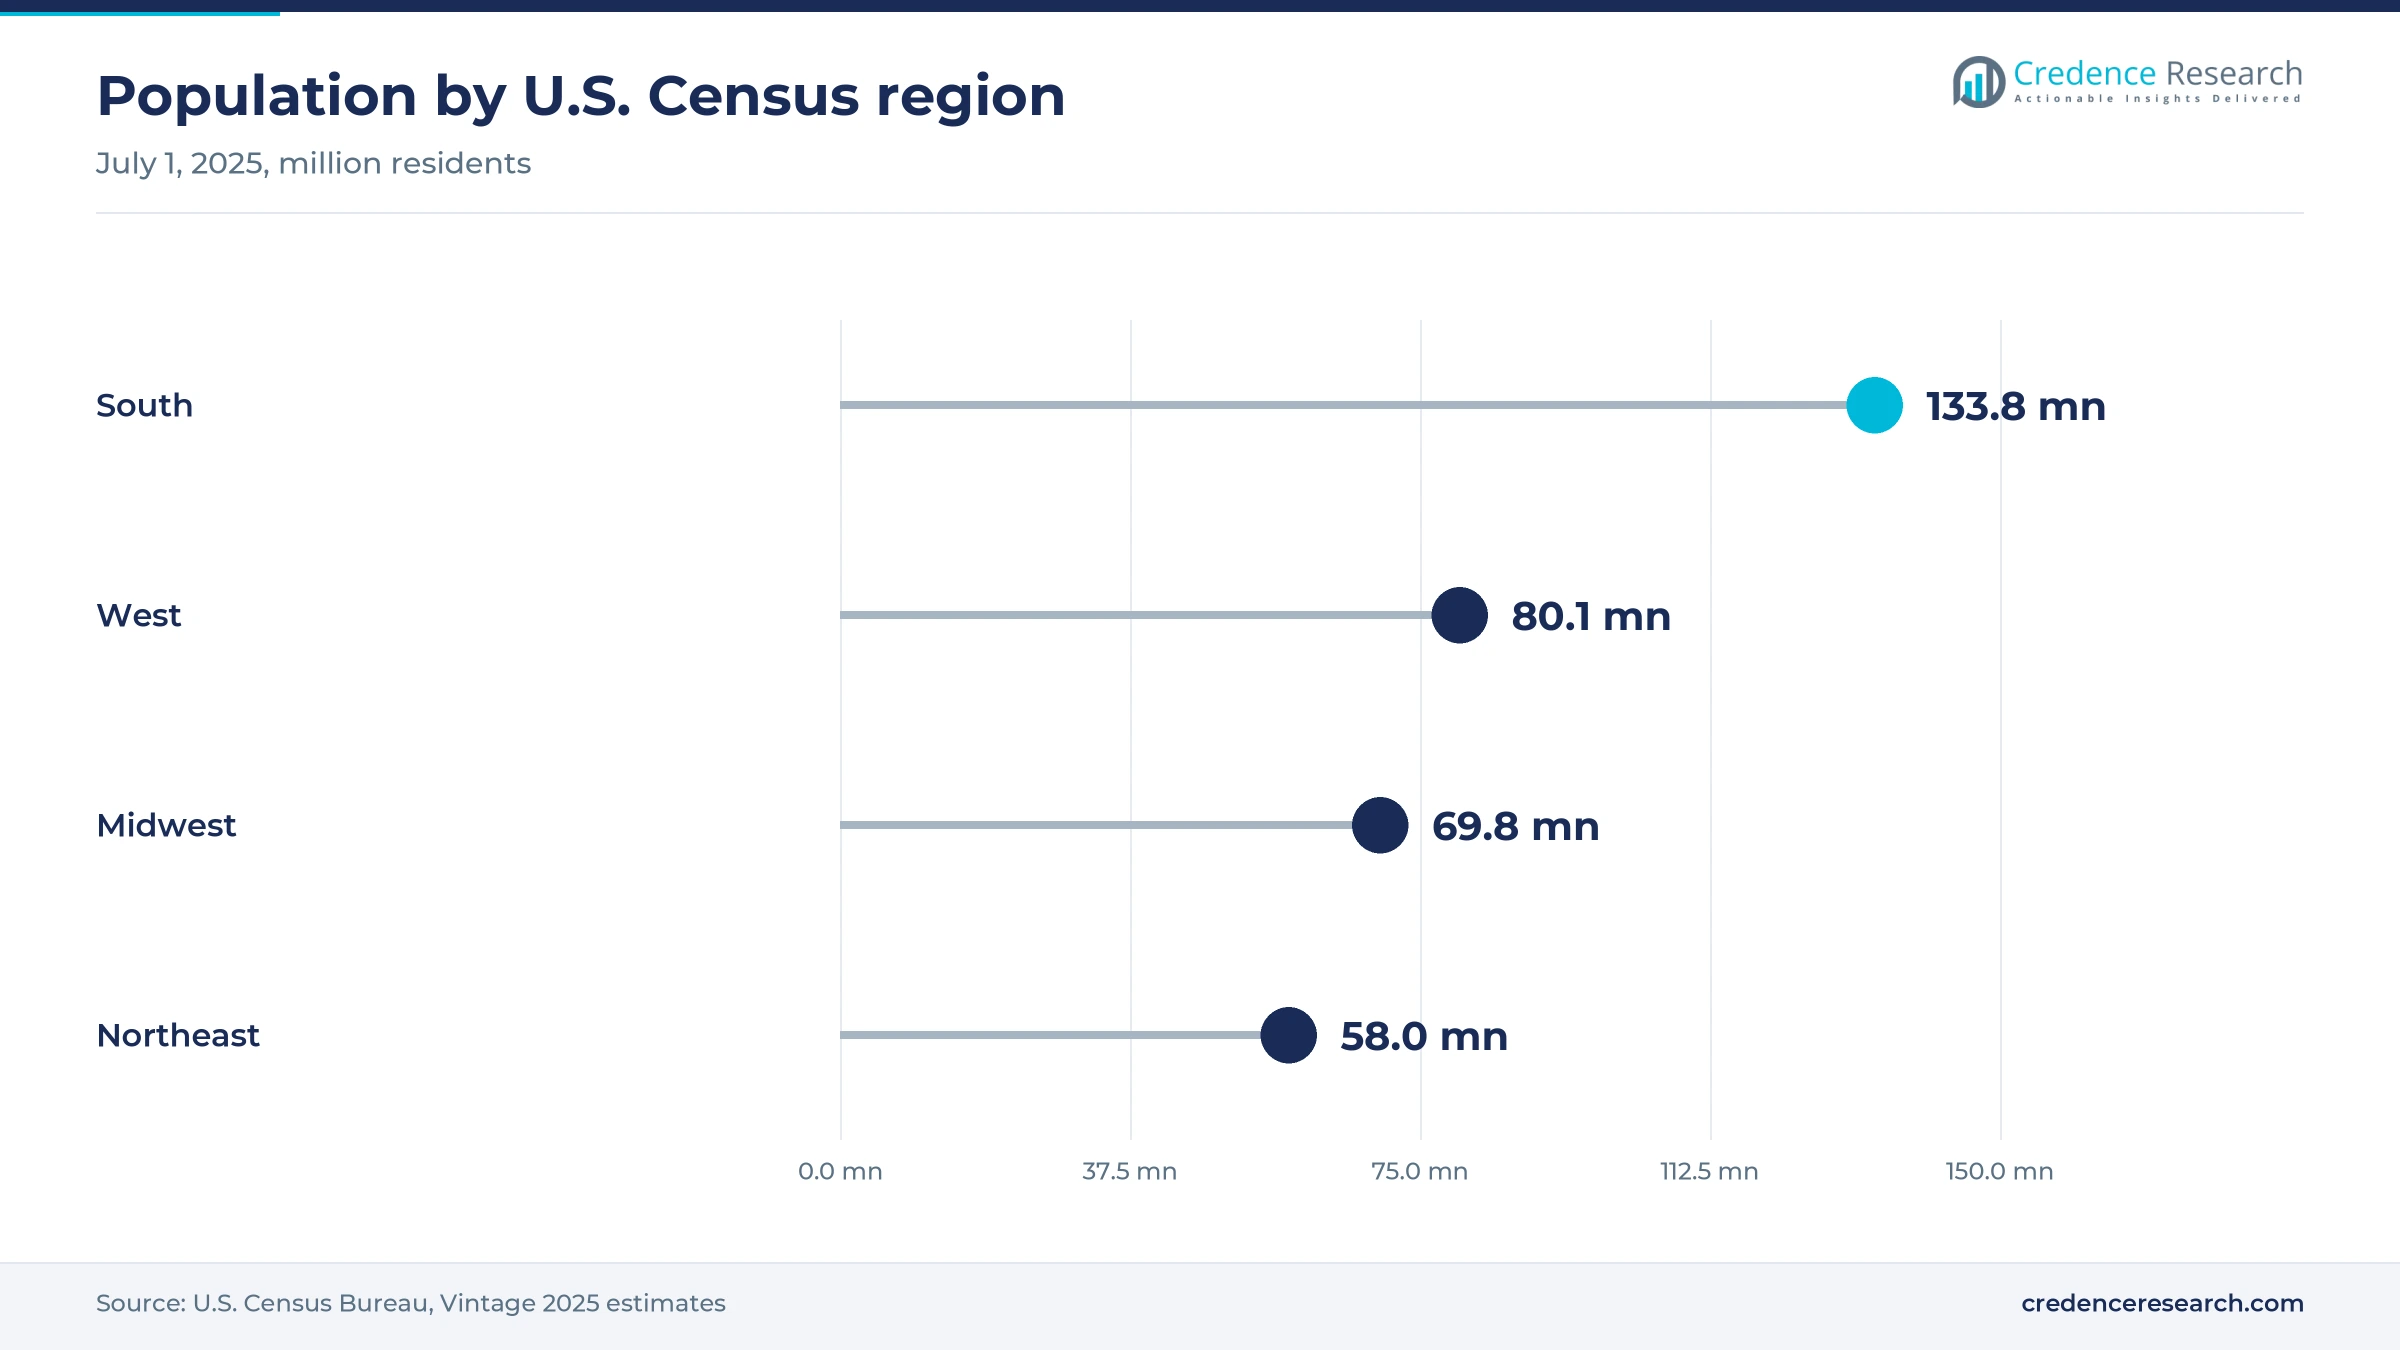
The South held 39.5% of 2025 value and grows at 4.70% a year, the fastest pace of the four Census regions. The Census Bureau reported that its population grew 6.0% from April 2020 to July 2025, nearly double the national 3.1%. Tennessee and South Carolina also host major capacity, including Hankook at Clarksville, Bridgestone at Warren County and Michelin at Greenville, Lexington and Spartanburg, which shortens delivery to southern dealers.
West gains retail reach as Mavis enters through Pep Boys
The West held 23.5% of 2025 value and grows at 4.50% a year, supported by about 80.1 million residents. Michelin, Hankook and Continental plants named in this report all sit east of the Rockies, so western dealers rely on long inland freight or imports and face the import duty directly. The Pep Boys purchase by Mavis in 2026 also adds a much larger western service network.
Midwest combines plant employment with farm tire demand
The Midwest held 20.5% of 2025 value and grows at 4.15% a year, with about 69.8 million residents and a strong manufacturing base. Continental employs more than 3,900 people at Mount Vernon, Illinois, according to Tire Review, and Goodyear names Findlay, Ohio, among its American plants. Titan International lists plants in Des Moines, Iowa, along with Freeport and Quincy, Illinois, serving Deere, CNH and AGCO. Farm and off-road fitments therefore make this region more important for special vehicle tires than its population suggests.
Northeast loses local capacity but keeps dense replacement demand
The Northeast held 16.5% of 2025 value and grows at 3.95% a year, the slowest pace of the four regions. It counts about 58.0 million residents, including about 20.0 million in New York, on a much smaller population base than the South. The Tonawanda closure removed a New York plant that had operated since 1923, so more local supply now comes from other states or abroad. Winter driving still supports seasonal sets, and Discount Tire strengthened its local presence through the 2023 Dunn Tire purchase.
Plant closures and retail deals defined 2025 and 2026
| Development | Status and market relevance |
|---|---|
| In January 2025, Bridgestone Americas announced the closure of its LaVergne, Tennessee, truck and bus radial plant, effective July 23, 2025. | Completed; about half the volume moved to Warren County. |
| In February 2025, Yokohama acquired the Goodyear off-the-road tire business, extending its off-highway range. | Completed; contributed to Yokohama off-highway growth. |
| In August 2025, Goodyear and PlusAI announced a collaboration on SightLine tire intelligence for autonomous trucks. | Exploratory; ahead of factory-built autonomous truck launches. |
| In February 2026, Modern Tire Dealer reported that Yokohama would close its Salem, Virginia, plant on March 18. | Closed on that date, leaving nearly 400 people out of work, according to WDBJ7. |
| In August 2026, Modern Tire Dealer reported that Mavis had completed its USD 700 million acquisition of Pep Boys. | Completed; network above 4,400 service centers. |
Sensors and new compounds are changing tire design
- Embedded sensors track wear, pressure and road friction, and Goodyear SightLine is the leading American example for fleets.
- RFID tagging gives each truck casing a digital identity, which supports retread decisions and fleet inventory control.
- Tread compounds blend natural rubber with styrene-butadiene rubber to balance grip, wear and rolling resistance on heavier vehicles.
- Inflation control through automatic inflation systems helps long-haul fleets hold target pressure and extend casing life between retreading cycles.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Global makers defend share with local plants
Competition in U.S. tires centers on a small group of global manufacturers with American plants, alongside importers that sell mainly on price. Goodyear operates eight tire plants in the United States and sells its Goodyear and Cooper brands through a large independent dealer network. Michelin runs about 15 major American manufacturing facilities, covering passenger, truck, earthmover and aircraft products. Bridgestone is concentrating truck production at Warren County, while Continental reports annual capacity above 16 million tires across Mount Vernon, Sumter and Clinton. Hankook is the most visible expansion story, with Clarksville aiming for 10 million passenger and light truck tires a year. Yokohama is moving toward off-highway and commercial products after its Goodyear business purchase, while Titan International serves farm and construction equipment makers. Because duties now raise the cost of imported supply, local capacity has become a stronger competitive advantage than brand alone.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Goodyear Tire & Rubber Company | American manufacturer | Eight U.S. plants; Goodyear and Cooper brands; about 505 company-owned Americas outlets |
| Michelin | Global manufacturer | U.S. plants in South Carolina, Alabama, Oklahoma and Indiana across passenger, truck and earthmover products |
| Bridgestone Americas | Global manufacturer | Warren County, Tennessee, truck and bus radial expansion with RFID capability |
| Continental Tire the Americas | Global manufacturer | Mount Vernon, Sumter and Clinton plants with more than 16 million tires of annual capacity |
| Hankook Tire America Corp. | Global manufacturer | Clarksville, Tennessee, expansion to 10 million passenger and light truck tires a year |
| Yokohama Tire Corporation | Global manufacturer | Closed Salem in March 2026; acquired Goodyear off-the-road business in 2025 |
| Sumitomo Rubber North America | Global manufacturer | Ended Tonawanda tire making in 2024; supplies market through other sourcing |
| Titan International | American manufacturer | Farm, off-road and consumer tires from plants including Des Moines, Freeport and Quincy |
Value growth depends on price and mix, not units
Credence Research's view is that value growth in U.S. tires will rely on price and mix, not on unit expansion. Shipments of 330.3 million units forecast for 2026 sit below the 336.3 million recorded in 2025, yet duties and larger fitments keep average value rising. Suppliers holding American capacity should gain the most, particularly in light truck sizes where the fleet is growing. The main risk is that tariff rules change again, which could reverse pricing quickly. Dealers with scale and installation coverage look best placed to protect margin through this period.
How Credence Research built these estimates
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, re-estimated for 2025 from public shipment and retail data. Segment and regional shares throughout this report are Credence Research estimates from those public data. Sources include U.S. Tire Manufacturers Association forecasts, Census Bureau population estimates, Federal Reserve Economic Data, Securities and Exchange Commission filings, Federal Register notices and named trade publications. No interviews or surveys were conducted for this edition of the report.
Replacement demand keeps growth steady through 2035
From USD 73.93 billion in 2026, U.S. tires should reach USD 109.11 billion by 2035 at 4.42% a year, led by replacement buying as the fleet keeps aging. Light Truck Tires remain the fastest vehicle segment, and online sellers gain share as buyers become comfortable pairing web orders with local installers. Domestic capacity should also improve as Clarksville and Warren County reach full output, while tariff policy remains the largest swing factor. Recycling rules and connected fleet services could add smaller but useful new sources of value over the period.
Frequently Asked Questions
How big is the U.S. tire market?
How many tires are shipped in the United States each year?
How does the tire aftermarket compare with OEM sales?
Who are the main American tire manufacturers?
Are all-weather tires gaining share of replacement sales?
How have tariffs affected U.S. tire prices?
What share of U.S. tire sales is imported?
What are connected tires and who is using them?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vehicle Type
- 1.2.1 Passenger Car Tires
- 1.2.2 Light Truck Tires
- 1.2.3 Truck and Bus Tires
- 1.2.4 Special Vehicle Tires
- 1.2.5 Motorcycle Tires
- 1.3 By Demand
- 1.3.1 Replacement
- 1.3.2 OEM
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 70.80 billion → 2035: USD 109.11 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Tires Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Tires Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Tires Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Tires Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Tires Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Tires Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Tires Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Tires Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 70.80 billion → 2035: USD 109.11 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Tires Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vehicle Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Passenger Car Tires
- 12.3.7.2 Light Truck Tires
- 12.3.7.3 Truck and Bus Tires
- 12.3.7.4 Special Vehicle Tires
- 12.3.7.5 Motorcycle Tires
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Demand - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Replacement
- 12.4.7.2 OEM
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Tires Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 U.S. Tires Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 U.S. Tires Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Goodyear Tire & Rubber Company
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Michelin
- 17.4 Bridgestone Americas
- 17.5 Continental Tire the Americas
- 17.6 Yokohama Tire Corporation
- 17.7 Hankook Tire America Corp.
- 17.8 Sumitomo Rubber North America
- 17.9 Titan International
- 17.10 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

