
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Data Center Liquid Cooling Market Size 2024 | USD 1173.1 million |
| U.S. Data Center Liquid Cooling Market, CAGR | 24.73% |
| U.S. Data Center Liquid Cooling Market Size 2032 | USD 6874.16 million |
Market Overview:
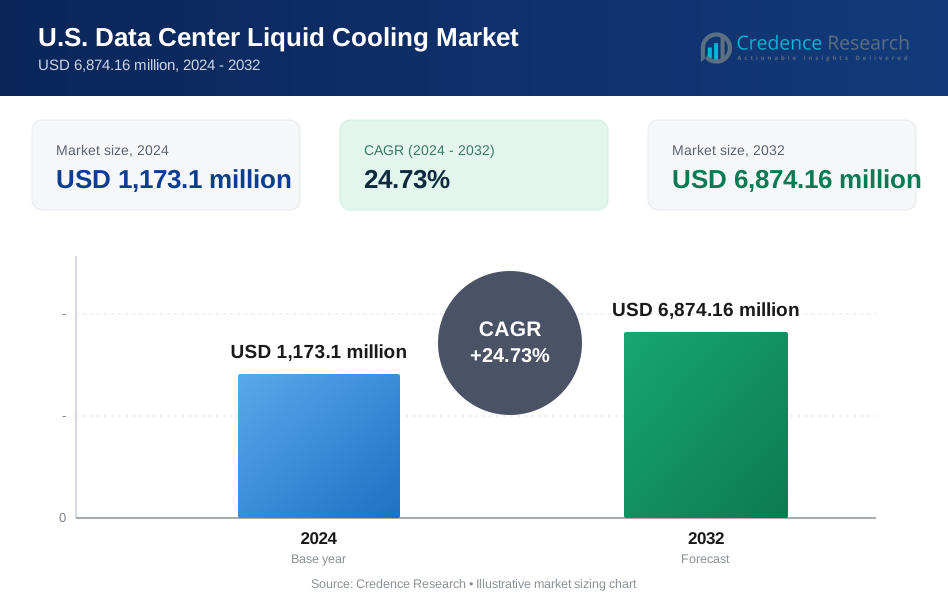
The U.S. Data Center Liquid Cooling Market is projected to grow from USD 1173.1 million in 2024 to an estimated USD 6874.16 million by 2032, with a compound annual growth rate (CAGR) of 24.73% from 2024 to 2032.
The growth of the U.S. data center liquid cooling market is primarily fueled by several key factors. Firstly, the surge in data center density, driven by the proliferation of cloud computing, artificial intelligence (AI), and Internet of Things (IoT) applications, has resulted in increased heat generation within servers. Traditional air-cooling methods often fall short in managing these thermal challenges, making liquid cooling a crucial solution to ensure optimal performance and reliability. Secondly, the emphasis on energy efficiency and sustainability is a significant driver. Data centers account for substantial energy consumption, and liquid cooling systems can reduce cooling energy usage by up to 40%. This not only helps lower operational costs but also aligns with corporate sustainability goals by minimizing carbon emissions. Lastly, technological advancements in liquid cooling, such as direct-to-chip and immersion cooling technologies, have significantly improved their cost-effectiveness and operational reliability. These innovations have made liquid cooling an attractive option for modern data centers facing increasingly demanding computing workloads.
The United States dominates the North American data center liquid cooling market, underpinned by several critical factors. The country is home to numerous hyperscale data centers operated by major cloud service providers and large enterprises, all of which demand highly efficient cooling systems to manage intense computational loads. Additionally, stringent environmental regulations and sustainability initiatives have compelled data center operators to adopt energy-efficient technologies like liquid cooling to meet compliance standards and reduce overall energy consumption. Furthermore, substantial investments in data center infrastructure across various U.S. regions have bolstered the adoption of advanced cooling technologies. The expansion of digital services, coupled with the increasing reliance on AI and cloud computing, continues to drive the need for innovative cooling solutions, positioning the U.S. as a leader in the global liquid cooling market.
Market Insights:
- The U.S. data center liquid cooling market is expected to grow from USD 1,173.1 million in 2024 to USD 6,874.16 million by 2032, registering a CAGR of 24.73%.
- Increasing data center density, driven by the rise of cloud computing, AI, and IoT applications, is creating a greater demand for efficient liquid cooling solutions.
- Liquid cooling systems can reduce energy consumption by up to 40%, supporting sustainability goals while lowering operational costs and minimizing carbon footprints.
- Technological advancements in direct-to-chip and immersion cooling methods are enhancing system efficiency, reliability, and cost-effectiveness, encouraging broader adoption.
- Government regulations promoting energy efficiency, along with economic incentives and tax benefits, are driving the integration of advanced liquid cooling technologies.
- High initial investment costs and integration challenges, particularly for small to medium-sized enterprises, are key restraints affecting the market's expansion.
- Key regions like Northern Virginia, Silicon Valley, and Dallas-Fort Worth are leading growth, supported by strong infrastructure, strategic locations, and investments in sustainable cooling solutions.
Market Drivers:
Escalating Data Center Density and High-Performance Computing Demands
The proliferation of data-intensive applications, including artificial intelligence (AI), machine learning, and big data analytics, has led to a substantial increase in data center density. Traditional air-cooling methods often struggle to dissipate the heat generated by densely packed servers, making liquid cooling an essential solution to maintain optimal operating temperatures and ensure system reliability. This shift is particularly pronounced in high-performance computing environments, where efficient thermal management is critical to support advanced computational workloads. For instance, Liquid cooling technologies, such as immersion cooling, are gaining popularity due to their ability to reduce energy usage by up to 50% compared to traditional air-cooling methods.
Emphasis on Energy Efficiency and Sustainability
As data centers consume significant amounts of energy, there is a growing emphasis on adopting energy-efficient and sustainable cooling solutions. Liquid cooling systems are more efficient than traditional air-cooling methods, capable of reducing cooling energy consumption by up to significantly. For instance, Alibaba Cloud’s liquid-cooled data centers have reported a 70% reduction in cooling energy use. This efficiency not only lowers operational costs but also aligns with sustainability goals by minimizing the carbon footprint of data center operations. Additionally, companies are under increasing pressure to meet environmental, social, and governance (ESG) standards, further accelerating the transition to more sustainable cooling methods. The long-term cost savings and positive environmental impact offered by liquid cooling systems make them an attractive choice for forward-thinking data center operators.
Technological Advancements in Liquid Cooling Solutions
Innovations in liquid cooling technologies, such as immersion cooling and direct-to-chip cooling, have enhanced their reliability and cost-effectiveness. These advancements have made liquid cooling more accessible and attractive to data center operators seeking to improve cooling efficiency and support the increasing power densities of modern IT equipment. For example, immersion cooling can reduce energy consumption by up to 30% or more. Furthermore, advancements in liquid coolant materials and system design have improved heat transfer efficiency, reducing maintenance needs and enhancing overall system performance. As these technologies continue to evolve, they are expected to drive down the total cost of ownership, encouraging broader adoption across the industry.
Regulatory Pressures and Economic Incentives
Government regulations aimed at reducing carbon emissions and promoting energy efficiency are encouraging data center operators to adopt liquid cooling solutions. Additionally, economic incentives and tax benefits in various states have spurred data center construction, further driving the demand for advanced cooling technologies. The regulatory landscape is also evolving to favor eco-friendly technologies, offering additional financial support for companies investing in sustainable infrastructure. Moreover, organizations that adopt such energy-efficient systems are better positioned to enhance their brand reputation and meet stakeholder expectations for responsible environmental practices. For example, Microsoft's partnership with Fortum to heat homes in Helsinki using waste heat from data centers not only reduces carbon emissions but also provides a financial boost by cutting around 400,000 tonnes of CO2 emissions annually.
Market Trends:
Adoption of Immersion and Direct-to-Chip Cooling Technologies
The U.S. data center liquid cooling market is experiencing a notable shift toward the adoption of advanced cooling methodologies, particularly immersion and direct-to-chip cooling technologies. These methods involve submerging servers in thermally conductive liquids or directly cooling critical components such as CPUs and GPUs. For instance, ZutaCore's HyperCool is a direct-to-chip liquid cooling solution that supports high-density computing by efficiently cooling processors up to 2800 watts, allowing for scalable deployment in both new and retrofitted data centers. The transition is driven by the increasing need to efficiently manage heat generated by high-performance computing applications. Major technology companies are spearheading this trend, introducing innovative solutions that enhance operational efficiency, reduce hardware failure rates, and optimize data center performance.
Integration of AI-Driven Cooling Management Systems
Artificial Intelligence (AI) is playing an increasingly vital role in optimizing cooling systems within data centers. AI-driven cooling management systems are designed to analyze real-time data, predict equipment failures, and adjust operational parameters dynamically to enhance cooling efficiency. This intelligent approach ensures consistent performance while significantly reducing energy consumption and operational costs. For example, Axiado's AI-driven Dynamic Thermal Management (DTM) solution can cut cooling costs by up to 50%, saving millions of dollars annually and reducing CO2 emissions by up to 11%. The integration of AI into cooling systems is not only enhancing reliability but also supporting sustainable data center operations by minimizing unnecessary energy usage and improving overall system resilience.
Advancements in Sustainable Cooling Solutions
Sustainability is becoming a core focus for the data center industry, leading to the advancement of environmentally friendly cooling solutions. For instance, evaporative cooling is a highly efficient method that uses the natural process of evaporation to remove heat from the air, reducing energy consumption by up to 80% compared to traditional air conditioning. Liquid immersion cooling, for example, offers enhanced energy efficiency and reduces the use of natural resources like water. These innovations contribute to the reduction of environmental impact, aligning with the broader sustainability goals of organizations. Leading industry players are actively investing in the development and deployment of such sustainable technologies, ensuring that their cooling solutions meet both operational efficiency standards and environmental responsibilities.
Increased Retrofitting of Existing Data Centers
An emerging trend in the U.S. data center liquid cooling market is the retrofitting of existing facilities with advanced liquid cooling systems. This approach is driven by the need to modernize legacy infrastructure to support contemporary workloads, including cloud services, big data analytics, and AI-driven applications. Retrofitting allows operators to enhance cooling efficiency and adapt to evolving technological requirements without constructing entirely new facilities. For instance, technotrans offers a plug-and-play cooling solution that can significantly increase performance within a short time without interfering with existing building infrastructure, enabling data centers to manage varying heat loads efficiently. This strategy not only optimizes resource use but also provides a cost-effective pathway for data centers to stay competitive and energy-efficient in a rapidly changing digital landscape.
Market Challenges Analysis:
High Initial Capital Expenditure
Implementing liquid cooling systems in data centers requires substantial initial investments, often exceeding those associated with traditional air-cooling methods. This elevated capital expenditure encompasses specialized equipment, infrastructure modifications, and the integration of advanced technologies. Consequently, organizations, particularly small to medium-sized enterprises, may find the financial barrier to entry prohibitive, hindering widespread adoption of liquid cooling solutions.
Integration and Compatibility Challenges
The absence of standardized protocols in liquid cooling technologies presents significant integration challenges. Compatibility issues can arise when incorporating liquid cooling systems into existing data center infrastructures, leading to potential operational disruptions. These complexities necessitate meticulous planning and customization, which can deter organizations from transitioning to liquid cooling solutions.
Competition from Alternative Cooling Technologies
Despite the advantages of liquid cooling, alternative technologies continue to pose competition. Established air-cooling systems, for instance, have undergone continuous improvements, enhancing their efficiency and cost-effectiveness. Organizations may prefer these familiar solutions over liquid cooling, perceiving them as less risky and more compatible with their current operations.
Technical and Maintenance Complexities
Implementing liquid cooling systems introduces technical complexities that require specialized knowledge for effective operation and maintenance. The need for skilled personnel to manage these sophisticated systems can increase operational costs and pose challenges in regions where such expertise is scarce. Additionally, concerns about potential leaks and the long-term reliability of liquid cooling systems may deter organizations from adopting these technologies.
Market Opportunities:
The growing demand for high-performance computing (HPC) and artificial intelligence (AI) workloads presents significant opportunities for the U.S. data center liquid cooling market. As AI-driven applications, big data analytics, and advanced cloud services continue to expand, data centers must handle increasing computational power and heat generation. Traditional air-cooling systems often struggle to meet the demands of these high-density environments, leading to the rising adoption of liquid cooling solutions. Liquid cooling not only ensures better thermal management but also enhances system performance and longevity. As enterprises invest in AI infrastructure, the need for efficient and reliable cooling systems becomes more pronounced, positioning liquid cooling technologies as essential for supporting future data processing demands. This trend opens new avenues for technology providers and infrastructure developers to innovate and expand their offerings.
The increasing emphasis on sustainability and energy efficiency within the data center industry offers another promising opportunity for the liquid cooling market. With rising concerns about energy consumption and carbon emissions, organizations are seeking eco-friendly solutions to align with regulatory standards and corporate sustainability goals. Liquid cooling systems, known for their reduced energy consumption and environmental impact, present a viable solution to meet these objectives. Moreover, government incentives supporting energy-efficient infrastructure upgrades further enhance market opportunities. Companies that prioritize sustainable cooling technologies stand to gain competitive advantages, attract eco-conscious clients, and contribute to broader environmental goals. This intersection of sustainability and technological advancement positions the U.S. liquid cooling market for sustained growth and innovation.
Market Segmentation Analysis:
The U.S. data center liquid cooling market is segmented into four primary categories: type, application, component, and industry vertical, each contributing to the market’s dynamic growth and structure.
By Type Segment The market is categorized into Direct Liquid Cooling and Indirect Liquid Cooling. Direct liquid cooling, which involves circulating coolant directly over heat-generating components, is gaining significant traction due to its superior efficiency in managing high-density computing environments. Indirect liquid cooling, which uses air-to-liquid heat exchangers, remains prevalent for data centers seeking gradual transition from traditional air-cooling systems.
By Application Segment This segment includes IT Equipment Cooling, Power Supply Cooling, UPS Cooling, and Others. IT equipment cooling holds the largest share, driven by the need for efficient heat management in high-performance computing. Power supply and UPS cooling are also crucial for maintaining equipment reliability and ensuring continuous power availability.
By Component Segment Key components driving the market include Chillers, Cooling Distribution Units, Heat Exchangers, Pumps, and Others. Chillers play a vital role in temperature control, while cooling distribution units and heat exchangers ensure efficient heat transfer. Pumps facilitate the movement of coolants, ensuring optimal system performance.
By Industry Vertical Segment Major industry verticals include BFSI, IT and Telecom, Government, Healthcare, and Others. The IT and telecom sector leads the market, fueled by the rising demand for data-intensive services. The healthcare and BFSI sectors are also adopting liquid cooling solutions to manage growing data processing needs securely and efficiently.
Segmentation:
By Type Segment
- Direct Liquid Cooling
- Indirect Liquid Cooling
By Application Segment
- IT Equipment Cooling
- Power Supply Cooling
- UPS Cooling
- Others
By Component Segment
- Chillers
- Cooling Distribution Units
- Heat Exchangers
- Pumps
- Others
By Industry Vertical Segment
- BFSI (Banking, Financial Services, and Insurance)
- IT and Telecom
- Government
- Healthcare
- Others
Regional Analysis:
The United States dominates the global data center liquid cooling market, propelled by its advanced digital infrastructure and the presence of key technology enterprises. As of 2024, North America accounts for 36.4% of the global market share in the data center liquid cooling sector. This substantial share, underscores the region's leadership and rapid adoption of advanced cooling technologies. The increasing demand for efficient thermal management solutions, driven by growing computational workloads, continues to shape the market’s trajectory.
Regional Concentrations and Growth Dynamics
Within the U.S., certain regions have emerged as prominent hubs for data center operations due to their strategic advantages in infrastructure, energy accessibility, and favorable business conditions. Northern Virginia, often termed "Data Center Alley," remains a significant stronghold, benefiting from reliable power supplies and proximity to major network hubs. Silicon Valley in California continues to attract investments due to its global reputation as a technology hub and the presence of leading tech corporations. Meanwhile, the Dallas-Fort Worth region in Texas has evolved into a data center hotspot, thanks to its central location, cost-effective energy resources, and business-friendly climate. These regions, with their robust ecosystems, continue to drive the adoption of liquid cooling technologies.
Factors Influencing Regional Market Shares
The adoption rate of liquid cooling systems varies across U.S. regions due to several influencing factors. Areas with stringent energy efficiency regulations and aggressive sustainability initiatives are more inclined to integrate liquid cooling solutions, recognizing their role in reducing power consumption and minimizing environmental impact. Additionally, regions hosting industries reliant on high-performance computing, such as financial services, healthcare, and research institutions, have embraced liquid cooling to manage the intense thermal demands of advanced computational processes. Moreover, state and local governments that offer tax incentives and grants for infrastructure development further promote the integration of advanced cooling technologies, enhancing regional market growth.
Outlook and Future Trends
The future outlook for the U.S. data center liquid cooling market remains positive, with significant growth anticipated across multiple regions. The continuous evolution of technologies like artificial intelligence, machine learning, and big data analytics will further amplify the need for efficient cooling solutions. Additionally, as sustainability becomes a critical component of data center operations, the transition to liquid cooling technologies will accelerate. This growing emphasis on energy efficiency, combined with government support and evolving industry demands, will drive the broader adoption of liquid cooling solutions, reinforcing the United States' leadership in this market.
Key Player Analysis:
- Vertiv
- CoolIT Systems
- IBM
- Green Revolution Cooling (GRC)
- Schneider Electric
- LiquidCool Solutions
- Stulz
- Iceotope Technologies
- Submer
Competitive Analysis:
The U.S. data center liquid cooling market is characterized by intense competition, driven by technological advancements and the increasing demand for efficient cooling solutions. For example, CoolIT Systems has expanded its liquid-cooling solutions to support NVIDIA's Blackwell AI platform, demonstrating how leading companies are innovating to meet the needs of high-performance computing applications. Leading companies such as Vertiv, Schneider Electric, CoolIT Systems, and Asetek dominate the landscape, leveraging their extensive product portfolios and technological expertise to secure significant market shares. These players focus on innovation, offering advanced solutions like immersion cooling and direct-to-chip technologies to address the growing thermal management needs of high-density data centers. Strategic partnerships, mergers, and acquisitions are common strategies employed to enhance market presence and expand product offerings. Companies are also investing in research and development to improve cooling efficiency and sustainability. Additionally, competitive differentiation is achieved through customization, allowing providers to cater to diverse client needs across industries. The competitive landscape is further shaped by the increasing emphasis on sustainability, pushing companies to offer eco-friendly and energy-efficient solutions.
Recent Developments:
- In January 2024, ZutaCore, a U.S.-based company specializing in liquid cooling technologies, announced a significant four-year commercial partnership with Valeo, an automotive technology company. This collaboration aims to enhance data center cooling solutions by integrating ZutaCore's innovative waterless two-phase direct-on-chip cooling system with Valeo's expertise. The partnership is designed to improve cooling efficiency for high-density servers while promoting sustainability by reusing heat and lowering carbon emissions. Valeo plans to deliver its first data center cooling components to ZutaCore in the second half of 2024.
- In March 2025, Accelsius, a subsidiary of Innventure, announced several key developments in the advanced liquid cooling technology sector. These include signing a three-year master purchasing agreement to white-label their cooling solution with a leading global thermal management company.
- In January 2025, Valeo announced that it had entered commercial production with Heat Reuse Units (HRUs) compatible with ZutaCore's HyperCool waterless direct-to-chip liquid cooling solution. These HRUs deliver 60kW of cooling power and are designed to enhance the efficiency and sustainability of data center operations by reusing waste heat for other industrial applications.
- In March 2025, Vertiv introduced the Vertiv CoolLoop Trim Cooler, a heat rejection system designed for hybrid liquid and air cooling applications in AI and high-performance computing environments. This system offers significant energy savings and space efficiency, aligning with the industry's need for compact and energy-efficient solutions
Market Concentration & Characteristics:
The U.S. data center liquid cooling market is moderately concentrated, with a mix of established global players and emerging innovators competing for market share. Leading companies such as Vertiv, Schneider Electric, CoolIT Systems, and Asetek dominate the industry, leveraging their technological expertise and extensive product portfolios. These firms invest heavily in research and development to introduce advanced cooling solutions that enhance efficiency, sustainability, and performance. The market is characterized by rapid technological advancements, driven by the increasing demand for high-performance computing, artificial intelligence, and cloud services. The adoption of direct-to-chip and immersion cooling technologies is expanding as data centers seek more efficient and sustainable cooling methods. Additionally, regulatory pressures and energy efficiency mandates are influencing market dynamics, encouraging companies to develop eco-friendly solutions. As competition intensifies, differentiation through innovation, customization, and energy-efficient solutions is becoming a key factor for long-term success in this evolving industry.
Report Coverage:
The research report offers an in-depth analysis based on type, application, component, and industry vertical It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The U.S. data center liquid cooling market is expected to witness steady growth, driven by increasing demand for high-performance computing and AI applications.
- Rising data center density will continue to accelerate the adoption of advanced liquid cooling solutions to manage escalating heat loads.
- Sustainability initiatives and stricter environmental regulations will push data centers toward more energy-efficient and eco-friendly cooling systems.
- Technological advancements in immersion and direct-to-chip cooling methods will enhance system efficiency and reliability.
- Growing investments in hyperscale data centers will contribute to the expanded deployment of liquid cooling technologies.
- Retrofitting existing data centers with liquid cooling systems will emerge as a cost-effective strategy for modernizing infrastructure.
- Increased collaboration between cooling technology providers and cloud service companies will drive innovation and customized solutions.
- Government incentives supporting energy-efficient infrastructure will encourage broader market adoption of liquid cooling technologies.
- Advancements in AI-driven cooling management systems will optimize operations and reduce energy consumption.
- The competitive landscape will intensify, with companies focusing on differentiation through innovation, sustainability, and strategic partnerships.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Data Center Liquid Cooling Market?
What factors are driving the growth of the U.S. Data Center Liquid Cooling Market?
What are some challenges faced by the U.S. Data Center Liquid Cooling Market?
Who are the major players in the U.S. Data Center Liquid Cooling Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Data Center Liquid Cooling Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. Data Center Liquid Cooling Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,173.1 million → 2032: USD 6,874.16 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Data Center Liquid Cooling Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Data Center Liquid Cooling Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Data Center Liquid Cooling Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. Data Center Liquid Cooling Market Drivers
- 3.3 U.S. Data Center Liquid Cooling Market Restraints & Challenges
- 3.4 U.S. Data Center Liquid Cooling Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Data Center Liquid Cooling Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Data Center Liquid Cooling Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Data Center Liquid Cooling category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Data Center Liquid Cooling Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. Data Center Liquid Cooling Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. Data Center Liquid Cooling market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Data Center Liquid Cooling Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. Data Center Liquid Cooling Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. Data Center Liquid Cooling Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Data Center Liquid Cooling (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. Data Center Liquid Cooling Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. Data Center Liquid Cooling Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. Data Center Liquid Cooling Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. Data Center Liquid Cooling Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. Data Center Liquid Cooling Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. Data Center Liquid Cooling Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. Data Center Liquid Cooling Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. Data Center Liquid Cooling Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. Data Center Liquid Cooling Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
