
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
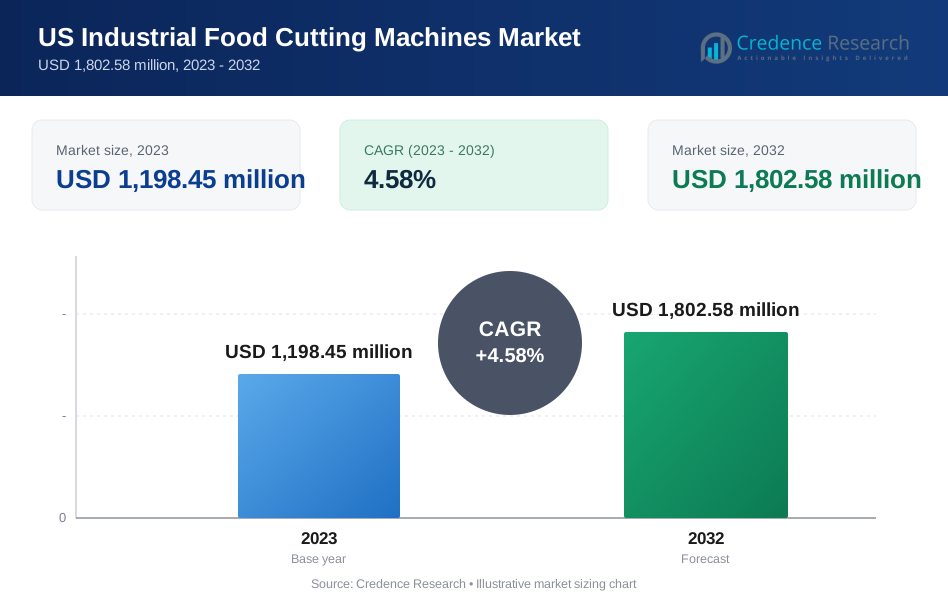
| US Industrial Food Cutting Machines Market Size 2023 | USD 1,198.45 million |
| US Industrial Food Cutting Machines Market, CAGR | 4.58% |
| US Industrial Food Cutting Machines Market Size 2032 | USD 1,802.58 million |
Market Overview
The US Industrial Food Cutting Machines Market is projected to grow from USD 1,198.45 million in 2023 to an estimated USD 1,802.58 million by 2032, with a compound annual growth rate (CAGR) of 4.58% from 2024 to 2032. This significant growth is driven by the increasing demand for processed and convenience foods, which necessitates efficient and high-capacity food cutting solutions.
Market drivers and trends include the rising adoption of automation in the food processing industry to improve operational efficiency and reduce labor costs. The growing consumer preference for ready-to-eat and packaged food products further propels the demand for industrial food cutting machines. Additionally, innovations such as smart cutting machines equipped with IoT and AI technologies are gaining traction, providing real-time monitoring and predictive maintenance capabilities to enhance productivity and minimize downtime.
Geographically, the US market is dominated by key regions such as the Midwest and the Southeast, where a significant number of food processing facilities are located. These regions benefit from robust infrastructure and access to raw materials. Major players in the market include Marel, GEA Group, and Urschel Laboratories, Inc., which are continuously innovating to offer advanced and efficient cutting solutions. Their strong distribution networks and comprehensive after-sales services contribute to their leading positions in the market.
Market Drivers
Increasing Demand for Processed and Convenience Foods
The escalating demand for processed and convenience foods is a primary driver of the US Industrial Food Cutting Machines Market. As modern lifestyles become more fast-paced, consumers are increasingly seeking quick and easy meal solutions. For instance, the consumption of ready-to-eat meals has seen a significant increase in sales over the past year. Processed foods, which include pre-cut fruits and vegetables, ready-to-eat meals, and packaged snacks, require precise and efficient cutting solutions to meet consumer expectations. Food cutting machines are essential in the processing of these products, ensuring uniformity, precision, and speed. The growing consumer base for processed and convenience foods necessitates high-capacity cutting machines that can handle large volumes while maintaining consistency and quality. Moreover, the food service industry, including restaurants, catering services, and fast-food chains, relies heavily on processed ingredients, further boosting the demand for industrial food cutting machines.
Rising Adoption of Automation in Food Processing
Automation is transforming the food processing industry by enhancing productivity, reducing labor costs, and improving operational efficiency. The adoption of automated food cutting machines is a significant driver of market growth. For instance, robot sales in food and consumer goods grew 13% year-over-year in Q2. Automated machines offer several advantages, including precision cutting, consistent quality, and the ability to handle complex cutting tasks that are challenging to perform manually. With the increasing focus on optimizing production processes, food processing companies are investing in advanced cutting technologies that integrate automation. These machines are equipped with features such as programmable controls, robotics, and sensors that enable precise cutting operations with minimal human intervention. Automation also reduces the risk of human errors, thereby improving overall product quality and safety. The labor-intensive nature of traditional food processing methods has led to a shift towards automation to address labor shortages and rising labor costs. Automated cutting machines not only enhance production capacity but also contribute to a safer and more hygienic working environment, as they minimize direct human contact with food products.
Advancements in Cutting Technology
Technological advancements in food cutting machines are driving market growth by offering innovative solutions that cater to the evolving needs of the food processing industry. The development of cutting-edge technologies, such as laser cutting, ultrasonic cutting, and water jet cutting, has revolutionized the way food products are processed. These technologies provide superior precision, reduced waste, and enhanced efficiency compared to traditional cutting methods. Laser cutting technology, for instance, allows for precise cuts with minimal product deformation, making it ideal for delicate and intricate food items. For instance, laser cutting technology allows for precise cuts with minimal product deformation, making it ideal for delicate and intricate food items such as thinly sliced fruits and vegetables. Ultrasonic cutting utilizes high-frequency vibrations to create clean and smooth cuts, reducing product sticking and ensuring uniformity. Water jet cutting, on the other hand, uses high-pressure water streams to slice through food products without generating heat, preserving the product’s texture and nutritional value. Moreover, the integration of smart technologies, such as the Internet of Things (IoT) and artificial intelligence (AI), into food cutting machines has enabled real-time monitoring, predictive maintenance, and data analytics. These advancements enhance machine performance, reduce downtime, and improve overall production efficiency, making them highly attractive to food processing companies looking to stay competitive in a rapidly evolving market.
Need for Food Safety and Quality
Food safety and quality are paramount concerns in the food processing industry, driving the demand for advanced food cutting machines that can ensure hygienic and safe processing conditions. The US food industry is subject to stringent regulations and standards set by agencies such as the Food and Drug Administration (FDA) and the United States Department of Agriculture (USDA). Compliance with these regulations necessitates the use of cutting machines that meet high standards of hygiene and safety. Industrial food cutting machines are designed to minimize the risk of contamination and ensure consistent product quality. They are constructed with food-grade materials and feature easy-to-clean components, reducing the likelihood of bacterial growth and cross-contamination. Additionally, these machines offer precise control over cutting parameters, ensuring that food products are cut uniformly and to the desired specifications, which is crucial for maintaining product quality and consumer satisfaction. The increasing awareness among consumers about food safety and quality further drives the demand for reliable and efficient food cutting machines. Food processing companies are investing in state-of-the-art cutting technologies to meet consumer expectations and regulatory requirements, thereby enhancing their market competitiveness.
Market Trends
Integration of Smart Technologies
One of the most notable trends in the US Industrial Food Cutting Machines Market is the integration of smart technologies such as the Internet of Things (IoT) and artificial intelligence (AI). These advancements are revolutionizing the food processing industry by enhancing machine functionality, improving operational efficiency, and ensuring higher levels of precision and consistency in food cutting processes. IoT-enabled cutting machines allow for real-time monitoring of machine performance and production parameters. This capability provides food processors with valuable insights into machine health, utilization rates, and potential issues, facilitating predictive maintenance and reducing downtime. For instance, a food processing company recently reported a 30% increase in productivity after adopting IoT-enabled cutting machines. AI, on the other hand, enhances the cutting process by enabling adaptive and intelligent decision-making. For example, AI algorithms have been used to optimize cutting patterns for meat processing, improving consistency and reducing waste. The adoption of smart technologies also supports traceability and compliance with stringent food safety regulations. Smart cutting machines can track and record every aspect of the cutting process, ensuring that food products meet quality standards and regulatory requirements. This trend is particularly significant as consumers become more conscious of food safety and quality, prompting food processors to invest in advanced technologies that enhance transparency and accountability.
Emphasis on Customization and Flexibility
Another significant trend in the US Industrial Food Cutting Machines Market is the growing emphasis on customization and flexibility. Food processors are increasingly seeking cutting solutions that can be tailored to their specific needs and can handle a wide variety of food products with varying textures, sizes, and shapes. For instance, the production of fruit yogurt has been revolutionized by the use of highly flexible, automated machinery that can output customized products at high volumes. This demand for versatility has led to the development of modular cutting machines that offer interchangeable blades and adjustable settings, allowing for quick and easy modifications to meet diverse processing requirements. Customization extends beyond the physical attributes of the machines to include software and control systems. Advanced cutting machines now come equipped with user-friendly interfaces and programmable controls that enable operators to customize cutting parameters, automate repetitive tasks, and integrate with other processing equipment. This level of flexibility is crucial for food processors looking to adapt to changing market demands, introduce new products, and maintain competitive advantage. Furthermore, the trend towards customization and flexibility is driven by the increasing popularity of specialty and niche food products. As consumers seek unique and diverse food options, food processors must be able to efficiently produce small batches of customized products. Flexible cutting machines that can easily switch between different cutting tasks and accommodate various product specifications are essential for meeting this demand
Market Restraints and Challenges
High Initial Investment and Maintenance Costs
A significant restraint in the US Industrial Food Cutting Machines Market is the high initial investment and maintenance costs associated with advanced cutting equipment. Industrial food cutting machines, especially those integrated with smart technologies like IoT and AI, come with substantial upfront costs. These machines are often equipped with sophisticated features and advanced materials that drive up their price. For small and medium-sized enterprises (SMEs), this high cost can be a significant barrier to entry, limiting their ability to adopt state-of-the-art cutting solutions. Moreover, the maintenance and operational costs of these machines add to the financial burden. Advanced cutting machines require regular maintenance to ensure optimal performance and longevity, which involves costs for spare parts, skilled technicians, and potential downtime during maintenance periods. The complexity of these machines also means that any malfunctions or breakdowns can be costly and time-consuming to repair. These financial challenges can deter food processing companies from investing in new cutting technologies, thereby restraining market growth.
Technical Complexity and Skilled Labor Shortage
The technical complexity of modern industrial food cutting machines poses a significant challenge for the market. These machines often require specialized knowledge and expertise to operate and maintain, which can be a hurdle for companies lacking a skilled workforce. The integration of smart technologies, while beneficial, adds layers of complexity to machine operation and troubleshooting, necessitating continuous training and upskilling of personnel. The food processing industry is experiencing a shortage of skilled labor, particularly in technical roles. Finding and retaining qualified operators and maintenance personnel who can handle the sophisticated machinery is becoming increasingly difficult. This shortage not only affects the efficient operation of cutting machines but also impacts the overall productivity and profitability of food processing companies. Additionally, the learning curve associated with new technologies can be steep. Companies must invest in extensive training programs to ensure their workforce can effectively use and maintain advanced cutting machines. This requirement for ongoing education and training can be resource-intensive, both in terms of time and cost, further exacerbating the challenges faced by the industry.
Market Segmentation Analysis
By Product
The US Industrial Food Cutting Machines Market is segmented into food slicers, dicers, shredders, and other specialized machines. Food slicers are crucial for processing meats, cheeses, and vegetables, providing uniform and precise slices, thereby reducing manual labor and ensuring consistency in food products for retail and foodservice industries. Food dicers, essential for creating uniform cubes or dices of vegetables, fruits, and meats, are growing in demand due to the popularity of pre-packaged and ready-to-eat food products. Food shredders cater to the processing of cheese, vegetables, and other items for salads, pizzas, and baked goods, with their efficiency and consistency driving their use in large-scale production. The 'others' category includes specialized machines like food choppers and graters, which address niche applications by providing tailored cutting solutions, driven by the need for customization and innovation in food product offerings.
Based on Application
The cheese processing segment requires precise cutting solutions to produce uniformly sliced, diced, or shredded cheese products, driven by the growing demand in culinary applications like pizzas, sandwiches, and salads. The meat processing industry relies heavily on cutting machines for slicing, dicing, and shredding, with increasing consumption of processed meat products boosting the need for efficient meat cutting solutions. The fruits and vegetables segment demands cutting machines capable of handling various textures and sizes while maintaining integrity and reducing waste, fueled by the trend of healthy eating and the popularity of pre-cut items in retail. Additionally, specialized applications such as bakery products, seafood, and confectionery items necessitate versatile and adaptable cutting machines to meet specific processing requirements across diverse products.
Segments
Based on Product
- Food Slicers
- Food Dicers
- Food Shredders
- Others
Based on Application
- Cheese
- Meat
- Fruits and Vegetables
- Others
Based on Region
- Midwest
- Southeast
- Northeast
- West
Regional Analysis
Midwest (30%):
The Midwest region holds a significant share of the US Industrial Food Cutting Machines Market, accounting for approximately 30% of the total market. This region's dominance is attributed to its robust agricultural base and high concentration of food processing facilities. The Midwest, often referred to as the "Breadbasket of America," is home to major meat, dairy, and grain processing industries. The abundance of raw materials and well-established infrastructure support the demand for advanced food cutting machines. Companies in this region invest heavily in automated and efficient cutting solutions to enhance productivity and meet the growing demand for processed food products.
Southeast (25%):
The Southeast region contributes around 25% to the US Industrial Food Cutting Machines Market. This area is characterized by a rapidly growing food processing industry, driven by an increasing population and a strong foodservice sector. The Southeast's favorable climate for agriculture supports a diverse range of food products, including fruits, vegetables, and poultry. The region's food processors are adopting advanced cutting technologies to keep pace with the rising demand for convenience foods and ready-to-eat meals. Additionally, the proximity to major ports facilitates the export of processed food products, further boosting the need for efficient cutting machines.
Key players
- FAM
- GEA Group
- TREIF Maschinenbau
- Urschel Laboratories
- Buhler
- Holac Maschinenbau
- MARELEC Food Technologies
- Nilma
- Sormac
- Stephan Machinery
Competitive Analysis
The US Industrial Food Cutting Machines Market is characterized by intense competition among several key players, each offering unique solutions and innovations. Urschel Laboratories and TREIF Maschinenbau are prominent for their high-precision and versatile cutting technologies, catering to a wide range of food processing needs. GEA Group and Buhler excel in integrating advanced automation and smart technologies into their machines, enhancing operational efficiency and productivity. FAM and Holac Maschinenbau are known for their robust and reliable cutting equipment, which is widely adopted in various food processing sectors. MARELEC Food Technologies focuses on precision and speed, offering state-of-the-art cutting solutions for meat and seafood processing. Nilma and Sormac provide specialized equipment tailored to specific applications, such as vegetable processing, ensuring high quality and consistency. Stephan Machinery stands out for its innovative approaches to cutting and processing, meeting the evolving demands of the industry. Together, these players drive the market forward through continuous innovation and competitive strategies.
Recent Developments
In May 2021, GEA Group Aktiengesellschaft launched the GEA OptiSlicer 6000, an advanced industrial slicer engineered for precise and efficient slicing of meat and cheese products. This state-of-the-art machine incorporates cutting-edge technology to ensure consistent slicing thickness and reduce product waste. Furthermore, in January 2023, GEA Group introduced the GEA MultiFormer, an innovative forming solution designed to shape food products, thereby enhancing production flexibility and product quality.
In May 2020, ANDRITZ introduced the ADuro product line of recycling shredders, designed for primary and secondary shredding as well as fine granulation of food products. These shredders offer high efficiency and versatility, capable of handling various food waste materials effectively. In February 2022, ANDRITZ expanded their product portfolio with the ADuro F shredder, specifically tailored for fine granulation processes, meeting diverse industrial needs with enhanced performance.
Urschel Laboratories remains at the forefront of food cutting innovation. In September 2022, they unveiled the Affinity Integra-D Dicer, a compact and high-performance dicing machine ideal for small to mid-sized processors. This machine ensures precision cutting for a variety of food products, delivering high yield and quality. In April 2023, Urschel introduced the Sprint 2 Dicer, which features improved sanitation and maintenance capabilities, addressing the growing demand for hygienic and efficient food processing equipment.
Buhler continues to advance food processing technology with significant innovations. In March 2022, Buhler launched the PolyCut cutting system, which enhances the precision and efficiency of food cutting operations. Designed for versatility, the PolyCut system accommodates various food types seamlessly. Additionally, in November 2023, Buhler introduced the Sortex A GlowVision optical sorter, offering superior sorting accuracy and efficiency for processed food products, underscoring their commitment to innovation and quality.
Market Concentration and Characteristics
The US Industrial Food Cutting Machines Market is characterized by a moderate to high level of market concentration, with a few key players such as Urschel Laboratories, GEA Group, and TREIF Maschinenbau dominating the landscape. These companies lead the market through continuous innovation, advanced technology integration, and comprehensive product offerings. The market is marked by significant investment in automation and smart technologies, which enhance operational efficiency and precision. Additionally, there is a strong focus on customization, sustainability, and compliance with stringent health and safety regulations. The competitive landscape is shaped by strategic mergers and acquisitions, expanding geographical reach, and robust after-sales support to maintain machine efficiency and reliability.
Report Coverage
The research report offers an in-depth analysis based on Product, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued integration of smart technologies, such as IoT and AI, will enhance precision and efficiency in food cutting operations, driving market growth.
- The increasing adoption of automated food cutting machines will reduce labor costs and improve productivity, becoming a key trend in the industry.
- There will be a growing emphasis on sustainable cutting solutions that minimize waste and reduce energy consumption, aligning with environmental regulations and consumer preferences.
- The market will see a rise in demand for customizable cutting machines that can handle diverse food products and adapt to specific processing requirements.
- Stricter health and safety regulations will drive innovation in hygienic design and materials, ensuring food cutting machines meet the highest standards.
- Increased mergers and acquisitions among key players will lead to market consolidation, enhancing technological capabilities and expanding product portfolios.
- Rising consumer demand for convenience foods and ready-to-eat meals will fuel the need for advanced food cutting machines that deliver consistent quality and efficiency.
- Key market players will expand their presence in emerging regions, leveraging local manufacturing and distribution networks to meet growing demand.
- The importance of robust after-sales services, including maintenance and training, will increase as companies strive to maximize machine uptime and efficiency.
- Ongoing research and development will lead to innovative cutting techniques, such as laser and ultrasonic cutting, offering new capabilities and improved product quality.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for the US Industrial Food Cutting Machines Market by 2032?
What are the main drivers of growth in the US Industrial Food Cutting Machines Market?
Which regions dominate the US Industrial Food Cutting Machines Market?
Who are the key players in the US Industrial Food Cutting Machines Market?
What technological advancements are influencing the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 US Industrial Food Cutting Machines Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global US Industrial Food Cutting Machines Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,198.45 million → 2032: USD 1,802.58 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 US Industrial Food Cutting Machines Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. US Industrial Food Cutting Machines Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 US Industrial Food Cutting Machines Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 US Industrial Food Cutting Machines Market Drivers
- 3.3 US Industrial Food Cutting Machines Market Restraints & Challenges
- 3.4 US Industrial Food Cutting Machines Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 US Industrial Food Cutting Machines Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 US Industrial Food Cutting Machines Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, US Industrial Food Cutting Machines category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 US Industrial Food Cutting Machines Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. US Industrial Food Cutting Machines Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the US Industrial Food Cutting Machines market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 US Industrial Food Cutting Machines Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 US Industrial Food Cutting Machines Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 US Industrial Food Cutting Machines Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in US Industrial Food Cutting Machines (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New US Industrial Food Cutting Machines Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global US Industrial Food Cutting Machines Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America US Industrial Food Cutting Machines Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe US Industrial Food Cutting Machines Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific US Industrial Food Cutting Machines Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America US Industrial Food Cutting Machines Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East US Industrial Food Cutting Machines Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa US Industrial Food Cutting Machines Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. US Industrial Food Cutting Machines Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
