
Adult hobbyists, licensed art and tariffs set demand
The U.S. jigsaw puzzle market was valued at USD 634.8 million in 2025 and is projected to increase from USD 667.2 million in 2026 to USD 1.04 billion by 2035, registering a CAGR of 5.10% during 2026–2035. Demand comes from adults who buy large, detailed puzzles as a screen-free hobby, from parents and preschools buying chunky and floor puzzles, and from gift buyers who choose licensed and custom photo designs. The South held the largest regional share, 35.5% in 2025, and it is also the fastest-growing region at 5.5% a year, because it is the only Census region where the child population grew between 2020 and 2025. The main commercial change is trade policy, since most puzzles sold in the country are imported from China and face shifting U.S. import duties. Domestic factories in New York, Massachusetts and Colorado gain a cost edge as a result.
Retail value counts paperboard, wooden and custom puzzles
The report counts U.S. retail sales of jigsaw puzzles made from paperboard, wood and plastic, including adult puzzles of 300 to 2,000 or more pieces, children's floor, chunky and peg puzzles, and custom photo puzzles printed on demand. Sales through mass merchants, supermarkets, online stores, toy and hobby shops, bookstores, museum shops and gift stores are included at the price the shopper pays.
Three-dimensional brain teasers, mechanical puzzles, puzzle apps and digital jigsaw games are excluded, as are puzzle accessories such as boards and sorting trays sold separately. The value chain runs from paperboard mills, art licensors and printers through domestic and Chinese cutting plants to brand owners, importers and retailers, where store brands compete with branded lines on price.
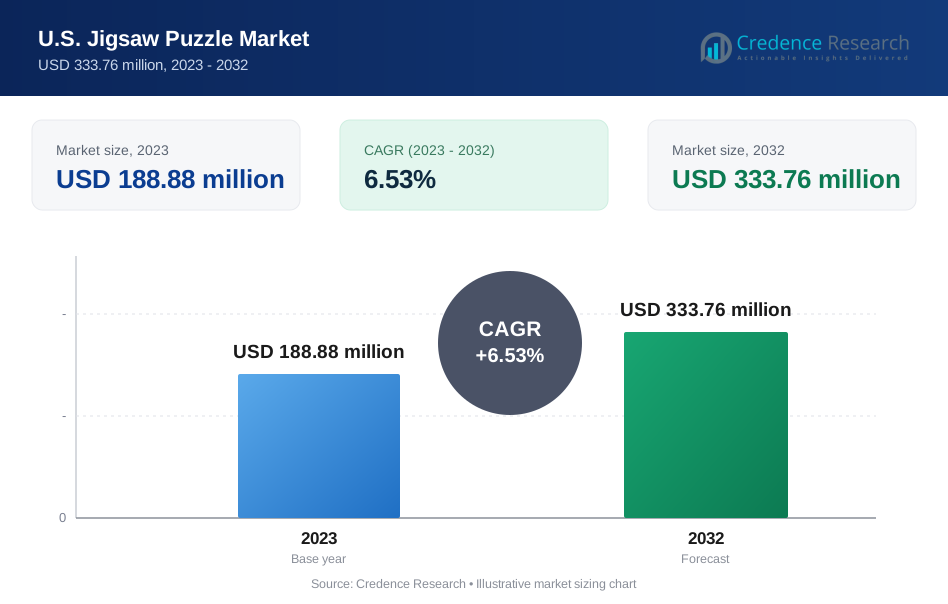
US Jigsaw Puzzle Market Insights
- The market reached USD 634.8 million in 2025 and is projected to reach USD 1.04 billion by 2035 at a 5.10% CAGR, with adult hobby demand and higher shelf prices setting the pace.
- The South held 35.5% of 2025 value and grows fastest at 5.5% a year, as its child population rose 1.1% between 2020 and 2025.
- Paper puzzles led materials with 81.0% of 2025 value, while Wood puzzles grow fastest at 6.4% a year from a small base.
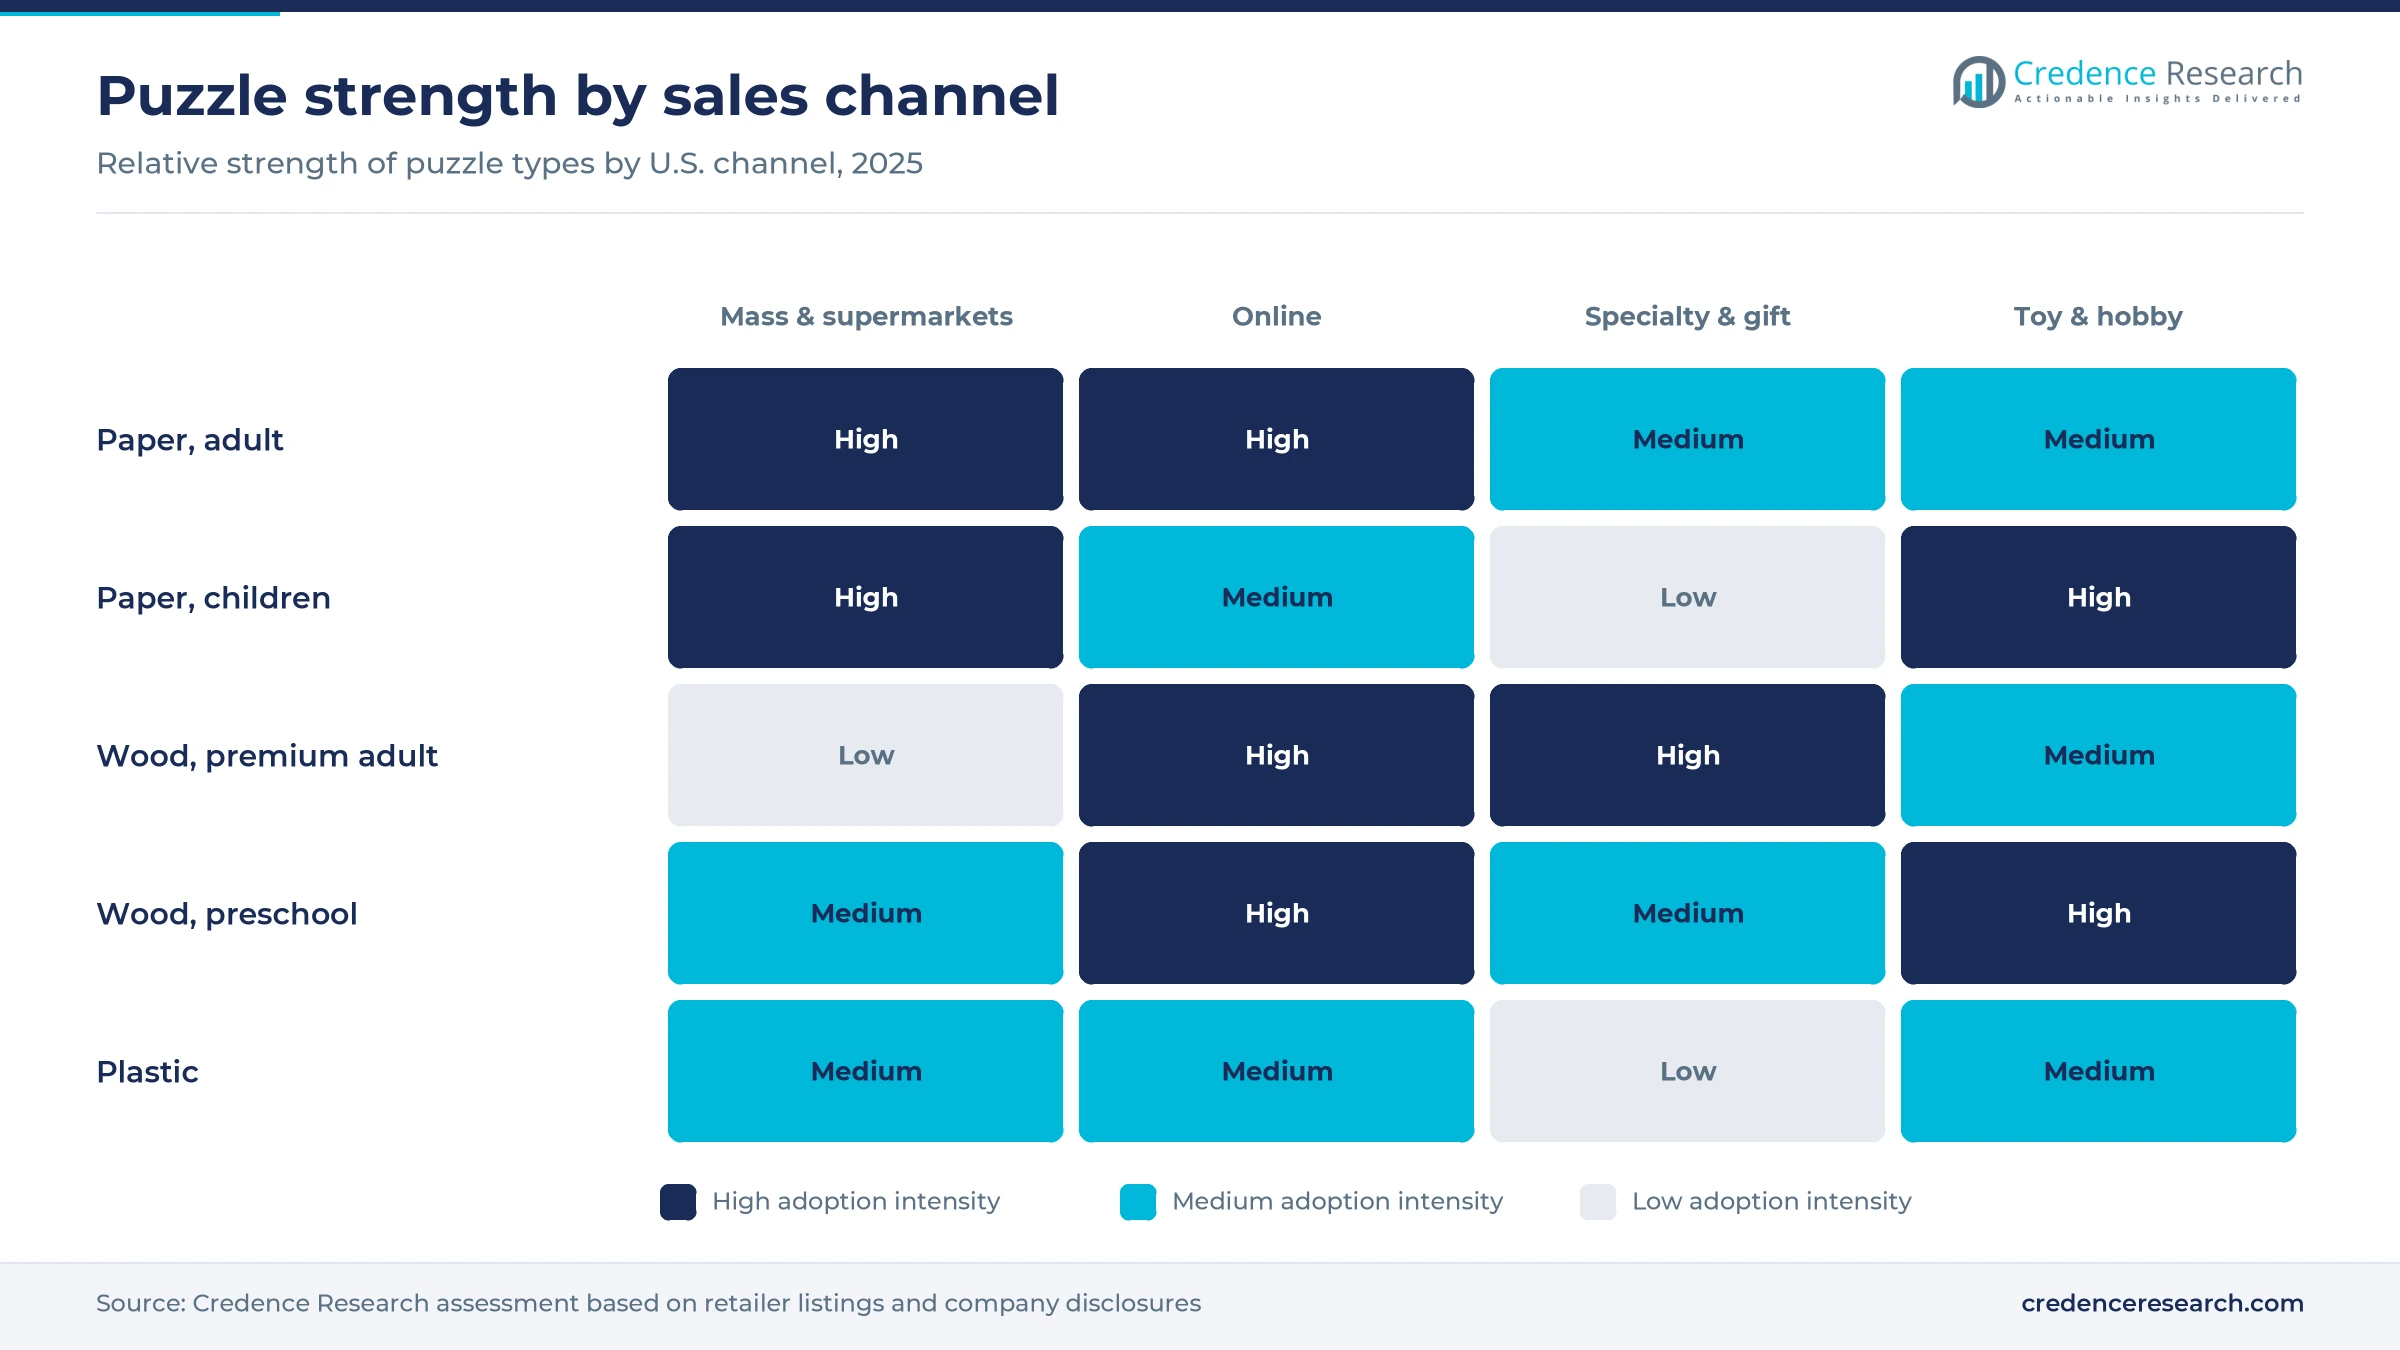
- The Supreme Court struck down the IEEPA tariffs on Feb. 20, 2026, and the 10% Section 122 surcharge that followed expired on July 24, 2026.
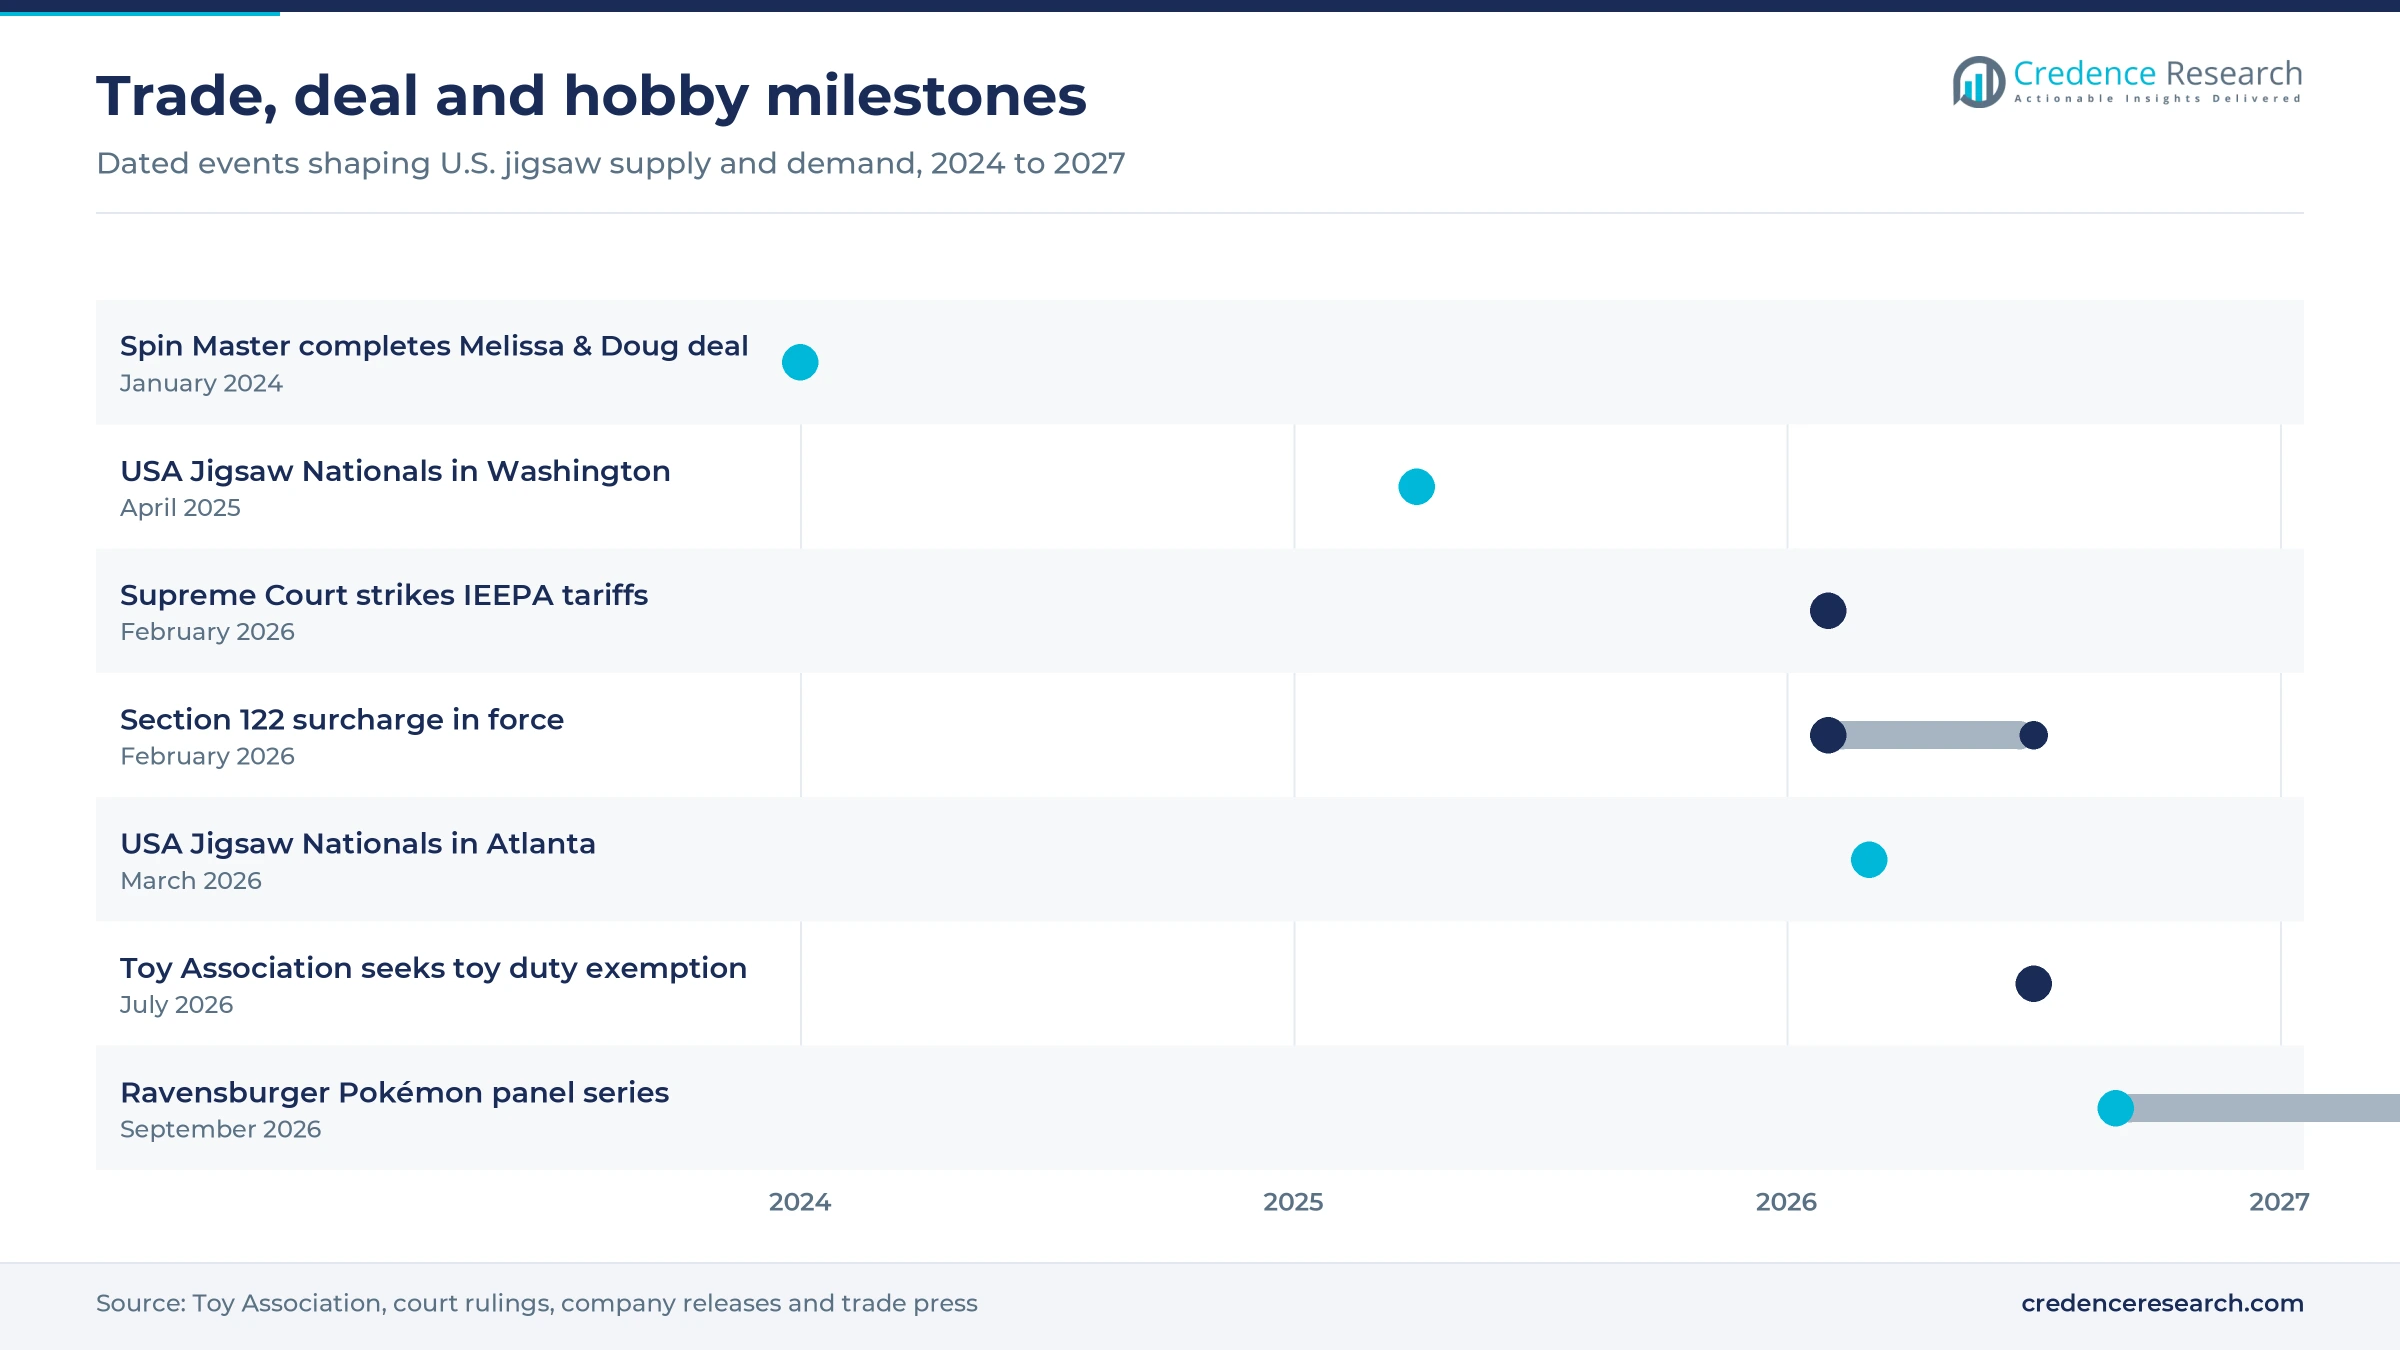
- Registrations at the USA Jigsaw Puzzle Nationals rose from 99 individuals in 2022 to 800 in 2026, a sign of a deeper adult hobby base.
Paper leads while wooden and online sales grow fastest
Why does paperboard dominate while wood gains?
Based on material, the market is categorized into wood, plastic and paper, and paperboard carries almost every adult design. Paper puzzles led with 81.0% of 2025 value because die-cut paperboard keeps a 1,000-piece puzzle at retail prices of USD 13.99 to 21.99, the range Ceaco, Buffalo Games and Springbok list on their own stores in November 2026. Wood puzzles grow fastest at 6.4% a year, as laser cutting lets small makers sell premium sets, and Liberty Puzzles runs 90 laser cutters in Boulder, Colorado, with most 500-piece puzzles at USD 115, according to the Alliance for American Manufacturing.
Why do adults outspend parents on puzzles?
Based on application, the market is categorized into children and adults. Adults led with 57.0% of 2025 value because adult hobbyists buy higher piece counts at higher prices, and adults already accounted for more toy sales than preschoolers in 2024, Retail Dive reported, citing Circana. Adults grow fastest at 5.6% a year, as adult-only households made up 55% of U.S. toy sales in the first half of 2026 and grew 16%, eMarketer reported, citing Circana. Children's puzzles grow more slowly because the under-18 population fell in three regions.
Why do mass retailers lead and online grows fastest?
Based on distribution channel, the market is categorized into sports and recreational stores, online retailers, specialty stores, supermarkets and hypermarkets, and others. Supermarkets/Hypermarkets led with 35.0% of 2025 value because licensed and impulse puzzles sell beside toys and seasonal goods at mass merchants, where Springbok, Buffalo Games and White Mountain all list adult puzzles on Walmart. Online Retailers grow fastest at 6.3% a year, as e-commerce reached 17.1% of U.S. retail sales in the second quarter of 2026, according to the Census Bureau, and collectors search deep catalogs online.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Material | Paper | 81.0% | Wood | 6.4% |
| By Application | Adults | 57.0% | Adults | 5.6% |
| By Distribution Channel | Supermarkets/Hypermarkets | 35.0% | Online Retailers | 6.3% |
A mass-market 1,000-piece set lists near USD 18
Jigsaw puzzles are priced per box, and piece count, board thickness, licensed art and cut quality set the tier. Mass-market 1,000-piece puzzles cluster between USD 14 and USD 22, while art-led brands such as New York Puzzle Company list near USD 29, and laser-cut wooden sets sell for several times that. Import duties move the whole ladder, because most mass-market boxes are cut in China, so the duties described in the challenges section raise landed costs. Domestic cutters can hold prices more easily, which gives them room to win shelf space from importers.
| Offer or segment | Typical price or fee | Basis |
|---|---|---|
| Ceaco 1,000-piece puzzle | USD 13.99 to 15.99 list | Ceaco online store, November 2026 |
| Buffalo Games 1,000-piece puzzle | USD 17.99 list | Buffalo Games online store, November 2026 |
| Galison 1,000-piece puzzle | USD 19.99 to 21.99 list | Galison online store, November 2026 |
| Springbok 1,000-piece puzzle, made in USA | USD 21.99 list | Springbok online store, November 2026 |
| New York Puzzle Company 1,000-piece puzzle | USD 29.00 list | New York Puzzle Company store, November 2026 |
| Liberty Puzzles laser-cut wooden puzzle | USD 44 to 225, most USD 115 | Alliance for American Manufacturing, December 2024 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Adult buyers, licensing and speed events lift spending
Adult buyers now account for most toy spending
Adults buy larger, pricier puzzles than children, so their rising share of toy spending lifts value per box. The games and puzzles supercategory rose 45% in the first half of 2026, eMarketer reported, citing Circana. Ravensburger, which names adult puzzles as a strong seller in international markets, reported 11% sales growth in the United States and Canada for 2025, according to Spielwarenmesse. Adult ranges carry art licenses, foil finishes and higher piece counts, and art-led brands list most adult boxes near or above USD 20. The adult lead, 57.0% of 2025 value, favors brands with large art catalogs, while children-focused makers depend on a slower family base.
Licensed franchises drive puzzle demand in the toy aisle
Entertainment licenses give puzzles a reason to sit beside the year's strongest toys, which brings extra traffic and impulse purchases. Games and puzzles was the largest U.S. toy supercategory in 2025, with dollar sales up 37%, mainly because of Pokémon, according to Circana data released by the Toy Association on Feb. 3, 2026. Ravensburger planned its first U.S. SpongeBob puzzle line, LaughingPlace reported in May 2026. Its six Disney Lorcana puzzles launched in the fall of 2025. License holders gain shelf space at mass merchants, while unlicensed art brands rely on specialty and online buyers. Licensed designs also age quickly, so brands must refresh them every season to hold placement.
Competitive puzzling deepens the adult hobby base
Speed events turn a solitary pastime into a repeat-purchase hobby, because competitors practice on many unseen puzzles each month. The USA Jigsaw Puzzle Association, co-founded in 2020 by Guinness record holder Tammy McLeod, held the 2026 Nationals in Atlanta, NPR member stations reported on March 27, 2026. Registration rose from 99 individuals, 93 pairs and 33 teams at the first Nationals in San Diego in 2022 to 800 individuals, 400 pairs and 200 teams in 2026, according to The Independent. Ravensburger has redesigned its Sort & Go trays to competition sizing, which shows suppliers building products around this audience. Brands that release unseen designs often gain the most from this repeat buying.
Higher toy prices lift value per puzzle sold
Rising shelf prices raise market value even where unit sales are flat, and puzzles follow the wider toy aisle. Toy prices rose 6.6% year over year in September 2026, according to Bureau of Labor Statistics data reported by Retail Dive. Average toy selling prices had already risen 4% in 2025, Circana data show. The BLS toy price index climbed from 28.729 in August 2026 to 30.374 in October 2026, Federal Reserve Economic Data show. Brands with domestic cutting capacity can raise prices less than importers, which helps them gain share while importers protect margins. Price-sensitive families may trade down to smaller boxes if increases continue into 2027.
Domestic cutting, collector formats and photo printing
Brands shift cutting toward domestic plants
Puzzle brands are shifting production toward U.S. plants to limit exposure to duties on Chinese imports. Buffalo Games makes about 10 million puzzles a year at its Buffalo, New York, facility, WGRZ reported. Its November 2020 purchase of Ceaco and Ceaco's contract manufacturer Edaron lifted headcount from about 110 to about 350, aNb Media reported. White Mountain Puzzles makes its puzzles mainly in Holyoke, Massachusetts, with more work in Indiana, according to Puzzle Warehouse. Springbok labels its adult puzzles as made in the USA on retail listings. Domestic capacity favors brands that can promise steady holiday supply, while importers carry tariff and freight risk.
Collector formats and hybrid games rise in new lines
Suppliers are shifting toward formats that turn a single puzzle into a series or a social game, which increases spending per buyer. Ravensburger's ten-panel Pokémon set releases three panels in fall 2026, two more before year-end and the last five in 2027, LaughingPlace reported. Its Speedy Puzzle mixes assembly with party-game challenges, and its Disney Collector's Edition added Stitch and Moana. Galison sells foil, shaped, panoramic and wooden puzzles from 100 to 2,000 pieces, according to its company page. Series formats suit dedicated collectors and board game cafes, while single-box commodity designs face tougher price competition at mass retailers.
Memory care and senior living need adapted sets
Older adults and memory care programs need puzzles with fewer, larger pieces and clear images, a format that mainstream adult catalogs rarely stock in depth. An estimated 7.2 million Americans aged 65 and older live with Alzheimer's dementia in 2025, and the number is projected to reach about 12.7 million by 2050, according to the Alzheimer's Association. The 65-and-older population grew in every Census region between 2020 and 2025, even in the Northeast, where it rose 14.6%. Makers that sell 36- to 300-piece adult designs to senior living operators and caregivers can gain steady institutional orders, although no public source tracks this channel, so its size remains a Credence Research estimate.
Preschool and wooden sets open a premium children's tier
Parents and early learning centers increasingly choose durable wooden and chunky puzzles, which sell for more than paperboard sets and suit open-ended play. Spin Master completed its USD 950 million acquisition of Melissa & Doug in January 2024, aNb Media reported, bringing a large catalog of wooden jigsaw, peg and floor puzzles under a global toy company. Ravensburger anchors its preschool range on Bluey and Peppa Pig and added heart-shaped 48-piece Disney Princess sets, LaughingPlace reported in May 2026. Suppliers of wooden toys and educational toys can extend into this tier, although the shrinking child population in three regions limits the volume opportunity for new entrants.
Import duties, child population loss and screen time
Import duties raise landed costs for China-made boxes
Most mass-market puzzles are cut in China, so every change in duty rates passes quickly into costs. About 76% of toys and puzzles sold in the United States come from China, Al Jazeera reported in May 2025, citing The New York Times. The Toy Association formally asked the U.S. Trade Representative on July 6, 2026, to exempt toy headings including HTS 9503.00.00 from new Section 301 duties, and public summaries do not confirm whether puzzles are covered. Importers and store-brand programs are most exposed, while domestic cutters gain.
Legal swings make tariff planning unreliable
Duty rules changed four times in 2026, which complicates holiday buying and pricing for importers. The Supreme Court struck down the IEEPA tariffs on Feb. 20, 2026, in a case brought by educational toy maker Learning Resources, and a 10% Section 122 surcharge followed on Feb. 24, the Toy Association reported. The Court of International Trade ruled that surcharge unlawful on May 7, 2026, but collection continued pending appeal until it expired in July. Smaller importers without customs counsel face the greatest planning risk.
A shrinking child population limits family demand
Fewer children means fewer first puzzles, birthday gifts and classroom orders for the children's segment. Between 2020 and 2025, the population under 18 fell 4.1% in the Northeast, 3.9% in the Midwest and 5.7% in the West, while it rose 1.1% in the South, according to the U.S. Census Bureau. Brands that rely on preschool licenses in northern and western states are most exposed, which pushes them toward adult lines.
Store brands and discounting compress branded margins
Mass retailers sell puzzles as seasonal and impulse items, which puts steady pressure on branded list prices. The price table above shows only about USD 4 between the main mass-tier brands, so a retailer's own label can undercut them with little visible loss of quality. Brands without licenses or distinctive art are most exposed when retailers fill shelves with private-label boxes. Annual line reviews give retailers further leverage, which can push branded makers toward deeper promotions in the holiday season.
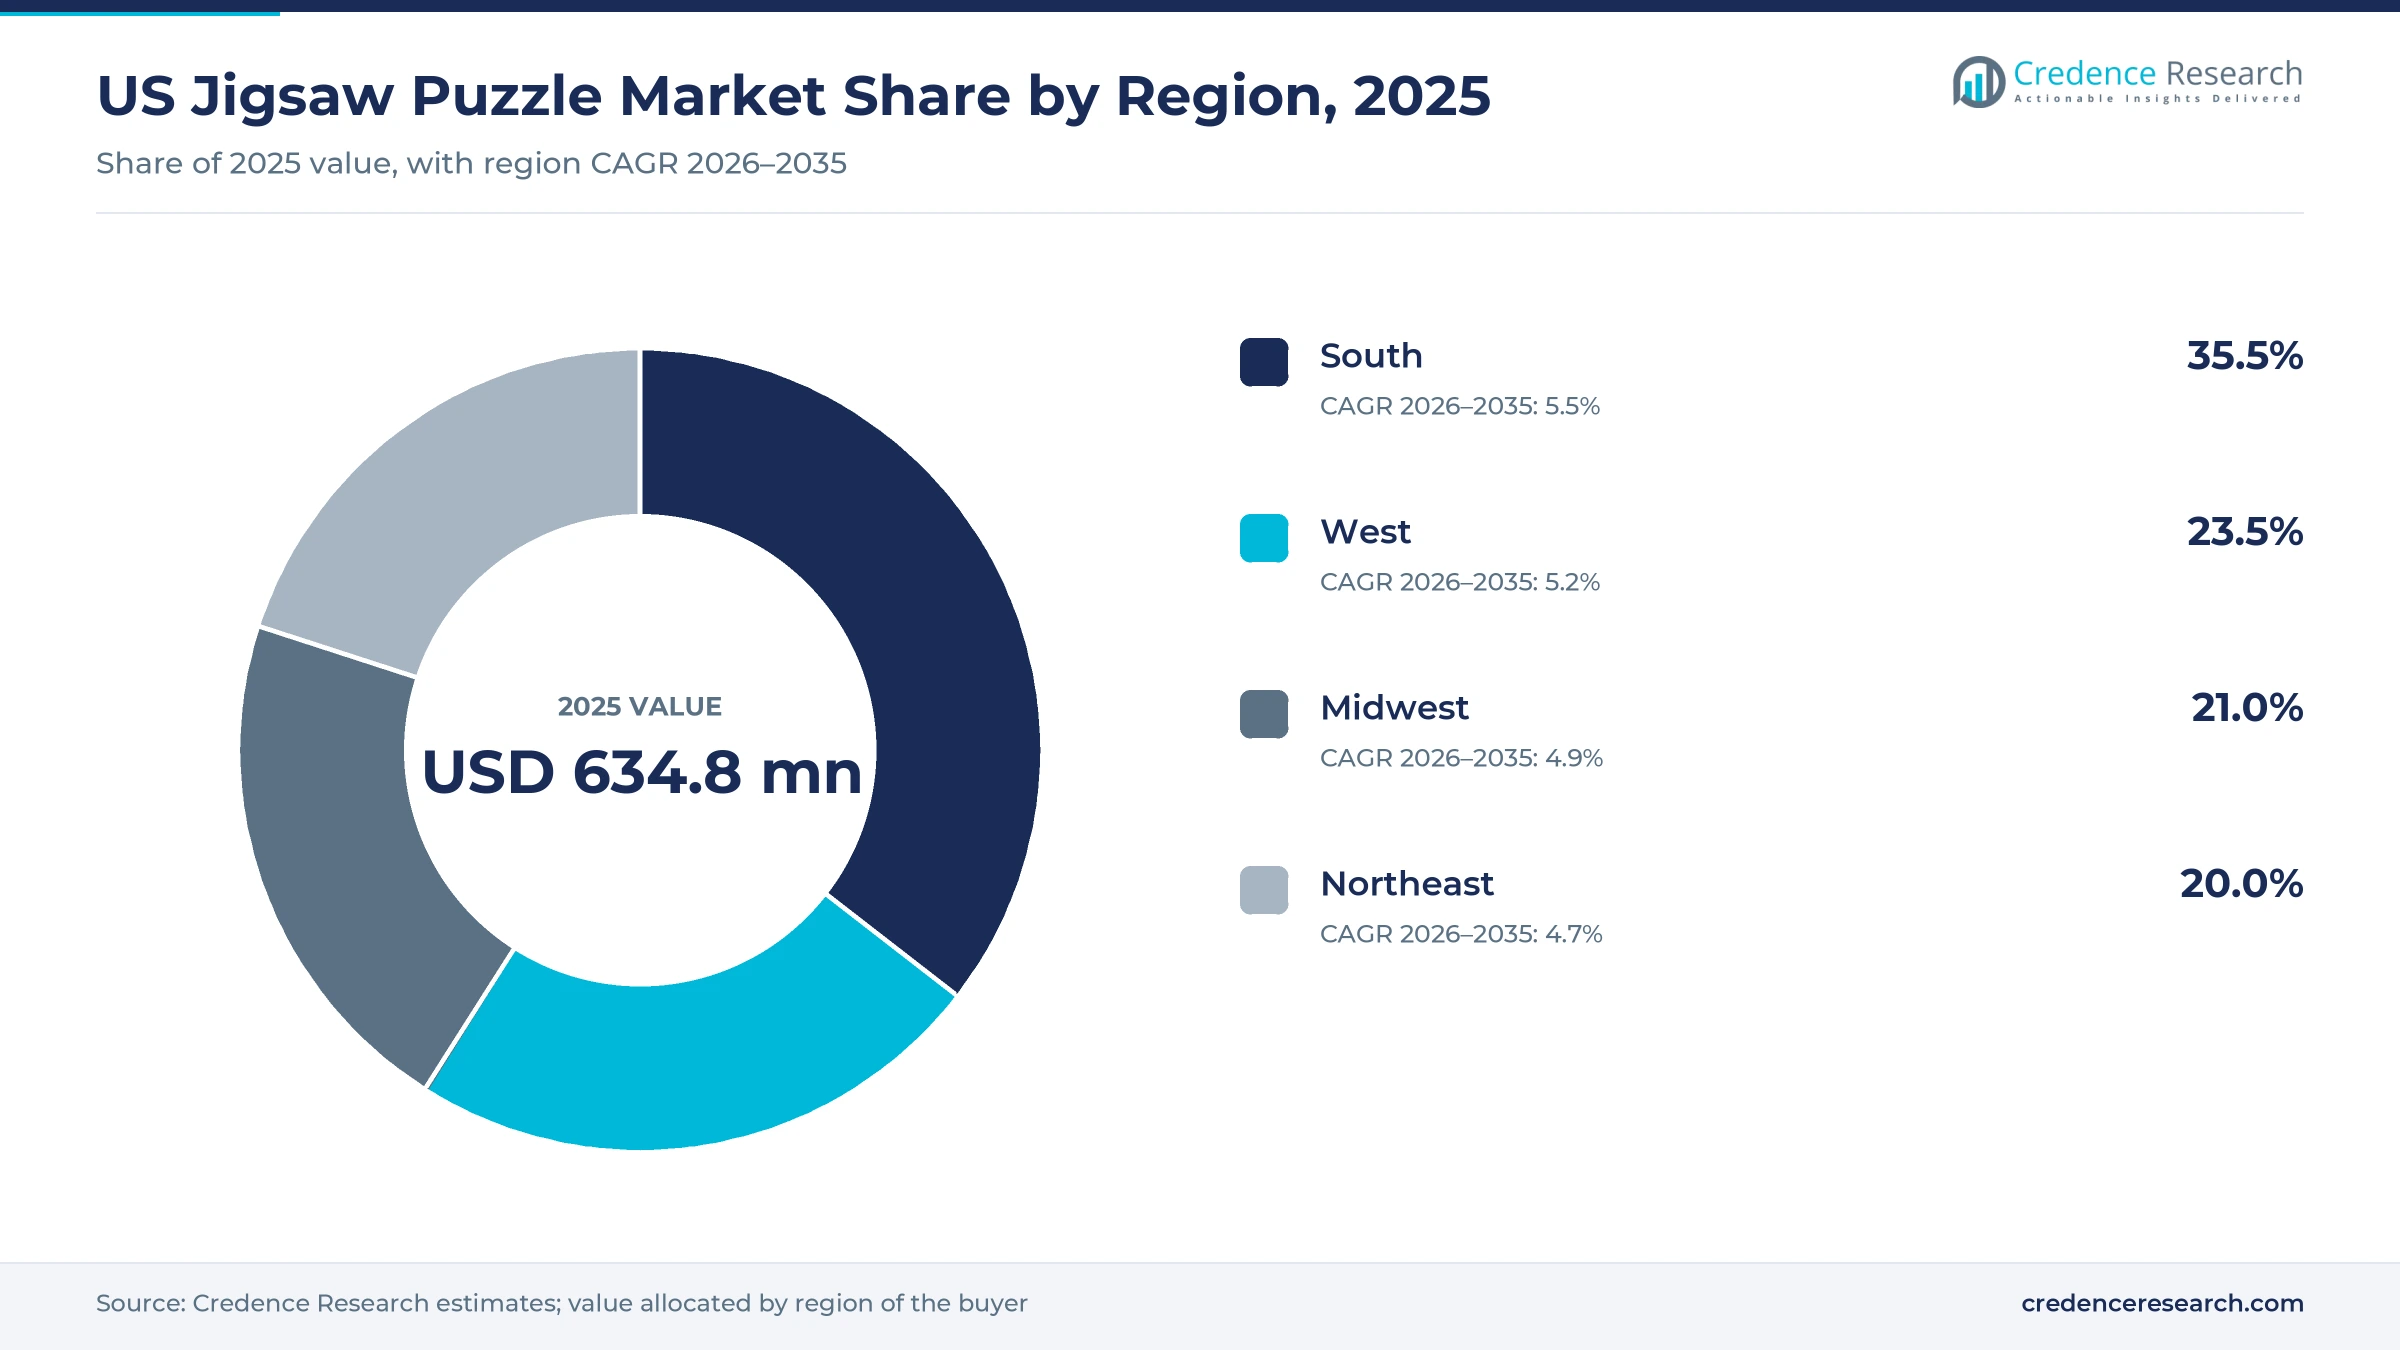
The South leads on population and young families
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| South | 225.4 | 35.5% | 5.5% |
| West | 149.2 | 23.5% | 5.2% |
| Midwest | 133.3 | 21.0% | 4.8% |
| Northeast | 127.0 | 20.0% | 4.7% |
The South leads on population and young families
The South held 35.5% of 2025 value and grows fastest at 5.5% a year. Its population grew 6% between April 2020 and July 2025, nearly double the 3.1% national rate, and it was the only region whose population under 18 grew, according to the Census Bureau. That gives the South the strongest base for both children's puzzles and family gifting. Atlanta hosted the 2026 USA Jigsaw Puzzle Nationals, which adds visible hobby activity to a region served mainly through mass merchants.
The West pays more for premium and wooden sets
The West held 23.5% of 2025 value and grows at 5.2% a year. Its population under 18 fell 5.7% between 2020 and 2025, the largest drop of any region, so children's puzzle volume is under pressure. Adult and premium demand offsets part of that decline, and Liberty Puzzles runs two factories in Boulder, Colorado, with 130 employees cutting wooden puzzles.
The Midwest relies on mass retail and value buyers
The Midwest held 21.0% of 2025 value and grows at 4.8% a year. Its population under 18 fell 3.9% between 2020 and 2025, so growth depends on adults and gift buyers rather than young families. Supermarkets and mass merchants carry most volume in the region, where standard paperboard puzzles in the mass price tier dominate shelves, a Credence Research estimate, since no regional channel data are published. White Mountain Puzzles adds production work in Indiana, which shortens delivery to Midwestern retailers.
The Northeast hosts the largest domestic makers
The Northeast held 20.0% of 2025 value and grows at 4.7% a year, the slowest regional pace. Its population under 18 fell 4.1% between 2020 and 2025, and it saw the slowest growth among people aged 65 and older. The region still hosts much of the domestic cutting capacity, since Buffalo Games cuts about 10 million puzzles a year in Buffalo, New York and White Mountain cuts in Holyoke, Massachusetts. Galison, a publisher founded in 1979, designs its puzzles in New York City.
Tariff rulings, a Spin Master deal and new formats
| Development | Status and market relevance |
|---|---|
| In January 2024, Spin Master completed its USD 950 million acquisition of Melissa & Doug, a maker of wooden and chunky children's puzzles. | Acquisition completed; adds a large preschool puzzle catalog to a global toy group |
| In February 2026, the Supreme Court struck down the IEEPA tariffs in a case brought by educational toy maker Learning Resources. | Ruling completed; importers began receiving refunds through the CAPE portal by May 2026 |
| In May 2026, Ravensburger detailed a ten-panel Pokémon puzzle, with the first three panels planned for fall 2026. | Phased launch planned; the last five panels are scheduled for 2027 |
| In July 2026, the Toy Association asked the U.S. Trade Representative to exempt toy headings, including HTS 9503.00.00, from new Section 301 duties. | Request filed on July 6, 2026; the outcome for puzzles is not confirmed in public sources |
Die cutting, laser cutting and print quality decide cost
- Steel-rule die cutting stamps hundreds of pieces from laminated paperboard in one press stroke, so mass-market paperboard puzzles stay inexpensive.
- Laser cutting shapes plywood pieces and figural whimsies one puzzle at a time, which is why wooden sets sell for several times the price of paperboard boxes.
- High-resolution offset and digital printing reproduces licensed art and photographs sharply enough for adults to sort pieces by detail.
- Competition-sized sorting systems such as Ravensburger's redesigned Sort & Go trays stack six trays to hold a 3,000-piece puzzle, tying hobbyists to one brand's accessories.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Two domestic leaders face German and Canadian brands
Competition splits between two domestic leaders, imported global brands, art-led publishers and small wooden specialists. Buffalo Games, which owns Ceaco, combines the largest and second-largest U.S. producers and sells licensed and art puzzles through mass merchants. Mason Wells, a Milwaukee private equity firm, acquired Buffalo Games from its founders in September 2018. The group then merged with EastPoint Sports in March 2023, widening its games range beyond puzzles. Ravensburger competes mainly through Disney, Pokémon and preschool licenses. Spin Master owns Melissa & Doug, a leader in wooden children's puzzles, and uses its global toy distribution to place them. Store brands at mass merchants compete on price below these labels. Springbok and White Mountain sell American-made puzzles, while Galison, New York Puzzle Company, MasterPieces and Cobble Hill compete on art and themes. Liberty Puzzles leads the laser-cut wooden tier among domestic makers.
How concentrated is U.S. puzzle supply and where do margins sit?
Supply is moderately concentrated at the mass tier and fragmented at the premium end. At the mass tier, the Buffalo Games group and Ravensburger hold most licensed shelf space, the first through domestic cutting and the second through imported licensed ranges. Below them sit art-led publishers such as Galison and New York Puzzle Company and many small laser-cut wooden makers. Entry barriers are die-cutting capacity, art licenses and retail listings rather than technology. Margins sit with licensed and premium wooden lines, while commodity paperboard boxes sold to mass retailers earn the least.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Buffalo Games (Ceaco) | Domestic manufacturer | Licensed and art jigsaw puzzles cut in Buffalo, New York, plus Ceaco lines |
| Ravensburger AG (Ravensburger North America) | Global brand owner | Adult, Disney, Pokémon and preschool jigsaw puzzles sold across U.S. retail |
| Spin Master (Melissa & Doug) | Toy group | Wooden, chunky and floor puzzles for preschool children |
| Springbok Puzzles | Domestic manufacturer | American-made 500- and 1,000-piece puzzles for adults |
| White Mountain Puzzles | Domestic manufacturer | Nostalgia and Americana puzzles made in Massachusetts and Indiana |
| Galison Publishing (Galison, Mudpuppy) | Art publisher | Art, foil and shaped puzzles plus Mudpuppy children's puzzles |
| New York Puzzle Company | Art publisher | Art and illustration puzzles at premium list prices near USD 29 |
| MasterPieces Puzzle Company | Brand owner | Licensed and themed jigsaw puzzles for mass and specialty retailers |
| Cobble Hill Puzzle Co. | Brand owner | Art and nature jigsaw puzzles sold through its own U.S. online store |
| Liberty Puzzles | Wooden specialist | Laser-cut wooden puzzles made in two Boulder, Colorado, factories |
Value now depends on adults, licenses and sourcing
Credence Research's view is that the U.S. jigsaw puzzle market has moved from a pandemic spike to a steadier adult hobby, where value comes from licensed art, premium formats and price rather than more boxes. Adult buyers, competitive events and collector series support spending, while a shrinking child population and volatile duties on Chinese imports add risk. Brands with domestic cutting capacity and strong licenses are best placed through 2035. The main evidence gaps are unit sales by channel and custom photo puzzle volumes, which no public source tracks, so those splits rest on Credence Research estimates.
Unit counts, list prices and statistics anchor values
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model; this edition revises the earlier estimate upward after a bottom-up check of producer output, unit volumes and list prices, and lowers the growth rate. Regional and segment splits are Credence Research estimates based on Census population and age data, plant locations, retailer listings and company disclosures. Sources include the Census Bureau, Bureau of Labor Statistics data, trade rulings, company stores and releases, industry associations and trade press. No interviews or surveys were conducted for this edition of the report.
Premium adult lines and sourcing shifts carry 2035
Growth in the U.S. jigsaw puzzle market to 2035 rests on three conditions. Adult hobby demand must hold after the strong 2025 and 2026 toy seasons, supported by competitive events, collector series and senior buyers. Brands must manage duty risk on Chinese imports, either through domestic cutting or diversified sourcing. Licensed art must keep puzzles visible at mass merchants during the holiday season, when most gift buying happens. If these hold, value grows through price and premium mix, and online retailers grow fastest at 6.3% a year.
Tariffs and adult demand set the range of outcomes
The range of outcomes depends on whether duty rates on Chinese goods stay near their late-2026 level and whether adult hobby demand holds after the strong first half of 2026. The base case assumes stable duties, steady price gains and continued growth in competitive and collector formats. The downside assumes higher duties and a weak consumer, while the upside assumes faster domestic cutting capacity and broader senior and institutional demand.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 3.6% | USD 917.2 million | Duties rise again, consumers trade down and licensed toy demand cools after 2026 |
| Base | 5.10% | USD 1.04 billion | Stable duties, steady price gains and continued adult and collector demand nationwide |
| Upside | 6.6% | USD 1.19 billion | Domestic cutting grows and senior living and competitive buyers widen the adult base |
Frequently Asked Questions
How big is the jigsaw puzzle market in the United States?
Which companies make jigsaw puzzles in the USA?
What are the most popular jigsaw puzzle brands?
How much does a 1,000-piece jigsaw puzzle cost?
What makes puzzles more expensive to produce and sell?
Are jigsaw puzzles still popular in the United States?
Which region buys the most puzzles in the United States?
Which puzzle segment grows fastest?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Paper
- 1.2.2 Wood
- 1.2.3 Plastic
- 1.3 By Application
- 1.3.1 Adults
- 1.3.2 Children
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 634.8 million → 2035: USD 1.04 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 US Jigsaw Puzzle Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 US Jigsaw Puzzle Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 US Jigsaw Puzzle Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 US Jigsaw Puzzle Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 US Jigsaw Puzzle Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 US Jigsaw Puzzle Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 US Jigsaw Puzzle Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 US Jigsaw Puzzle Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 634.8 million → 2035: USD 1.04 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 US Jigsaw Puzzle Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Paper
- 12.3.7.2 Wood
- 12.3.7.3 Plastic
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Adults
- 12.4.7.2 Children
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 US Jigsaw Puzzle End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 US Jigsaw Puzzle Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 US Jigsaw Puzzle Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 US Jigsaw Puzzle Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Buffalo Games (Ceaco)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ravensburger AG (Ravensburger North America)
- 18.4 Spin Master (Melissa & Doug)
- 18.5 Springbok Puzzles
- 18.6 White Mountain Puzzles
- 18.7 Galison Publishing (Galison, Mudpuppy)
- 18.8 New York Puzzle Company
- 18.9 MasterPieces Puzzle Company
- 18.10 Cobble Hill Puzzle Co.
- 18.11 Liberty Puzzles
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

