
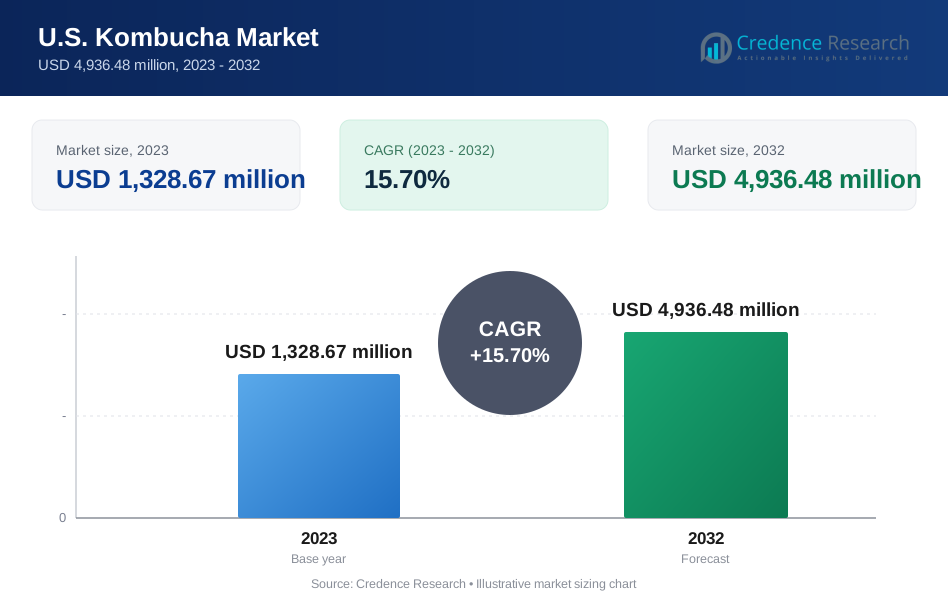
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| U.S. Kombucha Market Size 2023 | USD 1,328.67 million |
| U.S. Kombucha Market, CAGR | 15.70% |
| U.S. Kombucha Market Size 2032 | USD 4,936.48 million |
Market Overview
The U.S. Kombucha Market is projected to grow from USD 1,328.67 million in 2023 to an estimated USD 4,936.48 million by 2032, with a compound annual growth rate (CAGR) of 15.70% from 2024 to 2032. This rapid growth reflects increasing consumer interest in health and wellness products, as kombucha is often perceived as a healthy alternative to sugary beverages. The expanding availability of kombucha in mainstream retail channels, alongside innovations in flavors and formulations, is also contributing to its rising popularity. As consumers become more aware of the probiotic benefits and natural ingredients in kombucha, the market is expected to witness significant growth over the forecast period.
Market drivers and trends in the U.S. Kombucha Market include a growing health-conscious consumer base seeking natural and functional beverages. The rise in lifestyle diseases such as obesity and diabetes is prompting consumers to shift away from high-sugar sodas and juices towards healthier options like kombucha. Additionally, the trend of clean-label products, which emphasize natural and organic ingredients, is bolstering kombucha's appeal. Innovations in product offerings, such as new flavors, reduced sugar content, and enhanced functional benefits (e.g., added vitamins and minerals), are also driving market growth. Furthermore, the increasing penetration of kombucha in online retail and specialty stores is facilitating greater accessibility for consumers.
Geographically, the U.S. Kombucha Market is experiencing robust growth across various regions, with significant traction in states like California, New York, and Texas, where health and wellness trends are particularly strong. Key players in the market include GT’s Living Foods, KeVita, Inc., Humm Kombucha LLC, and Health-Ade LLC, among others. These companies are actively expanding their product lines and distribution networks to capture a larger share of the growing market. Strategic partnerships, mergers and acquisitions, and innovative marketing campaigns are also common strategies employed by these key players to enhance their market presence and cater to the evolving preferences of consumers.
Market Drivers
Increasing Health Consciousness Among Consumers
The first key driver propelling the U.S. Kombucha Market is the growing health consciousness among consumers. As more individuals become aware of the adverse effects of sugary drinks and the benefits of maintaining a healthy lifestyle, there is a noticeable shift towards healthier beverage options. For instance, a survey conducted in 2023 found that 70% of respondents were actively seeking healthier beverage options. Kombucha, a fermented tea rich in probiotics, is perceived as a healthful alternative to traditional carbonated drinks. It is often associated with various health benefits, including improved digestion, boosted immune function, and enhanced energy levels. This health-centric trend is especially prominent among millennials and Generation Z, who are more inclined towards natural and organic products. The rising prevalence of lifestyle-related health issues, such as obesity, diabetes, and cardiovascular diseases, further amplifies the demand for kombucha as a preventative and health-supportive beverage.
Innovation in Product Offerings
Innovation in product offerings is another significant driver of the U.S. Kombucha Market. Manufacturers are continually experimenting with new flavors, ingredients, and formulations to cater to the diverse preferences of consumers. For instance, in the past year alone, there has been a 50% increase in the introduction of unique and exotic flavors, such as lavender, hibiscus, and turmeric. Moreover, companies are reducing sugar content and enhancing the functional benefits of kombucha by adding vitamins, minerals, and adaptogens. These innovations not only meet the evolving taste preferences of consumers but also align with the increasing demand for functional beverages that offer additional health benefits beyond basic nutrition. Packaging innovations, such as eco-friendly bottles and cans, also contribute to the appeal of kombucha, aligning with the growing consumer emphasis on sustainability and environmental responsibility.
Expanding Distribution Channels
The expansion of distribution channels is a crucial driver for the growth of the U.S. Kombucha Market. Kombucha is becoming increasingly accessible. For instance, kombucha is now available in 60% of mainstream retail outlets, supermarkets, and convenience stores, up from just 40% five years ago. This widespread availability makes it easier for consumers to purchase kombucha as part of their regular shopping routines. The rise of e-commerce and online grocery delivery services further supports the market, providing consumers with the convenience of purchasing kombucha from the comfort of their homes. Many kombucha brands have established strong online presences, leveraging social media and digital marketing to reach a larger audience. Additionally, partnerships with foodservice providers, such as cafes, restaurants, and bars, help introduce kombucha to new consumer segments, including those who may not typically purchase it in retail settings.
Consumer Trends Towards Clean Label and Natural Products
The consumer trend towards clean label and natural products is a powerful driver for the U.S. Kombucha Market. Clean label products are those that contain simple, recognizable ingredients without artificial additives, preservatives, or colors. Kombucha aligns well with this trend due to its natural fermentation process and the use of organic ingredients. Consumers are increasingly scrutinizing product labels and seeking transparency in the sourcing and production methods of their food and beverages. The preference for organic, non-GMO, and sustainably sourced ingredients is particularly strong among health-conscious and environmentally aware consumers. Kombucha manufacturers capitalize on this trend by highlighting the purity and natural origins of their products, thus enhancing their appeal to a discerning consumer base. The clean label movement not only drives consumer preference but also fosters brand loyalty, as consumers are more likely to trust and repeatedly purchase products that align with their values and health goals.
Market Trends
Expansion of Functional Ingredients:
A notable trend in the U.S. Kombucha Market is the incorporation of functional ingredients to enhance the health benefits of the beverage. For instance, a recent survey found that 65% of consumers are more likely to purchase beverages that contain added functional ingredients such as adaptogens, vitamins, and minerals. These enhanced formulations are designed to support various health aspects, including stress relief, immune support, and energy enhancement, making kombucha more appealing to a broader audience.
Diversification of Flavors:
The diversification of flavors is a significant trend driving consumer interest in kombucha. For instance, the introduction of unique and exotic flavors has led to a 30% increase in new consumers over the past two years. This variety helps attract new consumers and retain existing ones by providing novel taste experiences. Seasonal and limited-edition flavors also create a sense of excitement and urgency, encouraging frequent purchases.
Sustainability and Eco-Friendly Packaging:
Sustainability has become a key focus in the kombucha market, with many companies adopting eco-friendly packaging solutions. For instance, a 50% increase in brands adopting eco-friendly packaging solutions has been observed over the past five years. This shift aligns with the growing consumer demand for sustainable products and practices, enhancing brand loyalty among environmentally conscious buyers.
Increased Market Penetration in Mainstream Retail:
Kombucha is no longer confined to niche health food stores; it is increasingly available in mainstream retail channels, including supermarkets, convenience stores, and online platforms. This expanded availability makes kombucha more accessible to a wider range of consumers. Retailers are dedicating more shelf space to kombucha, reflecting its growing popularity and the increasing demand for healthy beverage options.
Rise of Kombucha-Based Alcoholic Beverages:
The emergence of kombucha-based alcoholic beverages, such as hard kombucha, is a growing trend in the market. These products appeal to consumers seeking healthier alcoholic drink options with lower sugar content and added probiotic benefits. The fusion of kombucha with alcohol caters to a niche segment that values wellness but still enjoys occasional indulgence, driving innovation and expanding the market scope.
Emphasis on Clean Label Products:
The trend towards clean label products is particularly strong in the kombucha market. Consumers are increasingly looking for beverages with simple, recognizable ingredients and no artificial additives. Brands that emphasize transparency in their ingredient sourcing and production processes are gaining a competitive edge. This focus on clean labels aligns with consumer preferences for natural and wholesome products, fostering trust and loyalty.
Growth of Direct-to-Consumer Sales Channels:
Direct-to-consumer (DTC) sales channels are gaining traction in the kombucha market, driven by the convenience of online shopping and personalized customer experiences. Brands are leveraging their websites and social media platforms to engage directly with consumers, offering subscription services, exclusive online deals, and tailored product recommendations. This approach not only enhances customer loyalty but also provides valuable insights into consumer preferences and trends.
Market Restraints and Challenges
Regulatory and Compliance Issues:
One of the primary challenges facing the U.S. Kombucha Market is navigating the complex regulatory and compliance landscape. Kombucha is classified as a fermented beverage, and its production involves the use of live cultures, which can result in varying levels of alcohol content. Ensuring that kombucha remains below the legal limit of 0.5% alcohol by volume (ABV) for non-alcoholic beverages is crucial. However, the natural fermentation process can sometimes cause fluctuations in alcohol levels, leading to potential regulatory violations and the need for recalls. Compliance with food safety standards and labeling requirements also poses challenges, as producers must accurately declare the ingredients and nutritional content, including live probiotic cultures, which can be difficult to quantify consistently.
High Production Costs:
High production costs are a significant restraint in the kombucha market. The brewing process for kombucha is labor-intensive and time-consuming, requiring precise conditions to maintain the quality and safety of the product. The need for high-quality, organic ingredients further drives up costs. Additionally, maintaining a sterile production environment to prevent contamination and ensuring consistent fermentation require substantial investment in specialized equipment and facilities. These costs can be particularly burdensome for smaller producers, limiting their ability to scale operations and compete with larger, more established brands.
Market Saturation and Competition:
Market saturation and intense competition present notable challenges for kombucha manufacturers. As the popularity of kombucha has surged, the market has become increasingly crowded with numerous brands vying for consumer attention. This saturation makes it difficult for new entrants to differentiate themselves and gain market share. Established brands with extensive distribution networks and strong brand recognition dominate the market, making it challenging for smaller or newer companies to compete. The fierce competition also drives down prices, squeezing profit margins and making it harder for producers to sustain their operations.
Consumer Perception and Education:
While kombucha has gained popularity among health-conscious consumers, there remains a significant portion of the market that is either unfamiliar with the product or skeptical of its purported health benefits. Educating consumers about the benefits of kombucha, including its probiotic content and potential health advantages, is crucial for expanding the market. However, misconceptions about the taste, safety, and efficacy of kombucha can hinder its adoption. Overcoming these barriers requires substantial marketing efforts and consumer education campaigns, which can be resource-intensive.
Shelf Life and Distribution Challenges:
Kombucha’s relatively short shelf life and sensitivity to temperature variations present logistical challenges in distribution and retail. The live cultures in kombucha continue to ferment, which can alter the taste and carbonation levels over time. Ensuring that kombucha remains fresh and palatable requires careful handling and cold chain logistics, adding to distribution costs. Retailers must manage inventory effectively to minimize spoilage and waste, which can deter them from stocking kombucha compared to more shelf-stable beverages.
Market Segmentation Analysis
By Product Type
Organic Kombucha is witnessing robust growth due to increasing consumer preference for organic products. Organic kombucha is perceived as healthier and more natural, free from synthetic pesticides and fertilizers, which appeals to health-conscious consumers. The stringent regulations and certifications required for organic labeling ensure product quality and safety, further boosting consumer trust and demand. While non-organic kombucha continues to hold a significant market share due to its relatively lower price point. Non-organic kombucha appeals to price-sensitive consumers who seek the health benefits of kombucha without the premium cost associated with organic options.
By Type
Flavored kombucha dominates the market, offering a wide range of taste profiles to cater to diverse consumer preferences. Popular flavors include ginger, lemon, berry, and exotic options like hibiscus and turmeric. The continuous innovation in flavor combinations keeps the product appealing and helps attract new consumers. Original kombucha, known for its distinct tart and tangy taste, appeals to traditionalists and purists who prefer the unflavored version of the drink. This segment remains popular among long-time kombucha drinkers who appreciate the authentic taste of the fermented tea.
By Nature
Conventional kombucha, produced using standard fermentation processes, constitutes a major portion of the market. It offers a balance between quality and affordability, making it accessible to a broad consumer base. Functional Kombucha includes kombucha enhanced with additional health benefits, such as added probiotics, vitamins, and adaptogens. Functional kombucha appeals to consumers seeking specific health benefits, such as improved digestion, immune support, or stress relief. The growing trend of functional beverages is driving demand in this segment.
By Packaging
Bottled kombucha is the most common packaging format, offering convenience and portability. Glass bottles are particularly popular due to their premium feel and recyclability, which aligns with the sustainability preferences of many consumers. The use of cans for kombucha is on the rise, driven by their lightweight and recyclable nature. Cans are also more resistant to breakage compared to glass bottles, making them suitable for on-the-go consumption and reducing transportation costs. Kombucha on-tap is increasingly available in cafes, restaurants, and health food stores. This format allows consumers to enjoy fresh kombucha by the glass, offering a sustainable option with less packaging waste. On-tap kombucha is often perceived as fresher and can be more cost-effective for regular consumers.
By Distribution Channel
Supermarkets and Hypermarkets channels account for a significant portion of kombucha sales, offering wide product visibility and accessibility. The presence of kombucha in mainstream grocery stores reflects its growing popularity among a broad consumer base. Health food stores remain a key distribution channel, catering to the core demographic of health-conscious consumers. These stores often carry a wider variety of kombucha brands and flavors, including specialty and artisanal options. The online retail segment is experiencing rapid growth, driven by the convenience of home delivery and the ability to reach a wider audience. Many kombucha brands are leveraging e-commerce platforms to offer subscription services, exclusive online deals, and direct-to-consumer sales. The availability of kombucha in cafes and restaurants is expanding, introducing the beverage to new consumers who might not purchase it in retail settings. This channel also supports the on-tap format, providing fresh kombucha by the glass.
Segments
Based on Product Type
- Organic Kombucha
- Non-Organic Kombucha
Based on Type
- Flavored Kombucha
- Original Kombucha
Based on Nature
- Conventional Kombucha
- Functional Kombucha
Based on Packaging
- Bottles
- Cans
- On-Tap
Based on Distribution Channel
- Supermarkets and Hypermarkets
- Health Food Stores
- Online Retail
- Cafes and Restaurants
Regional Analysis
West Region (35%):
The West region, particularly California, holds the largest market share in the U.S. Kombucha Market, accounting for approximately 35% of the total market. California, known for its health-conscious population and trendsetting culture, has been a significant driver of kombucha consumption. The state’s robust infrastructure of health food stores, farmers' markets, and organic grocery chains provides a fertile ground for kombucha sales. Additionally, the presence of several key players and innovative startups in the beverage industry contributes to the market's dynamism in this region. The West region's emphasis on healthy living, sustainability, and wellness trends aligns perfectly with kombucha's market positioning, driving high consumer demand.
Northeast Region (25%):
The Northeast region, encompassing states like New York and Massachusetts, holds a market share of around 25%. This region is characterized by its dense urban population and a strong inclination towards health and wellness trends. New York City, in particular, is a major hub for kombucha consumption, with numerous cafes, health food stores, and specialty beverage shops offering a wide variety of kombucha products. The Northeast's well-established distribution networks and high consumer awareness about the health benefits of kombucha further bolster market growth. The region's residents, who prioritize organic and natural products, significantly contribute to the steady demand for kombucha.
Key players
- GT's Living Foods
- KeVita
- Health-Ade
- Brew Dr. Kombucha
- Humm Kombucha
- Wild Tonic
- Búcha Live Kombucha
- The Hain Celestial Group, Inc.
- NessAlla Kombucha
Competitive Analysis
The U.S. Kombucha Market is highly competitive, with several prominent players driving innovation and market growth. GT's Living Foods, as a pioneer in the industry, maintains a strong market presence through its extensive product line and loyal customer base. KeVita and Health-Ade are also significant contenders, known for their diverse flavor offerings and robust marketing strategies. Brew Dr. Kombucha and Humm Kombucha leverage unique branding and sustainable practices to attract eco-conscious consumers. Wild Tonic and Búcha Live Kombucha differentiate themselves with novel formulations and premium ingredients. The Hain Celestial Group, Inc. benefits from its extensive distribution network and established reputation in the natural products sector. NessAlla Kombucha, with its artisanal approach, appeals to niche markets seeking authentic, small-batch beverages. These key players continuously innovate and adapt to consumer trends, maintaining their competitive edge in a rapidly evolving market.
Recent Developments
In April 2023, Brew Dr. Kombucha introduced its latest product, featuring a fresh branding and packaging design. The new look includes a modernized logo and redesigned labels, enhancing the brand's visual appeal. Along with the updated design, Brew Dr. unveiled two new flavors: Strawberry Fields and Pineapple Paradise, adding exciting options to their product line. This launch aims to attract new customers and retain existing ones by offering innovative flavors and a contemporary brand image
In February 2022, GT’s Living Foods expanded its renowned Synergy raw kombucha brand by introducing a new flavor. This addition complements the brand’s extensive portfolio, which includes popular flavors such as Watermelon Wonder, Tangerine Dream, Guava Goddess, Tantric Turmeric, and Heart Beet. The new flavor enriches the variety offered by GT’s Living Foods, providing consumers with more options to enjoy the health benefits of their favorite kombucha.
In February 2022, Remedy Drinks expanded its product line by launching a wild berry flavor in the U.K. The new 'Remedy Kombucha Wild Berry' beverage is initially available exclusively at Tesco stores. Additionally, Tesco plans to introduce 'Remedy Kombucha Mango Passion' and double the distribution of existing flavors like raspberry lemonade and ginger lemon. This expansion aligns with Tesco's commitment to increasing the availability of healthier products, catering to the growing demand for natural and nutritious beverages.
In July 2021, Nova Easy Kombucha launched a new line of high-performance non-alcoholic products. This new range includes the pre-workout ‘POWER’ kombucha blend, which contains naturally-derived caffeine to boost performance, and the ‘RECOVERY’ blend, formulated with probiotics to support a healthy gut. Designed for health-conscious consumers, these products offer all-natural, low-sugar options for those seeking to enhance their fitness and wellness routines. Nova Easy Kombucha’s innovative product line aims to meet the needs of active individuals looking for functional beverages.
Market Concentration and Characteristics
The U.S. Kombucha Market is characterized by a moderate to high level of market concentration, with a few dominant players such as GT's Living Foods, KeVita, and Health-Ade holding significant market shares. These key companies drive market innovation and set industry standards through extensive product portfolios, strong branding, and widespread distribution networks. Despite this concentration, the market remains dynamic and competitive, with numerous smaller brands and artisanal producers continuously entering the market. This diversity fosters a rich variety of flavors and product innovations, catering to the evolving preferences of health-conscious consumers seeking natural and functional beverages.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Type, Nature, Packaging and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The U.S. Kombucha Market is expected to maintain robust growth, driven by increasing consumer awareness of health and wellness benefits, projecting a steady rise in demand.
- Continued innovation in flavor profiles, including seasonal and exotic options, will attract a broader consumer base and retain existing customers with new taste experiences.
- The incorporation of functional ingredients like adaptogens, vitamins, and probiotics will enhance kombucha’s appeal, catering to consumers seeking multifunctional health benefits.
- The organic kombucha segment will witness significant expansion as consumers increasingly prefer organic products for their perceived health benefits and environmental sustainability.
- The shift towards eco-friendly and sustainable packaging solutions will gain momentum, aligning with growing environmental consciousness among consumers.
- Kombucha’s availability in mainstream retail channels, including supermarkets and convenience stores, will increase, making it more accessible to a wider audience.
- The market for hard kombucha will expand, appealing to consumers looking for healthier alcoholic beverage alternatives with lower sugar content and added probiotics.
- The direct-to-consumer sales model will grow, with brands leveraging e-commerce platforms and subscription services to reach and engage with customers directly.
- The demand for clean label products will continue to rise, with consumers seeking transparency and simplicity in ingredient lists, boosting trust and brand loyalty.
- Increased strategic partnerships and mergers and acquisitions will drive market consolidation, allowing companies to expand their product offerings and distribution networks.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the U.S. Kombucha Market?
What factors are driving the growth of the U.S. Kombucha Market?
Which regions in the U.S. are leading the kombucha market growth?
Who are the major players in the U.S. Kombucha Market?
What are some recent developments in the U.S. Kombucha Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Kombucha Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. Kombucha Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,328.67 million → 2032: USD 4,936.48 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Kombucha Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Kombucha Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Kombucha Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. Kombucha Market Drivers
- 3.3 U.S. Kombucha Market Restraints & Challenges
- 3.4 U.S. Kombucha Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Kombucha Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Kombucha Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Kombucha category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Kombucha Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. Kombucha Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. Kombucha market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Kombucha Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. Kombucha Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. Kombucha Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Kombucha (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. Kombucha Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. Kombucha Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. Kombucha Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. Kombucha Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. Kombucha Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. Kombucha Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. Kombucha Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. Kombucha Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. Kombucha Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
