
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Parking Management Software Market Size 2024 | USD 1487.11 million |
| U.S. Parking Management Software Market, CAGR | 7.95% |
| U.S. Parking Management Software Market Size 2032 | USD 2743.16 million |
Market Overview:
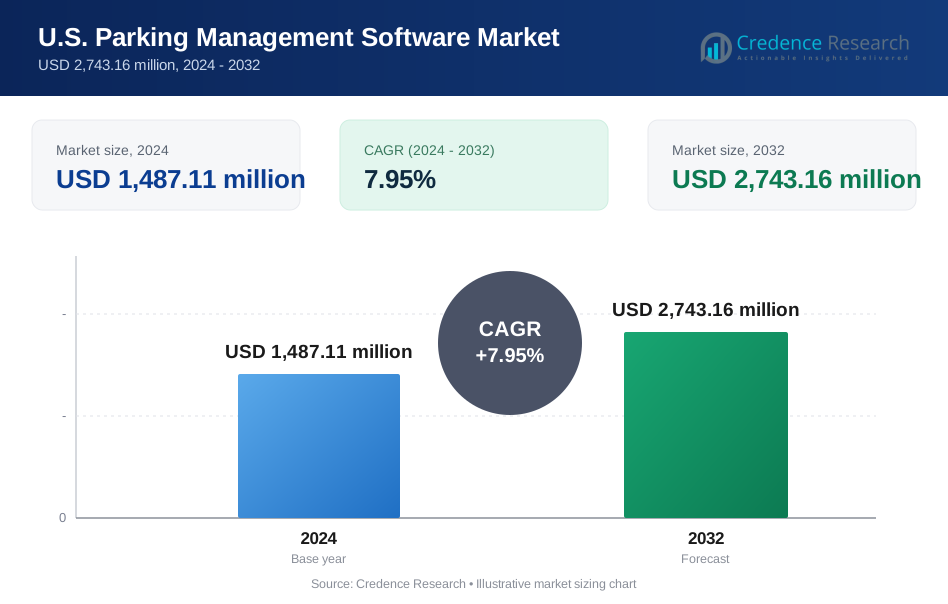
The U.S. Parking Management Software Market is projected to grow from USD 1487.11 million in 2024 to an estimated USD 2743.16 million by 2032, with a compound annual growth rate (CAGR) of 7.95% from 2024 to 2032.
The growth of the U.S. parking management software market is primarily driven by several key factors. Firstly, the continuous rise in urbanization and vehicle ownership has intensified the demand for efficient parking solutions. As cities expand and populations grow, the need for advanced systems that can alleviate traffic congestion and optimize limited parking spaces becomes crucial. Secondly, technological advancements are transforming the parking landscape. The integration of the Internet of Things (IoT), artificial intelligence (AI), and cloud-based solutions has enhanced the efficiency of parking systems by enabling real-time data collection, automated payment processes, and seamless user experiences. Lastly, increasing environmental concerns are contributing to market growth. Efficient parking management systems play a vital role in reducing greenhouse gas emissions by minimizing the time vehicles spend idling in search of parking, thus promoting sustainable urban mobility.
The adoption of parking management software in the United States shows significant regional variations. North America, particularly the U.S., dominates the market with a notable share, driven by the high rate of vehicle ownership and the pressing need to mitigate traffic congestion. Major urban centers such as New York City, Los Angeles, and Chicago have been early adopters of advanced parking technologies. These densely populated cities face challenges related to limited parking availability, which has accelerated the adoption of smart parking solutions. Furthermore, regional governments and municipalities are increasingly investing in digital infrastructure to modernize parking systems, ensuring smoother traffic flow and better utilization of urban spaces. This regional push towards innovation and smart city initiatives continues to drive the growth of the parking management software market across the country.
Market Insights:
- The U.S. Parking Management Software Market is expected to witness significant growth, expanding from 2024 to 2032 with a notable compound annual growth rate (CAGR) of 7.95%.
- Rising urbanization and increased vehicle ownership are major growth drivers, intensifying the demand for advanced parking management systems to reduce congestion and optimize limited parking spaces.
- Technological advancements, particularly the integration of IoT, AI, and cloud-based solutions, are enhancing the efficiency of parking operations by enabling real-time data collection and automated payment processing.
- Growing environmental concerns are encouraging the adoption of efficient parking systems that minimize vehicle idling and emissions, contributing to sustainable urban mobility.
- Regional variations exist, with major urban centers like New York City, Los Angeles, and Chicago leading the adoption of smart parking solutions due to high population densities and limited parking availability.
- Government investments in digital infrastructure and smart city initiatives are accelerating the modernization of parking systems, improving traffic flow and urban space utilization.
- Key challenges include high implementation costs, system integration complexities, and data security concerns, which may affect the pace of market growth and technology adoption.
Market Drivers:
Urbanization and Increased Vehicle Ownership
The rapid urbanization in the United States has led to a significant increase in vehicle ownership, intensifying the demand for efficient parking solutions. For instance, cities are implementing strategies to redistribute parking demand by extending paid parking zones and encouraging off-street facilities, which helps reduce congestion and optimize urban space usage. As urban areas become more densely populated, the availability of parking spaces diminishes, leading to congestion and inefficiencies. This scenario necessitates advanced parking management software that can optimize space utilization, streamline parking operations, and enhance the overall urban mobility experience. The growing number of vehicles in urban centers underscores the critical need for sophisticated parking management systems to address these challenges effectively.
Technological Advancements in Parking Solutions
The integration of cutting-edge technologies such as the Internet of Things (IoT), Artificial Intelligence (AI), and cloud computing has revolutionized parking management systems. IoT-enabled sensors provide real-time data on parking space availability, reducing the time drivers spend searching for spots and thereby decreasing traffic congestion. For instance, in the San Francisco Bay area, CityLift has implemented a fully automated parking system, the Hive Parking Structure, which maximizes space efficiency by turning seven standard parking spaces into 39. AI-driven analytics facilitate predictive modeling of parking demand, allowing for dynamic pricing and efficient resource allocation. Cloud-based platforms offer centralized control and scalability, enabling seamless updates and maintenance. These technological advancements not only improve operational efficiency but also enhance user satisfaction by providing convenient and reliable parking solutions.
Environmental Sustainability Initiatives
There is a growing emphasis on environmental sustainability within urban planning and development. Efficient parking management systems contribute to this goal by reducing vehicle idling times and minimizing emissions associated with searching for parking. By optimizing traffic flow and decreasing congestion, these systems play a pivotal role in lowering urban carbon footprints. For instance, the City of Vancouver mandates that 100% of parking spaces in multi-family dwellings be EV-ready, while commercial buildings must have 10% of spaces equipped for EV charging. These requirements reflect a growing commitment to supporting the transition to cleaner transportation. Cities adopting smart parking solutions are better positioned to meet environmental regulations and promote sustainable living practices, aligning with global efforts to combat climate change.
Government Support and Smart City Initiatives
Government initiatives aimed at developing smart cities have significantly propelled the adoption of advanced parking management solutions. Investments in intelligent transportation systems and infrastructure modernization projects often include the deployment of smart parking technologies. These initiatives not only improve urban mobility but also enhance economic productivity by reducing time wasted in traffic and parking searches. For example, cities are implementing policies to regulate cars more effectively, including emission-based regulations to encourage cleaner vehicles. The alignment of parking management advancements with governmental policies and funding opportunities has created a conducive environment for the proliferation of these technologies across various urban centers.
Market Trends:
Integration of Advanced Technologies
The U.S. parking management software market is witnessing a significant trend towards the integration of advanced technologies. Innovations such as sensor-based systems and Internet of Things (IoT) integration are being increasingly adopted to provide real-time tracking of parking space availability, thereby reducing search times and alleviating traffic congestion. For instance, sensors are installed at the entrance and exit points of car parks to track the number of vehicles, providing accurate data on occupied and vacant spots. Additionally, advancements in cloud-based platforms and artificial intelligence (AI) technologies are enabling dynamic pricing and predictive analytics, optimizing parking space usage and enhancing operational efficiency.
Emergence of Radar Sensor Technology
Radar sensors are emerging as a rapidly growing segment within the parking management market due to their ability to provide reliable, accurate, and real-time data for parking management systems. These sensors utilize electromagnetic waves to detect objects within their range, making them highly effective for monitoring parking spaces and vehicle movements under various environmental conditions, including poor visibility or harsh weather. For example, Siemens has developed a radar sensor system that can scan larger areas, detect multiple cars, and even identify obstructive parking, helping to manage traffic flow more efficiently. The adoption of radar sensor technology signifies a shift towards more precise and dependable parking management solutions.
Adoption of Cloud-Based Solutions
There is a notable shift towards cloud-based platforms in the parking management software market, offering scalability, flexibility, and accessibility. Cloud-based solutions facilitate seamless updates and maintenance, reduce the need for on-premise infrastructure, and enable real-time data access from any location. Easy Park's cloud-based smart parking system, for instance, enhances operational efficiency by streamlining parking space allocation and reducing congestion. This transition allows for more efficient management of parking resources and enhances the ability to respond swiftly to changing demands, thereby improving overall operational efficiency.
Focus on Interoperability and Open Data Standards
A growing emphasis on interoperability and open data standards is shaping the parking management ecosystem. Developing solutions that integrate seamlessly with other transportation systems, such as public transit networks and ride-sharing platforms, is becoming increasingly important. Open data standards facilitate data sharing among different stakeholders, enabling better coordination and decision-making to address urban mobility challenges effectively. For example, the proposed ParkingJSON standard aims to provide a common format for parking data, supporting interoperability across various parking infrastructures and enhancing data integrity. This trend towards interoperability reflects a holistic approach to urban transportation planning and management.
Market Challenges Analysis:
System Integration Challenges
The U.S. parking management software market faces significant challenges in integrating diverse hardware and software platforms. The variety of sensors, cameras, payment gateways, and other technologies involved often lack standardization, leading to interoperability issues. This diversity complicates the seamless integration of new systems with existing infrastructure, hindering scalability and the efficient deployment of comprehensive parking solutions.
High Implementation and Maintenance Costs
Implementing advanced parking management systems requires substantial financial investment. The costs associated with deploying sophisticated technologies, coupled with ongoing maintenance expenses, can be prohibitive, especially for smaller municipalities or private operators with limited budgets. This financial barrier often delays the adoption of modern parking solutions, affecting the overall growth of the market.
Data Security and Privacy Concerns
The increasing reliance on digital platforms for parking management raises significant data security and privacy issues. Systems that collect and store user information are vulnerable to cyber threats, making the protection of sensitive data a critical concern. Ensuring robust cybersecurity measures is essential to maintain user trust and comply with regulatory requirements, presenting an ongoing challenge for service providers.
Resistance to Technological Adoption
Some stakeholders exhibit reluctance to adopt new parking management technologies due to concerns about system reliability and the complexity of transitioning from traditional methods. This resistance can stem from a lack of technical expertise, fear of operational disruptions, or skepticism about the return on investment. Overcoming this inertia is crucial for the widespread implementation of advanced parking solutions.
Market Opportunities:
The U.S. parking management software market is anticipated to experience significant growth, driven by the rising adoption of advanced technologies and the increasing need for efficient urban mobility solutions. This growth presents considerable opportunities for stakeholders to develop and implement innovative parking management solutions that meet the evolving demands of modern urban environments. The market is also shaped by changing consumer preferences, with users seeking more convenient, automated, and user-friendly parking experiences. Furthermore, government initiatives focused on enhancing urban infrastructure and reducing congestion are expected to further propel market development and encourage the adoption of smart parking solutions.
The integration of advanced technologies, including the Internet of Things (IoT), Artificial Intelligence (AI), and cloud computing, is transforming the parking landscape. These technologies enable real-time data collection, predictive analytics, and automated processes, enhancing both operational efficiency and user experience. Additionally, the growing focus on environmental sustainability and the reduction of greenhouse gas emissions underscores the importance of efficient parking management systems in minimizing vehicle idling and alleviating traffic congestion. As cities continue to expand and prioritize the development of smart infrastructure, the demand for sophisticated parking management software is expected to grow, creating opportunities for companies to innovate and expand their market presence.
Market Segmentation Analysis:
The U.S. Parking Management Software Market is segmented into various categories, each contributing to the market's overall growth and development.
By Solution Segment, the market is driven by the increasing demand for efficient and secure parking systems. Access Control solutions are vital for ensuring authorized vehicle entry and enhancing security measures. Revenue Management solutions help optimize pricing and maximize profitability for parking operators. Parking Security and Surveillance systems are crucial for ensuring the safety of vehicles and deterring theft or vandalism. Parking Reservation Management solutions offer convenient options for users to book spaces in advance, enhancing customer satisfaction. Meanwhile, Analytics Solutions play a key role in providing data-driven insights for better operational decision-making.
By Application Segment, the market is categorized into On-Premise and Cloud-Based solutions. On-premise systems offer robust control and data security for enterprises, while cloud-based solutions provide scalability, real-time updates, and flexibility, making them ideal for dynamic urban environments.
By End-User Segment, the market serves diverse sectors. The Residential segment focuses on efficient management of private parking spaces. The Commercial segment, including shopping malls and office complexes, prioritizes customer convenience and traffic flow optimization. The Government and Municipalities segment seeks solutions to enhance urban mobility and manage public parking infrastructures effectively.
By Deployment Segment, the market is divided into On-Premise and Cloud-Based solutions. Cloud-based deployments are gaining traction due to lower upfront costs and easier scalability, while on-premise solutions remain preferred for organizations prioritizing data control.
Segmentation:
By Solution Segment
- Access Control
- Revenue Management
- Parking Security and Surveillance
- Parking Reservation Management
- Analytics Solutions
By Application Segment
- On-Premise
- Cloud-Based
By End-User Segment
- Residential
- Commercial
- Government and Municipalities
By Deployment Segment
- On-Premise
- Cloud-Based
Regional Analysis:
Within the United States, the adoption and implementation of parking management software exhibit regional variations influenced by factors such as urban density, technological infrastructure, and local government initiatives.
Northeastern United States
The Northeastern region, encompassing states like New York, Massachusetts, and Pennsylvania, has been proactive in adopting parking management solutions. The high population density and urbanization in cities such as New York City and Boston necessitate efficient parking systems to alleviate congestion. Initiatives to integrate smart parking technologies have been supported by local governments aiming to improve urban mobility and reduce environmental impacts.
Midwestern United States
In the Midwest, states like Illinois, Michigan, and Ohio have shown a growing interest in modernizing parking infrastructures. Cities such as Chicago and Detroit are implementing parking management software to revitalize urban centers and support economic development. The focus has been on integrating these systems with public transportation to create seamless mobility solutions for residents and visitors.
Southern United States
The Southern region, including states like Texas, Florida, and Georgia, has experienced rapid urban growth, leading to increased vehicle ownership. Cities such as Houston, Miami, and Atlanta are investing in parking management software to address traffic congestion and enhance the efficiency of parking facilities. The adoption rate in this region is expected to rise as urbanization continues and the demand for smart city solutions grows.
Western United States
The Western region, particularly California, has been at the forefront of implementing advanced parking management systems. Cities like Los Angeles and San Francisco face significant traffic challenges, prompting the adoption of innovative parking solutions. The emphasis on environmental sustainability and technological innovation in this region has accelerated the integration of smart parking technologies.
Key Player Analysis:
- ParkMobile, LLC
- Passport Parking Inc.
- Cisco Systems, Inc.
- Amano Corporation
- TIBA Parking Systems
- FlashParking
- SP Plus Corporation
- LAZ Parking Ltd, LLC
- ParkingSoft
- Q-Free ASA (U.S. operations)
Competitive Analysis:
The U.S. parking management software market is characterized by a diverse landscape of competitors, each striving to address the increasing demand for efficient parking solutions driven by urbanization and technological advancements. Prominent players in this sector include Amano McGann, SWARCO, SKIDATA, Chetu, INRIX, FAAC Technologies, TIBA Parking Systems, FlashParking, Passport Labs, Get My Parking, and DESIGNA. These companies offer a range of services, from mobile payment solutions to comprehensive parking management systems, catering to both public and private sectors. For instance, FAAC Mobility Services focuses on generating revenue from parking assets by employing proprietary software for complex parking needs. The competitive environment is further intensified by the integration of emerging technologies such as the Internet of Things (IoT), artificial intelligence (AI), and cloud computing, which enhance the functionality and user experience of parking systems. As urban areas continue to grow and the number of vehicles increases, the demand for innovative parking management solutions is expected to rise, encouraging ongoing competition and technological advancement within the industry.
Recent Developments:
- In July 2022, Flowbird Groupexpanded its digital capabilities through the acquisition of YourParkingSpace. This strategic move enhances Flowbird’s off-street parking services, particularly in the UK market, but also aligns with the company’s broader strategy to broaden its offerings in digital parking solutions, tapping into the growing demand for integrated parking system.
- In September 2023, TIBA Parking Systems partnered with REEF Technology to create a data-driven platform for parking operators and landlords. This partnership aims to enhance the parking experience by leveraging data insights.
Market Concentration & Characteristics:
The U.S. parking management software market exhibits a moderately fragmented structure, with numerous players contributing to its ongoing development. The market is witnessing substantial growth, driven by factors such as increasing urbanization, the rise in vehicle ownership, and the escalating demand for efficient parking solutions. This competitive landscape encourages innovation and competitive pricing, offering diverse options to end-users and fostering dynamic market growth. The trend towards integrating advanced technologies like Artificial Intelligence (AI) and the Internet of Things (IoT) is set to revolutionize parking management systems. These technologies enhance operational efficiency, enable real-time data collection, and improve the overall user experience. Additionally, the market is expected to benefit from strategic collaborations and partnerships among key players, aimed at fostering innovation and expanding market reach. As cities continue to evolve and smart infrastructure becomes more prevalent, the U.S. parking management software market is poised for continued growth and diversification, offering ample opportunities for both established and emerging players.
Report Coverage:
The research report offers an in-depth analysis based on By Solution Segment, By Application Segment, By End-User Segment and By Deployment Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The U.S. parking management software market is projected to experience significant growth over the forecast period, driven by increasing demand for efficient and automated parking solutions.
- Increasing urbanization and vehicle ownership will drive the demand for efficient and automated parking solutions.
- Advancements in IoT and AI technologies will enhance real-time parking analytics and predictive management capabilities.
- Integration of cloud-based platforms will streamline operations, offering scalability and improved data management.
- The rise of smart city initiatives will accelerate the adoption of intelligent parking management systems.
- Environmental concerns will encourage the development of eco-friendly and sustainable parking solutions.
- Growing investments in digital infrastructure will enhance the deployment of advanced parking technologies.
- Increased focus on mobile applications and digital payment solutions will improve user convenience and experience.
- The market will see heightened competition as both established players and startups innovate to capture market share.
- Regulatory support for efficient urban mobility will encourage the deployment of integrated and automated parking systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Urbanization and Increased Vehicle Ownership
Rapid urbanization and a surge in vehicle ownership in U.S. cities are intensifying the need for efficient parking management solutions, as limited parking availability and congestion require advanced software to optimize space and streamline operations.
Technological Advancements (IoT, AI, Cloud)
The integration of IoT sensors, artificial intelligence, and cloud-based platforms is transforming parking management by enabling real-time data collection, predictive analytics, and automated payment processes, which enhance operational efficiency and user experience.
Environmental Sustainability Initiatives
Growing environmental concerns and regulatory pressures are driving the adoption of parking management software that reduces vehicle idling and emissions, supporting sustainable urban mobility and helping cities meet climate goals.
Government Support and Smart City Initiatives
Federal, state, and municipal investments in smart city infrastructure and intelligent transportation systems are accelerating the deployment of advanced parking management solutions, improving traffic flow and urban space utilization.
Demand for Seamless User Experience
Consumers increasingly expect convenient, automated, and mobile-enabled parking solutions, prompting operators to adopt software that supports digital payments, reservations, and real-time space availability to enhance customer satisfaction.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Parking Management Software Market?
What factors are driving the growth of the U.S. Parking Management Software Market?
Who are the major players in the U.S. Parking Management Software Market?
Which regions are leading the U.S. Parking Management Software Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User Segment
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.2.3 Government and Municipalities
- 1.3 By Solution Segment
- 1.3.1 Access Control
- 1.3.2 Revenue Management
- 1.3.3 Parking Security and Surveillance
- 1.3.4 Parking Reservation Management
- 1.3.5 Analytics Solutions
- 1.4 By Deployment Segment
- 1.4.1 On-Premise
- 1.4.2 Cloud-Based
- 1.5 By Application Segment
- 1.5.1 On-Premise
- 1.5.2 Cloud-Based
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,487.11 million → 2032: USD 2,743.16 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Parking Management Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Parking Management Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 U.S. Parking Management Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 U.S. Parking Management Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Parking Management Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Parking Management Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Parking Management Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Parking Management Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,487.11 million → 2032: USD 2,743.16 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Parking Management Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User Segment - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Residential
- 12.3.6.2 Commercial
- 12.3.6.3 Government and Municipalities
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Solution Segment - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Access Control
- 12.4.6.2 Revenue Management
- 12.4.6.3 Parking Security and Surveillance
- 12.4.6.4 Parking Reservation Management
- 12.4.6.5 Analytics Solutions
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Segment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 On-Premise
- 12.5.6.2 Cloud-Based
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Application Segment - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 On-Premise
- 12.6.6.2 Cloud-Based
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Parking Management Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Parking Management Software Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Parking Management Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Parking Management Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ParkMobile, LLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Passport Parking Inc.
- 18.4 Cisco Systems, Inc.
- 18.5 Amano Corporation
- 18.6 TIBA Parking Systems
- 18.7 FlashParking
- 18.8 SP Plus Corporation
- 18.9 LAZ Parking Ltd, LLC
- 18.10 ParkingSoft
- 18.11 Q-Free ASA (U.S. operations)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

