
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| U.S. Underground Mining Equipment Market Size 2023 | USD 32,547.62 Million |
| U.S. Underground Mining Equipment Market, CAGR | 5.29% |
| U.S. Underground Mining Equipment Market Size 2032 | USD 52,496.02 Million |
Market Overview
The U.S. Underground Mining Equipment Market is projected to grow from USD 32,547.62 million in 2023 to an estimated USD 52,496.02 million by 2032, reflecting a CAGR of 5.29% from 2024 to 2032. This robust growth is driven by increasing demand for essential minerals and metals, heightened investment in advanced mining technologies, and rising focus on enhancing operational efficiency in underground mining activities.
Key market drivers include the growing demand for raw materials in industries such as construction, automotive, and electronics. The trend toward digitization and automation in mining operations is accelerating the adoption of equipment with advanced features like telematics and IoT integration. Furthermore, an increasing focus on safety and environmental sustainability is encouraging the deployment of low-emission, energy-efficient machinery in mining operations. These factors collectively contribute to a favorable market outlook.
Geographically, the U.S. market exhibits significant regional variability, with major mining activities concentrated in states such as Nevada, Wyoming, and West Virginia. These regions benefit from extensive mineral reserves and established mining infrastructures. Leading players in the market include Caterpillar Inc., Komatsu Ltd., Sandvik AB, Joy Global Inc., and Atlas Copco AB, among others. These companies focus on innovation and strategic collaborations to enhance their product portfolios and maintain competitive positions in this rapidly evolving market.
Market Drivers
Rising Demand for Essential Minerals and Metals
The increasing need for essential minerals and metals is a critical driver for the U.S. underground mining equipment market. As industries such as construction, automotive, renewable energy, and electronics continue to grow, the demand for resources like coal, copper, lithium, and rare earth metals has surged. For instance, the construction sector relies heavily on materials like iron ore for steel production, while the renewable energy sector requires significant quantities of lithium and cobalt for batteries used in electric vehicles and energy storage systems. This escalating demand compels mining companies to invest in advanced underground mining equipment to extract resources more efficiently, particularly as surface deposits become depleted.Furthermore, the global energy transition amplifies the need for metals like nickel and copper, which are vital for electric grids and wind turbines. This shift necessitates increased underground mining operations to access deeper, high-quality mineral deposits. Consequently, mining companies are investing in innovative and robust equipment designed to operate in challenging geological conditions, ensuring continuous extraction to meet market demands.
Technological Advancements and Automation in Mining
Technological innovation is revolutionizing the underground mining equipment market, enabling greater efficiency, productivity, and safety. Automation and digitization have emerged as game-changers, with many mining companies integrating Internet of Things (IoT) sensors, real-time monitoring systems, and autonomous machinery into their operations. For instance, remote-controlled drills and loaders allow operators to manage equipment from a safe distance, addressing challenges associated with limited visibility and hazardous environments. These technologies optimize resource extraction, reduce operational costs, and minimize downtime.IoT-enabled sensors monitor equipment performance, predict maintenance needs, and reduce unplanned shutdowns, further contributing to operational efficiency. As these technologies become more accessible, mining companies are increasingly adopting them to maintain competitiveness and ensure sustainability in operations.
Government Initiatives and Focus on Sustainable Mining
The U.S. government’s focus on sustainable mining practices is another significant market driver. Regulatory bodies such as the Mine Safety and Health Administration (MSHA) have introduced stringent safety and environmental regulations to mitigate the impact of mining activities. These policies encourage the adoption of energy-efficient and low-emission underground mining equipment.Moreover, the government’s emphasis on domestic mineral production to reduce reliance on imports has led to increased investment in mining infrastructure. Tax incentives and funding initiatives for sustainable mining projects have accelerated the adoption of equipment designed to minimize environmental impact. For instance, battery-electric mining vehicles are gaining popularity due to their lower emissions and operational efficiency. These measures align with the broader objective of transitioning toward a more sustainable and self-reliant mining sector in the U.S.
Expanding Investments in Mining Infrastructure
Expanding investments in mining infrastructure across the U.S. are significantly influencing the underground mining equipment market. Mining companies are allocating substantial budgets toward modernizing operations and upgrading outdated equipment. These investments aim to enhance productivity, extend equipment life, and comply with evolving safety and environmental standards.Additionally, private and public sector collaborations are fueling the development of advanced mining technologies and infrastructure. For example, partnerships between equipment manufacturers and mining operators focus on designing customized solutions to address specific operational challenges. Similarly, research and development initiatives are advancing cutting-edge technologies like electric and hybrid mining vehicles, boosting their integration into the underground mining ecosystem. These investments underscore the sector's commitment to modernizing its capabilities and meeting the growing demand for essential resources.
Market Trends
Adoption of Trenchless Technology and Advanced Construction Methods
A significant trend in the U.S. underground equipment market is the widespread adoption of trenchless technology and other advanced construction methods. Trenchless techniques, such as horizontal directional drilling (HDD), pipe bursting, and micro-tunneling, are being increasingly employed for infrastructure projects due to their ability to minimize surface disruption, reduce project timelines, and lower overall costs. This trend aligns with the growing need for upgrading or replacing aging underground infrastructure while maintaining public convenience and reducing environmental impact. By eliminating extensive excavation and enabling efficient subsurface installations, trenchless technology has become a preferred solution for deploying underground utilities, including water lines, sewage systems, and telecommunications networks. The trend is further supported by advances in machine capabilities, including automation, precision control, and integration with real-time monitoring technologies, which enhance operational efficiency and safety. For instance, during the Pumping Station 17 Force Main Relief Phase 2 project in Verona, Wisconsin, trenchless technology was employed to install a 42-inch diameter sewer pipe using pilot tube microtunneling under a railroad corridor, minimizing surface disruption and maintaining traffic flow while efficiently completing the project in early 2024.
Focus on Sustainable and Environmentally Friendly Solutions
Sustainability is increasingly at the forefront of the U.S. underground equipment market, driven by stringent environmental regulations and a rising awareness of climate change. Companies are investing in the development and deployment of eco-friendly underground equipment that minimizes emissions, reduces energy consumption, and adheres to environmental standards. Electric-powered and hybrid machines, low-emission diesel engines, and biodegradable lubricants are among the solutions that are gaining traction in the market. This trend underscores the market’s commitment to minimizing the carbon footprint of underground construction projects while ensuring compliance with environmental guidelines. Additionally, the integration of intelligent systems and digital technologies, such as IoT-enabled sensors and data analytics platforms, is enhancing project sustainability by enabling predictive maintenance, reducing resource waste, and optimizing equipment performance. The focus on sustainable practices aligns with public and private sector initiatives aimed at building resilient, future-ready underground infrastructure. This commitment to environmentally conscious solutions ensures that market growth is both sustainable and aligned with broader ecological goals.For instance, Alamos Gold's Young-Davidson mine in Ontario replaced six diesel haul trucks with an electric conveyance system as part of its lower mine expansion, which not only reduced fossil fuel usage but also cut greenhouse gas emissions significantly.
Market Restraints and Challenges
High Capital and Maintenance Costs
The substantial capital investment required for underground mining equipment is a significant restraint for market growth. Advanced equipment such as autonomous drills, IoT-enabled machinery, and battery-electric vehicles often involve high upfront costs, making it challenging for small and medium-sized enterprises (SMEs) to adopt these technologies. In addition to acquisition costs, the maintenance and operational expenses associated with these sophisticated machines can be burdensome. Regular servicing, replacement of parts, and upgrades to ensure compliance with safety and environmental regulations further add to the financial strain.Moreover, the rapid pace of technological advancements necessitates frequent upgrades to maintain competitiveness. Older equipment often becomes obsolete, forcing companies to invest in newer technologies. These financial pressures, coupled with fluctuating mineral prices and market uncertainties, can limit the ability of mining companies to invest in state-of-the-art equipment, restraining overall market growth.
Environmental and Regulatory Challenges
Stringent environmental regulations and safety standards pose significant challenges for the U.S. underground mining equipment market. Regulatory bodies, including the Environmental Protection Agency (EPA) and the Mine Safety and Health Administration (MSHA), enforce strict guidelines to minimize environmental impacts and ensure worker safety. Compliance with these regulations often requires substantial investment in specialized equipment and technologies, which can be cost-prohibitive for some operators.Additionally, environmental concerns such as carbon emissions, waste management, and ecosystem disruption create reputational risks for mining companies. Public scrutiny and opposition from local communities further complicate the expansion of mining operations. Balancing regulatory compliance with operational efficiency remains a persistent challenge, requiring companies to navigate complex environmental and legal landscapes while maintaining profitability.
Market Segmentation Analysis
By Product Type
The U.S. underground equipment market is driven by several key product types that are integral to efficient mining operations. Mining loaders are essential for moving ore and waste material, with demand increasing due to innovations in automation and fuel efficiency, which enhance productivity and reduce delays. Mining trucks are designed to haul heavy loads in harsh underground conditions, with a growing focus on optimizing productivity and ensuring safety through advanced features and high payload capacities. Mining drills are critical for precise exploration and extraction, particularly as demand grows for deeper mineral exploration and high-pressure drilling capabilities. Mining bolters are used for ground control and rock reinforcement, and their importance is amplified by the emphasis on worker safety and stability in underground mines. Finally, mining shearers are crucial in soft rock mining, particularly coal extraction, where their efficiency in continuous mining processes helps maximize output and minimize downtime. These product types reflect the diverse needs of the underground equipment market and its ongoing focus on safety, efficiency, and technological advancement.
By mining Technique
The U.S. underground equipment market is divided into two main mining techniques: soft rock mining and hard rock mining. Soft rock mining, which involves the extraction of materials such as coal and non-metallic minerals, demands specialized equipment like mining shearers and loaders to address the unique challenges of these operations. On the other hand, hard rock mining, focused on extracting metals like gold, copper, and iron, requires more robust and durable equipment capable of handling high-pressure conditions and abrasive materials. Equipment such as mining drills, bolters, and loaders specifically designed for hard rock environments are in high demand due to the challenging and intense nature of these mining operations.
Segments
Based on Product Type
- Mining Loaders
- Mining Trucks
- Mining Drills
- Mining Bolters
- Mining Shearer
Based on Mining Technique
- Soft Rock Mining
- Hard Rock Mining
Based on End User
- Mining Operators
- Rental Service Providers
Based on Region
- Western United States
- Midwestern United States
- Southern United States
- Northeastern United States
- Other Regions
Regional Analysis
Western United States (40%):
The Western U.S. dominates the underground mining equipment market, accounting for approximately 40% of the total market share. States like Nevada, Utah, and Colorado are major contributors, driven by their rich deposits of precious metals such as gold, silver, and copper. Nevada, often referred to as the "Silver State," leads in underground mining activity, with well-established mining infrastructures and significant investments in advanced equipment. The adoption of automation and IoT-enabled machinery is particularly high in this region, aligning with its focus on efficiency and sustainability.
Midwestern United States (20%):
The Midwest holds 20% of the market share, supported by mining operations for iron ore, limestone, and other industrial minerals. States like Minnesota and Michigan play a key role, with mining companies in the region investing in high-capacity underground equipment to meet the growing demand for raw materials in construction and manufacturing. The region also benefits from strong governmental support for sustainable mining practices, which encourages the adoption of energy-efficient equipment.
Key players
- Caterpillar Inc.
- Komatsu Ltd.
- Joy Global Inc.
- Sandvik AB
- Volvo AB
- Hitachi Construction Machinery Co. Ltd.
- Doosan Infracore Co. Ltd.
- Boart Longyear Ltd.
- FLSmidth Group
- Kennametal, Inc.
- Metso Corporation
- Thyssenkrupp AG
Competitive Analysis
The U.S. underground mining equipment market is characterized by intense competition among key players striving to enhance their market share through innovation and strategic collaborations. Caterpillar Inc. and Komatsu Ltd. lead the market with extensive product portfolios and a strong focus on automation and sustainability. Joy Global Inc. and Sandvik AB specialize in advanced underground solutions, offering technologically sophisticated and energy-efficient machinery. Volvo AB and Hitachi Construction Machinery Co. Ltd. focus on durable, high-capacity equipment to meet diverse mining needs. Companies like Doosan Infracore Co. Ltd. and Boart Longyear Ltd. emphasize niche technologies such as drilling and core sampling solutions. Meanwhile, FLSmidth Group and Kennametal, Inc. deliver value through materials handling and wear-resistant components. Metso Corporation and Thyssenkrupp AG stand out for their expertise in crushing and processing equipment. These players compete on innovation, regional presence, and sustainability, shaping the market's evolution in a technologically driven and environmentally conscious landscape.
Recent Developments
- In December 2023, Caterpillar demonstrated its first battery electric prototype underground mining truck in Tasmania, Australia, partnering with Newmont Corporation.
- In July 2024, Komatsu completed acquisition of GHH Group GmbH, a German manufacturer of underground mining equipment, expanding its underground mining portfolio.
- In September 2024, DSI Underground completed full integration and rebranding as Sandvik, strengthening Sandvik's position in underground safety solutions and ground support equipment.
- In October 2024, Hitachi Construction Machinery opened a new Mining Machinery Component Remanufacturing Plant in Kazakhstan.
- In May 2024, Doosan Bobcat signed MOU with HD Hyundai Infracore for portfolio expansion and strategic equipment sharing.
Market Concentration and Characteristics
The U.S. underground mining equipment market exhibits a moderate to high level of market concentration, with a few dominant players such as Caterpillar Inc., Komatsu Ltd., Sandvik AB, and Joy Global Inc. holding significant market shares. These companies benefit from extensive product portfolios, global reach, and strong R&D capabilities, enabling them to lead in innovation and technological advancements. However, the market also features several smaller and specialized players, such as Boart Longyear Ltd. and Kennametal, Inc., focusing on niche areas like drilling solutions and wear-resistant components. The market is characterized by rapid adoption of automation, digitization, and sustainable technologies, driven by stringent safety and environmental regulations. High entry barriers due to substantial capital requirements, technological expertise, and compliance mandates further concentrate the market among established players, ensuring competitive dynamics remain focused on innovation, efficiency, and environmental responsibility.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Mining Technique, End User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The U.S. underground mining equipment market is expected to maintain steady growth, driven by increasing demand for minerals essential to construction, energy, and manufacturing sectors.
- Automation technologies such as autonomous vehicles and remote-controlled equipment will gain widespread adoption, improving operational efficiency and safety in underground mining.
- The market will experience a growing transition to battery-electric mining equipment, aligning with industry goals to reduce emissions and improve air quality in underground environments.
- Mining companies will increasingly invest in energy-efficient machinery and sustainable practices to comply with stringent environmental regulations and meet stakeholder expectations.
- Enhanced focus on research and development will drive innovation in IoT-enabled and AI-powered equipment, enabling smarter, data-driven mining operations.
- The surge in renewable energy and electric vehicle production will boost the demand for rare earth metals, encouraging investments in advanced underground mining solutions.
- Regions such as the Midwest and Southwest are expected to see increased mining activity, fueled by demand for industrial minerals and base metals like copper.
- Key players will engage in strategic collaborations to develop customized solutions, expand their portfolios, and strengthen their presence in a competitive market.
- Innovative safety technologies, such as real-time monitoring systems and wearable devices, will become integral to improving workplace conditions and reducing mining accidents.
- Predictive maintenance technologies will play a critical role in reducing operational costs by enabling timely equipment servicing and minimizing unplanned downtime.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements and Automation
The integration of automation, IoT, and remote-controlled equipment is transforming underground mining operations, enabling higher productivity, improved safety, and reduced operational costs. These innovations are driving rapid adoption of advanced underground mining equipment across the U.S.
Government Initiatives and Sustainability Regulations
Stringent safety and environmental regulations, along with government incentives for sustainable mining, are compelling companies to invest in energy-efficient, low-emission underground equipment. This regulatory push is accelerating the transition to battery-electric and eco-friendly machinery.
Expanding Investments in Mining Infrastructure
Mining companies are allocating significant capital to modernize operations and upgrade equipment, aiming to boost productivity and comply with evolving standards. Public and private sector collaborations are also fostering the development and deployment of advanced underground mining technologies.
Growing Demand for Essential Minerals and Metals
The surge in demand for minerals such as copper, lithium, and rare earths - driven by growth in construction, renewable energy, and electric vehicles - is prompting mining operators to expand underground operations and invest in more efficient extraction equipment.
Regional Concentration of Mining Activities
States like Nevada, Utah, and Colorado have extensive mineral reserves and established mining infrastructures, leading to concentrated demand for underground mining equipment and fostering regional innovation and adoption of advanced technologies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the U.S. underground mining equipment market in 2023 and 2032, and what is its CAGR?
What factors are driving the growth of the U.S. underground mining equipment market?
How is technology influencing the U.S. underground mining equipment market?
Which regions in the U.S. dominate the underground mining equipment market?
Who are the key players in the U.S. underground mining equipment market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Mining Operators
- 1.2.2 Rental Service Providers
- 1.3 By Product Type
- 1.3.1 Mining Loaders
- 1.3.2 Mining Trucks
- 1.3.3 Mining Drills
- 1.3.4 Mining Bolters
- 1.3.5 Mining Shearer
- 1.4 By Mining Technique
- 1.4.1 Soft Rock Mining
- 1.4.2 Hard Rock Mining
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
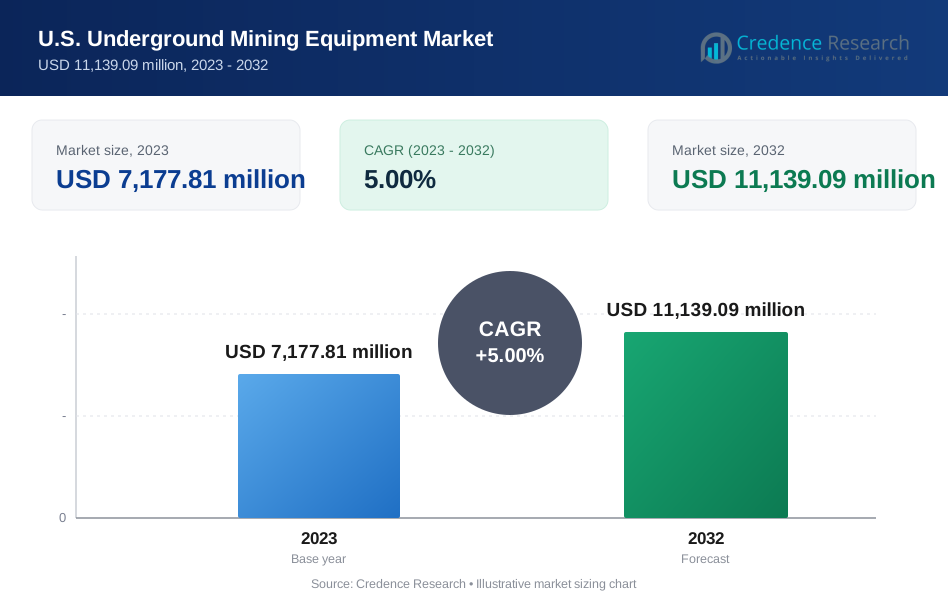
- 2.5.1 2023: USD 7,177.81 million → 2032: USD 11,139.09 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Underground Mining Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Underground Mining Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Underground Mining Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Underground Mining Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Underground Mining Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Underground Mining Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Underground Mining Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Underground Mining Equipment Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 7,177.81 million → 2032: USD 11,139.09 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Underground Mining Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Mining Operators
- 12.3.7.2 Rental Service Providers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Mining Loaders
- 12.4.7.2 Mining Trucks
- 12.4.7.3 Mining Drills
- 12.4.7.4 Mining Bolters
- 12.4.7.5 Mining Shearer
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Mining Technique - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Soft Rock Mining
- 12.5.7.2 Hard Rock Mining
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Underground Mining Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Underground Mining Equipment Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Underground Mining Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Underground Mining Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Caterpillar Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Komatsu Ltd.
- 18.4 Sandvik AB
- 18.5 Joy Global Inc.
- 18.6 Volvo AB
- 18.7 Hitachi Construction Machinery Co. Ltd.
- 18.8 Doosan Infracore Co. Ltd.
- 18.9 Boart Longyear Ltd.
- 18.10 FLSmidth Group
- 18.11 Kennametal, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

