
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vietnam Building Construction Market Size 2024 | USD 40.11 Million |
| Vietnam Building Construction Market, CAGR | 7.71% |
| Vietnam Building Construction Market Size 2032 | USD 78.34 Million |
Market Overview
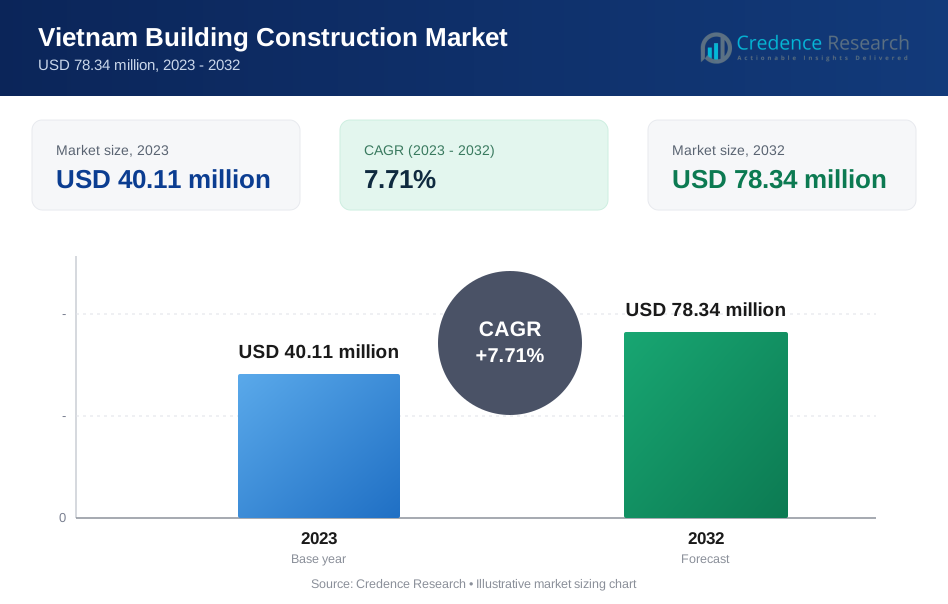
The Vietnam Building Construction Market is projected to grow from USD 40.11 million in 2023 to an estimated USD 78.34 million by 2032, with a compound annual growth rate (CAGR) of 7.71% from 2024 to 2032. This growth is driven by an increasing demand for residential, commercial, and infrastructure development projects, as urbanization and economic expansion continue to shape the landscape.
Key drivers of this growth include the ongoing urbanization, increased foreign investment, and government initiatives to improve infrastructure and urban planning. The demand for affordable housing, commercial spaces, and the development of smart cities also plays a significant role in accelerating the construction sector’s expansion. Additionally, the trend towards green building and sustainable construction practices is gaining momentum, with stakeholders prioritizing environmentally friendly materials and energy-efficient designs.
Geographically, the Vietnam Building Construction Market is concentrated in major urban areas, including Ho Chi Minh City, Hanoi, and Da Nang, where most of the development activities occur. The growing demand in these cities is being fueled by the expansion of residential and commercial projects. Key players in the market include Coteccons Construction, Hoa Binh Construction, and VinGroup, who are prominent in shaping the sector with innovative construction solutions and large-scale developments.
Market Insights
- The Vietnam Building Construction Market is projected to grow from USD 40.11 million in 2023 to USD 78.34 million by 2032, with a CAGR of 7.71% from 2024 to 2032.
- Key drivers include urbanization, increased foreign investment, government infrastructure initiatives, and growing demand for residential and commercial properties.
- The rise of sustainable building practices, including green buildings and energy-efficient designs, is significantly influencing market growth.
- Major market challenges include a shortage of skilled labor and rising construction material costs, which can delay projects and increase costs.
- The market is concentrated in major cities like Ho Chi Minh City, Hanoi, and Da Nang, where development activities are highest.
- South Vietnam dominates the market, with Ho Chi Minh City leading in residential, commercial, and infrastructure construction.
- Public-private partnerships (PPPs) are becoming increasingly important, offering opportunities for large-scale infrastructure and residential projects.
Market Drivers
Rapid Urbanization and Population Growth
One of the primary drivers of the Vietnam Building Construction Market is the country's rapid urbanization and population growth. Vietnam has been experiencing significant urban migration, with millions moving from rural to urban areas in search of better economic opportunities, healthcare, and education. As a result, there is a growing need for residential, commercial, and industrial infrastructure. The urban population in Vietnam is projected to grow significantly over the next decade, driving the demand for housing and public infrastructure. This urbanization trend creates an urgent need for the construction of residential complexes, commercial buildings, and public utilities such as transportation systems, schools, and hospitals. Consequently, the building construction market is expected to expand as developers focus on meeting the housing demands of the urban populace while ensuring that cities remain well-equipped to handle the influx of people.
Government Infrastructure Development Initiatives
The Vietnamese government has been prioritizing infrastructure development as a key part of its national growth strategy. Government-led initiatives, such as the construction of highways, bridges, and public transport systems, have fueled the building construction sector. Investments in large-scale projects, including the expansion of airports and the development of new industrial zones, are designed to improve connectivity and encourage both domestic and foreign investments. These infrastructure projects not only improve the nation's economic competitiveness but also create new opportunities for the building construction market. The government's focus on upgrading transportation networks, water management systems, and energy-efficient buildings is expected to continue driving demand for construction services. Public-private partnerships (PPPs) are becoming increasingly popular, where private investors collaborate with the government on large-scale construction projects, ensuring consistent market growth. For example, the Vietnamese government is prioritizing infrastructure development by investing in large-scale projects such as the expansion of airports and the development of new industrial zones. The construction of highways, bridges, and public transport systems is also underway, improving connectivity and encouraging domestic and foreign investments.
Rising Demand for Residential and Commercial Spaces
Another significant driver of the Vietnam Building Construction Market is the increasing demand for both residential and commercial spaces. The urban population growth and rising income levels are fueling the need for residential housing, especially affordable housing units. The Vietnamese government has introduced several initiatives to address the housing deficit by promoting affordable housing development projects through tax incentives and subsidies for developers. In addition, the growing middle class is pushing the demand for premium residential buildings and luxury housing, particularly in major cities like Hanoi and Ho Chi Minh City. On the commercial side, there is a steady rise in demand for office spaces, retail outlets, and industrial facilities due to increased business activity, foreign direct investment (FDI), and economic growth. International businesses are setting up operations in Vietnam, further increasing demand for office buildings, commercial complexes, and warehouses. Additionally, the booming retail sector and the rise of e-commerce require new spaces for shopping malls, logistics centers, and distribution hubs. These trends are creating a highly lucrative environment for construction firms involved in the development of both residential and commercial projects. For instance, major cities like Hanoi and Ho Chi Minh City are experiencing high demand for residential housing, particularly affordable housing units. The government has introduced initiatives to promote affordable housing through tax incentives and subsidies for developers. On the commercial side, there is a steady rise in demand for office spaces and industrial facilities due to increased business activity and foreign direct investment.
Focus on Sustainability and Green Building Practices
The growing emphasis on sustainability is another key driver in the Vietnam Building Construction Market. As global awareness of environmental issues continues to rise, there is a strong push for green building practices within the construction industry. This includes the use of sustainable materials, energy-efficient technologies, and environmentally friendly designs in both residential and commercial building projects. The Vietnamese government is supporting the adoption of green construction standards through regulations and incentives that encourage developers to build with a focus on sustainability. In response, the demand for green building materials, such as recycled construction materials, energy-efficient insulation, and solar power systems, has grown. Furthermore, developers are increasingly incorporating smart building technologies, which allow for energy-efficient management systems and reduced environmental impact. The trend toward eco-friendly and energy-efficient buildings is not only driving the construction of sustainable structures but also attracting international investors who prioritize sustainable investment opportunities. For example, the Vietnamese government is supporting the adoption of green construction standards through regulations and incentives. Developers are increasingly incorporating sustainable materials, energy-efficient technologies, and environmentally friendly designs in building projects. This trend is attracting international investors who prioritize sustainable investment opportunities.
Market Trends
Adoption of Smart Building Technologies
A notable trend in the Vietnam Building Construction Market is the growing adoption of smart building technologies. With increasing urbanization and the expansion of both residential and commercial real estate projects, there is an increasing demand for buildings that offer enhanced convenience, efficiency, and sustainability. Smart buildings integrate advanced technologies such as automation systems, energy management tools, and Internet of Things (IoT) solutions to optimize building performance. These technologies allow for greater control over lighting, heating, cooling, and security systems, which helps reduce energy consumption and operating costs.In Vietnam, the adoption of smart building technologies is becoming more prominent, especially in high-end residential developments and commercial real estate projects. Developers and investors are increasingly integrating these technologies to appeal to tech-savvy consumers and businesses that prioritize sustainability and operational efficiency. The government has also shown interest in supporting the development of smart cities, which is further pushing the market toward the integration of smart technologies. For instance, the number of smart building projects in Vietnam has been steadily increasing, with expectations of further growth by the end of the decade. In addition to enhancing the living experience, these smart solutions improve the long-term value of properties and are becoming key selling points in both the residential and commercial segments.
Focus on Sustainable Construction Practices and Green Buildings
Sustainability has emerged as a critical trend in the Vietnam Building Construction Market. There is growing pressure on developers to build energy-efficient, environmentally friendly buildings that meet green building standards. As environmental concerns intensify globally, stakeholders in the construction industry are increasingly adopting practices that reduce the environmental impact of their projects. In Vietnam, the government has implemented various incentives and regulations to encourage green construction practices, including the promotion of low-carbon buildings, the use of recycled materials, and the integration of renewable energy systems like solar panels.The demand for green buildings is rapidly increasing in both the residential and commercial sectors. This includes buildings that are designed to minimize resource consumption and reduce waste throughout their lifecycle. Several high-profile projects in major cities like Ho Chi Minh City and Hanoi are already certified as Green Buildings by international standards such as LEED (Leadership in Energy and Environmental Design) and LOTUS (Vietnam's green building rating system). For instance, the adoption of various green building certification systems such as EDGE, LEED, Green Mark, and Lotus demonstrates the market's commitment to sustainable practices. In addition to government initiatives, businesses and consumers are becoming more aware of the benefits of energy-efficient buildings, including lower operational costs, better air quality, and enhanced comfort. As a result, construction companies are incorporating sustainability into their building designs, and the trend of green buildings is expected to grow significantly in the coming years.
Rise of Mixed-Use Developments
The trend of mixed-use developments is becoming increasingly prevalent in Vietnam, driven by the growing demand for multifunctional spaces that integrate residential, commercial, and recreational facilities. These developments are seen as efficient solutions to the challenges of urbanization, as they promote the efficient use of space and reduce the need for long commutes. Mixed-use buildings typically feature a combination of residential apartments, office spaces, retail outlets, and leisure facilities, all within the same complex or neighborhood.In cities like Ho Chi Minh City and Hanoi, developers are increasingly focusing on creating integrated communities where residents can live, work, shop, and play without the need for significant travel. This trend is closely linked to the demand for urban living spaces that cater to modern lifestyles, offering convenience and flexibility. Additionally, mixed-use developments help address the shortage of land for new construction, as they maximize the use of limited space in urban centers. For instance, the development of mixed-use projects like CanGio in Ho Chi Minh City, which incorporates residential, tourism, and commercial elements across a vast area, showcases the trend towards integrated urban spaces. This trend is also driven by the increasing number of international businesses establishing offices in Vietnam, as well as the rising popularity of lifestyle-centric developments that offer easy access to amenities. As mixed-use developments become more common, they are expected to play a significant role in shaping Vietnam's urban landscape.
Growth of the Infrastructure Sector
The expansion of infrastructure projects is another prominent trend currently shaping the Vietnam Building Construction Market. The Vietnamese government has placed significant emphasis on upgrading and expanding the country's infrastructure to support economic growth and urbanization. Key infrastructure initiatives include the development of new highways, bridges, airports, ports, and transportation networks. These large-scale projects are aimed at improving connectivity within the country and with international markets, boosting trade and commerce.The construction of smart transportation systems, such as metro lines in Ho Chi Minh City and Hanoi, is also a growing trend in Vietnam. These projects are designed to reduce traffic congestion, improve public transport efficiency, and support the rapid urbanization of the country. The government's focus on upgrading infrastructure is also evident in the development of renewable energy projects, which are becoming crucial to the country's long-term sustainability goals. For instance, the government's plans to expand the highway network, increase airport capacity, and develop new railway lines, including the North-South high-speed railway, highlight the focus on enhancing connectivity and supporting economic growth. The need for robust infrastructure is fueling demand for construction services, particularly in areas such as civil engineering, utilities, and transport infrastructure. This trend is not only driven by government spending but also by foreign investment, as international companies are increasingly attracted to Vietnam's growing infrastructure sector. The combination of public and private sector investment in infrastructure is expected to continue driving the building construction market's expansion, contributing to the growth of the overall economy.
Market Challenges
Labor Shortage and Skill Gaps
One of the major challenges facing the Vietnam Building Construction Market is the shortage of skilled labor. While the demand for construction projects continues to rise, the availability of a highly skilled workforce remains limited. Many construction companies struggle to find workers with specialized skills in areas such as advanced construction techniques, project management, and sustainability practices. The labor market in Vietnam is also facing an aging workforce, with younger generations showing less interest in entering the construction industry. This gap in skilled labor can lead to delays, increased project costs, and suboptimal quality, which can undermine the efficiency and profitability of construction projects. Companies are increasingly investing in training and upskilling their workforce to bridge these gaps, but the issue persists as the demand for construction professionals outpaces the availability of qualified candidates. Furthermore, labor shortages can result in companies needing to rely on foreign workers, which can increase labor costs and add complexity to project management.
Rising Construction Material Costs and Supply Chain Disruptions
Another significant challenge for the Vietnam Building Construction Market is the rising cost of construction materials and disruptions in the supply chain. Global supply chain issues, partly exacerbated by the COVID-19 pandemic, have led to price volatility and shortages of essential construction materials such as steel, cement, and timber. These rising material costs have a direct impact on construction budgets, often resulting in project cost overruns or delays as contractors face difficulties sourcing materials at affordable prices. Additionally, fluctuations in material prices can hinder long-term planning and budgeting for developers, creating uncertainty in project execution. Supply chain disruptions further complicate project timelines, as construction firms struggle to meet deadlines due to delays in material deliveries. These challenges require construction companies to adopt more strategic sourcing practices and explore alternative materials to mitigate costs and ensure the timely delivery of projects. However, the unpredictable nature of material costs continues to pose a risk to the stability of the construction market in Vietnam.
Market Opportunities
Government Infrastructure Investments
The Vietnamese government’s ongoing investment in infrastructure development presents a significant opportunity for growth in the building construction market. As part of its economic strategy, the government has prioritized the enhancement of transportation networks, public utilities, and urban infrastructure, including the construction of highways, bridges, airports, and metro systems in major cities. These large-scale projects create substantial demand for construction services and provide opportunities for both domestic and international construction firms. The government’s push for smart cities and sustainable infrastructure further supports the growth of this sector. Additionally, the use of public-private partnerships (PPPs) in funding these infrastructure projects offers developers and investors a chance to engage in high-value projects with reduced financial risk. As infrastructure expansion continues to be a key focus, the market stands to benefit from both public sector investments and private sector participation.
Rising Demand for Sustainable and Green Building Solutions
The growing demand for environmentally friendly and energy-efficient buildings offers a promising market opportunity. With increasing awareness of environmental sustainability, both developers and consumers in Vietnam are increasingly prioritizing green building practices. The Vietnamese government has introduced policies and incentives to promote green construction, encouraging developers to adopt eco-friendly designs, use renewable energy sources, and incorporate sustainable building materials. This shift towards sustainability not only aligns with global trends but also offers long-term operational cost savings for property owners and tenants. As urbanization intensifies, the need for sustainable housing and commercial spaces in urban centers presents a significant opportunity for construction companies to differentiate themselves by embracing green building standards and contributing to the development of eco-conscious communities.
Market Segmentation Analysis
Segments
Based on Type
- Residential
- Non-residential
Based on Construction Type
- New Construction
- Renovation
Based on End User
- Private
- Public
Based on Region
- North Vietnam
- Central Vietnam
- South Vietnam
Regional Analysis
North Vietnam (25-30%)
North Vietnam, led by Hanoi, the capital city, is a significant player in the building construction market. This region accounts for approximately 25-30% of the total market share. Hanoi has seen substantial growth in both residential and commercial construction due to its expanding population, increased foreign investments, and the growing demand for modern infrastructure. The government’s focus on developing smart cities, improving transportation networks, and expanding public infrastructure has driven demand for large-scale construction projects, such as roads, bridges, and metro lines. The residential segment also plays a major role, with a rising demand for affordable housing and high-end residential buildings.
Central Vietnam (15-20%)
Central Vietnam, which includes key cities such as Da Nang and Hue, contributes about 15-20% to the Vietnam Building Construction Market. This region’s growth is largely driven by the tourism and hospitality sector, which has led to increased demand for hotels, resorts, and leisure-related real estate. Da Nang, in particular, has seen rapid development due to its strategic location as a gateway to both domestic and international markets. The city is experiencing an influx of foreign investments, which is driving the construction of commercial real estate, residential complexes, and infrastructure projects. Additionally, Central Vietnam’s infrastructure development, including transportation networks and port facilities, continues to grow as the region solidifies its position as a central economic hub.
Key players
- Sansiri Public Company Limited
- Vingroup
- Novaland
- CapitaLand Vietnam
- Hoa Binh Construction Group
- Daiwa House Industry
- Hoa Sen Group
- KEPPEL Land Vietnam
Competitive Analysis
The Vietnam Building Construction Market is highly competitive, with both domestic and international players actively contributing to its growth. Vingroup, one of the largest real estate developers in Vietnam, maintains a significant market share through its diverse portfolio, ranging from residential to commercial projects. Novaland is also a key player, focusing on luxury and high-end residential developments. CapitaLand Vietnam, a subsidiary of the Singapore-based CapitaLand Group, brings advanced expertise in property development, particularly in the commercial and mixed-use sectors. Hoa Binh Construction Group and Hoa Sen Group are strong competitors in the construction and materials sectors, respectively, with a solid presence in both residential and infrastructure projects. Additionally, international players like Sansiri Public Company Limited and Daiwa House Industry are strengthening their positions by bringing international best practices and investment to the market. These players are increasingly adopting sustainable and smart building technologies to differentiate themselves in a competitive landscape.
Recent Developments
- In February 2025, Sansiri Public Company Limited announced "Dynamic Growth" plan for 2025, focusing on premium and mid-range projects in Vietnam. The company aims to launch 29 new projects worth 52 billion baht, including 7 joint venture projects valued at 19.5 billion baht.
- In January 2025, Vingroup announced plans to begin construction of the Can Gio sea encroachment project in April 2025. The project, valued at over 282 trillion VND, will include a 155-hectare golf course and more than 27,000 townhouses and villas.
- In May 2024, Novaland faced challenges with some projects, particularly Aqua City in Dong Nai province. The company stated that all its projects in southern Vietnam provinces were under construction and negotiated extended payment periods for customers.
- In March 2024, CapitaLand Vietnam announced plans to develop 27,000 residential units in Vietnam by 2028, a 70% increase from its current portfolio. The company broke ground on two major projects, Sycamore in Binh Duong province and Lumi Hanoi in Hanoi.
- In January 2025, Hoa Binh Construction Group reported a profit of 851.8 billion VND for 2024, marking a strong recovery after two years of losses. The company secured contracts worth 9 trillion VND in 2024, mainly in housing development.
- In January 2024, Daiwa House Industry formed a joint venture with WHA Group to develop the "DPL Vietnam Minh Quang" logistics facility. Construction is set to begin on March 1, 2024, with a site area of 70,109 sqm.
- In February 2025, Hoa Sen Group announced plans to invest over 2.3 trillion VND to expand its steel plant in Binh Dinh province. The expansion will add approximately 9.1 hectares to the existing 21.84-hectare facility.
Market Concentration and Characteristics
The Vietnam Building Construction Market is moderately concentrated, with a mix of large domestic and international players competing for market share. Key players like Vingroup, Novaland, and CapitaLand Vietnam dominate the residential, commercial, and infrastructure sectors, benefiting from strong brand recognition, substantial financial resources, and extensive project portfolios. The market is characterized by significant competition in urban areas such as Ho Chi Minh City and Hanoi, where rapid urbanization and increased demand for both residential and commercial properties fuel growth. Smaller and mid-sized companies also contribute to the market, often focusing on niche segments such as affordable housing or specialized construction services. As the market continues to grow, there is an increasing trend toward collaboration, with public-private partnerships (PPPs) becoming more common in large-scale infrastructure projects. The emphasis on sustainability, smart building technologies, and eco-friendly construction practices is also shaping the competitive landscape.
Report Coverage
The research report offers an in-depth analysis based on Type, Construction type, End Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- As urban populations continue to rise, the demand for residential and commercial construction will see sustained growth, particularly in major cities like Ho Chi Minh City and Hanoi.
- Government investments in infrastructure projects, including roads, bridges, and transportation networks, will drive the market’s growth, creating opportunities for large-scale construction projects.
- The focus on developing smart cities will lead to increased demand for sustainable, energy-efficient buildings equipped with advanced technologies to support urban living.
- The shift toward green building practices will intensify, with a growing emphasis on environmentally friendly materials, energy-efficient designs, and renewable energy integration in construction projects.
- Mixed-use developments combining residential, commercial, and recreational spaces will become more prominent, driven by the growing demand for multifunctional urban environments.
- Continued government support through tax incentives, subsidies, and public-private partnerships (PPPs) will further encourage investment in large-scale residential and infrastructure projects.
- The adoption of construction technologies such as Building Information Modeling (BIM), 3D printing, and automated construction techniques will streamline project execution and improve efficiency.
- Foreign direct investment (FDI) in the Vietnamese construction market will continue to rise, particularly in the commercial real estate and infrastructure sectors, as Vietnam remains an attractive investment destination.
- As the middle class expands, there will be a growing demand for affordable housing solutions, prompting both public and private sectors to address the housing deficit through large-scale development projects.
- The market will see a gradual recovery from the impact of the COVID-19 pandemic, with a focus on accelerating construction timelines and addressing supply chain disruptions to meet pent-up demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Vietnam Building Construction Market in 2023 and 2032?
What are the key drivers of growth in the Vietnam Building Construction Market?
Which regions are the most active in the Vietnam Building Construction Market?
How are green building trends affecting the Vietnam Building Construction Market?
Who are the key players in the Vietnam Building Construction Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vietnam Building Construction Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vietnam Building Construction Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 40.11 million → 2032: USD 78.34 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vietnam Building Construction Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vietnam Building Construction Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vietnam Building Construction Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vietnam Building Construction Market Drivers
- 3.3 Vietnam Building Construction Market Restraints & Challenges
- 3.4 Vietnam Building Construction Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vietnam Building Construction Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vietnam Building Construction Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vietnam Building Construction category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vietnam Building Construction Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vietnam Building Construction Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vietnam Building Construction market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vietnam Building Construction Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vietnam Building Construction Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vietnam Building Construction Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vietnam Building Construction (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vietnam Building Construction Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vietnam Building Construction Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vietnam Building Construction Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vietnam Building Construction Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vietnam Building Construction Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vietnam Building Construction Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vietnam Building Construction Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vietnam Building Construction Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vietnam Building Construction Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
