
Market Overview
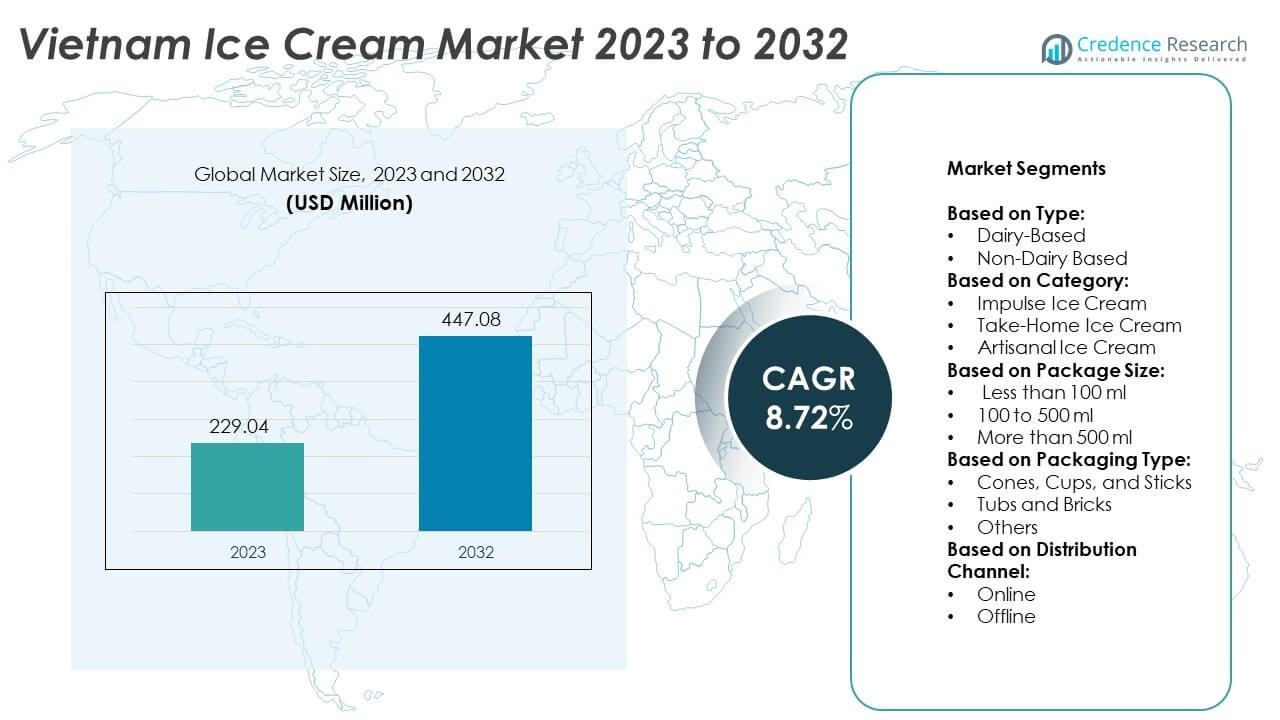
Vietnam Ice Cream Market size was valued at USD 229.04 million in 2024 and is anticipated to reach USD 447.08 million by 2032, at a CAGR of 8.72% during the forecast period.| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vietnam Ice Cream Market Size 2024 | USD 229.04 Million |
| Vietnam Ice Cream Market, CAGR | 8.72% |
| Vietnam Ice Cream Market Size 2032 | USD 447.08 Million |
Market Insights
- The Vietnam Ice Cream market was valued at USD 229.04 million in 2023 and is projected to reach USD 447.08 million by 2032, growing at a CAGR of 8.72% during the forecast period.
- Rising disposable income, urbanization, and changing lifestyles drive demand for indulgent and premium ice cream products.
- Consumers increasingly prefer diverse flavors, convenient packaging, and health-focused options such as low-sugar, plant-based, and protein-enriched variants.
- Innovation in artisanal, seasonal, and locally inspired flavors strengthens brand differentiation and encourages repeat purchases.
- Competitive intensity remains high with major players like Vinamilk, Nestlé Vietnam, Unilever Vietnam, and Lotte Confectionery Vietnam focusing on product innovation, promotions, and distribution expansion to capture market share.
- Challenges such as temperature sensitivity, high cold chain infrastructure costs, and price-sensitive consumer segments constrain rapid market growth and operational efficiency.
- Northern and Southern regions lead consumption due to urbanization, retail penetration, and tourism, while Central and rural regions provide growth potential through improved distribution, targeted products, and localized marketing campaigns.
Market Drivers
Rising Disposable Income and Changing Consumer Lifestyles Driving Vietnam Ice Cream Market Growth The Vietnam Ice Cream market benefits from increasing disposable income among urban consumers, which encourages spending on premium and indulgent food products. Consumers prioritize convenience and enjoyment, leading to higher demand for ready-to-eat ice cream products across retail and foodservice channels. It supports the introduction of diverse product ranges, including gourmet, artisanal, and seasonal flavors. Rising exposure to international brands influences consumer preferences, creating opportunities for imported and local premium ice cream. Retail expansion in supermarkets, convenience stores, and modern trade outlets strengthens accessibility and visibility. The combination of higher purchasing power and lifestyle shifts continues to drive sales across multiple urban centers in Vietnam.- For instance, Kido Group, Vietnam’s largest domestic ice cream producer, reported selling 90 million liters of ice cream in 2023, marking a significant increase in premium product consumption across urban centers.
- For instance, ShopeeFood Vietnam reported ice cream order volume surpassing 1.5 million in 2023, with peak demand during summer months. Efficient cold chain logistics ensure product quality during storage and transportation.
Market Trends
Rising Demand for Premium and Artisanal Ice Cream Driving Market Evolution The Vietnam Ice Cream market demonstrates strong growth in premium and artisanal segments due to shifting consumer preferences toward high-quality and unique offerings. Consumers increasingly seek indulgent experiences, encouraging brands to introduce gourmet flavors and creative combinations. It supports differentiation through limited-edition products, seasonal specialties, and collaborations with culinary experts. Premium packaging enhances perceived value and attracts urban consumers. Retailers highlight these products in dedicated sections to boost visibility. This trend strengthens brand positioning and encourages repeat purchases.- For instance, Unilever Vietnam sold 5 million low-sugar units of Wall’s and Magnum ice cream in the first six months, demonstrating the impact of targeted promotions and product visibility.
- For instance, TH True Milk introduced 1.2 million liters of its plant-based coconut milk ice cream, targeting lactose-intolerant and health-conscious consumers. It enables broader adoption among fitness-focused and diet-sensitive segments. Fortified products with vitamins, protein, or probiotics gain traction, offering functional benefits.
Market Challenges Analysis
High Sensitivity to Temperature Fluctuations and Supply Chain Constraints Limiting Market Expansion The Vietnam Ice Cream market faces challenges due to temperature sensitivity and reliance on robust cold chain infrastructure. Maintaining product integrity during transportation and storage requires continuous investment in refrigeration and logistics management. It increases operational costs for manufacturers, distributors, and retailers. Limited cold storage facilities in semi-urban and rural areas restrict market penetration. Seasonal demand fluctuations create pressure on inventory management and distribution efficiency. Suppliers must ensure timely delivery to avoid spoilage and product loss. These constraints hinder consistent availability and limit expansion into less-developed regions. Intense Competition and Price Sensitivity Affecting Profit Margins and Brand Positioning Competition in the Vietnam Ice Cream market remains high, with numerous local and international players offering diverse products at varying price points. It pressures companies to balance quality, innovation, and cost-effectiveness to maintain consumer loyalty. Price-sensitive segments often prioritize affordability over premium features, reducing opportunities for high-margin products. Brand differentiation requires continuous marketing investment, promotional campaigns, and product innovation. Smaller manufacturers face challenges competing with well-established brands in visibility and distribution reach. Market consolidation and aggressive pricing strategies by major players intensify competitive pressure. These factors collectively constrain profitability and strategic growth opportunities.Market Opportunities
Expansion into Untapped Rural and Emerging Urban Areas Creating Growth Potential The Vietnam Ice Cream market presents opportunities through expansion into rural and emerging urban regions where consumption remains underdeveloped. It allows manufacturers and distributors to reach new consumer bases with tailored products and affordable options. Investment in cold chain infrastructure and local partnerships can improve accessibility and maintain product quality. Introducing smaller packaging sizes and convenient formats can cater to price-sensitive and on-the-go consumers. Regional festivals and local events provide platforms for promotional campaigns and product sampling. Targeting these areas can diversify revenue streams and strengthen brand presence across the country. Introduction of Innovative Products and Health-Focused Variants Driving Consumer Engagement Innovation in flavors, formats, and health-oriented offerings continues to create opportunities in the Vietnam Ice Cream market. Companies can leverage consumer interest in premium, artisanal, and functional ice creams to differentiate their portfolios. It supports product diversification, including plant-based, low-sugar, and fortified options to attract health-conscious and younger consumers. Collaborations with local suppliers and culinary experts enable unique and culturally relevant flavors. E-commerce platforms and digital marketing campaigns can enhance visibility and drive direct-to-consumer sales. Continuous product innovation fosters brand loyalty and positions companies for long-term market growth.Market Segmentation Analysis:
By Type: The Vietnam Ice Cream market demonstrates strong demand for dairy-based products due to their rich taste, creamy texture, and widespread consumer acceptance. It drives growth in both retail and foodservice channels, particularly in urban centers. Non-dairy ice cream gains traction among health-conscious consumers, lactose-intolerant individuals, and those seeking plant-based alternatives. Manufacturers introduce options made from soy, almond, coconut, and oat milk to cater to evolving dietary preferences. Product differentiation through flavor innovation and nutritional enhancements strengthens adoption across multiple consumer segments.- For instance, Nestlé Vietnam produced 3.8 million liters of dairy-based ice cream, supplying supermarkets and convenience stores across Ho Chi Minh City and Hanoi. Non-dairy ice cream gains traction among health-conscious consumers, lactose-intolerant individuals, and those seeking plant-based alternatives
- For instance, Baskin Robbins Vietnam produced 1.9 million multi-flavor packs of 500 ml ice cream in, encouraging repeat purchases and brand loyalty. Artisanal ice cream represents a premium segment in the market, targeting consumers seeking unique flavors, natural ingredients, and gourmet experiences.
Segments:
Based on Type:- Dairy-Based
- Non-Dairy Based
- Impulse Ice Cream
- Take-Home Ice Cream
- Artisanal Ice Cream
- Less than 100 ml
- 100 to 500 ml
- More than 500 ml
- Cones, Cups, and Sticks
- Tubs and Bricks
- Others
- Online
- Offline
- Northern Vietnam
- Central Vietnam
- Southern Vietnam
- Mekong Delta and Rural Regions
Regional Analysis
Northern Vietnam Northern Vietnam holds a significant portion of the Vietnam Ice Cream market, accounting for 38% of total consumption. Urban centers such as Hanoi drive demand due to higher disposable income, exposure to international food trends, and modern retail penetration. It supports both premium and mass-market segments, with retail chains, convenience stores, and foodservice outlets contributing to distribution. Seasonal variations in temperature influence sales, with warmer months witnessing higher purchases of impulse ice cream. Manufacturers focus on localized flavors and promotions to capture consumer attention. Expansion in semi-urban areas further strengthens market penetration and brand visibility. Central Vietnam Central Vietnam accounts for 22% of the Vietnam Ice Cream market, driven by growing urbanization in cities like Da Nang and Hue. It experiences steady demand through supermarkets, local retail stores, and tourism-driven sales in coastal regions. Ice cream consumption benefits from increasing disposable income and rising preference for on-the-go and take-home products. It encourages manufacturers to diversify flavor offerings and packaging formats to appeal to varied consumer preferences. Local events, festivals, and beach tourism create opportunities for impulse purchases. Efficient cold chain infrastructure remains critical to maintain product quality across this region. Southern Vietnam Southern Vietnam represents the largest share of the Vietnam Ice Cream market at 40%, primarily due to Ho Chi Minh City and surrounding industrial hubs. It benefits from high population density, rising middle-class spending, and strong presence of modern retail and e-commerce channels. It supports premium, artisanal, and non-dairy product segments, responding to sophisticated consumer preferences. Tourism, nightlife, and recreational activities further boost seasonal and impulse consumption. Retailers emphasize promotional campaigns and limited-edition products to capture attention. Continuous investment in cold chain logistics ensures widespread availability and consistent product quality. Mekong Delta and Rural Regions The Mekong Delta and rural regions account for 10% of the Vietnam Ice Cream market, reflecting growing but still emerging demand. It focuses primarily on affordable, small-package ice cream and local flavors tailored to regional tastes. Limited cold chain infrastructure and dispersed retail channels constrain rapid market expansion. Manufacturers leverage local distributors and small retail outlets to improve access and visibility. Seasonal spikes during festivals and agricultural cycles present opportunities for temporary demand growth. Expanding distribution networks and introducing cost-effective packaging can enhance penetration in these regions.Key Player Analysis
- Nestlé Vietnam
- Baskin Robbins Vietnam
- Lotte Confectionery Vietnam
- Vinamilk
- Fanny Ice Cream
- Haagen-Dazs Vietnam
- Kido Group (KDC)
- Tràng Tiền Ice Cream
- TH True Milk
- Unilever Vietnam
Competitive Analysis
Key players in the Vietnam Ice Cream market include Nestlé Vietnam, Baskin Robbins Vietnam, Lotte Confectionery Vietnam, Vinamilk, Fanny Ice Cream, Haagen-Dazs Vietnam, Kido Group (KDC), Tràng Tiền Ice Cream, TH True Milk, and Unilever Vietnam.The market remains highly competitive, with domestic and international brands competing on product innovation, flavor diversity, and distribution reach. Companies focus on premium, artisanal, and health-oriented offerings to differentiate themselves and capture emerging consumer segments. It emphasizes quality, packaging, and seasonal promotions to drive brand loyalty. Retail and modern trade channels serve as primary platforms for visibility and sales, while e-commerce adoption strengthens direct-to-consumer engagement. Price competitiveness in mass-market segments challenges smaller players, compelling continuous marketing and product development investments.Innovation in flavors and formats remains a core strategy to attract younger and urban consumers. It leverages local tastes, limited-edition releases, and collaborations with culinary experts to sustain interest. Expansion into semi-urban and rural regions offers growth opportunities for companies with established cold chain infrastructure. The presence of established global brands intensifies competition, forcing local players to enhance operational efficiency and brand positioning. Overall, strategic differentiation, robust distribution, and targeted marketing define the competitive landscape of the Vietnam Ice Cream market.Recent Developments
- In April 2025, Vinamilk introduced a line of low-sugar and high-protein ice cream variants to address the growing health-conscious segment.
- In April 2024, Unilever’s Magnum brand introduced the Magnum Pleasure Express, a trio of mood-inspired ice cream flavors that represent a significant innovation for the brand. The three new Magnum Pleasure Express flavors are Magnum Euphoria, a lemon ice cream with a raspberry sorbet core and white chocolate shell with popping candy; Magnum Wonder, toffee-flavored ice cream with a dated core, golden chocolate, and caramelized almonds; and Magnum Chill, a vegan option with vanilla-biscuit ice cream, blueberry sorbet core, cookie pieces, and vegan chocolate couverture. The launch of these ice creams is part of a comprehensive multi-channel customer journey, supported by Magnum's award-winning advertisements and a media campaign featuring Magnum enthusiasts boarding the 'Pleasure Express' train.
- In April 2024, Cold Stone Creamery launched a limited-time offering called the Waffle Ice Cream Taco, available exclusively from April 30 to May 5, 2024, at its stores nationwide. This unique creation features Sweet Cream Ice Cream within a freshly made waffle taco shell, coated with rich chocolate and sprinkled with crunchy peanuts.
- In February 2024, Nestlé announced its 2024 range of sharing bags inspired by popular ice cream flavors. The new selection includes Aero Melts, a Neapolitan flavor, Munchies Cookie Dough Ice Cream, Raspberry Ripple, Milkybar Buttons, and ice cream-shaped Rowntree’s Randoms Foamies.
Market Concentration & Characteristics
The Vietnam Ice Cream market exhibits a moderately concentrated structure, with a mix of established domestic and international players driving competition. It is characterized by a combination of premium, artisanal, and mass-market offerings that cater to diverse consumer preferences across urban and semi-urban regions. Leading companies such as Vinamilk, Nestlé Vietnam, and Unilever Vietnam leverage strong brand recognition, extensive distribution networks, and innovative product portfolios to maintain market presence. It emphasizes differentiation through flavor innovation, health-oriented formulations, and seasonal promotions. Small and regional players focus on niche flavors and localized products to capture specific consumer segments. Retail chains, convenience stores, and e-commerce platforms serve as primary sales channels, supported by investments in cold chain infrastructure to ensure product quality. It responds to evolving consumer trends, including demand for plant-based options, low-sugar variants, and unique artisanal experiences. The market’s characteristics include high consumer engagement during festivals, summer months, and tourism seasons, creating seasonal spikes in sales. Strategic partnerships, limited-edition releases, and targeted marketing campaigns remain critical for maintaining competitive advantage. Overall, the Vietnam Ice Cream market combines brand-driven dominance with opportunities for niche innovation, reflecting a dynamic environment where quality, accessibility, and consumer-focused differentiation determine success.Report Coverage
The research report offers an in-depth analysis based on Type, Category, Package Size, Packaging Type, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook
- The Vietnam Ice Cream market will witness sustained growth driven by urbanization and changing consumer lifestyles.
- Demand for premium, artisanal, and health-focused ice cream products will increase.
- Plant-based and low-sugar ice cream options will gain wider adoption among health-conscious consumers.
- Innovation in local and seasonal flavors will continue to attract repeat purchases and brand loyalty.
- E-commerce and online delivery channels will expand market reach and convenience for consumers.
- Cold chain infrastructure development will enhance distribution efficiency across urban and semi-urban regions.
- Small and regional players will leverage niche flavors and localized products to capture specific segments.
- Retail chains and modern trade outlets will remain primary sales channels, complemented by convenience stores.
- Seasonal promotions and festival-driven campaigns will continue to boost short-term sales peaks.
- Strategic collaborations, limited-edition offerings, and targeted marketing will strengthen competitive positioning.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Disposable Income and Urbanization
Increasing disposable income and rapid urbanization in Vietnam are enabling consumers to spend more on premium and indulgent ice cream products, especially in major cities. This shift supports the growth of both mass-market and premium segments as consumers seek higher quality and more diverse offerings.
Expansion of Modern Retail and E-Commerce Channels
The proliferation of supermarkets, convenience stores, and online delivery platforms has significantly improved ice cream accessibility and visibility across urban and semi-urban regions. Enhanced cold chain infrastructure and digital engagement are making it easier for brands to reach new consumer segments and drive repeat purchases.
Innovation in Flavors and Health-Oriented Products
Manufacturers are introducing a wide variety of flavors, including locally inspired, artisanal, and seasonal options, as well as health-focused variants like low-sugar and plant-based ice creams. This innovation caters to evolving consumer preferences and dietary needs, encouraging trial and brand loyalty.
Tourism and Seasonal Promotions
Vietnam's vibrant tourism industry and frequent festivals create seasonal spikes in ice cream consumption, especially in urban and tourist-centric regions. Companies leverage these periods with targeted promotions and limited-edition products to boost short-term sales and enhance brand engagement.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Vietnam Ice Cream market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Vietnam Ice Cream Market projected to grow between 2023 and 2032?
Which Vietnam Ice Cream market segment held the largest share in 2023?
What are the primary factors fueling the growth of the Vietnam Ice Cream market?
Who are the leading companies in the Vietnam Ice Cream Market?
Which region commanded the largest share of the Vietnam Ice Cream market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Dairy-Based
- 1.2.2 Non-Dairy Based
- 1.3 By Category
- 1.3.1 Impulse Ice Cream
- 1.3.2 Take-Home Ice Cream
- 1.3.3 Artisanal Ice Cream
- 1.4 By Package Size
- 1.4.1 Less than 100 ml
- 1.4.2 100 to 500 ml
- 1.4.3 More than 500 ml
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 229.04 million → 2032: USD 447.08 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Vietnam Ice Cream Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Vietnam Ice Cream Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Vietnam Ice Cream Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Vietnam Ice Cream Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Vietnam Ice Cream Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Vietnam Ice Cream Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Vietnam Ice Cream Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Vietnam Ice Cream Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 229.04 million → 2032: USD 447.08 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Vietnam Ice Cream Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Dairy-Based
- 12.3.7.2 Non-Dairy Based
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Category - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Impulse Ice Cream
- 12.4.7.2 Take-Home Ice Cream
- 12.4.7.3 Artisanal Ice Cream
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Package Size - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Less than 100 ml
- 12.5.7.2 100 to 500 ml
- 12.5.7.3 More than 500 ml
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Vietnam Ice Cream Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Vietnam Ice Cream Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Vietnam Ice Cream Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Vinamilk
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Nestlé Vietnam
- 17.4 Unilever Vietnam
- 17.5 Lotte Confectionery Vietnam
- 17.6 Kido Group (KDC)
- 17.7 Baskin Robbins Vietnam
- 17.8 Fanny Ice Cream
- 17.9 Haagen-Dazs Vietnam
- 17.10 Tràng Tiền Ice Cream
- 17.11 TH True Milk
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

