
Vietnam Eye Care Market Overview:
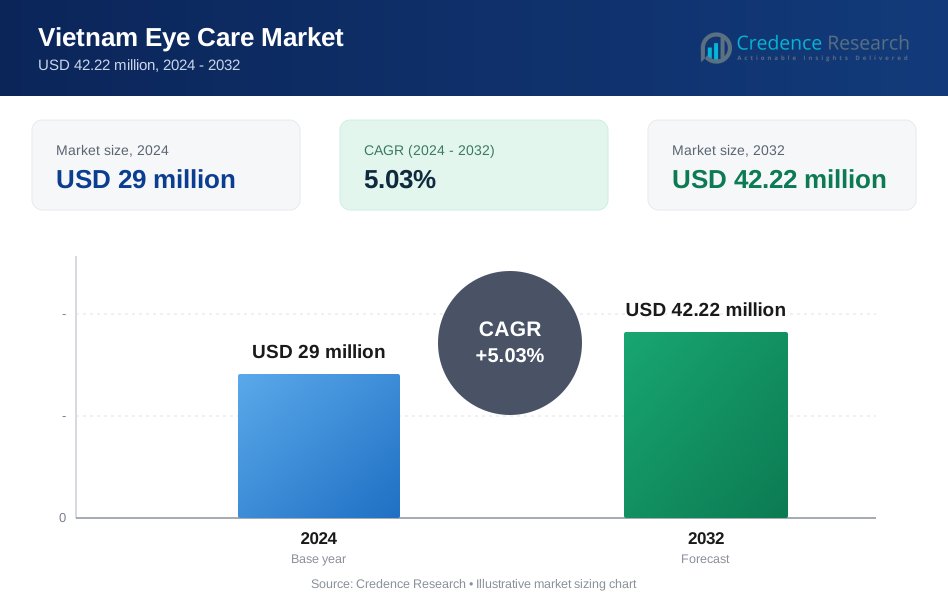
The Vietnam Eye Care Market size was valued at USD 29 million in 2024 and is anticipated to reach USD 42.22 million by 2032, growing at a CAGR of 5.03% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vietnam Eye Care Market Size 2024 | USD 29 million |
| Vietnam Eye Care Market, CAGR | 5.03% |
| Vietnam Eye Care Market Size 2032 | USD 42.22 million |
Vietnam Eye Care Market Insights
- Market growth is driven by increasing prevalence of refractive errors, cataracts, and age-related eye disorders, with eyeglasses leading the product segment at 8% share in 2024, followed by contact lenses at 32.1% and intraocular lenses at 21.1%.
- Key market trends include rising adoption of laser therapies, premium intraocular lenses, and organized optical retail expansion, while global and domestic players focus on product innovation, retail penetration, and hospital partnerships.
- Market restraints include uneven access to eye care in rural areas and high costs of advanced surgical procedures, which limit adoption of premium treatments among price-sensitive populations.
- Regionally, Southern Vietnam dominated with 44.2% share in 2024, followed by Northern Vietnam at 38.5% and Central Vietnam at 17.3%, driven by differences in healthcare infrastructure and spending patterns.

Vietnam Eye Care Market Segmentation Analysis:
By Product:
The Vietnam Eye Care Market by product is led by eyeglasses, which accounted for 46.8% market share in 2024, driven by rising myopia prevalence, increasing screen exposure, and affordability across urban and semi-urban populations. Strong demand from students and working professionals continues to support volume growth. Contact lenses held 32.1% share, supported by lifestyle preferences and cosmetic appeal among younger consumers. Intraocular lenses represented 21.1% share, benefiting from increasing cataract surgeries, an aging population, and wider adoption of advanced monofocal and multifocal lenses in specialized ophthalmic centers.
- For instance, Top Vision Eyewear in Ho Chi Minh City offers customized lenses for myopia, hyperopia, and astigmatism, along with myopia-control options like Rodenstock MyCon to enhance clarity for children with frequent squinting and blurry vision.
By Treatment:
Based on treatment, medication dominated the Vietnam Eye Care Market with a 41.6% share in 2024, supported by high prescriptions for dry eye, conjunctivitis, glaucoma, and post-operative care. Easy accessibility, recurring usage, and expanding retail pharmacy networks strengthen this segment. Surgery accounted for 34.7% share, driven by growing cataract, refractive, and retinal procedures supported by improved surgical infrastructure. Laser therapy held 23.7% share, benefiting from increasing adoption of LASIK and retinal laser treatments, particularly in private eye hospitals and premium clinics.
- For instance, Cao Thang Eye Hospital in Ho Chi Minh City, JCI-accredited since 2009, has performed over 100,000 surgeries using phacoemulsification for cataracts and advanced retinal treatments
By Distribution Channel:
By distribution channel, hospitals and clinics held the dominant position with a 52.4% market share in 2024, driven by high patient trust, availability of specialized ophthalmologists, and integrated diagnostic and surgical services. This channel benefits from rising government and private investments in eye care infrastructure. Retail stores captured 31.2% share, supported by optical chains and vision centers expanding across urban areas. Online channels accounted for 16.4% share, driven by digital adoption, price transparency, and growing demand for home delivery of eyewear and eye care products.
Key Growth Drivers
Increasing Burden of Vision Disorders
The Vietnam Eye Care Market is witnessing strong growth due to the rising incidence of vision disorders, including myopia, hyperopia, astigmatism, and age-related eye conditions. Increased screen exposure, urban lifestyles, and academic pressure among children and young adults are accelerating refractive error cases. An expanding elderly population is further increasing the prevalence of cataracts, glaucoma, and diabetic retinopathy. Growing awareness of routine eye check-ups and early diagnosis is encouraging timely treatment adoption, driving sustained demand for corrective eyewear, medications, and surgical interventions across Vietnam.
- For instance, Vinmec Times City Hospital and Alina International Eye Hospital launched a Myopia Control Unit in October 2025 in Hanoi, supported by The Fred Hollows Foundation, TVM Capital Healthcare, and Rohto Group.
Expansion of Eye Care Infrastructure
The continuous expansion of eye care infrastructure is a major driver of the Vietnam Eye Care Market. Investments in public hospitals, private eye clinics, and specialty ophthalmology centers are improving access to diagnostic and treatment services. The increasing availability of trained ophthalmologists and optometrists is strengthening service quality nationwide. Modern diagnostic tools and advanced surgical equipment are enhancing treatment outcomes. Government-led programs focused on vision screening and blindness prevention are further supporting infrastructure development and long-term market growth.
- For instance, Japan International Eye Hospital in Hanoi, established by Paris Miki Holdings, equipped facilities with Carl Zeiss Mel 90 and VisuMax lasers for refractive surgery plus Catalys for cataracts, treating about 70,000 patients and performing 30,000 surgeries to date.
Rising Healthcare Spending and Awareness
Rising healthcare spending and improving consumer awareness are contributing significantly to the Vietnam Eye Care Market growth. Higher disposable incomes are enabling greater spending on preventive eye care, premium eyewear, and advanced treatment options. Awareness campaigns conducted by healthcare providers and educational institutions are promoting early vision correction. Increasing insurance coverage and employer-sponsored healthcare benefits are improving affordability, encouraging wider adoption of professional eye care services across urban and semi-urban populations.
Key Trends & Opportunities
Advancements in Ophthalmic Technologies
Technological innovation is creating strong growth opportunities in the Vietnam Eye Care Market. Advancements in laser-based vision correction, minimally invasive cataract surgery, and premium intraocular lenses are improving clinical outcomes and patient satisfaction. Digital eye testing, AI-assisted diagnostics, and advanced imaging systems are enabling early disease detection and personalized treatment planning. The growing availability of these technologies in private hospitals and specialty clinics is supporting the expansion of high-value ophthalmic services and enhancing overall market competitiveness.
- For instance, DND International Eye Hospital in Hanoi introduced SMILE Pro using the Zeiss VisuMax 800 femtosecond laser, a flapless procedure with a 2–2.5 mm incision that corrects myopia up to -10.00 diopters and astigmatism up to -5.00 diopters in just 10 seconds per eye.
Expansion of Organized Optical Retail and Online Channels
The rapid expansion of organized optical retail chains and online platforms is reshaping the Vietnam Eye Care Market. Modern vision centers are improving access to professional eye examinations and branded eyewear products. E-commerce platforms offer convenience, competitive pricing, and broader product selection, driving higher consumer engagement. Virtual try-on tools and digital marketing strategies are enhancing customer experience. This trend presents opportunities for manufacturers and retailers to strengthen brand visibility and adopt omnichannel distribution strategies.
- For instance, Orbis International, partnering with NIDEK, deployed AI-led screenings using Cybersight AI and six fundus cameras across six Vietnamese health facilities, screening 14,463 diabetic patients by August 2025 and identifying 3,582 (24.8%) with referable retinopathy or other abnormalities.
Key Challenges
Uneven Access to Eye Care Services
Uneven access to eye care services remains a critical challenge for the Vietnam Eye Care Market. Rural and remote areas face shortages of trained ophthalmologists, optometrists, and specialized treatment facilities. Limited awareness and delayed diagnosis contribute to preventable vision impairment. Infrastructure gaps and travel constraints further restrict access to timely care. Addressing these disparities requires increased investment in mobile eye clinics, tele-ophthalmology solutions, and nationwide awareness initiatives to improve service reach and equity.
High Cost of Advanced Eye Care Treatments
The high cost of advanced eye care treatments presents a significant barrier to market growth in Vietnam. Premium intraocular lenses, laser surgeries, and advanced diagnostic equipment remain financially inaccessible for a large segment of the population. Limited insurance reimbursement for specialized procedures further restricts adoption. Healthcare providers also face challenges related to equipment investment and skilled workforce retention. These cost-related constraints may slow the penetration of innovative technologies and limit market expansion among price-sensitive consumers.
Regional Analysis
Northern Vietnam
Northern Vietnam accounted for 38.5% of the Vietnam Eye Care Market in 2024, supported by the high concentration of population in Hanoi and surrounding provinces. Strong demand for vision correction solutions is driven by rising screen usage, academic pressure, and growing awareness of routine eye examinations. The region benefits from well-established public hospitals, private eye clinics, and access to trained ophthalmologists. Increasing cases of refractive errors among children and age-related eye disorders among older adults are driving demand for eyeglasses, medications, and surgical treatments. Government-led screening programs further strengthen regional market performance.
Southern Vietnam
Southern Vietnam dominated the Vietnam Eye Care Market with a 44.2% market share in 2024, driven by advanced healthcare infrastructure and higher healthcare spending in Ho Chi Minh City and nearby urban centers. The region shows strong adoption of premium eyewear, contact lenses, and advanced surgical procedures due to higher disposable income levels. Private hospitals and specialty eye care centers play a significant role in expanding access to laser therapies and cataract surgeries. Growing lifestyle-related vision problems and increasing medical tourism also contribute to sustained demand, positioning Southern Vietnam as the leading regional contributor.
Central Vietnam
Central Vietnam held a 17.3% share of the Vietnam Eye Care Market in 2024, supported by gradual improvements in healthcare access and expanding ophthalmic services in cities such as Da Nang and Hue. Demand is driven by rising awareness of vision health and increasing availability of optical retail outlets and regional hospitals. While rural areas still face access limitations, ongoing investments in healthcare infrastructure and outreach programs are improving diagnosis and treatment rates. Growth in this region is supported by government initiatives, expanding private clinics, and increasing adoption of corrective eyewear and essential eye care medications.
Vietnam Eye Care Market Segmentations:
By Product
- Eyeglasses
- Contact Lenses
- Intraocular Lens
By Treatment
- Laser Therapy
- Medication
- Surgery
By Distribution Channel
- Hospitals and Clinics
- Retail Stores
- Online
By Geography
- Northern Vietnam
- Southern Vietnam
- Central Vietnam
Competitive Landscape
Competitive landscape analysis of the Vietnam Eye Care Market is shaped by the presence of key players such as EssilorLuxottica, HOYA Corporation, Johnson & Johnson Vision, Alcon, Bausch + Lomb, Zeiss Group, CooperVision, and local optical chains including Mat Kinh Ha Noi and Mat Kinh Sai Gon. The market remains moderately fragmented, with multinational companies leveraging strong product portfolios, advanced lens technologies, and established distribution networks, while domestic players compete through localized pricing and retail expansion. Strategic focus centers on product innovation, brand differentiation, and partnerships with hospitals and optical retailers. Companies are strengthening their footprint through investments in modern vision centers, professional training programs, and digital engagement platforms. Increasing competition is also evident in premium lenses, contact lenses, and surgical solutions, supported by rising consumer awareness and demand for high-quality eye care services across Vietnam.
Key Player Analysis
- Hoan My Medical Corporation
- DND International Co., Ltd. (DND Eyes)
- Saigon Eye Hospital
- American Eye Center, Vietnam
- Alcon (Novartis)
- Bausch & Lomb
- Carl Zeiss AG
- Essilor
- Johnson & Johnson Vision Care
- Hoya Corporation
Recent Developments
- In November 2025, Medical Saigon Group, Topcon Healthcare, and DKSH Vietnam signed a strategic partnership to deploy advanced ophthalmic diagnostic and treatment technology across Vietnam, enhancing eye care standards nationwide.
- In October 2025, DKSH, Topcon Healthcare, and Medical Saigon Group formalized their collaboration to prioritize Topcon's integrated eye care technology ecosystem in Vietnam's private clinics, supported by training and maintenance services.
- In October 2025, Vinmec Times City Hospital and Alina International Eye Hospital launched the Vinmec-Alina International Myopia Control Unit to provide comprehensive myopia prevention and treatment services for children using advanced diagnostic and therapeutic solutions.
Report Coverage
The research report offers an in-depth analysis based on Product, Treatment, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Vietnam Eye Care Market will continue to expand steadily, supported by rising demand for vision correction and preventive eye care services.
- Increasing prevalence of refractive errors among children and working-age adults will sustain long-term product and service adoption.
- Growth in the aging population will drive higher demand for cataract treatment, glaucoma management, and chronic eye disease care.
- Advanced diagnostic technologies and minimally invasive surgical procedures will gain wider acceptance across hospitals and specialty clinics.
- Organized optical retail chains will expand further, improving access to professional eye examinations and branded eyewear.
- Digital eye testing, tele-ophthalmology, and online eyewear sales will strengthen market reach and consumer convenience.
- Private healthcare investment will accelerate the adoption of premium lenses, laser therapies, and advanced intraocular solutions.
- Government-led vision screening and blindness prevention programs will support early diagnosis and treatment uptake.
- Increasing health awareness and insurance coverage will improve affordability and utilization of eye care services.
- Competitive intensity will rise as global and domestic players focus on innovation, retail expansion, and service differentiation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Vietnam Eye Care Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Vietnam Eye Care Market projected to grow between 2024 and 2032?
Which Vietnam Eye Care Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Vietnam Eye Care Market?
Who are the leading companies in the Vietnam Eye Care Market?
Which region commanded the largest share of the Vietnam Eye Care Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vietnam Eye Care Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vietnam Eye Care Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 29 million → 2032: USD 42.22 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vietnam Eye Care Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vietnam Eye Care Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vietnam Eye Care Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vietnam Eye Care Market Drivers
- 3.3 Vietnam Eye Care Market Restraints & Challenges
- 3.4 Vietnam Eye Care Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vietnam Eye Care Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vietnam Eye Care Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vietnam Eye Care category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vietnam Eye Care Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vietnam Eye Care Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vietnam Eye Care market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vietnam Eye Care Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vietnam Eye Care Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vietnam Eye Care Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vietnam Eye Care (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vietnam Eye Care Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vietnam Eye Care Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vietnam Eye Care Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vietnam Eye Care Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vietnam Eye Care Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vietnam Eye Care Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vietnam Eye Care Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vietnam Eye Care Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vietnam Eye Care Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
