
Vietnam Oral Solid Dosage Contract Manufacturing Market Overview:
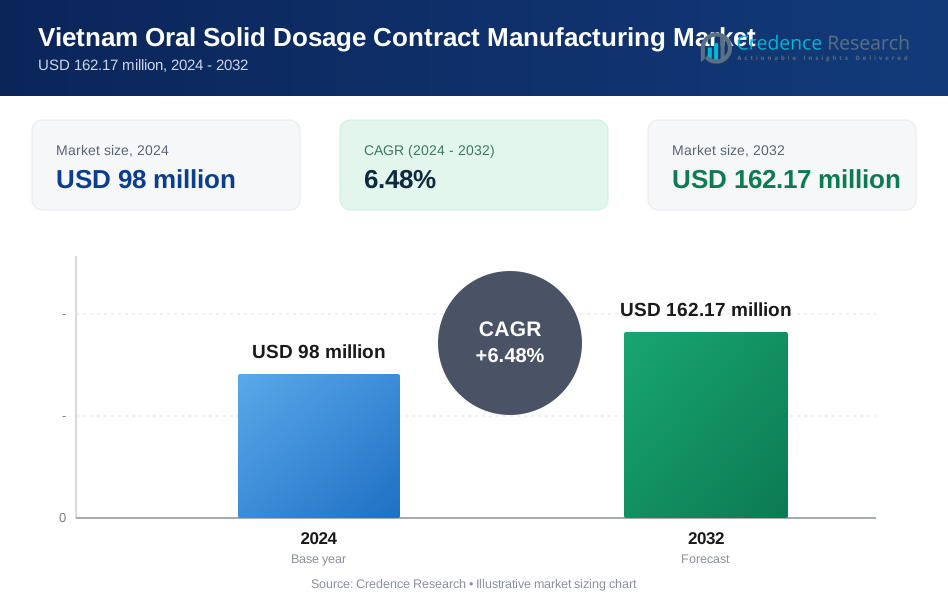
The Vietnam Oral Solid Dosage Contract Manufacturing Market size was valued at USD 98 million in 2024 and is anticipated to reach USD 162.17 million by 2032, growing at a CAGR of 6.48% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vietnam Oral Solid Dosage Contract Manufacturing Market Size 2024 | USD 98 million |
| Vietnam Oral Solid Dosage Contract Manufacturing Market, CAGR | 6.48% |
| Vietnam Oral Solid Dosage Contract Manufacturing Market Size 2032 | USD 162.17million |
Vietnam Oral Solid Dosage Contract Manufacturing Market Insights
- Rising outsourcing by domestic and export-oriented pharma firms accelerates demand for high-volume tablet and capsule manufacturing, led by tablets with 46.3% segment share in 2024.
- Immediate-release formulations dominate with 52.8% share in 2024, while controlled-release at 31.2% gains momentum as manufacturers expand modified-release capabilities for chronic therapies.
- Leading players including DHG Pharma, Traphaco, Hau Giang, Imexpharm, and Pymepharco strengthen scale through GMP compliance, capacity upgrades, and cost-efficient production amid pricing pressure and higher QA requirements.
- Southern Vietnam leads with 41.2% regional share in 2024, followed by Northern Vietnam at 34.6% and Central Vietnam at 24.2%, supported by export logistics, regulatory proximity, and expanding industrial zones.

Vietnam Oral Solid Dosage Contract Manufacturing Market Segmentation Analysis:
By Type:
The Vietnam Oral Solid Dosage Contract Manufacturing Market by type is led by tablets, which accounted for 46.3% market share in 2024, driven by high prescription volumes, ease of large-scale manufacturing, and strong demand for chronic disease therapies. Tablets remain the preferred format for cardiovascular, anti-diabetic, and analgesic drugs due to dose accuracy, stability, and cost efficiency. Capsules held 28.6% share, supported by nutraceutical and specialty drug demand, while powders and granules together represented 17.4%, primarily for pediatric and geriatric formulations. Advanced coating and compression capabilities continue to reinforce tablet dominance.
- For instance, Stellapharm installed Vietnam's first contained integrated granulation line with two MODUL P rotary tablet presses at its Binh Duong facility for producing steroid/hormonal tablets used in chronic therapies.
By Mechanism:
By mechanism, immediate-release formulations dominated with a 52.8% share in 2024, supported by widespread use in acute therapies, faster regulatory approvals, and lower production complexity. Immediate-release products are extensively outsourced by domestic pharmaceutical firms to optimize cost and capacity utilization. Controlled-release formulations captured 31.2% share, driven by rising demand for sustained therapeutic effects in chronic treatments such as hypertension and diabetes. Delayed-release products accounted for 16.0%, benefiting from increasing gastrointestinal and targeted drug delivery applications. Growing investments in formulation expertise continue to support mechanism-based diversification.
- For instance, EUDRAGIT® L 30 D-55 polymers protect acid-sensitive APIs like proton pump inhibitors during gastric transit before releasing in the small intestine.
By End-user:
Based on end-user, large-size pharmaceutical companies held the dominant share of 58.7% in 2024, driven by high-volume outsourcing, strong export orientation, and compliance with international manufacturing standards. These companies leverage contract manufacturing to scale production while focusing on R&D and brand development. Medium- and small-size companies accounted for 32.9%, supported by increasing domestic drug registrations and cost-driven outsourcing strategies. The remaining 8.4% share was held by other entities, including nutraceutical and specialty healthcare firms, reflecting the expanding scope of oral solid dosage contract manufacturing services in Vietnam.
Key Growth Drivers
Rising Outsourcing by Domestic and Export-Oriented Pharmaceutical Companies
The Vietnam Oral Solid Dosage Contract Manufacturing Market is experiencing strong growth due to increasing outsourcing by both domestic and export-focused pharmaceutical companies. Rising pressure to reduce capital expenditure, optimize operational efficiency, and accelerate time-to-market is encouraging manufacturers to rely on specialized contract partners. Local pharmaceutical firms increasingly outsource tablet and capsule production to scale volumes without expanding in-house facilities. At the same time, export-oriented companies leverage Vietnamese CMOs to meet regional demand across Southeast Asia, benefiting from competitive manufacturing costs, skilled labor availability, and improving compliance with international quality standards.
- For instance, Ha Tay Pharmaceutical Joint Stock Company offers contract manufacturing services for tablets and capsules to domestic partners like Kim Long Investment Joint Stock Company and Dong Au Pharmaceutical Joint Stock Company, leveraging its PIC/S GMP-compliant facilities to enable scaled production without client facility expansions.
Expanding Chronic Disease Burden and Solid Dosage Demand
The growing prevalence of chronic diseases such as cardiovascular disorders, diabetes, and respiratory conditions is significantly driving demand for oral solid dosage forms in Vietnam. Tablets and capsules remain the preferred formats for long-term therapies due to their stability, dosing accuracy, and patient convenience. This sustained demand is encouraging pharmaceutical companies to expand product portfolios while outsourcing manufacturing to contract partners with high-capacity compression, coating, and formulation capabilities. As chronic disease management expands across urban and aging populations, contract manufacturers are witnessing steady volume growth and longer-term supply agreements.
- For instance, STADA Pymepharco supplies generics like tablets and capsules for chronic respiratory, cardiovascular, and diabetes care through partnerships such as with Pharmacity, focusing on affordable dose-reduced combokits to boost patient compliance.
Strengthening Regulatory Framework and Manufacturing Infrastructure
Vietnam’s strengthening pharmaceutical regulatory framework is playing a critical role in market expansion by enhancing confidence in local contract manufacturing services. Continuous improvements in Good Manufacturing Practice compliance, quality control systems, and inspection transparency are enabling contract manufacturers to attract multinational and regional clients. Government support for pharmaceutical self-sufficiency and export readiness is also accelerating investments in modern production lines and analytical laboratories. These improvements reduce regulatory risks for outsourcing companies while positioning Vietnam as a reliable manufacturing hub for oral solid dosage products across Southeast Asia.
Key Trends & Opportunities
Growing Demand for Modified-Release and Value-Added Formulations
The Vietnam Oral Solid Dosage Contract Manufacturing Market is witnessing a shift toward modified-release and value-added formulations, creating new growth opportunities for contract manufacturers. Pharmaceutical companies increasingly seek partners capable of producing controlled-release, delayed-release, and multi-layer tablets to differentiate products and improve patient adherence. This trend is driven by rising chronic disease treatments and the need for extended therapeutic efficacy. Contract manufacturers investing in advanced formulation technologies, specialized excipients, and process optimization are well positioned to secure long-term partnerships and higher-margin projects within both domestic and export markets.
- For instance, Traphaco partnered with Daewoong Pharmaceutical for technology transfer of advanced dosage forms, initiating phase 2 manufacturing at its Hung Yen facility with support from four Korean experts.
Expansion of Export-Oriented Contract Manufacturing Services
Export-oriented manufacturing is emerging as a major opportunity as Vietnamese contract manufacturers expand their presence beyond domestic markets. Companies are increasingly targeting regulated and semi-regulated markets in Southeast Asia, the Middle East, and Africa by aligning production with international quality and documentation requirements. Competitive production costs, favorable trade policies, and improving regulatory recognition are enabling contract manufacturers to attract overseas pharmaceutical clients. This trend is encouraging investments in capacity expansion, serialization, and packaging upgrades, positioning Vietnam as a strategic regional hub for oral solid dosage contract manufacturing.
- For instance, RV Group acquired OPV Pharmaceuticals in Bien Hoa Industrial Estate, enhancing its general-purpose oral solid dosage capabilities for ASEAN growth. It further expanded by acquiring BRV Pharma in Cu Chi Industrial Estate, focusing on oral solid dosage, oral liquids, and oncology orals to support export strategies.
Key Challenges
Regulatory Compliance and Quality Consistency Pressure
Maintaining consistent regulatory compliance remains a key challenge for the Vietnam Oral Solid Dosage Contract Manufacturing Market. Contract manufacturers must continuously meet evolving domestic and international regulatory expectations, including documentation accuracy, validation requirements, and audit readiness. Smaller manufacturers often face challenges in upgrading facilities, training personnel, and maintaining robust quality management systems. Any lapses in compliance can impact client trust and limit access to export markets. The growing scrutiny from regulatory authorities increases operational complexity and cost, particularly for manufacturers aiming to serve multinational pharmaceutical clients.
Intense Pricing Competition and Margin Constraints
Intense pricing competition presents a significant challenge as numerous contract manufacturers compete for similar outsourcing projects. Pharmaceutical companies exert strong pricing pressure to minimize production costs, which can compress margins for contract manufacturers. Rising input costs, including raw materials, energy, and labor, further strain profitability. Smaller and mid-sized manufacturers face difficulties balancing competitive pricing with investments in technology, compliance, and capacity expansion. Sustained margin pressure may limit innovation and slow modernization efforts, impacting long-term competitiveness in the Vietnam Oral Solid Dosage Contract Manufacturing Market.
Regional Analysis
Northern Vietnam
Northern Vietnam accounted for 34.6% market share in 2024 in the Vietnam Oral Solid Dosage Contract Manufacturing Market, supported by the presence of major pharmaceutical manufacturing hubs around Hanoi and neighboring provinces. The region benefits from strong regulatory oversight, proximity to government agencies, and a high concentration of GMP-certified facilities. Contract manufacturers in Northern Vietnam actively serve domestic pharmaceutical companies and public healthcare supply chains, particularly for tablets and immediate-release formulations. Growing investments in formulation development, quality testing infrastructure, and workforce training continue to strengthen the region’s position in high-volume and compliance-driven contract manufacturing activities.
Southern Vietnam
Southern Vietnam dominated the Vietnam Oral Solid Dosage Contract Manufacturing Market with a 41.2% share in 2024, driven by its advanced industrial ecosystem and export-oriented pharmaceutical clusters in Ho Chi Minh City and surrounding provinces. The region hosts a large number of established contract manufacturers with high-capacity production lines and international quality certifications. Strong logistics connectivity, access to ports, and proximity to key pharmaceutical clients support large-scale outsourcing contracts. Southern Vietnam also leads in capsule and controlled-release manufacturing, supported by continuous investments in automation, packaging capabilities, and export-focused compliance standards.
Central Vietnam
Central Vietnam held a 24.2% market share in 2024, reflecting its growing role as an emerging manufacturing base in the Vietnam Oral Solid Dosage Contract Manufacturing Market. The region benefits from lower operating costs, expanding industrial zones, and increasing government support for pharmaceutical manufacturing decentralization. Contract manufacturers in Central Vietnam primarily serve medium- and small-size pharmaceutical companies, focusing on tablets, powders, and granules. Infrastructure development, improved transportation networks, and rising investments in GMP-compliant facilities are steadily enhancing the region’s manufacturing capabilities and its attractiveness for cost-efficient outsourcing projects.
Vietnam Oral Solid Dosage Contract Manufacturing Market Segmentations:
By Type
- Tablets
- Capsules
- Powders
- Granules
- Others (Lozenges, Gummies, Pastilles, etc.)
By Mechanism
- Immediate-release
- Delayed-release
- Controlled-release
By End-user
- Large-size Companies
- Medium- & Small-size Companies
- Others
By Geography
- Northern Vietnam
- Southern Vietnam
- Central Vietnam
Competitive Landscape
The Vietnam Oral Solid Dosage Contract Manufacturing Market features a moderately consolidated structure, supported by the presence of established domestic pharmaceutical manufacturers with expanding contract manufacturing capabilities, including DHG Pharmaceutical Joint Stock Company, Traphaco Joint Stock Company, Hau Giang Pharmaceutical, Imexpharm Corporation, Pymepharco, OPV Pharmaceutical, Mekophar Chemical Pharmaceutical, Vietnam Pharmaceutical Corporation (Vinapharm), Vimedimex Medi-Pharma, and Everpia JSC. Market participants focus on capacity expansion, GMP compliance, and formulation expertise to strengthen outsourcing partnerships. Leading players invest in high-speed tablet compression, capsule filling, and coating technologies to support large-volume and export-oriented contracts. Strategic collaborations with regional pharmaceutical firms, investments in quality systems, and portfolio diversification across immediate- and modified-release formulations enhance competitiveness. Increasing emphasis on regulatory readiness, cost efficiency, and scalable production positions Vietnamese manufacturers as preferred partners for domestic and Southeast Asian pharmaceutical outsourcing.
Key Player Analysis
- Imexpharm Corporation
- OPV Pharmaceutical
- Everpia JSC
- Hau Giang Pharmaceutical
- Vimedimex Medi-Pharma
- Traphaco Joint Stock Company
- Pymepharco
- DHG Pharmaceutical Joint Stock Company
- Mekophar Chemical Pharmaceutical
- Vietnam Pharmaceutical Corporation (Vinapharm)
Recent Developments
- In May 2025, Imexpharm Pharmaceutical JSC announced plans to build a $58 million high-tech pharmaceutical plant in Dong Thap province, featuring EU-GMP production lines for advanced oral solid dosage forms to support contract manufacturing expansion.
- In March 2025, Davipharm outlined plans to develop 12 new SKUs annually for international markets, expanding its oral solid dosage production alongside a new warehouse and quality control lab.
Report Coverage
The research report offers an in-depth analysis based on Type, Mechanism, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Vietnam Oral Solid Dosage Contract Manufacturing Market will continue expanding due to rising outsourcing by domestic and regional pharmaceutical companies.
- Increasing demand for tablets and capsules used in chronic disease management will support long-term volume growth.
- Contract manufacturers will invest in advanced formulation technologies to support controlled- and delayed-release products.
- Strengthening regulatory compliance will improve access to regional and international export markets.
- Capacity expansion and automation will enhance production efficiency and consistency.
- Export-oriented manufacturing will gain traction across Southeast Asia, the Middle East, and Africa.
- Medium- and small-size pharmaceutical companies will increasingly rely on contract partners to optimize costs.
- Growing focus on quality assurance and documentation will strengthen client trust and long-term contracts.
- Strategic partnerships with regional pharmaceutical firms will support portfolio diversification.
- Continued government support for pharmaceutical manufacturing will reinforce Vietnam’s position as a regional outsourcing hub.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Vietnam Oral Solid Dosage Contract Manufacturing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Vietnam Oral Solid Dosage Contract Manufacturing Market projected to grow between 2024 and 2032?
Which Vietnam Oral Solid Dosage Contract Manufacturing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Vietnam Oral Solid Dosage Contract Manufacturing Market?
Who are the leading companies in the Vietnam Oral Solid Dosage Contract Manufacturing Market?
Which region commanded the largest share of the Vietnam Oral Solid Dosage Contract Manufacturing Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vietnam Oral Solid Dosage Contract Manufacturing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vietnam Oral Solid Dosage Contract Manufacturing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 98 million → 2032: USD 162.17 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vietnam Oral Solid Dosage Contract Manufacturing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vietnam Oral Solid Dosage Contract Manufacturing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vietnam Oral Solid Dosage Contract Manufacturing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vietnam Oral Solid Dosage Contract Manufacturing Market Drivers
- 3.3 Vietnam Oral Solid Dosage Contract Manufacturing Market Restraints & Challenges
- 3.4 Vietnam Oral Solid Dosage Contract Manufacturing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vietnam Oral Solid Dosage Contract Manufacturing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vietnam Oral Solid Dosage Contract Manufacturing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vietnam Oral Solid Dosage Contract Manufacturing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vietnam Oral Solid Dosage Contract Manufacturing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vietnam Oral Solid Dosage Contract Manufacturing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vietnam Oral Solid Dosage Contract Manufacturing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vietnam Oral Solid Dosage Contract Manufacturing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vietnam Oral Solid Dosage Contract Manufacturing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vietnam Oral Solid Dosage Contract Manufacturing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vietnam Oral Solid Dosage Contract Manufacturing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vietnam Oral Solid Dosage Contract Manufacturing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vietnam Oral Solid Dosage Contract Manufacturing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vietnam Oral Solid Dosage Contract Manufacturing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vietnam Oral Solid Dosage Contract Manufacturing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vietnam Oral Solid Dosage Contract Manufacturing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vietnam Oral Solid Dosage Contract Manufacturing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vietnam Oral Solid Dosage Contract Manufacturing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vietnam Oral Solid Dosage Contract Manufacturing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vietnam Oral Solid Dosage Contract Manufacturing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
