
Market Overview:
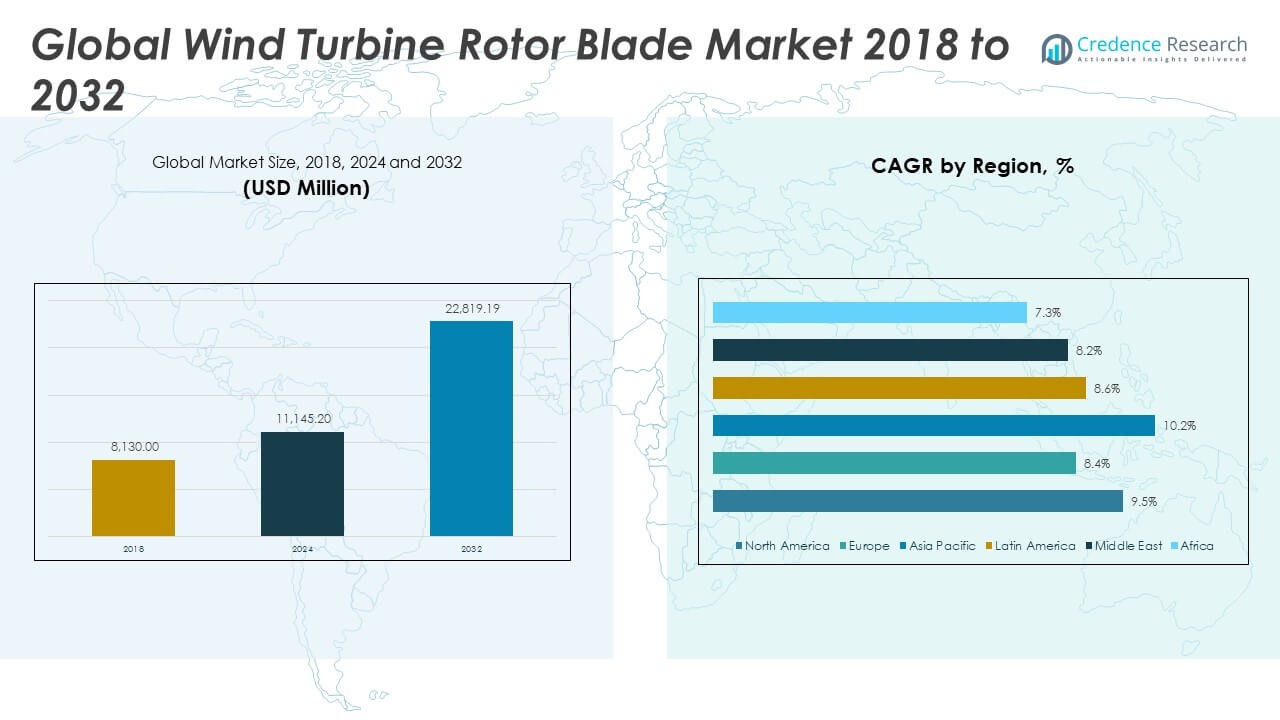
The Wind Turbine Rotor Blade Market size was valued at USD 8,130.00 million in 2018 to USD 11,145.20 million in 2024 and is anticipated to reach USD 22,819.19 million by 2032, at a CAGR of 9.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wind Turbine Rotor Blade Market Size 2024 | USD 11,145.20 Million |
| Wind Turbine Rotor Blade Market, CAGR | 9.45% |
| Wind Turbine Rotor Blade Market Size 2032 | USD 22,819.19 Million |
The market is experiencing significant growth due to increasing global investments in renewable energy, coupled with supportive government initiatives aimed at reducing carbon emissions. Rising demand for wind power as a sustainable energy source is accelerating the adoption of both onshore and offshore wind turbines, which, in turn, is driving rotor blade installations. Continuous innovations in blade materials and designs are enhancing efficiency, leading to higher energy output per turbine and fostering market expansion.
Geographically, Europe and Asia-Pacific dominate the Wind Turbine Rotor Blade Market due to their strong wind power infrastructure and ambitious renewable targets. Countries like China, Germany, and India are key contributors owing to high wind energy capacities and consistent policy support. North America is also witnessing steady growth, driven by wind energy integration in the U.S. Emerging markets in Latin America and Africa are gaining momentum as governments pursue cleaner energy pathways and improve grid connectivity to support wind installations.
Market Insights:
- The Wind Turbine Rotor Blade Market was valued at USD 11,145.20 million in 2024 and is projected to reach USD 22,819.19 million by 2032, growing at a CAGR of 9.45%.
- Rising global focus on renewable energy and decarbonization is driving sustained demand for rotor blade installations.
- Government incentives, such as tax credits and renewable energy targets, are supporting wind energy expansion across multiple regions.
- High transportation and logistics costs for large blades remain a major restraint, especially in remote or offshore installations.
- Asia Pacific holds the largest market share due to significant investments and manufacturing capacities in China and India.
- Europe leads in offshore deployments and recyclable blade innovations, supported by advanced R&D infrastructure.
- Emerging markets in Latin America and Africa show potential for growth with improving energy access and policy support.
Market Drivers:
Surging Global Demand for Renewable Energy is Accelerating Rotor Blade Deployment
Global emphasis on decarbonization is driving large-scale investments in renewable power generation. Wind energy, being cost-competitive and scalable, is gaining traction among utilities and governments. The Wind Turbine Rotor Blade Market is benefiting directly from this shift, with increased demand for both onshore and offshore wind installations. Utility-scale wind farms are expanding rapidly across developed and developing economies. Grid parity achievements in key regions are making wind power more viable without subsidies. Rotor blade manufacturers are scaling production capacities to meet surging turbine orders. National targets and climate commitments are creating stable demand pipelines for wind infrastructure. This structural energy transition supports long-term growth in rotor blade installations.
- For instance, Vestas manufactured the V236-15.0 MW offshore turbine, which is equipped with 115.5-meter rotor blades and achieves a capacity factor exceeding 60%, illustrating how manufacturers are deploying longer and more efficient rotor blades to meet escalating project demands.
Government Incentives and Policy Support Are Strengthening Market Foundations
Incentive mechanisms such as tax credits, green energy mandates, and renewable portfolio standards are reinforcing wind power investments. The Wind Turbine Rotor Blade Market is seeing benefits from policy-led momentum across regions like the EU, U.S., and China. Governments are simplifying permitting processes and enhancing grid integration frameworks. Procurement auctions are helping drive down project costs while increasing installation volumes. Local manufacturing mandates are encouraging blade production within national borders. R&D grants and subsidies are pushing innovation in lightweight blade materials and extended-length designs. These strategic interventions are enabling rapid expansion of the wind sector. Policy continuity and regulatory clarity remain key catalysts for rotor blade market growth.
- For instance, Siemens Gamesa’s B81 RecyclableBlades-measuring 81 meters-were first commercially installed at RWE’s Kaskasi offshore wind project in Germany, where 38 SG 8.0-167 DD turbines will collectively supply up to 400,000 households, a deployment made possible by favorable regulatory frameworks and government support for sustainable, innovative solutions.
Advancements in Blade Design and Composite Materials Are Improving Efficiency
Technological innovation is transforming rotor blade performance, enabling higher energy capture and lower lifecycle costs. The Wind Turbine Rotor Blade Market is evolving with breakthroughs in aerodynamic profiles, longer blade spans, and modular production techniques. Next-generation materials such as carbon fiber-reinforced polymers are improving strength-to-weight ratios. Smart blades with embedded sensors are enabling real-time condition monitoring and predictive maintenance. These innovations enhance turbine capacity factors and extend operational life. OEMs are investing in R&D partnerships with research institutes and universities. Blade transportation and logistics technologies are also being optimized for larger blades. These advancements create a strong foundation for cost-efficient energy generation.
Offshore Wind Expansion Is Creating Significant Growth Avenues
Global offshore wind deployment is rising rapidly due to high-capacity potential and steady wind speeds. The Wind Turbine Rotor Blade Market is witnessing new demand from offshore turbine projects that require longer, robust blades. Countries like the UK, Germany, and China are investing in large-scale offshore wind parks. Blades for offshore applications must endure harsher marine conditions, pushing demand for corrosion-resistant materials and advanced structural designs. Floating wind technologies are expanding market boundaries to deepwater locations. OEMs are customizing blade configurations for offshore-specific turbine classes. Port infrastructure upgrades and specialized vessels are facilitating offshore blade logistics. This segment is emerging as a high-growth area with distinct technical requirements.
Market Trends
Shift Toward Recyclable and Sustainable Blade Materials Is Gaining Ground
Sustainability concerns are pushing manufacturers to adopt recyclable materials and reduce environmental impact. The Wind Turbine Rotor Blade Market is seeing a trend toward using thermoplastics and bio-based composites in blade manufacturing. OEMs are exploring circular economy models to reclaim and reuse blade components at end-of-life. Lifecycle assessments and eco-label certifications are influencing procurement preferences. Industry collaborations aim to standardize sustainable blade material formulations. Pilot projects are underway to test fully recyclable rotor blades under real-world conditions. Sustainability is becoming a core design parameter, not just a regulatory requirement. This trend is expected to reshape material supply chains in the rotor blade segment.
Digital Twin and Predictive Maintenance Integration in Blade Design
Adoption of digital technologies is redefining how rotor blades are designed, monitored, and maintained. The Wind Turbine Rotor Blade Market is incorporating digital twin solutions that simulate blade performance under diverse conditions. These virtual models help identify design flaws before physical prototyping. Embedded sensors in blades are enabling continuous data collection on load, vibration, and temperature. Predictive maintenance algorithms use this data to forecast potential failures and schedule timely interventions. Digital integration supports cost savings and reduces unplanned downtimes. OEMs are leveraging these insights to refine future blade designs. The convergence of mechanical engineering and data science is becoming a new industry norm.
Regionalization of Manufacturing to Reduce Supply Chain Risks
Supply chain disruptions and geopolitical tensions are driving regional blade production strategies. The Wind Turbine Rotor Blade Market is experiencing a localization trend as countries aim to reduce import dependency. Manufacturers are setting up new facilities closer to demand hubs to cut transportation costs and avoid tariffs. Governments are offering land, tax incentives, and infrastructure support to attract rotor blade factories. Localized production ensures compliance with domestic content rules in procurement auctions. It also enables faster delivery timelines for project developers. This regionalization trend is strengthening supply chain resilience and creating new manufacturing jobs. Blade producers are recalibrating logistics and sourcing networks accordingly.
- For instance, Vestas operates specialized manufacturing facilities in Brighton and Windsor, Colorado, and in 2024, reported investing $1.7 billion across the U.S. supply chain while collaborating with over 1,000 domestic suppliers to support regional wind energy projects.
Development of Hybrid Rotor Blades for Low-Wind Regions
Blade designers are engineering hybrid blades that can efficiently operate in areas with low or variable wind speeds. The Wind Turbine Rotor Blade Market is adopting segmented and extendable blades to address this challenge. These designs offer enhanced energy capture across diverse wind profiles. Hybrid blades combine lightweight tips with rigid bases to optimize structural balance and aerodynamics. Such innovations are making wind power viable in inland and urban-edge regions. Developers are expanding site selection options, boosting project pipelines in previously unsuitable locations. This trend is increasing the total addressable market for rotor blades. Flexibility in blade design is becoming a key competitive advantage.
- For instance, Siemens Gamesa developed its SG 5.0-145 turbine with optimized low-wind performance, using 71-meter blades with hybrid carbon and fiberglass construction, enabling an annual energy production increase of up to 13% compared to the previous SG 4.5-132 model.
Market Challenges Analysis
Blade Transportation and Logistics Constraints Are Hindering Scalability
Longer and heavier blades pose significant transportation hurdles, especially for remote or mountainous wind farm sites. The Wind Turbine Rotor Blade Market faces mounting challenges in logistics planning and cost optimization. Road permits, turning radius restrictions, and bridge load limits add complexity. Specialized trailers and modular transport systems are often required. OEMs must coordinate closely with local authorities and infrastructure agencies. Offshore blade transport requires custom vessels and weather-dependent scheduling. These constraints can delay project timelines and increase CAPEX. Manufacturers are exploring on-site blade assembly and rail-based transport alternatives. Addressing these challenges is critical to supporting the industry's growth trajectory.
Material Recycling and End-of-Life Disposal Remain Critical Industry Gaps
Rotor blades have long lifespans but present end-of-life disposal challenges due to their composite construction. The Wind Turbine Rotor Blade Market is grappling with a lack of scalable recycling solutions for glass and carbon fiber-reinforced polymers. Landfilling blades is environmentally unsustainable and increasingly restricted by regulations. Thermal and mechanical recycling methods are under development but remain cost-intensive. Stakeholders are piloting reuse applications in construction and infrastructure. OEMs face rising pressure to integrate recyclability into the design phase. Industry-wide standards for blade decommissioning are still evolving. Solving these environmental challenges will be essential to meet long-term sustainability goals.
Market Opportunities
Growing Investments in Floating Wind and Deepwater Projects Expand Application Scope
Floating wind projects are opening new geographic frontiers for wind energy deployment. The Wind Turbine Rotor Blade Market stands to gain from this development as demand rises for specialized blades suited to deepwater and high-turbulence environments. Floating platforms require lighter yet durable blade designs to ensure stability and performance. New investments are being channeled into R&D for blade-tip control, flexible geometry, and adaptive materials. Countries with deep coastal waters are fast-tracking floating wind pilot programs, increasing global demand for innovative rotor blade technologies. Manufacturers entering this niche can tap into a less competitive, fast-growing segment.
Urban Wind Turbines and Distributed Energy Systems Present Niche Growth Potential
Urban wind installations are emerging in smart cities and commercial zones seeking localized renewable power. The Wind Turbine Rotor Blade Market can leverage this trend by designing compact, low-noise blades optimized for rooftop or microgrid use. These applications call for aesthetics, low maintenance, and adaptable designs. Local energy generation needs are driving policy support and consumer interest. Companies investing in this segment can capture a share of the distributed energy boom. Strategic partnerships with smart infrastructure developers can unlock new revenue channels.
Market Segmentation Analysis:
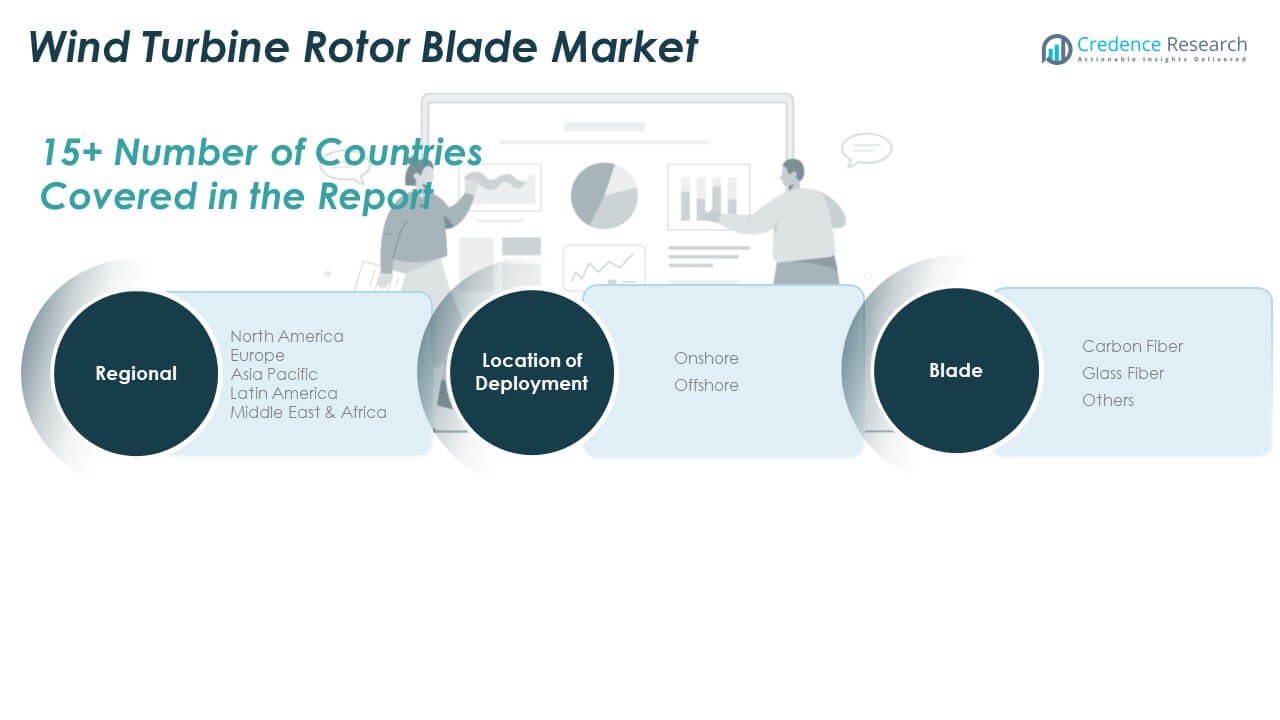
The Wind Turbine Rotor Blade Market is segmented
By location of deployment,
into onshore and offshore categories. Onshore blades hold a dominant share due to widespread land-based wind projects across Asia Pacific, Europe, and North America. These blades are cost-efficient and easier to transport and install. Offshore blades are gaining momentum with increased investments in deep-sea wind farms and floating turbines. Longer blades with robust structural integrity are in demand for offshore turbines, driving technological innovation in blade design and material use.
- For instance, GE’s Haliade-X 14 MW offshore turbine incorporates carbon fiber-reinforced blades measuring 107 meters each, contributing to a swept area of 38,000 m² and achieving capacity factors exceeding 60% in North Sea pilot installations.
By blade material,
the market is divided into carbon fiber, glass fiber, and others. Glass fiber dominates due to its affordability, ease of processing, and favorable mechanical properties for large-scale production. Carbon fiber blades, while more expensive, are preferred for their lightweight and high-strength characteristics in high-capacity turbines, particularly in offshore settings. The “others” segment includes hybrid and experimental materials that are emerging as manufacturers seek enhanced durability, recyclability, and performance optimization.
- For instance, Nordex Group’s N149/5.X turbine, part of the Delta4000 series, is widely used in onshore projects across Europe and Latin America, featuring a 149-meter rotor diameter and designed for IEC low to medium wind classes to maximize energy yield in inland terrains.
Segmentation:
By Location of Deployment
- Onshore
- Offshore
By Blade Material
- Carbon Fiber
- Glass Fiber
- Others
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Regional Analysis:
North America
The North America Wind Turbine Rotor Blade Market size was valued at USD 1,731.69 million in 2018 to USD 2,324.82 million in 2024 and is anticipated to reach USD 4,748.72 million by 2032, at a CAGR of 9.5% during the forecast period. North America accounts for 20.8% of the global market share. The U.S. leads the regional market with robust wind energy installations across Texas, Iowa, and Oklahoma. Federal tax incentives such as the Production Tax Credit (PTC) are encouraging investment in new turbine capacity. Technological innovation and a strong domestic manufacturing base are supporting rotor blade production. Canada is increasing its wind capacity, contributing to market growth. Offshore wind developments along the U.S. East Coast are creating new demand for longer, high-performance blades. Blade producers are expanding operations to support regional supply chains. The market benefits from well-established infrastructure and policy continuity.
Europe
The Europe Wind Turbine Rotor Blade Market size was valued at USD 1,579.66 million in 2018 to USD 2,051.53 million in 2024 and is anticipated to reach USD 3,880.46 million by 2032, at a CAGR of 8.4% during the forecast period. Europe holds 17% of the global market share. The region is driven by aggressive renewable energy targets and an advanced offshore wind sector. Countries such as Germany, the UK, and Denmark lead in blade innovation and deployment. EU Green Deal funding and carbon neutrality commitments are fostering demand. The North Sea and Baltic regions are key offshore hubs. Local blade manufacturing and recycling initiatives are gaining traction. R&D in recyclable and composite blades is strong. Europe maintains leadership in rotor blade efficiency and sustainability.
Asia Pacific
The Asia Pacific Wind Turbine Rotor Blade Market size was valued at USD 3,682.89 million in 2018 to USD 5,169.66 million in 2024 and is anticipated to reach USD 11,188.27 million by 2032, at a CAGR of 10.2% during the forecast period. Asia Pacific commands the largest global market share at 45.7%. China dominates the region through massive investments in wind power and local blade manufacturing. India is scaling up onshore capacity through government-led auctions and policy incentives. Japan and South Korea are pushing offshore development and floating wind technology. The region benefits from low production costs and growing electricity demand. Turbine OEMs are setting up large-scale blade factories. Export-oriented manufacturing hubs in Vietnam and China support global supply chains. The market is dynamic and innovation-driven.
Latin America
The Latin America Wind Turbine Rotor Blade Market size was valued at USD 598.37 million in 2018 to USD 813.49 million in 2024 and is anticipated to reach USD 1,562.43 million by 2032, at a CAGR of 8.6% during the forecast period. Latin America represents 6.8% of the global market share. Brazil leads regional wind deployment with a strong pipeline of projects in the northeast. Mexico supports market growth with its resource-rich wind corridors. Policy frameworks and energy diversification goals are expanding investment. Local content rules are encouraging domestic blade production. Grid integration and transmission upgrades are improving. Regional demand for clean energy is rising. Blade producers are targeting Latin America for expansion due to its growth potential.
Middle East
The Middle East Wind Turbine Rotor Blade Market size was valued at USD 334.96 million in 2018 to USD 432.36 million in 2024 and is anticipated to reach USD 805.64 million by 2032, at a CAGR of 8.2% during the forecast period. The region holds 3.5% of the global market share. The UAE and Saudi Arabia are pioneering wind energy initiatives as part of their energy diversification strategies. Projects like Dumat Al Jandal in Saudi Arabia mark significant milestones. Government-owned utilities are issuing tenders for renewable power. Regional investments are strengthening blade procurement and installation services. Harsh desert conditions are influencing blade design requirements. The market is still nascent but poised for steady growth. Policy momentum and funding support are emerging.
Africa
The Africa Wind Turbine Rotor Blade Market size was valued at USD 202.44 million in 2018 to USD 353.35 million in 2024 and is anticipated to reach USD 633.67 million by 2032, at a CAGR of 7.3% during the forecast period. Africa contributes 2.8% of the global market share. South Africa remains the leading market due to its REIPPPP renewable energy program. Morocco and Egypt are also investing in large-scale wind farms. Infrastructure limitations and financing constraints slow broader adoption. International aid and multilateral funding are supporting new installations. Local blade manufacturing is minimal but under exploration. Coastal regions offer strong wind potential. The market remains small but presents long-term opportunity through strategic partnerships and investment.
Key Player Analysis:
- TPI Composites Inc.
- Nordex SE
- Siemens Gamesa Renewable Energy, S.A.
- MFG Wind
- Sinoma Wind Power Blade Co. Ltd
- Aeris Energy
- Suzlon Energy Limited
- LM Wind Power
- Vestas Wind Systems A/S
- General Electric
- Enercon GmbH
- Acciona S.A.
- Avangrid Inc.
- Envision Group
Competitive Analysis:
The Wind Turbine Rotor Blade Market is dominated by key players such as LM Wind Power (GE Renewable Energy), TPI Composites, Siemens Gamesa, Vestas, and Nordex SE. These companies maintain strong market positions through advanced blade designs, global manufacturing facilities, and strategic alliances. It remains highly competitive, with innovation in blade length, materials, and sensor integration driving differentiation. Mergers and acquisitions are expanding product portfolios and geographic reach. Emerging players in China and India are entering with cost-efficient manufacturing and local supply advantages. Offshore wind expansion is intensifying competition in large-format blade segments. Companies are investing in recyclable and lightweight materials to meet sustainability targets. The competitive landscape continues to evolve with digital blade monitoring and predictive maintenance capabilities.
Recent Developments:
- In July 2025, Nordex SE secured major new orders from UKA for its N175/6.X and N163/6.X wind turbines, totaling 435MW in Germany. This significant achievement reinforces Nordex’s position as a leading supplier of wind turbine technology for large-scale European projects
- In March 2025, Siemens Gamesa Renewable Energy reached an agreement for TPG, through its TPG Rise Climate fund, to acquire a majority stake in Siemens Gamesa's onshore wind turbine generator manufacturing business in India and Sri Lanka.
- In Feb 2025, Aeris Energy launched the Aeris IoT Watchtower, the world’s first fully integrated cellular IoT security solution, enabling improved real-time security for IoT-connected infrastructure, including wind turbine networks
- In November 2024, Sinoma Wind Power Blade Co. Ltd signed a global strategic cooperation agreement with Goldwind Technology. This partnership is designed to deepen global collaboration and enhance the development and internationalization of the wind power industry, positioning both companies for expanded growth in renewable energy markets.
Market Concentration & Characteristics:
The Wind Turbine Rotor Blade Market exhibits moderate to high concentration, led by a few multinational OEMs with vertically integrated operations. It relies heavily on technological innovation, scale efficiency, and long-term OEM partnerships. Entry barriers are high due to capital-intensive manufacturing and strict quality requirements. It is characterized by cyclical demand, long product life cycles, and increasing customization based on turbine specifications. Regional production hubs in China, Europe, and North America dominate exports. The market favors suppliers with advanced composite capabilities and strong after-sales support. Blade length, aerodynamics, and recyclability define competitive differentiation.
Report Coverage:
The research report offers an in-depth analysis based on Location of Deployment and Blade Material. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for longer and more efficient rotor blades will increase with the global shift toward higher-capacity wind turbines.
- Offshore wind expansion will drive innovation in blade durability, corrosion resistance, and aerodynamic optimization.
- Digital technologies such as embedded sensors and digital twins will become standard in blade design and maintenance.
- Sustainability concerns will accelerate development of recyclable and bio-based composite blade materials.
- Emerging markets in Asia, Latin America, and Africa will contribute to diversified growth across onshore installations.
- Floating wind projects will open new application segments requiring lighter, flexible rotor blade designs.
- Regional manufacturing hubs will expand to reduce logistics costs and meet local content regulations.
- Industry collaborations will focus on circular economy models for blade end-of-life reuse and recycling.
- R&D investments will continue to push blade performance, especially in low-wind and turbulent environments.
- Competitive pressure will drive faster commercialization of next-generation smart blade technologies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Global Decarbonization and Renewable Energy Targets
Governments worldwide are setting ambitious renewable energy and carbon reduction targets, driving large-scale investments in wind power. This policy momentum ensures a stable pipeline of wind projects, directly increasing demand for rotor blades.
Technological Advancements in Blade Design and Materials
Continuous innovation in blade aerodynamics, length, and composite materials is enabling higher energy capture and improved turbine efficiency. These advancements make wind energy more cost-competitive and expand the application of wind turbines to new environments, boosting rotor blade demand.
Expansion of Offshore and Floating Wind Projects
The rapid growth of offshore wind, including floating wind farms, is creating demand for longer, more robust, and corrosion-resistant rotor blades. Offshore projects require specialized blade designs, opening new high-value market segments.
Government Incentives and Local Content Policies
Incentives such as tax credits, renewable portfolio standards, and local manufacturing mandates are encouraging investment in wind energy infrastructure. These policies support both the installation of new turbines and the establishment of regional blade manufacturing facilities.
Sustainability and Circular Economy Initiatives
Rising environmental concerns and regulatory pressures are pushing manufacturers to develop recyclable and bio-based rotor blades. This trend is driving R&D investment and shaping procurement preferences, supporting long-term market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Wind Turbine Rotor Blade Market?
What factors are driving the growth of the Wind Turbine Rotor Blade Market?
What are the key segments within the Wind Turbine Rotor Blade Market?
What are some challenges faced by the Wind Turbine Rotor Blade Market?
Who are the major players in the Wind Turbine Rotor Blade Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Blade Material
- 1.2.1 Carbon Fiber
- 1.2.2 Glass Fiber
- 1.2.3 Others
- 1.3 By Location of Deployment
- 1.3.1 Onshore
- 1.3.2 Offshore
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 8,130.00 million → 2032: USD 22,819.19 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wind Turbine Rotor Blades Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wind Turbine Rotor Blades Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wind Turbine Rotor Blades Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wind Turbine Rotor Blades Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wind Turbine Rotor Blades Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wind Turbine Rotor Blades Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wind Turbine Rotor Blades Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wind Turbine Rotor Blades Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 8,130.00 million → 2032: USD 22,819.19 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wind Turbine Rotor Blades Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Blade Material - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Carbon Fiber
- 12.3.7.2 Glass Fiber
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Location of Deployment - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Onshore
- 12.4.7.2 Offshore
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wind Turbine Rotor Blades Geographic Market Outlook, 2018-2032
- 13.1 Regional Market Size and Share, 2018
- 13.2 Regional Market Forecast, 2018-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Wind Turbine Rotor Blades Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2018-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Wind Turbine Rotor Blades Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2018
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2018-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 LM Wind Power (GE Renewable Energy)
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 TPI Composites Inc.
- 17.4 Siemens Gamesa Renewable Energy, S.A.
- 17.5 Vestas Wind Systems A/S
- 17.6 Nordex SE
- 17.7 Sinoma Wind Power Blade Co. Ltd
- 17.8 Aeris Energy
- 17.9 Suzlon Energy Limited
- 17.10 General Electric
- 17.11 Enercon GmbH
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

