
Market Overview
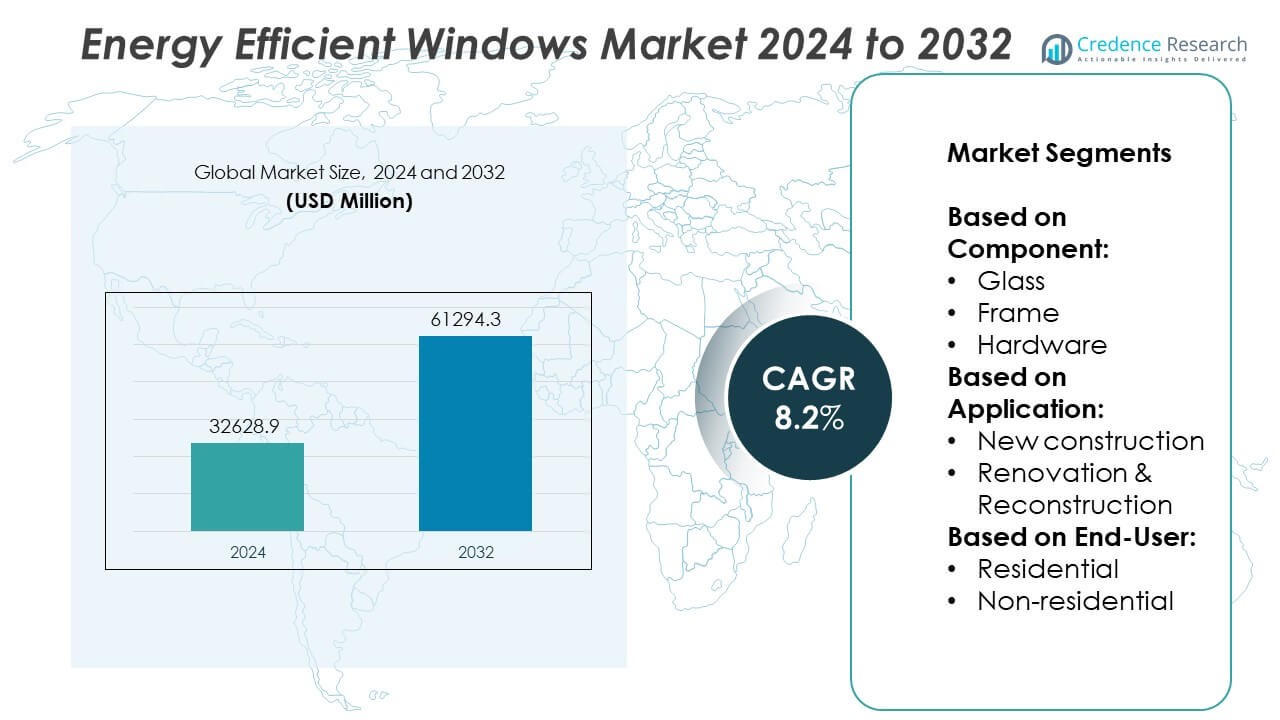
The Energy Efficient Windows market size was valued at USD 32,628.9 million in 2024 and is anticipated to reach USD 61,294.3 million by 2032, growing at a CAGR of 8.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Energy Efficient Windows Market Size 2024 | USD 32,628.9 Million |
| Energy Efficient Windows Market, CAGR | 8.2% |
| Energy Efficient Windows Market Size 2032 | USD 61,294.3 Million |
The Energy Efficient Windows market grows steadily due to increasing demand for energy conservation and stringent government regulations promoting sustainable construction. Rising urbanization and new building developments drive adoption, while technological advancements such as low-emissivity glass and smart window systems enhance product performance and appeal. Consumers prioritize reducing energy costs and improving indoor comfort, encouraging upgrades in both residential and commercial sectors. The growing focus on green building certifications further accelerates market growth. These drivers, combined with trends toward eco-friendly materials and automated window technologies, shape the dynamic expansion of the Energy Efficient Windows market globally.
The Energy Efficient Windows market shows strong growth across North America, Europe, and Asia-Pacific, driven by regulatory support and increasing construction activities. North America and Europe lead in adopting advanced technologies due to strict energy codes, while Asia-Pacific experiences rapid urbanization and rising environmental awareness. Key players such as Saint-Gobain S.A., Andersen Corporation, Pella Corporation, and JELD-WEN, Inc. dominate the market with extensive product portfolios and innovation capabilities. These companies focus on enhancing window efficiency and expanding their global presence to meet rising demand across diverse regions. Their strategic investments in research and development fuel ongoing market growth.
Market Insights
- The Energy Efficient Windows market was valued at USD 32,628.9 million in 2024 and is projected to reach USD 61,294.3 million by 2032, growing at a CAGR of 8.2% during the forecast period.
- Increasing global focus on energy conservation and rising electricity costs drive demand for energy-efficient window solutions in both residential and commercial sectors.
- Technological advancements such as low-emissivity coatings, triple glazing, and smart windows that adjust tint and insulation based on environmental conditions are shaping market trends.
- Strong regulatory support through stringent building codes and energy standards in regions like North America and Europe pushes adoption of energy-efficient windows.
- High initial costs, complex installation processes, and inconsistent regulatory frameworks in certain regions restrict market growth and adoption rates.
- North America, Europe, and Asia-Pacific dominate the market, with Asia-Pacific showing the fastest growth due to rapid urbanization and increasing environmental awareness.
- Leading players including Saint-Gobain S.A., Andersen Corporation, Pella Corporation, and JELD-WEN, Inc. compete through innovation, strategic partnerships, and expanding product portfolios to strengthen their market positions.
Market Drivers
Rising Demand for Energy Conservation and Regulatory Support Driving Market Growth
The growing emphasis on reducing energy consumption in residential and commercial buildings significantly propels the Energy Efficient Windows market. Governments worldwide implement stringent energy efficiency regulations and building codes to lower greenhouse gas emissions and promote sustainable construction. These policies create a strong demand for windows that offer superior insulation and thermal performance. Consumers increasingly seek products that help reduce energy bills and improve indoor comfort. This shift in priorities encourages manufacturers to innovate and offer advanced window technologies, boosting market expansion. The drive for sustainability in urban development further reinforces the adoption of energy-efficient window solutions.
- For instance, Saint-Gobain reported that its high-performance glazing solutions helped reduce energy consumption in over 2,000 commercial projects globally, contributing to significant heating and cooling energy savings.
Technological Advancements Enhancing Performance and Market Appeal
Technological innovation plays a crucial role in expanding the Energy Efficient Windows market. Manufacturers introduce features such as low-emissivity coatings, triple glazing, and gas-filled panels to enhance thermal insulation and reduce heat transfer. These innovations improve window durability, reduce noise pollution, and increase natural light penetration while minimizing energy loss. The integration of smart window technologies adds value by enabling users to control light and heat transmission remotely. It helps meet the evolving preferences of consumers seeking both efficiency and convenience. Continuous research and development efforts strengthen the product portfolio and competitive edge in the market.
- For instance, Pella Corporation has supplied energy-efficient window replacements for over 15,000 retrofit projects across North America, resulting in measurable reductions in annual energy consumption. Pella's windows are designed to improve energy efficiency, which helps lower heating and cooling costs.
Rising Urbanization and Construction Activities Creating Market Opportunities
Rapid urbanization and increased construction of residential and commercial properties fuel the demand for energy-efficient building components. The Energy Efficient Windows market benefits from large-scale infrastructure projects and the growing preference for green buildings. Urban centers emphasize sustainable architecture to comply with environmental standards and reduce operational costs. Builders and developers incorporate energy-efficient windows to enhance building certifications and attract environmentally conscious buyers. The market also sees growth in retrofit projects, where existing buildings upgrade to improve energy performance. These factors contribute to consistent demand growth across multiple regions.
Growing Consumer Awareness and Preference for Sustainable Solutions
Consumer awareness about the environmental and economic benefits of energy-efficient windows influences purchasing decisions. Homeowners and businesses increasingly recognize the long-term savings in energy costs and the positive impact on carbon footprints. It encourages investment in premium window products despite higher initial costs. Marketing efforts and educational campaigns by manufacturers and environmental organizations raise knowledge about product advantages. The trend toward sustainable living and green building practices aligns with consumer values, supporting market penetration. This shift fosters steady growth and strengthens the position of energy-efficient windows in the broader building materials industry.
Market Trends
Increasing Adoption of Smart and Automated Window Technologies
The Energy Efficient Windows market experiences a significant shift toward smart and automated window solutions. Integration of sensors and IoT technology allows windows to adjust tint, ventilation, and insulation based on environmental conditions. This innovation enhances energy savings by optimizing natural light and heat control throughout the day. Consumers and commercial property owners show growing interest in intelligent systems that offer convenience and reduce operational costs. It also supports smart building frameworks, improving overall energy management. Manufacturers invest heavily in developing user-friendly interfaces and seamless connectivity with home automation platforms. This trend is likely to accelerate the adoption of advanced window technologies globally.
- For instance, Saint-Gobain’s SageGlass dynamic glazing technology has been installed in over 300 commercial buildings worldwide, providing adjustable solar control that reduces HVAC loads substantia.
Preference for Sustainable and Eco-Friendly Materials in Window Manufacturing
Sustainability trends influence the choice of materials used in energy-efficient windows. The market shifts toward eco-friendly components such as recycled aluminum, low-VOC sealants, and sustainably sourced wood. These materials lower the environmental impact throughout the product lifecycle while maintaining high performance. The demand for green building certifications encourages manufacturers to comply with environmental standards in their production processes. It also drives research into alternative, sustainable materials that enhance thermal efficiency. Buyers increasingly prefer products with transparent environmental credentials. This trend supports the broader movement toward sustainable construction and energy conservation.
- For instance, JELD-WEN has expanded its manufacturing footprint in India and China, supplying energy-efficient windows to over 5,000 new housing developments, helping reduce energy loads in urban residential projects.
Expansion of Retrofitting and Renovation Projects in Developed Regions
Retrofitting existing buildings with energy-efficient windows gains momentum in developed markets. Aging infrastructure and rising energy costs push property owners to upgrade windows for better insulation and energy savings. The Energy Efficient Windows market benefits from government incentives and rebate programs promoting renovations. It offers an opportunity to replace older, inefficient windows without extensive structural modifications. This trend also aligns with efforts to meet stricter energy codes and sustainability goals. Retrofit projects create a steady demand for customized solutions tailored to different architectural styles and building types. It broadens the market reach beyond new construction activities.
Growing Demand in Emerging Economies Due to Urbanization and Climate Awareness
Emerging economies witness rapid urbanization and increasing climate awareness, boosting demand for energy-efficient building components. The Energy Efficient Windows market experiences growth driven by rising disposable incomes and government initiatives promoting energy conservation. Consumers in these regions seek products that enhance indoor comfort while lowering electricity bills. Developers adopt energy-efficient windows to comply with evolving building regulations and improve property value. It presents opportunities for market players to expand through localized manufacturing and affordable solutions. This trend contributes to the global diffusion of energy-efficient window technologies across diverse economic landscapes.
Market Challenges Analysis
High Initial Costs and Installation Complexity Limiting Market Penetration
The Energy Efficient Windows market faces challenges due to the relatively high upfront costs of advanced window systems. Consumers and builders often hesitate to invest in premium products despite their long-term energy savings. Installation requires skilled labor to ensure proper sealing and optimal performance, which increases overall project expenses. In some regions, limited access to trained professionals further complicates adoption. The complexity of retrofitting energy-efficient windows into existing structures also poses technical difficulties and higher costs. These factors restrict widespread penetration, especially in price-sensitive markets. Manufacturers and stakeholders must focus on cost reduction and simplified installation processes to overcome these barriers.
Variability in Regulatory Standards and Market Fragmentation Impeding Uniform Growth
Divergent energy efficiency regulations and building codes across regions create challenges for the Energy Efficient Windows market. Manufacturers must tailor products to comply with varying local standards, increasing production complexity and costs. Inconsistent enforcement of regulations weakens market incentives and slows adoption rates in certain areas. Fragmented market demand limits economies of scale, affecting pricing strategies and profitability. It also complicates global supply chain management and product certification processes. These challenges hinder the establishment of universal benchmarks for performance and quality. Industry collaboration and harmonization of standards could support smoother market expansion and innovation.
Market Opportunities
Expanding Demand for Green Buildings and Sustainable Construction Driving Market Potential
The growing emphasis on green buildings and sustainable construction creates significant opportunities for the Energy Efficient Windows market. Developers and architects increasingly incorporate energy-efficient components to meet environmental certifications such as LEED and BREEAM. It encourages the adoption of windows that reduce energy consumption and improve indoor air quality. Rising awareness about carbon footprint reduction among end-users further supports market growth. Investment in large-scale commercial and residential projects focused on sustainability boosts demand for advanced window solutions. Manufacturers can capitalize on this trend by offering products that align with evolving green standards and consumer preferences. This shift opens new avenues for innovation and market expansion globally.
Technological Innovation and Emerging Markets Offering Growth Prospects
Technological advancements in window design and materials provide substantial opportunities for market players to differentiate their offerings. Innovations such as smart windows, dynamic glazing, and enhanced thermal insulation improve energy performance and user convenience. The Energy Efficient Windows market benefits from the increasing adoption of these technologies across developed and developing regions. Emerging economies present untapped potential due to rapid urbanization, rising disposable incomes, and growing government initiatives promoting energy efficiency. It creates demand for affordable, high-performance window solutions tailored to local climates and building practices. Collaborations between manufacturers, governments, and construction firms can accelerate market penetration in these regions. This environment fosters steady growth and diversification of product portfolios.
Market Segmentation Analysis:
By Component:
The market divides into glass, frame, and hardware segments. Glass represents the largest share due to its critical role in thermal insulation and light transmission. Innovations such as low-emissivity coatings and triple glazing enhance energy performance, making glass a focal point for manufacturers. Frames contribute significantly by providing structural support and additional insulation through materials like vinyl, aluminum, and wood composites. Hardware includes locks, hinges, and other fittings that ensure window functionality and security, with demand increasing for durable and energy-efficient designs. The combination of these components determines overall window efficiency and market appeal.
- For instance, Marvin Windows and Doors completed over 8,000 retrofit projects in urban residential communities, achieving notable reductions in heating and cooling loads through upgraded window installations.
By Application:
New construction drives demand for energy-efficient windows to comply with current building codes and sustainability standards. Developers prioritize advanced windows to enhance property value and reduce operational energy costs. The renovation and reconstruction segment grows steadily as owners upgrade older buildings to improve energy efficiency and meet updated regulations. Retrofitting existing structures with modern windows offers a cost-effective solution for reducing energy consumption without complete rebuilding. This segment benefits from government incentives and growing awareness of energy conservation benefits in existing properties.
By End-User:
Residential demand dominates due to increased consumer focus on reducing home energy expenses and improving indoor comfort. Homeowners invest in energy-efficient windows to lower heating and cooling costs, particularly in regions with extreme temperatures. The non-residential segment encompasses commercial, institutional, and industrial buildings, where energy savings translate into substantial operational cost reductions. Office complexes, schools, hospitals, and retail spaces increasingly integrate energy-efficient windows to achieve green building certifications and improve occupant well-being. It presents significant growth opportunities driven by expanding urbanization and stricter energy policies in public and private sectors.
Segments:
Based on Component:
- Glass
- Frame
- Hardware
Based on Application:
- New construction
- Renovation & Reconstruction
Based on End-User:
- Residential
- Non-residential
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant portion of the Energy Efficient Windows market, accounting for approximately 28% of the global market share. The region’s market growth benefits from stringent government regulations aimed at improving building energy efficiency and reducing carbon emissions. The United States, Canada, and Mexico implement comprehensive building codes that encourage the use of energy-efficient windows in both new construction and renovation projects. High consumer awareness about energy savings and environmental sustainability also drives demand. Technological innovation, combined with incentives and rebate programs, supports adoption among residential and commercial sectors. The mature construction industry and increasing focus on green buildings further bolster North America’s leading position in the market.
Europe
Europe commands about 26% of the global Energy Efficient Windows market. The region enforces some of the world’s most rigorous energy efficiency standards and policies, such as the European Union’s Energy Performance of Buildings Directive (EPBD). These regulations mandate the use of energy-efficient materials in new and existing buildings, fueling market demand. Germany, the United Kingdom, France, and the Nordic countries lead in adopting advanced window technologies that improve insulation and reduce energy consumption. Rising investments in retrofitting older buildings, along with increasing consumer preference for sustainable living, contribute to steady market growth. Europe’s commitment to carbon neutrality by 2050 also encourages continuous innovation and widespread market adoption.
Asia-Pacific
Asia-Pacific represents the fastest-growing segment with a market share of around 30%, driven by rapid urbanization, infrastructure development, and rising environmental awareness. Countries like China, India, Japan, and South Korea lead the regional demand due to increasing residential and commercial construction activities. Growing disposable incomes and government initiatives promoting energy efficiency fuel consumer interest. The region sees increased investments in smart windows and innovative materials that enhance thermal performance. Expanding green building certifications and energy-saving regulations create opportunities for manufacturers. Asia-Pacific’s large population base and emerging economies position it as a crucial growth market with significant untapped potential.
Latin America
Latin America accounts for about 8% of the Energy Efficient Windows market. The region experiences gradual growth due to rising urban development and increased emphasis on sustainable construction practices. Brazil, Mexico, and Argentina spearhead market demand with new construction and retrofit projects targeting energy efficiency improvements. Regulatory frameworks are evolving, encouraging adoption of energy-efficient products. Consumer awareness and government incentives remain key factors driving market penetration. However, challenges such as fluctuating economic conditions and limited access to advanced technologies slow growth compared to other regions. Latin America presents steady opportunities for market expansion with increasing investments in green infrastructure.
Middle East and Africa (MEA)
Middle East and Africa (MEA) hold approximately 8% of the market share. The region faces unique challenges due to extreme climate conditions that require highly specialized window solutions to manage heat gain and energy consumption. Gulf countries like the UAE, Saudi Arabia, and Qatar invest heavily in smart cities and sustainable buildings, boosting demand for energy-efficient windows. Growing infrastructure projects and government-led sustainability initiatives support market growth. However, the overall pace of adoption remains moderate due to economic and political variability. Increasing focus on renewable energy and energy conservation creates potential for further expansion in MEA’s Energy Efficient Windows market.
Key Player Analysis
- Marvin Windows and Doors
- Andersen Corporation
- Kolbe Windows & Doors
- JELD-WEN, Inc.
- Saint-Gobain S.A.
- Harvey Building Products
- Pella Corporation
- Atrium Windows & Doors
- Milgard Windows & Doors
- Simonton Windows
Competitive Analysis
Key players in the Energy Efficient Windows market include Saint-Gobain S.A., Andersen Corporation, Pella Corporation, JELD-WEN, Inc., Marvin Windows and Doors, Simonton Windows, Kolbe Windows & Doors, Harvey Building Products, Atrium Windows & Doors, and Milgard Windows & Doors. These companies maintain strong market positions through continuous innovation, diversified product portfolios, and expansive distribution networks. They invest significantly in research and development to enhance window efficiency, incorporating advanced technologies such as low-emissivity glass, smart glazing, and improved frame materials. Strategic acquisitions and partnerships enable them to broaden their geographical reach and strengthen customer base across residential and commercial sectors. Focus on sustainability and compliance with evolving energy regulations drives product development and marketing strategies. Leading manufacturers also emphasize customization and quality assurance to meet diverse consumer preferences and regional building codes. Competitive pricing and after-sales support further differentiate their offerings. These efforts collectively enable them to maintain leadership amid rising competition and evolving market demands, positioning them for sustained growth in the expanding Energy Efficient Windows market.
Recent Developments
- In September 2024, Harvey Windows + Doors unveiled a new entry door system featuring advanced technologies like HydroShield™ protection and full-length panels powered by industry leader Plastpro, enhancing durability and energy efficiency. Harvey continues to focus on energy-efficient vinyl windows with multi-chamber frames, Low-E glass, Argon gas fills, and warm edge spacers contributing to superior insulation and performance.
- In April 2023, Marvin Windows and Doors launched a new line of Solar Eclipse windows featuring a solar-powered tint technology.
- In January 2023, YES WORLD Climate Tech Pte Ltd announced the launch of energy-efficient Windows Solution for home and commercial buildings. The product includes a specialized glass solution comprising of double pane and sandwich glass designed to reflect a 85% of solar radiant heat. The product provides control over reflectivity, emissivity, absorption, radiant heat gain, solar heat gain, and privacy.
Market Concentration & Characteristics
The Energy Efficient Windows market exhibits a moderately concentrated structure dominated by a few leading manufacturers that hold significant market shares. These key players leverage advanced technology, extensive distribution channels, and strong brand recognition to maintain competitive advantages. It features a mix of global corporations and regional manufacturers catering to diverse consumer needs across residential, commercial, and industrial sectors. The market’s characteristics include continuous innovation focused on improving thermal performance, durability, and aesthetic appeal. Fragmented demand across different regions and application segments creates opportunities for both established firms and emerging players. Price sensitivity in certain markets encourages manufacturers to balance cost-efficiency with product quality. Regulatory compliance and sustainability considerations remain critical factors influencing product development and market entry. The interplay between technological advancements, regional preferences, and regulatory landscapes defines the competitive dynamics within the Energy Efficient Windows market. This environment drives companies to adopt strategic partnerships and invest in research and development to sustain growth and meet evolving customer expectations.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Energy Efficient Windows market will continue to grow steadily driven by rising energy conservation awareness.
- Adoption of smart and automated window technologies will increase significantly.
- Regulations enforcing stricter energy efficiency standards will expand globally.
- Demand for eco-friendly and sustainable window materials will gain momentum.
- Urbanization and construction in emerging markets will create new growth opportunities.
- Retrofitting older buildings with energy-efficient windows will become more common.
- Technological innovation will focus on improving thermal insulation and reducing installation complexity.
- Consumer preference for products that balance cost and energy savings will shape market offerings.
- Strategic collaborations between manufacturers and governments will accelerate market penetration.
- Expansion into untapped regions will diversify the competitive landscape and drive long-term growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Energy Efficiency Regulations
Governments worldwide are implementing strict building codes and energy efficiency standards, compelling builders and property owners to adopt energy efficient windows to comply with regulations and reduce greenhouse gas emissions.
Technological Advancements in Window Materials
Innovations such as low-emissivity coatings, triple glazing, and smart window systems are enhancing thermal insulation and user convenience, making energy efficient windows more attractive for both new construction and retrofit projects.
Urbanization and Construction Boom in Emerging Markets
Rapid urbanization and increased construction activities, especially in Asia-Pacific, are driving demand for energy efficient building materials, including advanced window solutions that help reduce operational energy costs.
Consumer Focus on Energy Savings and Indoor Comfort
Rising electricity costs and greater awareness of the benefits of energy conservation are motivating homeowners and businesses to invest in windows that lower energy bills and improve indoor comfort.
Growth in Green Building Certifications
The pursuit of certifications such as LEED and BREEAM is encouraging developers and property owners to incorporate energy efficient windows, as these products contribute significantly to meeting sustainability criteria and enhancing property value.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Energy Efficient Windows market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Energy Efficient Windows Market projected to grow between 2025 and 2032?
Which Energy Efficient Windows market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Energy Efficient Windows market?
Who are the leading companies in the Energy Efficient Windows Market?
Which region commanded the largest share of the Energy Efficient Windows market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Residential
- 1.2.2 Non-residential
- 1.3 By Component
- 1.3.1 Glass
- 1.3.2 Frame
- 1.3.3 Hardware
- 1.4 By Application
- 1.4.1 New construction
- 1.4.2 Renovation & Reconstruction
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 32,628.9 million → 2032: USD 61,294.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Energy Efficient Window Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Energy Efficient Window Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Energy Efficient Window Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Energy Efficient Window Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Energy Efficient Window Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Energy Efficient Window Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Energy Efficient Window Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Energy Efficient Window Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 32,628.9 million → 2032: USD 61,294.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Energy Efficient Window Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Non-residential
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Glass
- 12.4.7.2 Frame
- 12.4.7.3 Hardware
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 New construction
- 12.5.7.2 Renovation & Reconstruction
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Energy Efficient Window End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Energy Efficient Window Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Energy Efficient Window Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Energy Efficient Window Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Saint-Gobain S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Andersen Corporation
- 18.4 Pella Corporation
- 18.5 JELD-WEN, Inc.
- 18.6 Marvin Windows and Doors
- 18.7 Simonton Windows
- 18.8 Kolbe Windows & Doors
- 18.9 Harvey Building Products
- 18.10 Atrium Windows & Doors
- 18.11 Milgard Windows & Doors
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

