
Wireless Portable Medical Devices Market Overview:
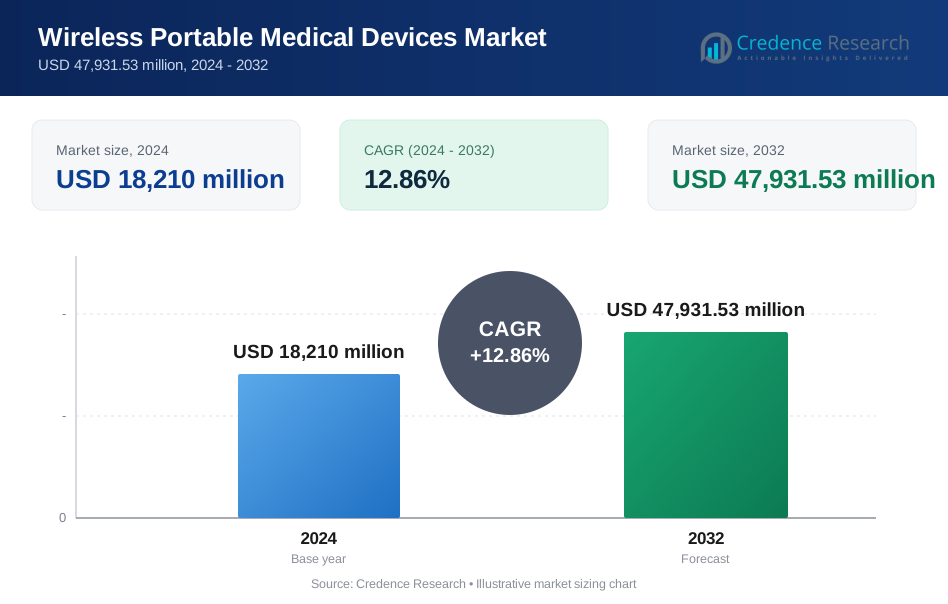
The Wireless Portable Medical Devices Market size was valued at USD 18,210 million in 2024 and is anticipated to reach USD 47,931.53 million by 2032, growing at a CAGR of 12.86% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wireless Portable Medical Devices Market Size 2024 | USD 18,210 million |
| Wireless Portable Medical Devices Market, CAGR | 12.86% |
| Wireless Portable Medical Devices Market Size 2032 | USD 47,931.53 million |
Wireless Portable Medical Devices Market Insights
- Market growth is driven by rising adoption of remote patient monitoring, increasing chronic disease prevalence, expanding geriatric population, and growing demand for home healthcare solutions using wireless and portable devices.
- Key market trends include rapid adoption of wearable devices holding 6% segment share in 2024, increased use of Bluetooth technology with 38.9% share, and integration of AI-enabled analytics for continuous and predictive healthcare monitoring.
- The market features strong presence of global players focusing on innovation, portfolio expansion, partnerships with digital health platforms, and advancements in wireless connectivity to strengthen remote monitoring capabilities.
- Regionally, North America led with 38.7% share in 2024, followed by Europe at 27.4% and Asia Pacific at 23.6%, while Latin America and Middle East & Africa collectively account for the remaining share, supported by expanding digital health initiatives.

Wireless Portable Medical Devices Market Segmentation Analysis:
By Product Type:
The Wireless Portable Medical Devices Market, by product type, is led by Wearable Devices, which accounted for 42.6% market share in 2024, driven by rising adoption of continuous health monitoring, preventive care, and patient-centric diagnostics. Wearables such as smart ECG monitors, glucose sensors, and vital-sign trackers enable real-time data transmission and remote patient management, supporting improved clinical outcomes. Strong demand from home healthcare and chronic disease management further reinforces dominance. Handheld & portable devices follow due to diagnostic flexibility, while implantable and stationary devices maintain steady demand in specialized clinical settings.
- For instance, the Apple Watch Series 4 and later models use an electrical heart sensor to record single-lead ECGs in 30 seconds, detecting atrial fibrillation and storing data in the Health app for sharing with clinicians to enable real-time heart rhythm monitoring.\
By Technology:
Based on technology, Bluetooth emerged as the dominant sub-segment, holding 38.9% market share in 2024, supported by low power consumption, reliable short-range connectivity, and seamless integration with smartphones and cloud platforms. Bluetooth technology enables continuous data synchronization for wearable and portable devices, improving usability and patient compliance. Growing penetration of mobile health applications and remote monitoring solutions continues to accelerate adoption. Wi-Fi remains significant in hospital environments, while NFC, RFID, and UWB gain traction in asset tracking, secure data transfer, and advanced localization applications.
- For instance, Withings BPM Core collects blood pressure and ECG data over Bluetooth, automatically uploading measurements to the Health Mate app for physician review and seamless sharing of health reports.
By Application:
By application, Cardiology accounted for the largest share at 36.4% in 2024, driven by the high prevalence of cardiovascular diseases and increased use of wireless ECG monitors, heart rate trackers, and ambulatory cardiac diagnostics. Demand is reinforced by the need for early detection, continuous monitoring, and post-operative follow-up outside hospital settings. Integration of wireless devices with telecardiology platforms supports clinical decision-making and reduces hospital readmissions. Neurology and respiratory applications show strong growth, supported by rising neurological disorders and chronic respiratory conditions.
Key Growth Drivers
Rising Adoption of Remote Patient Monitoring
The Wireless Portable Medical Devices Market is driven by the rapid adoption of remote patient monitoring across hospitals, clinics, and homecare environments. Increasing prevalence of chronic diseases, including cardiovascular disorders, diabetes, and respiratory conditions, is accelerating demand for continuous and real-time monitoring solutions. Wireless portable devices enable clinicians to track patient health remotely, reduce hospital readmissions, and improve early intervention. The shift toward value-based healthcare models further supports adoption, as remote monitoring enhances care efficiency while lowering overall treatment costs for healthcare systems.
- For instance, Medtronic's MyCareLink Heart app enables Bluetooth-enabled cardiac devices to transmit wireless alerts for remote monitoring, boosting transmission success to 95% from under 70% with legacy systems and supporting early interventions to cut unnecessary hospitalizations.
Growing Geriatric Population and Chronic Disease Burden
The expanding geriatric population is a major growth driver for the Wireless Portable Medical Devices Market. Aging individuals are more prone to chronic illnesses that require ongoing monitoring and long-term management. Wireless portable devices support mobility, ease of use, and continuous health tracking, allowing elderly patients to maintain independence while ensuring medical supervision. Rising life expectancy in both developed and emerging economies increases demand for such solutions. Healthcare providers increasingly rely on portable wireless technologies to manage long-term care and improve patient outcomes.
- For instance, Abbott's FreeStyle Libre system, a wearable glucose sensor worn on the upper arm, supports diabetes management in older adults by eliminating fingersticks and enabling frequent scans.
Technological Advancements in Wireless Connectivity and Sensors
Technological advancements in wireless communication and sensor technologies are significantly driving the Wireless Portable Medical Devices Market. Improvements in Bluetooth Low Energy, Wi-Fi, NFC, and advanced biosensors enhance device accuracy, battery efficiency, and data transmission reliability. Integration with cloud platforms and mobile applications allows real-time monitoring and actionable health insights. These innovations support broader adoption across clinical and homecare settings, encouraging manufacturers to develop compact, multifunctional, and patient-friendly devices that meet evolving healthcare demands.
Key Trends & Opportunities
Integration of Artificial Intelligence and Advanced Analytics
Integration of artificial intelligence and advanced data analytics represents a key trend and opportunity in the Wireless Portable Medical Devices Market. AI-enabled devices can analyze continuous patient data streams to detect early warning signs, predict disease progression, and automate alerts for healthcare providers. This capability enhances clinical decision-making and supports personalized treatment approaches. As healthcare systems move toward precision medicine, wireless portable devices with embedded analytics gain strong market potential, enabling proactive care delivery and improved long-term patient management.
- For instance, Apple Watch Series 4 and later models use AI-powered ECG functionality to generate single-lead electrocardiograms, classifying rhythms as sinus rhythm or atrial fibrillation while detecting irregular pulses through proprietary algorithms during daily wear.
Expansion of Home Healthcare and Preventive Care Solutions
The expansion of home healthcare and preventive care services creates strong growth opportunities for the Wireless Portable Medical Devices Market. Patients increasingly prefer home-based monitoring solutions that provide convenience, comfort, and continuous health tracking. Wireless portable devices enable early diagnosis, preventive intervention, and reduced dependency on hospital visits. Government initiatives promoting homecare models and rising consumer awareness of preventive health management further support adoption, encouraging manufacturers to design intuitive devices tailored for daily, long-term home use.
- For instance, Dexcom's G6 continuous glucose monitor delivers real-time readings every five minutes (288 per day) without fingersticks, supporting home diabetes management. It achieved a mean absolute relative difference (MARD) of 12.8% against point-of-care testing in non-critically ill patients.
Key Challenges
Data Security and Patient Privacy Risks
Data security and patient privacy risks remain a significant challenge for the Wireless Portable Medical Devices Market. Wireless transmission of sensitive medical data increases exposure to cyber threats and unauthorized access. Compliance with strict healthcare data protection regulations adds complexity to device development and deployment. Ensuring robust encryption, secure data storage, and interoperability increases operational costs. Addressing these concerns is critical to maintaining patient trust and enabling large-scale adoption across healthcare systems.
Regulatory Complexity and Approval Barriers
Regulatory complexity presents a major challenge in the Wireless Portable Medical Devices Market. Devices must comply with rigorous safety, performance, and clinical validation standards across different regions. Varying regulatory frameworks and lengthy approval processes can delay product launches and increase development costs. Rapid technological innovation further complicates compliance, requiring continuous validation of new features. Manufacturers must invest in regulatory expertise and testing capabilities to balance innovation with timely market entry.
Regional Analysis
North America
The Wireless Portable Medical Devices Market in North America accounted for 38.7% market share in 2024, supported by advanced healthcare infrastructure and high adoption of digital health technologies. Strong demand for remote patient monitoring, wearable diagnostics, and home healthcare solutions continues to drive growth across the region. The presence of leading medical device manufacturers and rapid integration of wireless connectivity into clinical workflows further strengthen market expansion. Favorable reimbursement policies and widespread use of telehealth platforms enhance adoption, particularly for chronic disease management and post-acute care monitoring.
Europe
Europe held 27.4% market share in 2024 in the Wireless Portable Medical Devices Market, driven by rising healthcare digitization and aging demographics. Increasing prevalence of cardiovascular and neurological disorders has boosted demand for portable wireless monitoring solutions. Government initiatives supporting remote care and early diagnosis promote adoption across hospitals and homecare settings. Strong regulatory focus on patient safety and data protection encourages deployment of advanced wireless devices. Growing investments in connected healthcare infrastructure and preventive care models continue to support steady regional market growth.
Asia Pacific
The Asia Pacific Wireless Portable Medical Devices Market captured 23.6% market share in 2024, supported by rapid healthcare modernization and expanding patient populations. Rising incidence of chronic diseases, increasing geriatric population, and growing awareness of preventive healthcare are key drivers. Adoption of cost-effective wireless portable devices is accelerating in both urban and semi-urban areas. Government investments in digital health initiatives and expanding telemedicine services further boost market penetration, making Asia Pacific the fastest-growing regional market during the forecast period.
Latin America
Latin America accounted for 6.2% market share in 2024 in the Wireless Portable Medical Devices Market, driven by improving healthcare access and gradual adoption of remote monitoring solutions. Increasing prevalence of lifestyle-related diseases supports demand for portable diagnostic and monitoring devices. Expansion of private healthcare facilities and growing use of telehealth services enhance market growth. While infrastructure limitations persist in some countries, rising healthcare expenditure and digital health initiatives are improving adoption of wireless portable medical technologies across the region.
Middle East & Africa
The Middle East & Africa Wireless Portable Medical Devices Market held 4.1% market share in 2024, supported by increasing healthcare investments and growing focus on digital health transformation. Demand is driven by rising chronic disease burden and expanding homecare services. Government-led healthcare modernization programs and adoption of remote monitoring solutions support market growth, particularly in urban centers. Although limited infrastructure in certain regions restricts adoption, increasing awareness of wireless healthcare technologies and gradual expansion of telemedicine platforms continue to create growth opportunities.
Wireless Portable Medical Devices Market Segmentations:
By Product Type
- Wearable Devices
- Implantable Devices
- Handheld & Portable Devices
- Stationary Devices
By Technology
- Bluetooth
- Wi-Fi
- Near Field Communication (NFC)
- RFID (Radio Frequency Identification)
- Ultra-wideband (UWB)
By Application
- Cardiology
- Neurology
- Respiratory
- Others
By End-User
- Hospitals & Clinics
- Home Healthcare
- Long-Term Care & Assisted Living Facilities
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Wireless Portable Medical Devices Market highlights the presence of major players including Medtronic plc, Koninklijke Philips N.V., GE Healthcare, Abbott, Boston Scientific Corporation, Siemens Healthineers, Omron Healthcare, Dexcom, Fitbit Health Solutions, and Samsung Electronics Co. Ltd. The market is characterized by strong emphasis on product innovation, wireless connectivity enhancement, and integration of advanced analytics to strengthen clinical performance and user experience. Companies actively invest in research and development to expand wearable, handheld, and implantable device portfolios tailored for remote monitoring and chronic disease management. Strategic partnerships with digital health platforms and cloud service providers support data-driven healthcare delivery. Market participants also focus on geographic expansion, regulatory compliance, and portfolio diversification to address evolving healthcare needs. Continuous technological advancements and patient-centric design strategies enable leading companies to strengthen their market positioning and sustain long-term growth.
Key Player Analysis
- Samsung Electronics Co. Ltd.
- Siemens Healthineers
- Dexcom, Inc
- Koninklijke Philips N.V.
- Fitbit Health Solutions
- Abbott
- Omron Healthcare, Inc.
- Boston Scientific Corporation
- Medtronic plc
- GE Healthcare
Recent Developments
- In December 2025, Nordic Semiconductor unveiled the nRF54LV10A, a breakthrough low-voltage Bluetooth LE System-on-Chip (SoC) designed specifically for ultra-low-power wireless healthcare wearable devices such as continuous glucose monitors and biosensors, enhancing connectivity and battery performance for next-gen medical wearables.
- In December 2025, Medtronic launched the MiniMed 780G insulin pump system, a wireless portable device integrated with Abbott's Instinct continuous glucose monitor sensor, in the United States.
- In July 2025, Samsung Electronics acquired Xealth, a digital health platform specializing in wearable data integration for medical applications.
- In April 2025, Clarius Mobile Health received FDA clearance for the Clarius Median Nerve AI Tool, an AI-enabled software for its wireless handheld ultrasound scanners that automates median nerve measurements to support carpal tunnel syndrome diagnosis.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Technology, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Wireless Portable Medical Devices Market will continue to expand driven by rising demand for remote and continuous patient monitoring solutions.
- Increasing integration of wireless devices with telehealth platforms will strengthen real-time clinical decision-making.
- Technological advancements in sensors and low-power wireless connectivity will improve device accuracy and battery efficiency.
- Adoption of wearable and handheld devices will increase across home healthcare and preventive care settings.
- Growing geriatric population and chronic disease prevalence will sustain long-term market demand.
- Artificial intelligence and data analytics will enhance predictive diagnostics and personalized healthcare delivery.
- Regulatory frameworks will increasingly adapt to support connected and digital medical technologies.
- Data security and interoperability solutions will become a critical focus for device manufacturers.
- Emerging economies will offer strong growth opportunities due to expanding healthcare access and digital health investments.
- Strategic collaborations between medical device companies and digital health providers will accelerate innovation and market penetration.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Wireless Portable Medical Devices Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Wireless Portable Medical Devices Market projected to grow between 2024 and 2032?
Which Wireless Portable Medical Devices Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Wireless Portable Medical Devices Market?
Who are the leading companies in the Wireless Portable Medical Devices Market?
Which region commanded the largest share of the Wireless Portable Medical Devices Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Wireless Portable Medical Devices Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Wireless Portable Medical Devices Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 18,210 million → 2032: USD 47,931.53 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Wireless Portable Medical Devices Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Wireless Portable Medical Devices Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Wireless Portable Medical Devices Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Wireless Portable Medical Devices Market Drivers
- 3.3 Wireless Portable Medical Devices Market Restraints & Challenges
- 3.4 Wireless Portable Medical Devices Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Wireless Portable Medical Devices Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Wireless Portable Medical Devices Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Wireless Portable Medical Devices category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Wireless Portable Medical Devices Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Wireless Portable Medical Devices Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Wireless Portable Medical Devices market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Wireless Portable Medical Devices Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Wireless Portable Medical Devices Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Wireless Portable Medical Devices Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Wireless Portable Medical Devices (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Wireless Portable Medical Devices Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Wireless Portable Medical Devices Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Wireless Portable Medical Devices Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Wireless Portable Medical Devices Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Wireless Portable Medical Devices Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Wireless Portable Medical Devices Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Wireless Portable Medical Devices Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Wireless Portable Medical Devices Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Wireless Portable Medical Devices Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
