
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wood Coatings Market Size 2024 | USD 11,381.8 million |
| Wood Coatings Market, CAGR | 4.87% |
| Wood Coatings Market Size 2032 | uSD 16,659.2 million |
Market Overview
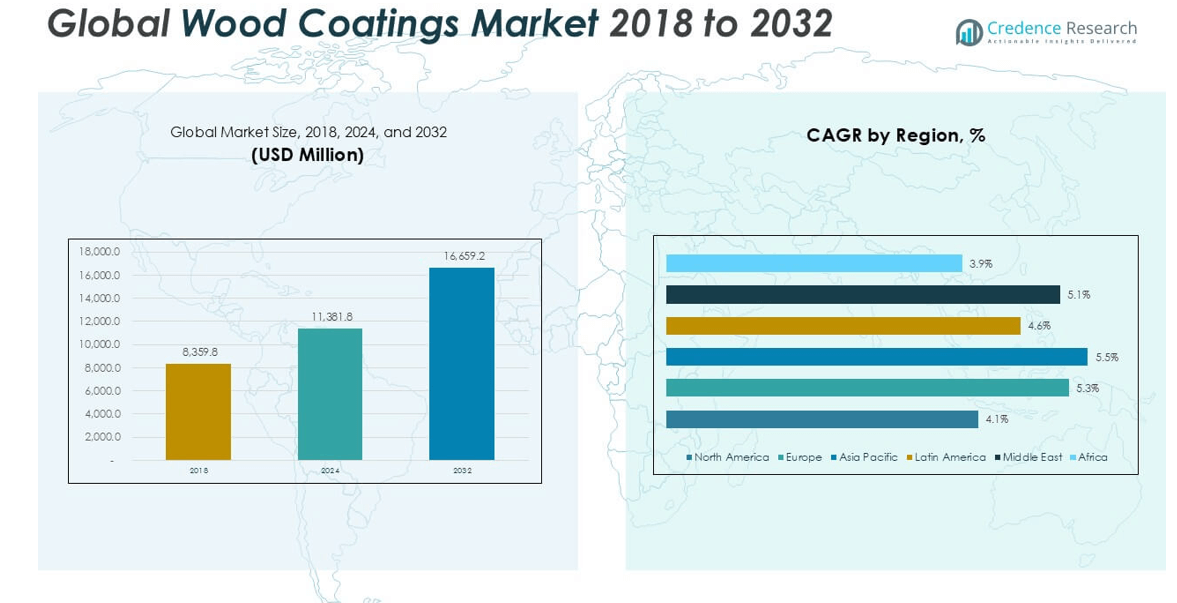
The Global Wood Coatings Market is projected to grow from USD 11,381.8 million in 2024 to an estimated USD 16,659.2 million by 2032, with a compound annual growth rate (CAGR) of 4.87% from 2025 to 2032.
Growing consumer preference for durable, visually appealing furniture and interiors is fueling demand for advanced wood coatings. The market is also being driven by the rising adoption of polyurethane, nitrocellulose, and waterborne coatings due to their enhanced performance characteristics, including abrasion resistance, fast drying times, and lower VOC emissions. Additionally, the trend of do-it-yourself (DIY) furniture refinishing and home improvement projects is supporting the sales of easy-to-apply wood coatings in retail segments. Manufacturers are investing in R\&D to introduce sustainable and UV-curable coatings, catering to the increasing emphasis on eco-compliance and low environmental impact.
Geographically, the Asia Pacific region dominates the global wood coatings market, driven by robust construction activity and a flourishing furniture manufacturing sector, particularly in China, India, and Southeast Asia. North America and Europe follow, with strong demand supported by home improvement trends and sustainability regulations. Key players operating in the global market include AkzoNobel N.V., PPG Industries, Sherwin-Williams Company, RPM International Inc., Axalta Coating Systems, and Nippon Paint Holdings Co., Ltd., among others.
Market Insights
- The Global Wood Coatings Market is projected to grow from USD 11,381.8 million in 2024 to USD 16,659.2 million by 2032, registering a CAGR of 4.87% from 2025 to 2032.
- Rising construction and renovation activities across residential and commercial sectors are fueling demand for protective and decorative wood coatings.
- Increasing consumer preference for low-VOC, sustainable coatings is driving the shift toward water-based and UV-curable technologies.
- Volatility in raw material prices and complex environmental regulations limit profit margins and product flexibility for manufacturers.
- Asia Pacific dominates the global market due to robust furniture manufacturing and urbanization trends in China, India, and Southeast Asia.
- North America and Europe show strong growth driven by DIY trends, sustainability regulations, and demand for premium interior finishes.
- Leading companies like AkzoNobel, Sherwin-Williams, and PPG Industries are focusing on innovation, eco-friendly solutions, and regional expansion to strengthen their market positions.
Market Drivers
Expansion in Construction and Furniture Sectors Driving Demand
The Global Wood Coatings Market benefits significantly from the expansion of residential and commercial construction projects worldwide. Rapid urbanization and population growth increase the need for housing, which directly boosts demand for wood-based products such as doors, windows, and furniture. Governments are investing in infrastructure development, creating more opportunities for wood coatings to be used in both structural and decorative applications. The furniture sector also contributes heavily to market growth, with consumers seeking durable and aesthetically pleasing products. It supports the use of coatings that enhance surface appeal and protect against moisture, scratches, and wear. The combined growth in construction and furniture manufacturing strongly supports the demand for wood coatings globally.
- For instance, in 2024, the Asia Pacific region saw a surge in wood coatings consumption driven by large-scale construction and furniture manufacturing, with China, India, Vietnam, Indonesia, and Malaysia leading the demand for wood-based furniture, flooring, and cabinetry across both residential and commercial projects
Shift Toward Eco-Friendly and Low-VOC Products Enhancing Market Appeal
Environmental regulations continue to influence product development in the Global Wood Coatings Market. Regulatory bodies enforce limits on volatile organic compound (VOC) emissions, encouraging manufacturers to offer water-based and low-VOC alternatives. It aligns with consumer preferences for sustainable and non-toxic home improvement products. Waterborne coatings provide reduced environmental impact without compromising performance, making them a preferred choice in both developed and emerging economies. Manufacturers are adopting advanced technologies to ensure compliance and meet the growing sustainability standards. These shifts create opportunities for innovation and help companies capture market share by addressing environmental concerns.
- For instance, over 1,500,000 metric tons of synthetic zeolites were produced globally for use in detergents and water treatment, and in the U.S. alone, the furniture and kitchen cabinet markets used over 227,000,000 liters of wood coatings annually, with a growing share shifting to low-VOC and water-based formulations to comply with environmental regulations
Technological Advancements Improving Product Performance and Application
Advances in coating technologies contribute to market expansion by improving durability, application ease, and finish quality. The Global Wood Coatings Market benefits from innovations such as UV-curable, polyurethane, and nano-coatings, which provide better resistance to wear and longer lifespan. It enables faster drying times, energy savings, and reduced maintenance costs, particularly in industrial settings. The availability of high-performance coatings supports their usage in high-traffic and outdoor environments. Technological improvements help manufacturers differentiate products and meet evolving customer expectations. These advancements strengthen the value proposition of premium wood coatings.
DIY Trends and Home Renovation Boosting Retail Sales
The rising popularity of do-it-yourself (DIY) home improvement projects positively impacts the Global Wood Coatings Market. Consumers increasingly invest in small-scale renovations, including furniture refinishing and interior updates, which require accessible and user-friendly coatings. It creates demand in retail segments for low-maintenance, easy-to-apply wood finishes. E-commerce platforms further support this trend by offering a wide selection of products directly to end-users. The shift toward personalization and aesthetic customization in home design encourages frequent coating purchases. DIY activity continues to drive sales volume and introduces new consumer segments to the market.
Market Trends
Rising Adoption of Water-Based and UV-Curable Coatings Shaping Product Innovation
Manufacturers are increasingly shifting toward water-based and UV-curable coatings due to growing demand for sustainable and low-emission solutions. These coatings offer reduced VOC content, faster drying times, and improved safety for both users and the environment. The Global Wood Coatings Market sees innovation focused on enhancing performance while maintaining regulatory compliance. It reflects a broader trend of replacing solvent-based coatings with eco-friendly alternatives across residential, commercial, and industrial segments. UV-curable coatings are gaining popularity for their quick curing, energy efficiency, and suitability in automated production environments. Companies continue to invest in R\&D to improve formulation quality and broaden product portfolios.
- For instance, in 2024, a leading coatings manufacturer reported producing over 180,000 tonnes of water-based and UV-curable wood coatings for the furniture and construction industries, with more than 60,000 tonnes used in automated production lines across Europe and Asia, according to company production data and industry association surveys.
Customization and Aesthetic Enhancement Fueling Demand for Specialty Finishes
The market is witnessing increased interest in decorative finishes that offer texture, gloss, and color variety. Interior designers and homeowners prefer coatings that enhance the natural look of wood while offering long-lasting protection. The Global Wood Coatings Market responds with tailored solutions such as metallic, matte, and distressed finishes that cater to evolving design trends. It drives demand in the premium furniture and interior décor segments, where aesthetics hold strong importance. Brands are leveraging color science and finish innovations to deliver customizable options that match modern design preferences. These specialty coatings support differentiation in a competitive market.
- For instance, in 2024, more than 12,000 new specialty wood coating products featuring custom finishes were launched globally, with over 3,500 of these products specifically designed for premium furniture and interior décor applications, as documented in product registries and industry market surveys.
Digitalization of Retail Channels Expanding Consumer Access and Engagement
E-commerce platforms have significantly transformed how consumers purchase wood coatings. Easy access to product information, reviews, and how-to content encourages do-it-yourself applications and supports informed purchasing decisions. The Global Wood Coatings Market benefits from digital outreach, with brands optimizing online presence to boost visibility and customer engagement. It enables small and medium businesses to compete more effectively alongside established players. Direct-to-consumer models and subscription-based offerings are emerging as scalable strategies. Digital retail expansion strengthens brand-customer relationships and accelerates product adoption across diverse consumer bases.
Sustainable Packaging and Supply Chain Practices Gaining Industry Focus
Sustainability trends are not limited to product formulations but extend to packaging and logistics. Companies are reducing plastic use, adopting recyclable materials, and improving transportation efficiency. The Global Wood Coatings Market reflects this shift through responsible sourcing and environmental certifications. It aligns with stakeholder expectations for full-cycle sustainability and brand transparency. Supply chains are adapting to lower carbon footprints through lean inventory management and regional production hubs. These practices help enhance corporate reputation and meet long-term sustainability targets.
Market Challenges
Fluctuating Raw Material Prices and Supply Chain Disruptions Impact Cost Structures
Volatility in raw material prices, particularly for resins, solvents, and additives, poses a major challenge for manufacturers. Global supply chain disruptions and geopolitical tensions continue to impact the availability and cost of essential inputs. The Global Wood Coatings Market faces pressure to maintain pricing stability while ensuring consistent quality. It increases operational costs and affects profitability for small and medium enterprises. Companies must balance cost-efficiency with performance demands, often requiring adjustments in sourcing strategies. Unpredictable logistics and transportation delays further complicate timely product delivery.
- For instance, the average price of epoxy resins-a key raw material for wood coatings-rose from 2,300 units per ton to over 3,100 units per ton within a single year due to supply chain disruptions and increased demand. Meanwhile, transportation costs for imported solvents increased by 40 to 60 units per ton during the same period, putting additional financial strain on manufacturers and leading some small producers to temporarily halt production or seek alternative suppliers.
Stringent Environmental Regulations Restrict Product Formulation Flexibility
Tightening environmental regulations across key markets constrain the use of traditional solvent-based coatings. Manufacturers must invest in reformulation and certification processes to comply with emission and safety standards. The Global Wood Coatings Market must navigate differing regional policies, which creates complexity in product development and distribution. It slows time-to-market for new products and raises R\&D expenditures. Smaller firms often struggle with compliance due to limited resources. Regulatory uncertainty also impacts long-term planning and innovation cycles
Market Opportunities
Growing Demand for Sustainable Construction and Green Building Materials
The increasing focus on sustainable construction creates strong opportunities for eco-friendly wood coatings. Builders and architects prefer materials with low VOC emissions and sustainable certifications to meet green building standards. The Global Wood Coatings Market can leverage this demand by offering water-based, bio-based, and UV-curable formulations. It positions manufacturers to supply coatings that align with LEED and BREEAM compliance requirements. Consumer awareness around indoor air quality and environmental impact further supports this shift. Companies that prioritize sustainability will likely gain a competitive edge in both residential and commercial segments.
Expansion into Emerging Markets with Rising Urbanization and Furniture Demand
Urban development in emerging economies offers a high-potential growth avenue for coating manufacturers. Rising income levels and a growing middle class drive demand for new housing and modern furniture, increasing wood coating requirements. The Global Wood Coatings Market can capitalize on these trends by expanding distribution networks and tailoring products to regional preferences. It enables local partnerships and capacity building to serve high-growth markets such as India, Brazil, and Southeast Asia. Government initiatives supporting housing and infrastructure development further strengthen demand. Strategic entry into these regions can unlock long-term market expansion.
Market Segmentation Analysis
By Technology
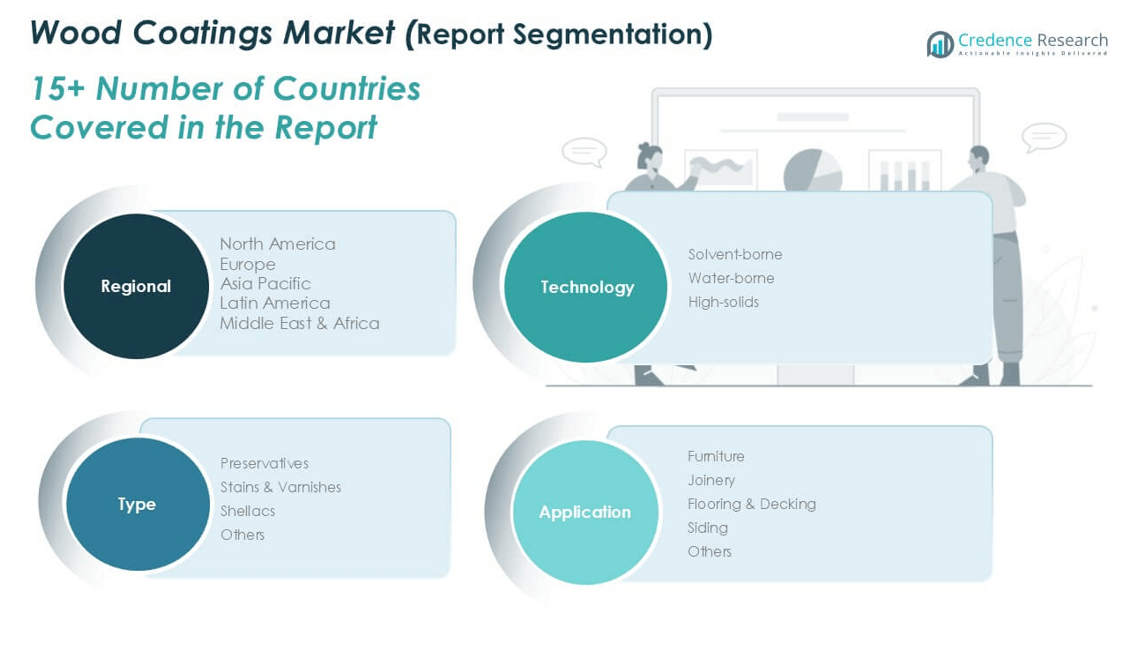
The Global Wood Coatings Market is segmented by technology into solvent-borne, water-borne, and high-solids coatings. Water-borne coatings hold a growing share due to increasing environmental regulations and demand for low-VOC solutions. It offers excellent durability and minimal odor, making it suitable for residential and indoor applications. Solvent-borne coatings remain relevant in industrial use where high performance and quick drying are required, though they face regulatory pressure. High-solids coatings are gaining popularity for their ability to reduce emissions while maintaining strong protective qualities. The shift toward sustainable technologies continues to drive innovation and reshape market dynamics.
- For instance, more than 1.2 billion liters of water-borne wood coatings were produced globally, compared to approximately 850 million liters of solvent-borne and 320 million liters of high-solids coatings.
By Type
The market is categorized by type into preservatives, stains & varnishes, shellacs, and others. Stains & varnishes dominate the segment due to their dual role in enhancing wood appearance and providing protection. It appeals to both consumers and professionals in furniture and interior applications. Preservatives are widely used in outdoor wooden structures, offering resistance against moisture, insects, and decay. Shellacs cater to specialty and traditional applications where natural and glossy finishes are preferred. The "others" category includes oils, waxes, and hybrid formulations that address niche demands across custom woodworking and heritage restoration.
- For instance, a 2023 survey of leading wood coatings manufacturers found that over 650 million liters of stains and varnishes were sold worldwide, while preservatives accounted for about 270 million liters, and shellacs and other specialty products totaled around 90 million liters.
By Application
Key application areas include furniture, joinery, flooring & decking, siding, and others. Furniture accounts for the largest share, driven by rising demand for aesthetic and durable wood finishes in homes and offices. The Global Wood Coatings Market benefits from growth in joinery applications such as doors and windows, where coatings protect against wear and weathering. Flooring and decking require high-performance coatings that offer abrasion resistance and long-lasting finish. Siding applications focus on exterior protection and visual appeal. The “others” segment includes cabinetry and decorative elements, supporting the overall market expansion across both new construction and renovation sectors.
Segments
Based on Technology
- Solvent-borne
- Water-borne
- High-solids
Based on Type
- Preservatives
- Stains & Varnishes
- Shellacs
- Others
Based on Application
- Furniture
- Joinery
- Flooring & Decking
- Siding
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Wood Coatings Market
The North America Wood Coatings Market was valued at USD 3,719.88 million in 2024 and is projected to reach USD 5,127.69 million by 2032, growing at a CAGR of 4.1%. It held approximately 32.7% of the global market share in 2024. The market is driven by strong demand in residential construction, home renovation, and premium furniture segments. The United States remains the dominant contributor due to high consumer spending and established DIY trends. Growth in environmentally friendly coatings and demand for water-based formulations also supports market expansion. Canada contributes significantly through its rising infrastructure investments and sustainable building codes.
Europe Wood Coatings Market
The Europe Wood Coatings Market was valued at USD 2,538.46 million in 2024 and is expected to reach USD 3,831.61 million by 2032, expanding at a CAGR of 5.3%. It accounted for 22.3% of the global market share in 2024. Germany, France, and Italy are key markets due to their large furniture and woodwork manufacturing industries. The region leads in eco-regulatory compliance, encouraging the use of low-VOC and waterborne coatings. It benefits from increasing demand for high-end interior solutions and architectural wood coatings. Product innovation and sustainable practices drive market competitiveness across Europe.
Asia Pacific Wood Coatings Market
The Asia Pacific Wood Coatings Market stood at USD 3,140.71 million in 2024 and is projected to reach USD 4,831.16 million by 2032, with the highest CAGR of 5.5%. Holding 27.6% of the global share in 2024, it is led by China, India, and Southeast Asia. Rapid urbanization, rising disposable incomes, and expanding housing projects fuel market growth. China dominates due to its extensive furniture production and export capacity. India follows with a rising demand for ready-to-assemble furniture and branded coatings. The region presents strong opportunities for market entry and product localization.
Latin America Wood Coatings Market
The Latin America Wood Coatings Market was valued at USD 1,135.57 million in 2024 and is forecast to reach USD 1,632.60 million by 2032, growing at a CAGR of 4.6%. It represented 10% of the global market share in 2024. Brazil and Mexico are key contributors, driven by residential development and a growing middle-class population. The market is evolving with a shift toward water-based solutions and sustainable raw materials. Furniture exports and regional trade agreements support growth in coating applications. It also benefits from increasing retail expansion and DIY trends across urban areas.
Middle East Wood Coatings Market
The Middle East Wood Coatings Market reached USD 624.86 million in 2024 and is projected to grow to USD 934.58 million by 2032 at a CAGR of 5.1%. It accounted for 5.5% of the global market share in 2024. Demand is supported by infrastructure development and interior design investments in the UAE, Saudi Arabia, and Qatar. Luxury construction projects and hotel refurbishments drive high-end coating applications. The market is gradually adopting eco-friendly solutions in response to global sustainability goals. It offers growth potential through project-based demand and increased use of decorative coatings in public infrastructure.
Africa Wood Coatings Market
The Africa Wood Coatings Market was valued at USD 222.27 million in 2024 and is projected to reach USD 301.53 million by 2032, growing at a CAGR of 3.9%. It held around 2% of the global market share in 2024. South Africa, Nigeria, and Kenya are leading markets due to rising urbanization and construction activity. Demand remains largely price-sensitive, with growing interest in cost-effective protective coatings. It is gradually shifting toward modern finishes as home ownership and interior renovation trends expand. Market development depends on improving distribution channels and affordable product access across rural and urban areas.
Key players
- Teknos Group Oy
- BASF SE
- Akzo Nobel N.V.
- The Sherwin-Williams Company
- Valspar Corporation
- Covestro AG
- PPG Industries, Inc.
- Morrells Wood Finishes
Competitive Analysis
The Global Wood Coatings Market is highly competitive with the presence of both multinational corporations and regional players. Leading companies like Akzo Nobel N.V., The Sherwin-Williams Company, and PPG Industries, Inc. dominate through extensive product portfolios, global distribution networks, and continuous R\&D investment. It emphasizes innovation in waterborne, UV-curable, and low-VOC coatings to align with evolving environmental regulations and consumer preferences. Companies such as Teknos Group Oy and Morrells Wood Finishes strengthen their market position through specialized wood finish solutions and regional expertise. Strategic collaborations, acquisitions, and expansion into emerging markets remain key growth strategies. The competition also centers on offering customizable, high-performance, and cost-effective products to meet diverse application needs across construction, furniture, and industrial sectors.
Recent Developments
- In April 2025, BASF SE's Greenville, Ohio site was recognized as the 2025 Business of the Year by the Darke County Community Improvement Corporation (CIC). This award highlights the site's operational excellence in coatings production and its positive impact on the local community, including support for STEM2D education and economic development. The Greenville site is a major producer of automotive coatings and a significant employer in the area.
- In February 2025, Akzo Nobel N.V. launched RUBBOL WF 3350, a new water-borne wood coating with 20% bio-based content. This development is part of AkzoNobel's strategy to increase the use of renewable materials in its coating products. The new coating, suitable for both interior and exterior use, is designed to maintain high performance standards while incorporating sustainable elements. It was developed and manufactured at AkzoNobel's Malmö site in Sweden. The bio-based content is derived from renewable plant-based materials and has been verified by external testing using ASTM standards. The product also comes with the Sikkens Wood Coatings Extralife warranty.
Market Concentration and Characteristics
The Global Wood Coatings Market demonstrates moderate to high market concentration, with a few large players such as Akzo Nobel N.V., The Sherwin-Williams Company, and PPG Industries, Inc. holding significant shares. It features a blend of global corporations and regional manufacturers competing on innovation, sustainability, and product performance. The market is characterized by high product differentiation, driven by evolving consumer preferences, environmental regulations, and diverse end-use applications. Technological advancements in water-based and UV-curable formulations continue to shape product development. Entry barriers include regulatory compliance, raw material sourcing, and the need for established distribution networks. It remains dynamic, with continuous shifts in material trends and customer demand patterns influencing strategic direction.
Report Coverage
The research report offers an in-depth analysis based on Technology, Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Wood Coatings Market is projected to maintain steady growth through 2032, supported by rising demand in construction, furniture, and interior design sectors worldwide.
- Water-based coatings will gain more market share due to increasing environmental regulations and consumer preference for low-VOC, eco-friendly products.
- Technological improvements in UV-curable coatings will enhance curing speed, durability, and efficiency, especially in high-volume industrial applications.
- Leading manufacturers will invest in research and development to create advanced formulations with superior performance, faster drying, and minimal environmental impact.
- Emerging economies in Asia Pacific, Latin America, and Africa will offer substantial growth opportunities due to urbanization, rising income levels, and expanding housing demand.
- There will be a greater push toward bio-based and renewable raw material coatings, aligning with global sustainability goals and carbon reduction initiatives.
- E-commerce and digital platforms will continue to reshape consumer access, encouraging DIY adoption and widening market reach for small and medium enterprises.
- Companies will adopt recyclable and biodegradable packaging materials to meet environmental standards and improve brand responsibility.
- The market will see growing demand for customized textures, finishes, and colors in wood coatings, reflecting evolving consumer tastes and premium segment growth.
- Key players will pursue mergers, acquisitions, and regional partnerships to strengthen their footprint, improve supply chains, and address diverse consumer requirements.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion in Construction and Furniture Sectors
Rapid urbanization and infrastructure development are increasing demand for wood-based products in residential and commercial projects, directly boosting the need for protective and decorative wood coatings in doors, windows, furniture, and interiors.
Shift Toward Eco-Friendly and Low-VOC Products
Stringent environmental regulations and consumer preference for sustainable, non-toxic products are accelerating the adoption of water-based and UV-curable wood coatings, which offer lower VOC emissions and improved safety.
Technological Advancements in Coating Formulations
Innovations such as UV-curable, polyurethane, and nano-coatings are enhancing durability, drying speed, and finish quality, making wood coatings more attractive for both industrial and DIY applications.
DIY and Home Renovation Trends
The growing popularity of do-it-yourself furniture refinishing and home improvement projects is driving retail sales of easy-to-apply wood coatings, expanding the market to new consumer segments.
Growth in Emerging Markets
Rising income levels, urbanization, and expanding housing demand in Asia Pacific, Latin America, and Africa are creating significant opportunities for wood coatings manufacturers to expand their presence and tailor products to regional needs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Wood Coatings Market in 2023 and 2032, and what is the CAGR?
Which technologies are gaining popularity in the wood coatings industry?
Which region leads the Global Wood Coatings Market?
Who are the key players in the wood coatings market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Preservatives
- 1.2.2 Stains & Varnishes
- 1.2.3 Shellacs
- 1.2.4 Others
- 1.3 By Technology
- 1.3.1 Solvent-borne
- 1.3.2 Water-borne
- 1.3.3 High-solids
- 1.4 By Application
- 1.4.1 Furniture
- 1.4.2 Joinery
- 1.4.3 Flooring & Decking
- 1.4.4 Siding
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 10,832.4 million → 2032: USD 16,659.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wood Coatings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wood Coatings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wood Coatings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wood Coatings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wood Coatings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wood Coatings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wood Coatings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wood Coatings Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 10,832.4 million → 2032: USD 16,659.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wood Coatings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Preservatives
- 12.3.7.2 Stains & Varnishes
- 12.3.7.3 Shellacs
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Solvent-borne
- 12.4.7.2 Water-borne
- 12.4.7.3 High-solids
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Furniture
- 12.5.7.2 Joinery
- 12.5.7.3 Flooring & Decking
- 12.5.7.4 Siding
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wood Coatings End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Wood Coatings Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Wood Coatings Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Wood Coatings Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Akzo Nobel N.V.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 The Sherwin-Williams Company
- 18.4 PPG Industries, Inc.
- 18.5 BASF SE
- 18.6 Teknos Group Oy
- 18.7 Valspar Corporation
- 18.8 Covestro AG
- 18.9 Morrells Wood Finishes
- 18.10 RPM International Inc.
- 18.11 Nippon Paint Holdings Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

