
Market Overview
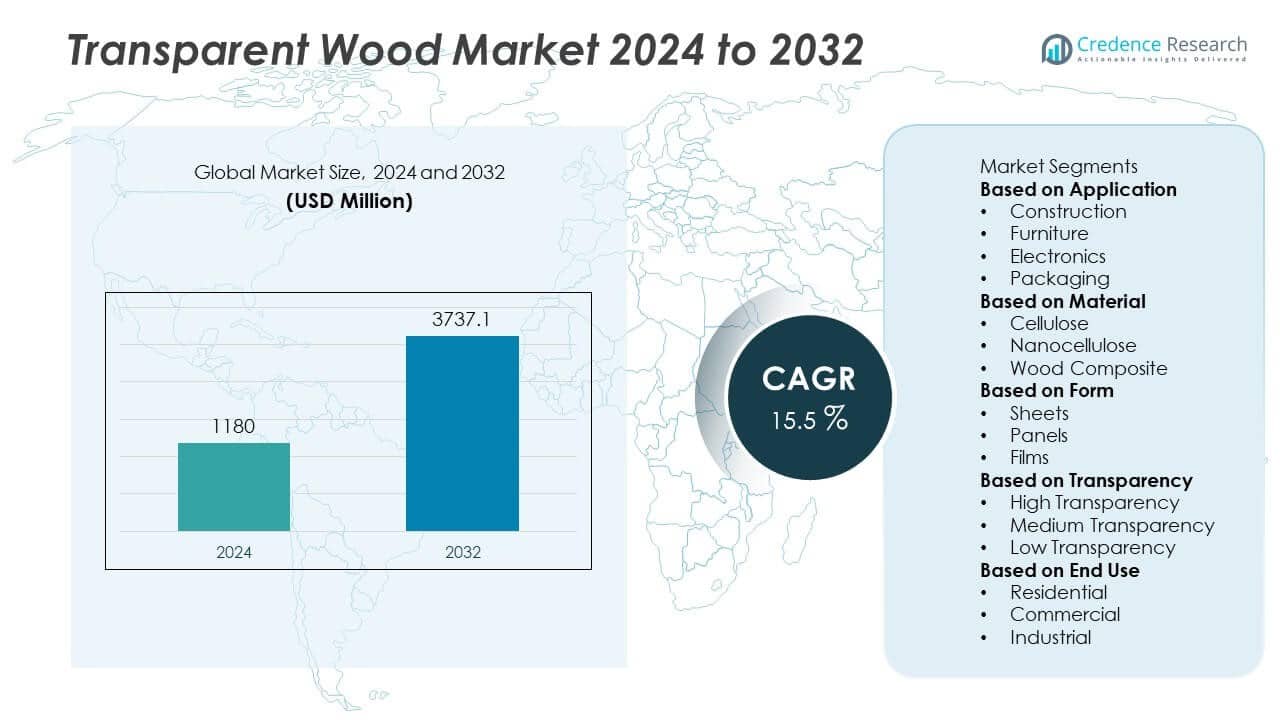
The Transparent Wood Market size was valued at USD 1,180 million in 2024 and is anticipated to reach USD 3,737.1 million by 2032, registering a CAGR of 15.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Transparent Wood Market Size 2024 | USD 1,180 Million |
| Transparent Wood Market, CAGR | 15.5% |
| Transparent Wood Market Size 2032 | USD 3,737.1 Million |
The Transparent Wood Market is expanding with strong drivers and evolving trends that reinforce its long-term potential. Growing demand for sustainable alternatives to glass and plastics fuels adoption in construction and automotive industries, where it offers superior strength, insulation, and environmental benefits.
The Transparent Wood Market shows dynamic growth across regions, with North America leading research and commercialization supported by institutions such as the University of Maryland and the University of British Columbia, which are advancing scalable production methods. Europe demonstrates strong momentum through innovations from RISE Research Institutes of Sweden, KTH Royal Institute of Technology, and Chalmers University of Technology, focusing on applications in sustainable architecture and smart materials. Asia-Pacific emerges as a fast-growing region, driven by rising investments in eco-friendly construction solutions and collaborations with global research bodies. Key players shaping the market include Arbora, Granulo, AkzoNobel, and Swiss Federal Laboratories for Materials Science and Technology, which are integrating technological expertise and industrial-scale development to expand adoption across construction, automotive, and consumer applications. This geographical diversity ensures robust innovation pipelines and global partnerships that reinforce the commercialization of transparent wood technologies.
Market Insights
- The Transparent Wood Market was valued at USD 1180 million in 2024 and is expected to reach USD 3737.1 million by 2032, growing at a CAGR of 15.5% during the forecast period.
- Rising demand for sustainable construction materials drives adoption, with transparent wood offering strength, durability, and eco-friendly alternatives to glass and plastics.
- A strong trend is the integration of transparent wood into smart building solutions, where its insulating properties reduce energy consumption and align with green architecture goals.
- Competitive analysis highlights Arbora, Granulo, AkzoNobel, and RISE Research Institutes of Sweden as leading players, investing in scalable production methods and partnerships with universities and research institutions.
- The market faces restraints such as high production costs, limited large-scale manufacturing capabilities, and technical challenges in achieving consistent optical clarity for commercial applications.
- Regional analysis shows North America leading in research and commercialization, Europe driving innovations through Sweden and Switzerland, and Asia-Pacific expanding rapidly due to urbanization and green construction demand.
- The Transparent Wood Market benefits from collaborations between industry and academia, with institutions such as the University of Maryland, University of British Columbia, and KTH Royal Institute of Technology contributing to breakthroughs in material performance and scalability.
Market Drivers
Rising Demand for Sustainable and Eco-Friendly Materials
The growing emphasis on sustainability drives the adoption of transparent wood as a substitute for glass and plastics. It combines renewable raw materials with innovative engineering to reduce carbon emissions and energy use. Governments and industries promote bio-based alternatives to align with climate targets. Transparent wood addresses these demands by offering a recyclable and biodegradable solution. Its role in reducing environmental impact enhances its acceptance across industries. The Transparent Wood Market benefits strongly from these eco-driven initiatives.
- For instance, AkzoNobel has introduced a new waterborne wood coating, RUBBOL WF 3350, with 20% bio-based content. This innovation, developed by AkzoNobel's Sikkens Wood Coatings business, aims to increase the use of renewable raw materials while maintaining high performance standards.
Superior Mechanical and Thermal Properties
Transparent wood provides unique advantages over conventional glass, including higher impact resistance and better thermal insulation. It enhances safety by reducing shatter risks and lowers energy costs through improved insulation performance. These characteristics attract applications in windows, skylights, and building facades. Architects and engineers prioritize materials that improve energy efficiency without compromising aesthetics. Transparent wood meets these criteria, reinforcing its position in construction markets. It creates opportunities for wider deployment in energy-conscious building designs.
- For instance, the University of Maryland achieved transparent wood panels with tensile strength of 45 MPa and thermal conductivity of just 0.32 W/m·K, outperforming standard glass in both safety and insulation metrics.
Growing Applications in Construction and Automotive Industries
The construction industry recognizes transparent wood for its strength, light weight, and energy efficiency. It supports innovative designs for sustainable buildings and smart infrastructure. Automotive manufacturers explore its use in lightweight components, enhancing fuel efficiency and durability. Transparent wood also finds opportunities in solar panels, packaging, and interior design. This multi-sector adoption strengthens its demand base and accelerates industrial integration. The Transparent Wood Market gains traction from this broad applicability.
Advancements in Research and Commercialization Efforts
Ongoing research in nanotechnology and polymer science fuels the development of transparent wood. It improves transparency, scalability, and durability, addressing challenges for mass production. Collaborations between universities and industrial players expand pilot projects into commercial-scale manufacturing. Investments in material innovation accelerate cost reduction and improve market readiness. These advancements support integration into mainstream industries over time. Transparent wood evolves from niche research material to a viable alternative for large-scale applications.
Market Trends
Integration into Green Building and Smart Infrastructure
A leading trend in the Transparent Wood Market is its adoption in sustainable construction projects. Builders and architects prefer materials that support energy efficiency and reduce carbon footprints. Transparent wood provides better thermal insulation than glass, lowering heating and cooling costs in buildings. It also enables modern architectural designs by combining strength with transparency. Developers integrate it into facades, skylights, and smart windows to enhance energy performance. This trend aligns with the growing demand for green buildings and eco-friendly infrastructure.
- For instance, researchers at KTH Royal Institute of Technology developed transparent wood that achieves optical transmittance of 90 (measured at ~1.5 mm thickness) and an exceptionally low haze of 10, while boasting a thermal conductivity of 0.35 W/m·K, which is approximately one-third that of standard glass (~1 W/m·K)
Expansion of Applications in Automotive and Transportation
The automotive industry explores transparent wood for lightweight windows, sunroofs, and interiors. It offers durability and energy efficiency that supports advancements in electric vehicles. Lighter materials reduce overall vehicle weight, extending driving range and reducing fuel consumption. Transparent wood combines safety with aesthetic appeal, meeting consumer demand for sustainable innovation. It is also being considered for use in public transportation systems where durability and insulation are critical. The market expands with this diversification beyond construction applications.
- For instance, transparent wood developed by Wang and colleagues demonstrated optical transmittance exceeding 90, with thermal conductivity lowered to about 0.14 W/m·K, within a 4-inch by 4-inch sample fabricated using a scalable process.
Advancements in Material Engineering and Nanotechnology
Research in nanotechnology enhances the optical and mechanical properties of transparent wood. Scientists focus on improving clarity and scalability for commercial applications. Enhanced polymer resins and advanced processing techniques boost durability and transparency. These innovations make the material suitable for high-performance applications such as solar panels and optical devices. Continuous breakthroughs in material science accelerate the transition from laboratory research to industrial production. It strengthens confidence in transparent wood as a next-generation material.
Rising Collaboration between Industry and Academia
Strategic partnerships between research institutions and commercial enterprises drive innovation in the Transparent Wood Market. Universities develop prototypes while manufacturers invest in scaling production. These collaborations accelerate commercialization and reduce costs through knowledge sharing. Industry players establish pilot plants to test large-scale production of transparent wood panels. Collaborative efforts ensure steady progress in making the material commercially viable. It reflects a trend where cross-sector alliances play a critical role in market growth.
Market Challenges Analysis
High Production Costs and Scalability Issues
The Transparent Wood Market faces challenges due to high production costs and limited scalability. Current manufacturing techniques involve complex chemical treatments and polymer infiltration, which require significant investment. Limited large-scale production facilities slow down commercialization and restrict supply to niche applications. It creates barriers for widespread adoption in cost-sensitive industries such as residential construction. The reliance on advanced equipment and skilled labor further increases expenses. Until cost-efficient methods are developed, adoption will remain concentrated in premium and research-driven projects.
Durability, Standardization, and Market Acceptance
Another major challenge is ensuring durability and meeting standardized quality benchmarks for transparent wood. The material must withstand moisture, UV radiation, and long-term mechanical stress to compete with established alternatives like glass and plastics. Lack of standardized testing protocols and performance certifications limits its acceptance among architects, automotive manufacturers, and regulators. It also struggles with awareness gaps in mainstream markets where traditional materials dominate. Concerns about lifecycle performance and recyclability further slow adoption. Overcoming these hurdles requires industry collaboration, technological improvements, and greater awareness campaigns to build trust among end users.
Market Opportunities
Expansion into Sustainable Construction and Green Architecture
The Transparent Wood Market holds strong opportunities in sustainable construction and green architecture. Rising global demand for eco-friendly building materials supports the adoption of transparent wood as a substitute for energy-intensive glass and plastics. Its superior thermal insulation and renewable origin make it attractive for residential and commercial projects seeking LEED or green building certifications. It allows natural light penetration while reducing heat loss, creating energy-efficient structures. Governments promoting carbon-neutral construction policies also accelerate its potential adoption. Architects and urban developers exploring innovative, sustainable materials view transparent wood as a future-ready solution for modern infrastructure.
Growth in Automotive, Electronics, and Advanced Applications
Another key opportunity lies in expanding applications of transparent wood across automotive, electronics, and specialty industries. Automakers explore it as a lightweight alternative for windshields and interior panels to enhance energy efficiency and design flexibility. Electronics manufacturers evaluate transparent wood for displays, touch panels, and optical devices due to its durability and renewable origin. It is also gaining traction in advanced applications such as smart windows and solar panels where material efficiency and sustainability are critical. Partnerships between research institutes and manufacturers foster faster commercialization. The versatility of transparent wood across industries strengthens its position as a next-generation material with high-value opportunities.
Market Segmentation Analysis:
By Application
The Transparent Wood Market demonstrates diverse applications across construction, automotive, electronics, and energy. In construction, it is gaining strong adoption for windows, skylights, and structural elements due to its ability to transmit light while providing thermal insulation. Automotive manufacturers evaluate it for windshields, roof panels, and interiors to reduce weight and improve fuel efficiency. Electronics companies explore transparent wood for displays, touchscreens, and optical devices where durability and renewable material advantages are crucial. It also shows promise in solar panels and smart windows, combining sustainability with high-performance energy efficiency. This broad adaptability strengthens its position across multiple industries seeking innovative materials.
- For instance, the Swedish start-up Woodoo-specializing in lignin-modified wood screens-has prototyped touch-sensitive car dashboard displays using wood-based materials that originally transmitted around 80 to 90 in millimeter-thin sheets, though visibility declined when thickness increased to approximately 3.7 millimeters, transmitting around 40.
By Material
Material segmentation includes hardwood, softwood, and engineered wood. Hardwood-based transparent wood offers higher strength and durability, making it suitable for structural applications and premium products. Softwood provides lightweight characteristics and cost advantages, which appeal to sectors requiring scalability and flexibility. Engineered wood solutions are emerging, leveraging layered structures for enhanced transparency and insulation. It reflects the industry’s focus on balancing performance, cost, and sustainability through material innovation. Companies and research institutions invest heavily in refining delignification and polymer infiltration techniques to maximize clarity and resilience across material categories.
- For instance, Li and colleagues documented that transparent wood derived from birch achieved a tensile elastic modulus of around 2.4 GPa and tensile strength of approximately 52.3 MPa, along with an increase in elongation at break from about 1 up to 5 compared to untreated wood.
By Form
In terms of form, the market is segmented into panels, sheets, and customized blocks. Panels dominate due to their extensive use in construction and infrastructure, where they replace traditional glass and plastics. Sheets gain traction in electronics, automotive, and energy sectors where thin, lightweight solutions are essential. Customized blocks are applied in research, specialty products, and niche industrial uses that demand specific dimensions and properties. It illustrates how manufacturers adapt product forms to meet distinct industry requirements while ensuring performance efficiency. Continuous innovation in scalability and manufacturing processes enhances the commercial viability of all forms.
Segments:
Based on Application
- Construction
- Furniture
- Electronics
- Packaging
Based on Material
- Cellulose
- Nanocellulose
- Wood Composite
Based on Form
- Sheets
- Panels
- Films
Based on Transparency
- High Transparency
- Medium Transparency
- Low Transparency
Based on End Use
- Residential
- Commercial
- Industrial
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest share of the Transparent Wood Market at around 35%, supported by strong research initiatives, high adoption in sustainable construction, and the presence of advanced manufacturing capabilities. The United States leads the region, with universities and research labs actively investing in transparent wood technologies for windows, facades, and smart materials. Canada supports growth with government-backed sustainability programs that encourage renewable materials in infrastructure projects. It benefits from established players collaborating with construction and automotive industries to integrate innovative materials into practical applications. Growing investment in energy-efficient buildings further drives adoption, positioning the region as a global leader in commercialization.
Europe
Europe accounts for nearly 28% of the Transparent Wood Market, driven by stringent environmental regulations, demand for eco-friendly construction materials, and strong adoption of renewable resources. Countries such as Germany, Sweden, and Finland lead advancements with research into polymer infiltration processes and scalable transparent wood production. The European Union’s Green Deal framework fosters greater use of sustainable alternatives to plastics and glass in architecture and transportation. It strengthens industry collaboration between material suppliers and construction firms, creating demand for transparent wood in both residential and commercial projects. Automotive manufacturers in Germany also test transparent wood in lightweight vehicle components, aligning with carbon-reduction targets.
Asia-Pacific
Asia-Pacific represents approximately 25% of the Transparent Wood Market, with rapid growth fueled by industrial expansion, urbanization, and government emphasis on green building practices. China, Japan, and South Korea lead in production technologies, with heavy investments in research on perovskite solar cells embedded in transparent wood panels. India shows growing adoption in sustainable construction projects, driven by energy-efficient housing demand and smart city initiatives. It benefits from the region’s strong electronics sector, where transparent wood is tested for displays and consumer devices. Expanding infrastructure development combined with the need for lightweight, cost-effective materials makes Asia-Pacific a high-growth region.
Latin America
Latin America captures a smaller share of about 7% in the Transparent Wood Market, but it shows potential through sustainable construction initiatives and growing demand for renewable materials. Brazil leads the adoption with pilot projects integrating transparent wood into eco-friendly housing models, supported by government sustainability incentives. Mexico and Chile demonstrate interest in using the material for modern architecture that balances aesthetics with energy efficiency. It reflects an increasing shift among regional builders toward renewable, high-performance materials. Challenges remain in scaling production and affordability, but regional R&D collaborations open opportunities for wider adoption.
Middle East & Africa
The Middle East & Africa hold nearly 5% of the Transparent Wood Market, primarily driven by investments in sustainable construction in the Gulf countries. The United Arab Emirates and Saudi Arabia integrate renewable materials into futuristic projects aligned with their national sustainability visions. South Africa explores applications in modern housing and energy-efficient solutions, though adoption remains limited due to cost constraints. It benefits from growing awareness of the need for alternatives to traditional glass and plastics in high-temperature climates. With continued investment in advanced materials, the region holds potential for gradual but steady adoption in niche markets.
Key Player Analysis
- Swiss Federal Laboratories for Materials Science and Technology
- Chalmers University of Technology
- AkzoNobel
- University of British Columbia
- Royal Institute of Technology
- Granulo
- University of Maryland
- Arbora
- RISE Research Institutes of Sweden
- KTH Royal Institute of Technology
Competitive Analysis
The Transparent Wood Market is shaped by key players such as Arbora, Granulo, AkzoNobel, RISE Research Institutes of Sweden, University of Maryland, University of British Columbia, KTH Royal Institute of Technology, Chalmers University of Technology, Royal Institute of Technology, and Swiss Federal Laboratories for Materials Science and Technology, who collectively drive research, development, and commercialization. Academic institutions like the University of Maryland and KTH Royal Institute of Technology focus on material innovation, improving transparency, strength, and thermal insulation. Industrial participants such as Arbora, Granulo, and AkzoNobel work on scaling production, enhancing material performance, and exploring integration into construction, automotive, and architectural applications. RISE, Empa, and other research organizations contribute by creating standardized processes, conducting durability studies, and supporting large-scale testing. The Transparent Wood Market remains in an early commercialization phase, but strong collaboration between academic and industrial players positions transparent wood as a viable sustainable alternative to glass and plastics, accelerating its adoption in energy-efficient building and advanced design applications.
Recent Developments
- In February 2025, AkzoNobel introduced a new waterborne wood coating featuring 20% bio-based content, strengthening its commitment to sustainability and enhancing wood’s renewable potential in architectural and decorative uses.
- In July 2024, UBC researchers unveiled "Nxylon," a super-black wood material that absorbs nearly 100% of incoming light by trapping it within its structure-offering high potential for precision optics, solar applications, and luxury designs.
- In August 2023, Empa researchers developed an innovative epoxy resin that is both repairable and recyclable, marking a pioneering advancement in sustainable polymers for wood-based materials and supporting future eco-friendly applications.
Market Concentration & Characteristics
The Transparent Wood Market shows a moderate to high level of concentration, with research institutes, universities, and industrial players leading innovations and commercialization efforts. It demonstrates unique characteristics as a sustainable alternative to glass and plastics, combining strength, light transmission, and environmental benefits. Companies and academic institutions focus on enhancing scalability, cost efficiency, and optical clarity to meet demand from construction, automotive, and consumer electronics sectors. It benefits from active collaborations between material science researchers and manufacturers, aiming to bridge the gap between laboratory breakthroughs and industrial production. The market reflects early-stage commercialization, where pilot projects and partnerships dominate, and government support for sustainable materials accelerates adoption. It highlights innovation-driven competition, with emphasis on patents, advanced formulations, and bio-based processing techniques that differentiate players in this emerging industry. The Transparent Wood Market positions itself as a transformative segment in the broader sustainable materials landscape, driven by eco-innovation and high-performance applications.
Report Coverage
The research report offers an in-depth analysis based on Application, Material, Form, Transparency, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Transparent Wood Market will expand with rising demand for sustainable building materials in urban infrastructure projects.
- It will gain traction as a lightweight and stronger alternative to glass in architectural applications.
- Research on enhancing optical clarity and energy efficiency will accelerate adoption in windows and facades.
- It will find growing use in automotive design for lightweight panels and enhanced safety features.
- Consumer electronics manufacturers will integrate transparent wood in displays and casings for eco-friendly devices.
- Investment in large-scale production facilities will reduce costs and improve availability.
- Governments will support commercialization through funding and incentives for green materials.
- Partnerships between universities and industries will drive innovation and technology transfer.
- The market will diversify across regions with strong uptake in Europe, North America, and Asia-Pacific.
- It will strengthen its position in sustainable materials by aligning with circular economy initiatives.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Sustainable and Eco-Friendly Materials
Transparent wood is increasingly adopted as a renewable, recyclable alternative to glass and plastics, aligning with global sustainability goals and regulatory pressures for greener construction and manufacturing.
Superior Mechanical and Thermal Properties
The material offers higher impact resistance and better thermal insulation than conventional glass, making it attractive for energy-efficient buildings and safer, lighter automotive components.
Advancements in Research and Commercialization
Ongoing breakthroughs in nanotechnology, polymer science, and scalable production methods are reducing costs and improving the optical clarity and durability of transparent wood, accelerating its transition from laboratory to industrial applications.
Expansion into Construction and Automotive Industries
Transparent wood’s unique combination of strength, light weight, and energy efficiency is driving its adoption in innovative building designs and lightweight automotive parts, broadening its market base.
Integration into Smart and Green Infrastructure
The insulating and light-transmitting properties of transparent wood support its use in smart windows, facades, and energy-efficient infrastructure, meeting the growing demand for green buildings and smart city solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Transparent Wood, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Transparent Wood market projected to grow between 2025 and 2032?
Which Transparent Wood market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Transparent Wood market?
Who are the leading companies in the Transparent Wood market?
Which region commanded the largest share of the Transparent Wood market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Sheets
- 1.2.2 Panels
- 1.2.3 Films
- 1.3 By Material
- 1.3.1 Cellulose
- 1.3.2 Nanocellulose
- 1.3.3 Wood Composite
- 1.4 By Application
- 1.4.1 Construction
- 1.4.2 Furniture
- 1.4.3 Electronics
- 1.4.4 Packaging
- 1.5 By Transparency
- 1.5.1 High Transparency
- 1.5.2 Medium Transparency
- 1.5.3 Low Transparency
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,180 million → 2032: USD 3,737.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Transparent Wood Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Transparent Wood Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Transparent Wood Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Transparent Wood Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Transparent Wood Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Transparent Wood Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Transparent Wood Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Transparent Wood Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,180 million → 2032: USD 3,737.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Transparent Wood Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sheets
- 12.3.7.2 Panels
- 12.3.7.3 Films
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cellulose
- 12.4.7.2 Nanocellulose
- 12.4.7.3 Wood Composite
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Construction
- 12.5.7.2 Furniture
- 12.5.7.3 Electronics
- 12.5.7.4 Packaging
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Transparency - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 High Transparency
- 12.6.7.2 Medium Transparency
- 12.6.7.3 Low Transparency
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Transparent Wood End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Transparent Wood Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Transparent Wood Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Transparent Wood Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AkzoNobel
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Arbora
- 18.4 Granulo
- 18.5 Swiss Federal Laboratories for Materials Science and Technology (Empa)
- 18.6 RISE Research Institutes of Sweden
- 18.7 KTH Royal Institute of Technology
- 18.8 Chalmers University of Technology
- 18.9 University of Maryland
- 18.10 University of British Columbia
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

