
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Enteral Feeding Devices Market Size 2023 | USD 4551.32 Million |
| Enteral Feeding Devices Market, CAGR | 5.20% |
| Enteral Feeding Devices Market Size 2032 | USD 7182.55 Million |
Market Insights
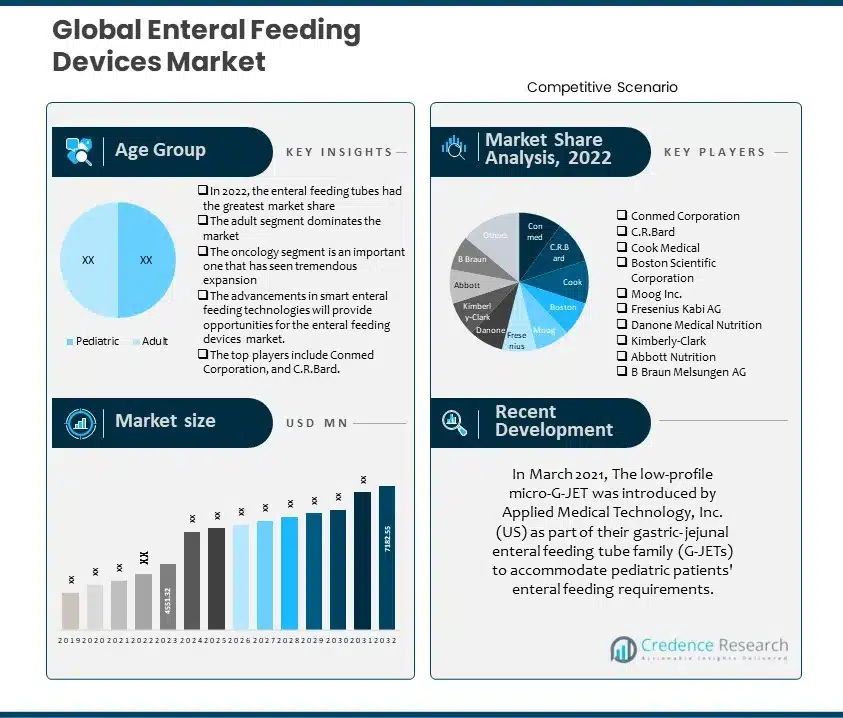
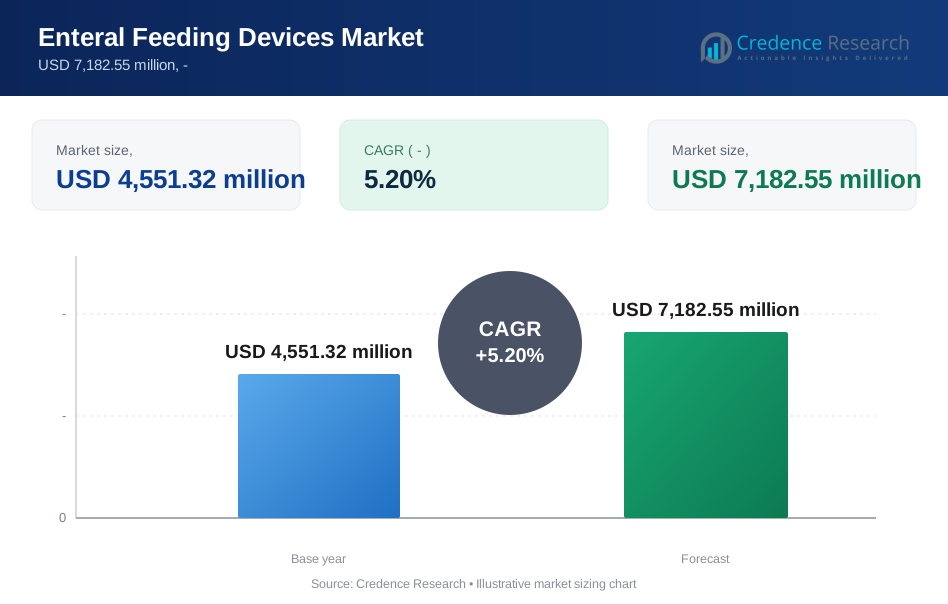
- Between 2024 and 2032, the global enteral feeding devices market is expected to develop at a compound annual growth rate (CAGR) of 5.20%, from its estimated USD 4551.32 million in 2023 to USD 7182.55 million in 2032.
- Enteral feeding tubes are a noteworthy product type category. On the other hand, enteral feeding pumps are expected to grow at a strong CAGR.
- The leading age group segment is adults.
- The CAGR for oncology is expected to be the highest during the projection period.
- The hospitals will have the highest CAGR throughout the prediction period.
- North America dominated the enteral feeding devices market.
- Regarding the market share of enteral feeding devices, Europe is expected to come second.
- Asia Pacific is anticipated to grow fastest in the enteral feeding devices market.
- The factors propelling the market's expansion are increasing surgical procedures, advantages over parenteral nutrition, increasing cancer incidence, and rising healthcare expenditure.
- Nutritional support in geriatric care, a growing focus on disposable and single-use devices, and the integration of nutritional supplements are the main opportunities for the enteral feeding devices market.
Executive Summary
Market Definition
The industry that includes medical devices intended to supply nutrients directly into the gastrointestinal system is known as the enteral feeding devices market. These are essential gadgets for patients with medical issues that prevent them from eating by mouth. Enteral nutrition solutions that are both safe and effective are offered via a variety of feeding tubes, pumps, and accessories available on the market. The rising prevalence of chronic illnesses and technological developments in healthcare are driving this market's growth.
Market Overview
The enteral feeding devices sector is estimated to develop at a 5.20% compound annual growth rate (CAGR) between 2024 and 2032, maintaining its current upward trend. The market will keep developing, rising from its estimated value of USD 4551.32 million in 2023 to USD 7182.55 million in 2032.
Increased cases of diabetes, severe pancreatitis, and other gastrointestinal disorders have been associated with an aging population, which supports market expansion. In the United States, subsidies for these devices are made possible by the adoption of the "Feed Early Enteral Diet Adequately for Maximum Effect" (FEED ME) protocol in surgical trauma ICUs. Technological developments like the launch of G-tubes with reverse balloon designs and J-tubes that replace G-tubes with tri-funnels are anticipated to support growth during the projection period.
People over 65 may be more susceptible to chronic illnesses, including Parkinson's and nervous system disorders, according to a number of NCBI research. It is projected that the number of people in the world who are 60 years of age or older will rise from approximately 1 billion in 2020 to approximately 1.4 billion in 2030, and that number will double by 2050 to approximately 2.1 billion. Over the past few years, there has been a noticeable increase in the number of older adults with serious illnesses. Because of numerous age-related changes in body composition and muscle mass, the risk of malnutrition and frailty is significantly higher among the older population with comorbidities such as stroke, depression, and dementia. As a result, there is an increased risk of falls or other accidents and a decreased capacity to conduct Activities of Daily Living.
Approximately 6 out of 10 persons, according to a CDC report, have at least one chronic illness. Because these devices are frequently used to provide nourishment to patients in critical care, the increasing number of surgeries performed worldwide also contributes to the growth of the market. An NCBI article claims that 310 million procedures are done annually on average throughout the world, offering potential for business expansion. Improvements in medical equipment, rising healthcare spending, and expanding healthcare infrastructure might all drive the market during the projected period.
Segmentation by Product Type
- Enteral feeding tubes are the market leader by product type. Enterostomy tubes are enteral feeding tubes placed directly into the stomach, duodenum, or jejunum through the abdominal wall. This can be done by various techniques, including endoscopy, laparoscopy, or open surgery. Typically, these tubes are utilized for prolonged enteral assistance, lasting longer than four weeks. Enterostomy feeding tube sales are anticipated to be driven by technological advancements like the creation of tri-funnel replacement enterostomy tubes and the introduction of reverse balloon designs.
- The enteral feeding pumps category will exhibit a sizable CAGR during the projected period. The purpose of enteral feeding pumps is to provide safer and easier-to-use nutritional care. Enteral feeding involves sending nutrients straight to the stomach via a tube that is attached to an electric pump. The medical devices segment's technical improvements and expanding healthcare infrastructure are anticipated to propel market expansion. Throughout the forecast period, technological improvements, such as the launch of small, dependable, and user-friendly devices like Covidien's Kangaroo ePump, are likely to increase demand for enteral feeding pumps.
- Other product types, including giving sets, enteral syringes, administration reservoirs, and accessories (extension sets, connectors, caps, etc.), also influence the need for enteral feeding devices.
Segmentation by Age Group
- The significant age group category is adult. Chronic illnesses and disorders, including cancer, multiple sclerosis, liver disease, motor neuron disease, Parkinson's disease, sepsis, anorexia, cystic fibrosis, dementia, and inflammatory bowel disease, are more common in adults than in children. The need for efficient nutrition management to maintain weight, enhance recovery, and improve treatment responses has grown due to the aging population and the rise in chronic illnesses. For these patients, tube feeding is advised because it lowers muscle catabolism, promotes overall healing and recovery, and preserves small intestinal mass and pancreatic functions. As a result, by age group, the adult category leads the worldwide market.
- The pediatric category will likely register a significant CAGR during forecasting. The WHO estimates that undernutrition accounts for about 45% of deaths among children under the age of five. In an annual report, UNICEF estimates that malnutrition claims the lives of about 3 million children. Infants are fed enterally using a variety of formulae, including jejunostomy tubes, nasojejunal, nasoduodenal, and gastrostomy.
Segmentation by Application
- The oncology category is projected to grow fastest over the projection period. Chemotherapy and radiation therapy are two examples of oncology treatments that can cause adverse effects like nausea, vomiting, and appetite loss. Patients who might have difficulty with oral intake during treatment can receive essential nutrients through the use of enteral feeding systems.
- Other applications, including gastroenterology, neurology, critical care, diabetes, geriatrics, and others, also influence the need for enteral feeding devices.
Segmentation by End User
- The hospitals category will likely have the highest CAGR during the projection period. Hospital demand for enteral feeding systems is predicted to increase due mainly to growing awareness of hospital-associated malnutrition among healthcare workers and others. Additional factors propelling the market's expansion include the rise in the number of ICU admissions and re-admissions, the need for enteral foods and formulations among patients who are critically or severely ill, and the rising prevalence of a number of chronic illnesses like diabetes, cancer, and others.
- Other end users, such as ambulatory surgical centers, long-term care centers, home care settings, and others, also contribute to the demand for enteral feeding devices.
Segmentation by Region
- North America leads the enteral feeding devices industry. Advanced medical technology is used in the region's hospitals, clinics, and other modern healthcare facilities. The integration of enteral feeding devices into standard patient care is made easier by this infrastructure.
- Europe is estimated to rank second in market size for enteral feeding devices.
- The enteral feeding devices industry is predicted to flourish rapidly in Asia Pacific.
- The remaining requirement for enteral feeding devices is covered by world regions such as Africa, the Middle East, and Latin America.
The industry's growth is driven by several factors, such as the expansion of enteral nutrition programs, increasing emphasis on personalized medicine, global increase in malnutrition cases, and government initiatives and support.
Based on projections, the market for enteral feeding devices is dominated by North America for several reasons. The regional market is growing due to an increase in the number of premature infants receiving critical care. For example, the CDC estimates that in 2021, almost 1 in 10 newborns in the United States were born premature. The growing elderly population is a major factor driving the market since they are more prone to chronic illnesses that cause a variety of ailments, including neurological, metabolic, and gastrointestinal issues.
The American Cancer Society has released data showing that there were around 26,380 new cases of stomach cancer in the country in 2022. 10,480 women and 15,900 males.) Approximately 11,090 persons died from this type of cancer (6,690 men and 4,400 women). Data indicate that the need for enteral feeding systems is anticipated to increase in the near future because patients with stomach cancer require enteral nutrition.
The enteral feeding devices market in Asia Pacific will expand fastest throughout the forecast. The region is home to a large geriatric population and patient pool. Several ailments, including diabetes, cancer, autoimmune diseases, and gastrointestinal disorders, are becoming more common as a result of changes in lifestyle. In the long run, this is predicted to raise the need for enteral feeding equipment for the nutritional management of chronic illnesses. A considerable portion of the older population in China and Japan is susceptible to chronic illnesses. Due to the higher prevalence of nutritional inadequacies in the elderly population, Asia Pacific is predicted to see increased demand for enteral feeding devices. Approximately 70% of malnourished children reside in Asia, according to World Hunger Education Service.
Furthermore, Japan also contributes to the healthcare industry, being at the forefront of technology applications. The impact of enteral feeding solutions for children with Crohn's disease has been studied by Japanese medical professionals. It is advised that the region follow suit in light of the excellent results. Enteral feeding device sales in the area will probably be boosted by this.
Key Highlights of the Report
The global enteral feeding devices market is segmented by product type, age group, application, end user, and region. Regarding product type, enteral feeding tubes are the market spearhead. Adult is the top age group category. The oncology category is anticipated to increase at the highest CAGR throughout the projection period. The hospitals category will experience the highest CAGR during the forecast period. The enteral feeding devices market is expanding mostly in North America.
Patients who have a viable and accessible gastrointestinal tract but are unable to eat or absorb enough food to stay adequately nourished and hydrated are fitted with enteral feeding systems. During periods of illness, trauma, or other medical procedures, enteral access feeding devices can be utilized to provide nutrients for optimal functioning. The growing patient population is suffering from dysphagia and other disorders. Enteral feeding systems, which enable patients to receive liquid nutrition, fluids, and medications straight into the gastrointestinal tract, are thus made possible for different manufacturers. For instance, the Journal of Translational Medicine article from April 2022 states that the estimated global prevalence rate of oropharyngeal dysphagia was 43.8%, with Africa having the highest incidence rate in 2021 at 64.2%.
The North American region is expected to account for the global largest enteral feeding devices market. North America has some of the greatest worldwide healthcare spending, especially between the US and Canada. The adoption of cutting-edge medical innovations, such as enteral feeding systems, is facilitated by this significant investment in healthcare services and infrastructure. The Asia Pacific is also assumed to have the market's sharpest growth. The Asia-Pacific region's governments are taking action to enhance healthcare facilities. Investments in medical infrastructure and supportive healthcare regulations foster an atmosphere favorable to the market expansion for enteral feeding devices.
Which Key Factors Are Driving The Global Enteral Feeding Devices Market?
The primary drivers of the enteral feeding devices market are the growing awareness of enteral nutrition, the aging population, the increasing rate of chronic illnesses, and technological improvement.
What Are The Main Challenges Confronting The Global Enteral Feeding Devices Market?
The biggest obstacles to the growth of the global enteral feeding devices industry are infection risks, tube dislodgement and misplacement, difficulty in device insertion, and complications in pediatric patients.
What Market Opportunities Exist For Enteral Feeding Devices Globally?
The factors propelling the enteral feeding devices market potential are rising demand for home enteral nutrition, advancements in smart enteral feeding technologies, customization of enteral feeding solutions, and increased adoption in rehabilitation centers.
Market Drivers
Multiple factors propel the enteral feeding devices industry across the globe. The primary factors propelling the global enteral feeding devices market are as follows:
Increasing Need for Enteral Feeding in Home Care Environments
Government policies that support and encourage the use of enteral nutritional supplements have been developed in several nations throughout the world as a result of the rising incidence of malnutrition. For example, because China has the second-largest undernourished population in the world, the government created the Healthy China 2030 program, with direct participation from the President of China, and created a National Nutrition Plan (2017–2030). Through optimal nutrition and diet intake, this program aims to prevent malnutrition, anemia, breastfeeding, obesity, and other medical disorders that are prevalent in the nation. Thus, the global increase in malnutrition instances and the increased government assistance are anticipated to drive the market growth for enteral feeding devices in the coming years.
Market Restraints
There are several obstacles that the global enteral feeding devices market must overcome to continue growing. Among them are the following:
Complications Related to Enteral Feeding Equipment
Some main issues with using an enteral feeding device are difficulties with initial placement, mechanical issues, clinical issues, and nutritional issues. These issues lead to higher healthcare costs. While the majority of enteral feeding-related problems are mild, some can be quite dangerous. Although enteral nutrition metabolic consequences are less common and less severe than parenteral nutrition difficulties, they are nonetheless highly similar. Tight observation can lessen or even stop these issues. However, the adoption of enteral feeding devices is hindered by these worries and the mortality related to these issues.
Opportunities
There are plenty of potential prospects in the global enteral feeding devices industry. Among these are the following:
Market Participants in Developing Countries Have Significant Growth Potential
In the coming years, market participants should anticipate finding substantial growth opportunities in the emerging economies of the Asia-Pacific region. This is mainly due to the region's diverse healthcare markets, rising infectious and chronic illness rates, and increased R&D efforts to create cutting-edge medical technologies. For example, in emerging nations like Brazil, China, and India, cancer is one of the most common diseases. In addition, Asia's growing economies record the highest number of premature births. Growing patient awareness of treatment alternatives and improvements in healthcare systems throughout Asia have led to a surge in the use of advanced nutritional therapy, which has driven the adoption of enteral feeding devices in emerging nations.
Competitive Landscape
Key Players
Several major competitors exist in the fiercely competitive global enteral feeding devices market. The following are a few of the leading market participants and their market shares:
- Conmed Corporation
- C.R.Bard
- Cook Medical
- Boston Scientific Corporation
- Moog Inc.
- Fresenius Kabi AG
- Danone Medical Nutrition
- Kimberly-Clark
- Abbott Nutrition
- B Braun Melsungen AG
- Avanos Medical, Inc.
- Cardinal Health
- Applied Medical Technology, Inc.
- Vygon India
- Fidmi Medical
- ALCOR Scientific
- Amsino International, Inc.
- Others
To remain competitive, these companies prioritize product innovation, distribution channel expansion, mergers, and acquisitions.
The largest suppliers in the global enteral feeding devices market continuously work to keep one step ahead of the competition by developing innovative concepts and products.
In November 2022, A collaboration between Ronald McDonald House Charities (US) and Medela AG (US) was announced. Medela announced a partnership with US-based non-profit Ronald McDonald House Charities to support its 60 programs worldwide by donating NICU supplies that fall under its breastfeeding business unit. This partnership is part of the company's commitment to fighting infant mortality and malnutrition.
In November 2022, The US FDA received the Amsino Medical Group Company 510(k) certification for their AMSafe NeuFlo Needleless Connector.
In March 2022, The acquisition of distributor Macatt Medica (Peru) was announced by Vygon (France). The acquisition is anticipated to increase Vygon's (France) footprint in South America, particularly given its extensive portfolio of enteral feeding products.
Summary of Key Findings
- The enteral feeding devices sector continues to grow due to increasing gastrointestinal disorders.
- The market is segmented by product type, age group, application, end user, and region.
- The most popular product type in the market is enteral feeding tubes.
- Adult is the foremost category.
- Oncology is expected to grow fastest regarding CAGR during the forecast period.
- The hospitals category will likely see the highest CAGR during the anticipated time frame.
- North America is leading market development; the market is highly competitive with key players including Conmed Corporation, C.R.Bard, Cook Medical, Boston Scientific Corporation, Moog Inc., Fresenius Kabi AG, Danone Medical Nutrition, Kimberly-Clark, Abbott Nutrition, B Braun Melsungen AG, Avanos Medical, Inc., Cardinal Health, Applied Medical Technology, Inc., Vygon India, Fidmi Medical, ALCOR Scientific, Amsino International, Inc., and Others.
Future Outlook
- The enteral feeding devices industry is expected to increase significantly in North America and has a positive outlook worldwide.
- Increased adoption in ambulatory care centers is contributing to the global expansion of the enteral feeding devices market.
- During the forecast duration, one of the main challenges expected to impede the enteral feeding devices market growth is the complications related to enteral feeding equipment.
- To stay ahead of the competition, key enterprises must develop new products, expand their market reach, and keep their prices competitive.
How CXOs Can Benefit from the Credence Research Enteral Feeding Devices Market Report
CXOs may get a detailed picture of the market in the Credence Research Enteral Feeding Devices Market Report, which includes:
- Market size and growth forecast: The report provides detailed estimates of the global enteral feeding devices market size, segmented by product type, age group, application, end user, and region. It also includes forecasts for the market through 2032 based on key trends and drivers.
- Market segmentation: The research report breaks down the market for enteral feeding devices into segments based on product type, age group, application, end user, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape: The research report offers a detailed analysis of the major companies in the enteral feeding devices industry, including information on their business plans, line of products, and earnings. CXOs can use this information to evaluate and identify their competitors.
- Key trends and drivers: The research report identifies and evaluates the main trends and factors influencing the market for enteral feeding devices. CXOs can use this information to make well-informed choices regarding their plans and investments.
CXOs can use the insights from the Credence Research Enteral Feeding Devices Market Report to:
- Identify growth opportunities: With the help of this analysis, CXOs may identify new growth opportunities in the enteral feeding devices sector. For example, the report identifies the growing demand for enteral feeding devices from hospitals and ambulatory surgical centers as a key opportunity.
- Make informed investment decisions: With the help of the report, CXOs can choose enteral feeding devices wisely. For example, the research study provides information on the critical factors to consider while selecting enteral feeding device solutions and evaluating suppliers.
- Develop competitive strategies: The research report can be used by CXOs to develop competitive strategies for their enteral feeding devices businesses. For example, the research paper outlines the main strategies suppliers of enteral feeding devices utilize to differentiate themselves from competitors.
- Track market developments: CXOs may stay ahead of the curve by tracking market developments with the aid of this research report. For instance, the research report offers insights into the most recent developments and trends in the market for enteral feeding devices.
In general, CXOs seeking to expand their industry knowledge and spot growth prospects will find the Credence Research Enteral Feeding Devices Market Report a useful tool.
Segmentation
- By Product Type
- Enteral Feeding Tubes
- Nasogastric Tubes (NG Tubes)
- Nasojejunal Tubes (NJ Tubes)
- Gastrostomy Tubes (G Tubes)
- Jejunostomy Tubes (J Tubes)
- Percutaneous Endoscopic Gastrostomy Tubes (PEG Tubes)
- Percutaneous Endoscopic Jejunostomy Tubes (PEJ Tubes)
- Others
- Enteral Feeding Pumps
- Gravity Feeding Sets
- Syringe Pumps
- Electric Feeding Pumps
- Ambulatory Feeding Pumps
- Others
- Giving Sets
- Enteral Syringes
- Administration Reservoirs
- Accessories (Extension Sets, Connectors, Caps, etc.)
- Enteral Feeding Tubes
- By Age Group
- Pediatric
- Adult
- By Application
- Oncology
- Gastroenterology
- Neurology
- Critical Care
- Diabetes
- Geriatrics
- Others
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Long-term Care Centers
- Home Care Settings
- Others
- By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- North America
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Diseases and Aging Population
The increasing incidence of chronic illnesses such as cancer, neurological disorders, and gastrointestinal diseases, particularly among the growing elderly population, is driving demand for enteral feeding devices as these patients often require nutritional support.
Technological Advancements in Enteral Feeding Devices
Innovations such as reverse balloon designs, tri-funnel tubes, and user-friendly enteral feeding pumps are making devices safer and easier to use, encouraging broader adoption in both hospital and home care settings.
Expansion of Healthcare Infrastructure and Expenditure
Rising healthcare spending and improvements in medical infrastructure, especially in emerging markets, are facilitating greater access to advanced enteral feeding solutions, supporting market growth.
Increased Surgical Procedures and ICU Admissions
The global rise in surgeries and critical care admissions, where patients frequently require enteral nutrition, is boosting the need for enteral feeding devices in hospitals and acute care settings.
Government Initiatives and Nutrition Programs
Supportive government policies and national nutrition programs, particularly in countries with high malnutrition rates, are promoting the adoption of enteral feeding devices to improve patient outcomes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How much does the global market currently hold for enteral feeding devices?
What is the enteral feeding devices market's projected growth rate between 2024 and 2032?
In terms of product type, which market category is leading?
Which end-user segment is estimated to have the highest CAGR throughout the forecast period?
Who are the main players in the global enteral feeding devices industry?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Ambulatory Surgical Centers
- 1.2.3 Long-term Care Centers
- 1.2.4 Home Care Settings
- 1.3 By Age Group
- 1.3.1 Pediatric
- 1.3.2 Adult
- 1.4 By Application
- 1.4.1 Oncology
- 1.4.2 Gastroenterology
- 1.4.3 Neurology
- 1.4.4 Critical Care
- 1.4.5 Diabetes
- 1.4.6 Geriatrics
- 1.5 By Product Type
- 1.5.1 Enteral Feeding Tubes
- 1.5.2 Enteral Feeding Pumps
- 1.5.3 Giving Sets
- 1.5.4 Enteral Syringes
- 1.5.5 Accessories
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 4,551.32 million → 2032: USD 7,182.55 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Enteral Feeding Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Enteral Feeding Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Enteral Feeding Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Enteral Feeding Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Enteral Feeding Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Enteral Feeding Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Enteral Feeding Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Enteral Feeding Devices Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 4,551.32 million → 2032: USD 7,182.55 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Enteral Feeding Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Ambulatory Surgical Centers
- 12.3.7.3 Long-term Care Centers
- 12.3.7.4 Home Care Settings
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Age Group - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pediatric
- 12.4.7.2 Adult
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oncology
- 12.5.7.2 Gastroenterology
- 12.5.7.3 Neurology
- 12.5.7.4 Critical Care
- 12.5.7.5 Diabetes
- 12.5.7.6 Geriatrics
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Enteral Feeding Tubes
- 12.6.7.2 Enteral Feeding Pumps
- 12.6.7.3 Giving Sets
- 12.6.7.4 Enteral Syringes
- 12.6.7.5 Accessories
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Enteral Feeding Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Enteral Feeding Devices Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Enteral Feeding Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Enteral Feeding Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Fresenius Kabi AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Abbott Nutrition
- 18.4 Boston Scientific Corporation
- 18.5 Moog Inc.
- 18.6 B Braun Melsungen AG
- 18.7 Cardinal Health
- 18.8 Avanos Medical, Inc.
- 18.9 Cook Medical
- 18.10 Conmed Corporation
- 18.11 Vygon
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

