
Market Overview:
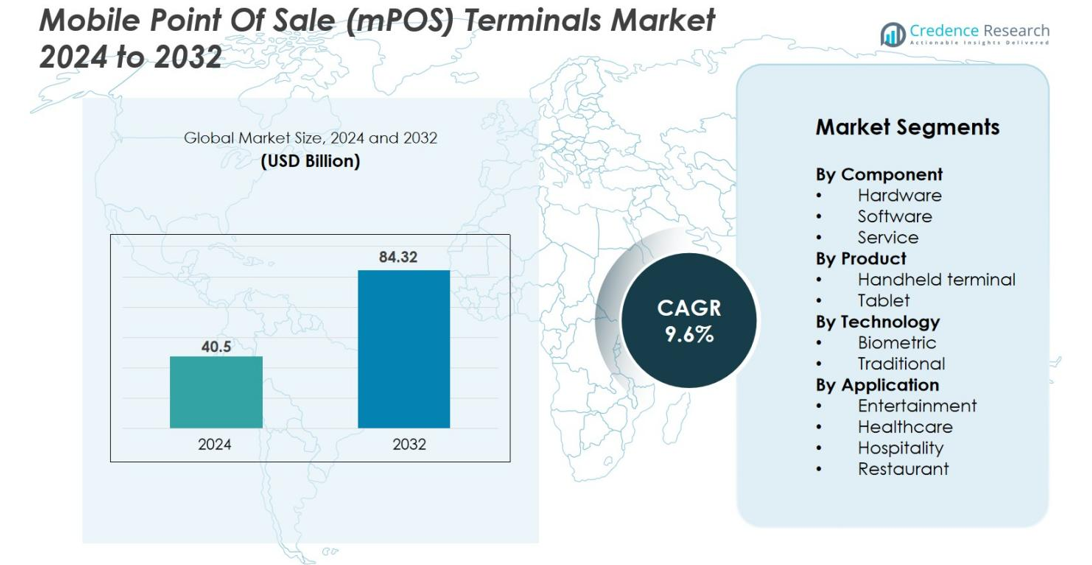
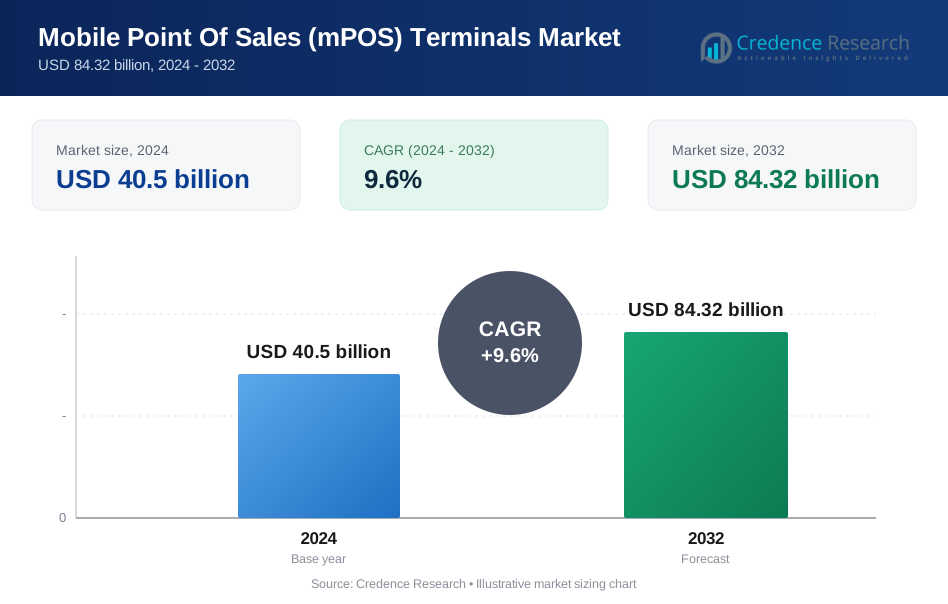
The Mobile Point of Sale (mPOS) Terminals Market size was valued at USD 40.5 billion in 2024 and is anticipated to reach USD 84.32 billion by 2032, growing at a CAGR of 9.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mobile Point of Sale (mPOS) Terminals MarketSize 2024 | USD 40.5 billion |
| Mobile Point of Sale (mPOS) Terminals Market, CAGR | 9.6% |
| Mobile Point of Sale (mPOS) Terminals Market Size 2032 | USD 84.32 billion |
The Mobile Point of Sale (mPOS) Terminals Market is led by key players such as Square, Inc., Ingenico Group, VeriFone Systems, Inc., PAX Technology, NEC Corporation, NCR Corporation, Diebold Nixdorf, Epicor Software Corporation, Panasonic Corporation, and MICROS Systems, Inc.. These companies have established themselves through innovation in both hardware and software, with a strong focus on enhancing mobility, contactless payments, and customer analytics. In 2024, the Asia-Pacific region holds the largest market share at 30.6%, driven by high smartphone penetration and a growing number of micro-merchants adopting mobile payment solutions. Europe follows with a 24.3% share, and North America holds 13.4%, fueled by robust retail infrastructure and widespread adoption of NFC-enabled payments. The increasing integration of cloud solutions and biometric authentication is expected to further accelerate mPOS growth globally.
Market Insights
- The Mobile Point Of Sale (mPOS) Terminals Market size reached USD 40.5 billion in 2024 and is projected to grow at a CAGR of 9.6% to USD 84.32 billion by 2032.
- The hardware component segment held 63% of the market share in 2024, driven by widespread portable payment device deployment.
- Asia‑Pacific accounted for 30.6% of global market share in 2024, while Europe held 24.3% and North America 13.4%, underscoring regional dominance of digital‑payments growth.
- Cloud‑based and software‑driven mPOS solutions are gaining traction as merchants look for scalable, subscription‑based models and real‑time integrations.
- Data security concerns, fraud risk and complex ecosystem interoperability are acting as restraints that may slow down market adoption in certain regions.
Market Segmentation Analysis
By Component
In the component segmentation of the mPOS terminals market, the hardware sub‑segment is dominant, capturing 63% of the market share in 2024. This leadership stems from the widespread deployment of portable payment devices that enable retailers and service businesses to reduce checkout time and support mobile, contactless transactions. Key drivers include the rising acceptance of EMV chip and NFC‑enabled payments, and the proliferation of compact terminals by providers such as VeriFone Inc. and Ingenico Group. The software and service segments are gaining momentum, though hardware retains the bulk of revenue due to the immediate need for physical terminals.
- For instance, VeriFone offers a broad range of compact and rugged hardware including countertop, mobile, and portable terminals with EMV chip, NFC, and Bluetooth capabilities, widely deployed in retail and hospitality sectors.
By Product
Under the product segmentation, handheld terminals hold the lead with 45% share of the market by 2032 due to their compact form factor and suitability for mobile, curb‑side, and SMB environments. The appeal of handheld devices lies in their portability and ability to integrate card readers, mobile wallets, and business apps in one unit. In contrast, tablets are gaining traction in large‑scale retail and hospitality settings for their richer interfaces and application‑integration capabilities. The dominance of handhelds is grounded in the mobility demand from merchants seeking flexible payment processing solutions.
- For instance, handheld devices integrate card readers, mobile wallet support, and business apps in a single unit, allowing merchants to process payments on the go efficiently.
By Technology
In the technology segmentation, the traditional technology sub‑segment (i.e., conventional card readers, magnetic stripe/NFC readers) remains the dominant share, accounting for 36.8% of the market in 2024. This reflects the current prevalence of conventional and contactless payment infrastructures in merchant environments. At the same time, the biometric sub‑segment (such as fingerprint, facial recognition, etc.) is emerging fast-driven by rising concerns over fraud, regulatory mandates for secure transactions, and the demand for a seamless customer experience. While biometric’s share is still smaller, it is growing at a higher CAGR, signaling a shift toward more secure authentication technologies in mPOS systems.
Key Growth Drivers
Rapid smartphone and mobile‑connectivity penetration
The expansion of affordable smartphones and enhanced mobile connectivity underpins growth in the mPOS terminals market. As both Android and iOS devices now support mobile payment applications natively, micro‑merchants and small businesses increasingly adopt mPOS solutions with minimal infrastructure investment. This shift enables broader outreach beyond traditional retail settings into pop‑up stores, food trucks, and remote service locations. The confluence of high smartphone ownership and faster mobile networks sets the stage for accelerated mPOS uptake and drives market expansion globally.
- For instance, Android devices natively support Google Pay, while iOS devices natively support Apple Pay, enabling micro-merchants and small businesses to adopt mPOS solutions with minimal setup costs.
Surge in digital payments and contactless transactions
The increasing consumer preference for contactless payments, digital wallets and cashless commerce is a strong growth driver for the mPOS terminals market. Businesses are responding by deploying mobile POS solutions that support NFC, QR‑code and biometric methods to meet evolving payment behaviour. This trend is reinforced by regulatory mandates and cash‑reduction strategies across regions. As consumers demand faster, seamless checkout experiences, merchants invest in mPOS hardware and software to enable omnichannel and mobile‑first payment flows, thereby expanding the market.
- For instance, India's Unified Payments Interface (UPI) transactions surged 35% year-over-year in the first half of 2025, reaching 106.36 billion transactions, with a value of ₹143.34 trillion, driven by PIN-less and biometric innovations.
SME digitisation and business process automation
Small and medium‑sized enterprises (SMEs) are increasingly digitising their operations, which boosts demand for mPOS terminals. These systems not only handle transactions but integrate with inventory, CRM and analytics platforms, enabling streamlined operations and data‑driven insights. The need to reduce manual intervention, cut operational costs and deliver improved customer experience drives SME adoption of mPOS solutions. With many SMEs treating POS as an operating expense rather than capital investment, uptake is widening and propelling market growth.
Key Trends & Opportunities
Cloud‑based and software‑driven mPOS evolution
The transition from stand‑alone hardware to cloud‑connected and software‑driven mPOS solutions presents a major opportunity. Cloud deployments, which accounted for approximately 29.7% of the market in 2024, enable subscription models, real‑time updates, and integration with broader business systems. Merchants benefit from scalability, lower upfront costs and remote management while vendors gain recurring revenue streams. This trend opens avenues for vertical‑specific solutions, multi‑site roll‑outs and service‑oriented ecosystems, making the mPOS market ripe for innovation.
- For instance, Lightspeed Retail offers a cloud-based POS system that provides advanced inventory management and customizable reporting, enabling retailers to manage complex inventories at scale with remote oversight.
Emerging markets and underserved merchant segments
High growth potential exists in emerging regions such as Asia‑Pacific, where the market share reached about 30.6% in 2024 and continues to grow at double‑digit CAGRs. Many micro‑merchants in these regions still lack access to formal POS infrastructure, creating an opportunity for low‑cost mPOS devices and mobile‑first payment solutions. Vendors can capture new addressable markets by offering affordable terminals, enabling digital payments for street vendors, small kiosks and service providers and tapping into financial inclusion initiatives and government‑led digital‑payment programs.
- For instance, in China, tech giants Alibaba and Tencent have led QR code-based mPOS implementations, making mobile payments dominant in informal sectors.
Key Challenges
Data security, fraud and regulatory compliance
As mPOS terminals process sensitive payment and personal data, security concerns pose a major market challenge. Weak encryption, device vulnerabilities and network risks create exposure for merchants and service providers. Additionally, evolving regulatory mandates (e.g., PSD2 SCA in Europe) impose compliance burdens on both hardware and software vendors. Addressing these security and regulatory issues without eroding ease‑of‑use remains critical for market players to build trust and drive adoption.
Fragmentation and interoperability of payment ecosystems
The mPOS market faces complexity from varied hardware standards, connectivity protocols and regional regulatory frameworks. Devices must support magnetic stripe, EMV chip, NFC, QR‑code, and increasingly biometric authentication-while integrating with servers, cloud services and local banking systems. This fragmentation slows deployment and raises costs for vendors and merchants. Without standardised interoperability and streamlined certification processes, some potential users hesitate to adopt mPOS solutions, limiting market scale‑up in certain areas.
Regional Analysis
North America
The North America region accounted for a 13.4% share of the global mobile Point of Sale (mPOS) terminals market in 2024. The region’s mature retail landscape and rapid adoption of contactless payment methods drive demand for mobile and portable POS devices. Merchants increasingly integrate mPOS terminals with inventory management and CRM systems to support omnichannel operations. Large‑scale chain stores, quick‑service restaurants, and mobile services are major adopters. Regulatory compliance (such as PCI DSS and EMV) and high penetration of smartphones and NFC‑enabled cards further bolster market growth.
Europe
Europe holds a 24.3% share of the global mPOS terminals market in 2024. The region's advanced payment infrastructure and strong merchant networks support substantial growth. The widespread deployment of cloud-connected and NFC-enabled mPOS devices is notable, especially in retail and hospitality sectors. The implementation of open-loop transit payments and POS-fiscal integration mandates across several countries accelerates terminal refresh cycles. While growth in key European countries like the UK, Germany, and France leads the way, a focus on cross-border certification and multi-currency support strengthens the region’s market presence.
Asia-Pacific
Asia-Pacific commanded a 30.6% share of the global mPOS terminals market in 2024. Rapid smartphone penetration, government-led digital payment initiatives, and high adoption among micro-merchants drive the region's dominance. In emerging markets like India and Southeast Asia, incentives targeting small and medium enterprises spur large-scale deployment of mPOS devices. The region also leads in contactless and QR-based payment usage. Expansion in e-commerce, mobile wallets, and rural acceptance terminals contribute to the region's sustained growth across retail, transportation, and service sectors.
Middle East & Africa (MEA)
The Middle East & Africa (MEA) region holds a 7.2% share of the global mPOS terminals market in 2024. Increasing financial inclusion programs, rising tourism, and the proliferation of mobile connectivity are key drivers in the region. Local acquirers and fintech companies are boosting adoption of low-cost handheld and smartphone-based mPOS solutions in retail and roadside services. Although the region's current market share remains smaller compared to others, MEA is seeing rapid growth driven by the transition from cash to digital payments.
Market Segmentations
By Component
- Hardware
- Software
- Service
By Product
- Handheld terminal
- Tablet
By Technology
- Biometric
- Traditional
By Application
- Entertainment
- Healthcare
- Hospitality
- Restaurant
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The global mPOS terminals market features a competitive environment led by key players such as Diebold Nixdorf, Epicor Software Corporation, Ingenico Group, PAX Technology, Square, Inc. and VeriFone Systems, Inc.. These companies differentiate through hardware innovation, software‑platform enhancements and integrated service offerings, responding to evolving merchant needs for mobility, contactless payments and analytics. They maintain extensive global distribution networks and engage in strategic partnerships (for example device manufacturers aligning with acquirers) to expand market reach across regions. The competitive dynamics drive continuous product refresh cycles, especially in emerging markets where device affordability and cloud‑connectivity matter. Meanwhile, margins are pressured by commoditisation of terminal hardware, prompting vendors to shift up‑the‑stack into value‑added services such as subscription based software, analytics and managed services. As the ecosystem evolves, vendors with scalable platforms, strong security credentials and broad merchant‑acquirer linkages are best positioned to secure volume and capture recurring revenue streams.
Key Player Analysis
- Square, Inc.
- PAX Technology
- Ingenico Group
- NEC Corporation
- NCR Corporation
- VeriFone Systems, Inc.
- Micros Systems, Inc.
- Panasonic Corporation
- Epicor Software Corporation
- Diebold Nixdor
Recent Developments
- In September 2025, Worldline partnered with Mypinpad to enable SoftPOS (software-based POS) acceptance on Android devices across South Asia.
- In June 2024, Posiflex Technology Inc. launched the Opera MT-6200 Series mobile POS tablets.
- In September 2024, Newland Payment Technology Ltd. expanded its European footprint by acquiring the terminal business of its partner NewNote in France and Spain.
Report Coverage
The research report offers an in-depth analysis based on Component, Product, Technology, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as small and micro‑merchants in emerging economies increasingly adopt mobile POS terminals for low‑cost payments.
- Cloud‑based and SaaS‑driven mPOS platforms will gain ground, enabling merchants to deploy terminals with minimal upfront hardware investment and rapid scalability.
- Integration of biometric authentication (such as fingerprint and facial recognition) will become more common, enhancing security and reducing fraud in mobile payment transactions.
- The continued shift from cash to contactless and mobile wallet payments will accelerate demand for mPOS terminals that support NFC, QR code and tap‑to‑pay methods.
- Hardware manufacturers will increasingly bundle value‑added services (analytics, loyalty programmes, inventory tracking) with mPOS devices to capture recurring revenue and differentiate offerings.
- Tablet‑based and smartphone‑based mPOS solutions will penetrate new environments such as home‑services, field‑sales and mobile merchants, broadening the use‑case beyond traditional retail.
- In regions with lower banking infrastructure, mPOS adoption will be driven by financial‑inclusion initiatives and government‑led digital‑payment programmes targeting unbanked populations.
- Vendors will face mounting pressure to ensure interoperability, seamless integration with acquirer/processor networks and multi‑currency support as cross‑border commerce expands.
- Amid hardware commoditisation, providers will compete on software ecosystems and subscription models; thus margins will shift from hardware sales to software and services.
- Regulatory and cybersecurity requirements will intensify, prompting mPOS vendors to invest in advanced encryption, tokenisation and certification processes to maintain compliance and merchant trust.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid smartphone and mobile-connectivity penetration
The widespread availability of affordable smartphones and improved mobile connectivity enables micro-merchants and small businesses to adopt mPOS solutions with minimal infrastructure, expanding the market beyond traditional retail into new environments such as pop-up stores and remote services.
Surge in digital payments and contactless transactions
Consumer preference for contactless payments, digital wallets, and cashless commerce is driving businesses to deploy mPOS terminals that support NFC, QR-code, and biometric methods, accelerating market growth as merchants respond to evolving payment behaviors.
SME digitisation and business process automation
Small and medium-sized enterprises are digitizing operations and integrating mPOS terminals with inventory, CRM, and analytics platforms, reducing manual processes and operational costs while improving customer experience, thus boosting mPOS adoption.
Cloud-based and software-driven mPOS evolution
The shift to cloud-connected and software-driven mPOS solutions allows merchants to benefit from scalable, subscription-based models and real-time integrations, lowering upfront costs and enabling rapid deployment, which is expanding the addressable market.
Financial inclusion and government-led digital payment initiatives
In emerging markets, government programs and financial inclusion initiatives are promoting the adoption of low-cost mPOS devices among micro-merchants and unbanked populations, driving significant market expansion in regions with previously limited access to formal POS infrastructure.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Mobile Point of Sales (mPOS) Terminals market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Mobile Point of Sales (mPOS) Terminals market projected to grow between 2025 and 2032?
Which Mobile Point of Sales (mPOS) Terminals market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Mobile Point of Sales (mPOS) Terminals market?
Who are the leading companies in the Mobile Point of Sales (mPOS) Terminals market?
Which region commanded the largest share of the Mobile Point of Sales (mPOS) Terminals market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Handheld terminal
- 1.2.2 Tablet
- 1.3 By Component
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Service
- 1.4 By Technology
- 1.4.1 Biometric
- 1.4.2 Traditional
- 1.5 By Application
- 1.5.1 Entertainment
- 1.5.2 Healthcare
- 1.5.3 Hospitality
- 1.5.4 Restaurant
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 40.5 billion → 2032: USD 84.32 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Mobile Point Of Sales (mPOS) Terminals Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Mobile Point Of Sales (mPOS) Terminals Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Mobile Point Of Sales (mPOS) Terminals Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Mobile Point Of Sales (mPOS) Terminals Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Mobile Point Of Sales (mPOS) Terminals Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Mobile Point Of Sales (mPOS) Terminals Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Mobile Point Of Sales (mPOS) Terminals Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Mobile Point Of Sales (mPOS) Terminals Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 40.5 billion → 2032: USD 84.32 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Mobile Point Of Sales (mPOS) Terminals Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Handheld terminal
- 12.3.7.2 Tablet
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Service
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Biometric
- 12.5.7.2 Traditional
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Entertainment
- 12.6.7.2 Healthcare
- 12.6.7.3 Hospitality
- 12.6.7.4 Restaurant
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Mobile Point Of Sales (mPOS) Terminals End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Mobile Point Of Sales (mPOS) Terminals Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Mobile Point Of Sales (mPOS) Terminals Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Mobile Point Of Sales (mPOS) Terminals Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Square, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ingenico Group
- 18.4 VeriFone Systems, Inc.
- 18.5 PAX Technology
- 18.6 NEC Corporation
- 18.7 NCR Corporation
- 18.8 Diebold Nixdorf
- 18.9 Epicor Software Corporation
- 18.10 Panasonic Corporation
- 18.11 MICROS Systems, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

