
3D Printing Plastics Market Overview:
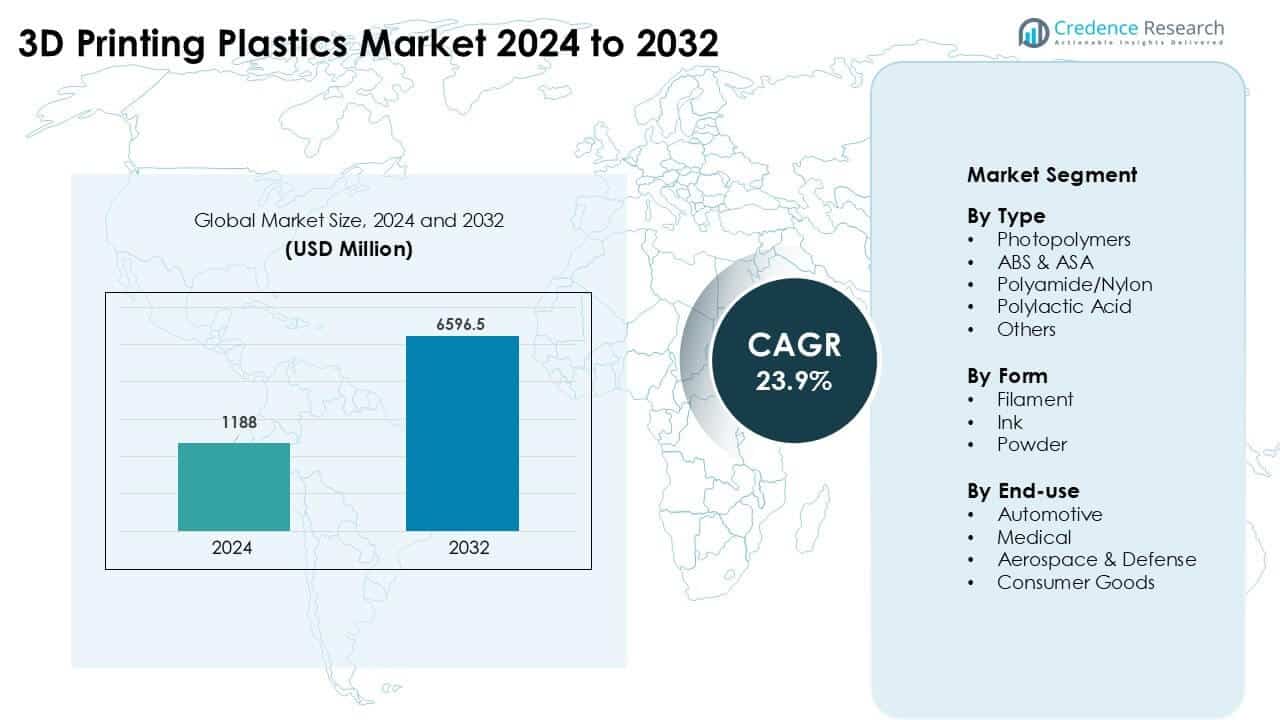
3D Printing Plastics Market was valued at USD 1188 million in 2024 and is anticipated to reach USD 6596.5 million by 2032, growing at a CAGR of 23.9 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| 3D Printing Plastics Market Size 2024 | USD 1188 million |
| 3D Printing Plastics Market, CAGR | 23.9 % |
| 3D Printing Plastics Market Size 2032 | USD 6596.5 million |
3D Printing Plastics Market Insights
- Demand rises as automotive, medical, and aerospace sectors adopt additive manufacturing for faster prototyping and lightweight part production.
- Key trends include the shift toward high-performance polymers, growing use of sustainable materials, and expansion of on-demand manufacturing for customized components.
- Competitive activity strengthens as HP Inc., SABIC, Royal DSM N.V., Stratasys Ltd., and others invest in advanced engineered polymers and integrated printing solutions.
- North America leads with 38% share, Europe follows with 30%, while filaments hold the largest segment share at 52% due to strong industrial and consumer use.
3D Printing Plastics Market Segmentation Analysis:
By Type
Photopolymers lead the 3D Printing Plastics market with about 41% share in 2024 due to strong use in precision parts, dental models, and prototyping. Demand grows as manufacturers adopt SLA and DLP systems for smooth surface finishes and fine details. ABS & ASA follow because engineering teams prefer durable materials for functional testing. Polyamide/nylon supports high-strength applications in aerospace and automotive. Polylactic acid remains common in desktop printers, while others fill niche industrial needs. The segment expands as material developers improve heat resistance and mechanical stability for end-use components.
- For instance, The typical Young's (tensile) Modulus for standard Ultrafuse PLA is approximately 2,308 MPa in the XY printing direction, as verified by ISO 527 testing.
By Form
Filament dominates the market with nearly 52% share in 2024, driven by broad adoption in FDM printers and steady use across consumer, education, and industrial sectors. Filament suits rapid prototyping, tooling, and light-duty end-use parts. Powder usage rises with SLS technology due to strong mechanical strength and design freedom. Ink-based formats grow in specialized applications such as multimaterial and color prototyping. Demand strengthens as companies scale powder-based production for higher accuracy and repeatability in complex geometries.
- For instance, Materialise scaled powder-based production by achieving repeatability variance below 5 microns across large SLS batches in certified facilities. The company processed more than 1.8 million polymer parts annually for industrial clients. Its workflow software also handled over 30 million build preparation operations in a single year.
By End-Use
Automotive holds the largest share at about 35% in 2024, supported by rapid prototyping, lightweight design, and small-batch production for interior components and brackets. Automakers rely on durable polymers to shorten development cycles and reduce tooling costs. Medical applications expand with rising adoption of biocompatible polymers for anatomical models and surgical guides. Aerospace and defense demand increases due to weight reduction needs and certification of high-performance polymers. Consumer goods benefit from customization trends, but industrial users remain the primary revenue source.
Key Growth Drivers
Rising Adoption of Additive Manufacturing in End-Use Industries
Growing use of additive manufacturing in automotive, medical, aerospace, and consumer goods drives strong demand for 3D printing plastics. Companies use these materials to cut production time, reduce tooling costs, and create lighter parts. Automakers rely on polymers for prototypes and custom fixtures, while aerospace firms adopt high-strength plastics for lightweight components. Medical professionals now use biocompatible materials for surgical models and patient-specific devices. This cross-industry adoption strengthens material innovation and supports higher-volume production. The trend increases the need for reliable, high-performance polymers that deliver accuracy and repeatability across complex designs.
- For instance, Procter & Gamble uses filament and powder-based AM systems to fabricate tooling and consumer product prototypes, producing more than 700,000 printed parts annually across global design hubs. Its AM workflows reduced tooling lead times from 4 weeks to 1 week, verified in internal manufacturing optimization audits.
Advancements in Material Engineering and Polymer Performance
Rapid improvements in polymer chemistry fuel the market growth by enabling stronger, more durable, and heat-resistant 3D printing plastics. Material suppliers develop engineered polymers that match metal-like properties for specific loads and stress environments. These innovations open new uses in electric vehicles, aircraft interiors, and precision medical tools. Manufacturers also explore composite plastics reinforced with carbon fiber and glass fiber to boost stiffness and reduce weight. Better thermal stability and chemical resistance help expand adoption in manufacturing and tooling. Advancements support consistent part quality, making plastics suitable for both prototyping and end-use functions.
- For instance, Arkema improved its specialty PA11 and PA12 grades for SLS printing, achieving elongation-at-break values up to 200 %, validated for sports and industrial products. Arkema’s materials are used by more than 100 service bureaus worldwide. The company’s R&D labs processed over 1,000 tons of AM polymer powder in the previous full year.
Expansion of Industrial-Scale 3D Printing Systems
Increased deployment of industrial 3D printers accelerates the demand for compatible plastics. Large manufacturers implement additive systems on production floors to support batch manufacturing, reducing reliance on traditional machining. High-speed printers boost throughput and allow complex part geometries in a shorter cycle. Powder-based and high-temperature polymer systems gain traction as companies scale additive workflows. Industries adopt automated material handling, quality control software, and integrated printing systems, which increases polymer consumption. This shift toward mass customization and digital production workflows strengthens long-term demand for advanced 3D printing plastics.
Key Trend & Opportunity
Shift Toward High-Performance and Sustainable Polymers
The market sees strong movement toward high-performance plastics such as reinforced nylon, PEKK, and PEEK, driven by aerospace and medical approval needs. Companies seek materials that deliver strength, heat tolerance, and reliability in critical components. Sustainable bioplastics also present large potential as brands focus on lowering carbon impact. PLA, recycled composites, and bio-based photopolymers support eco-friendly production goals. These materials attract users in consumer goods, healthcare, and packaging. Growing R&D spending helps accelerate adoption of recyclable and renewable polymers, creating opportunities for suppliers that offer certified sustainable materials.
- For instance: DSM (now part of Covestro) advanced its Arnite AM materials with heat deflection temperatures above 140 °C and tensile modulus exceeding 3,000 MPa. The company’s bio-based SLA resin passed ISO 10993 cytotoxicity testing for medical use. DSM also validated recycled polymer grades that reduce material footprint by up to 60 %, based on lifecycle assessments.
Growth of Customized Manufacturing and On-Demand Production
Rising demand for customized devices, spare parts, and consumer products creates strong opportunities for 3D printing plastics. Companies use additive manufacturing to replace warehouse inventory with digital storage and on-demand production. Medical providers benefit from one-off implants, dental models, and patient-fit tools. Automotive suppliers use mass customization for interior components and functional prototypes. Retail brands explore personalized goods, helping drive polymer consumption. This shift supports expertise in fast-turnaround production and encourages investment in advanced polymer grades that maintain quality while enabling flexible manufacturing across industries.
- For instance, GE Additive helped industrial clients reduce spare-part storage by digitizing more than 10,000 part files for on-demand polymer and metal printing. Its validated AM parts passed 30,000-cycle fatigue tests for aerospace maintenance programs. GE’s polymer AM labs operate 70+ production-grade machines.
Key Challenge
Material Performance Limitations in High-Stress Applications
Many 3D printing plastics still face structural and thermal limits that restrict adoption in heavy-load or high-temperature environments. Industries like aerospace, automotive, and defense often require mechanical properties that approach metal-like performance. While advanced polymers exist, they remain costly and difficult to process. Material instability during prolonged stress, moisture absorption, and limited long-term durability create concerns for end-use deployment. Certification requirements also hinder adoption because plastics must meet strict safety and compliance standards. These constraints slow full-scale integration and reduce the use of plastics in mission-critical components.
High Material Costs and Limited Scalability for Mass Production
3D printing plastics remain more expensive than conventional manufacturing materials, especially engineered polymers and powder-based plastics. High costs limit large-scale adoption in price-sensitive industries. Production scalability also creates challenges because many printers operate slower than traditional molding lines. Manufacturers face cost barriers in acquiring industrial equipment, maintaining consistent material quality, and integrating additive workflows into existing processes. These issues delay widespread adoption for mass manufacturing and push companies to restrict polymer usage to prototypes or small volumes. Reducing costs and improving supply chains remain priorities for broader market growth.
Regional Analysis
North America
North America leads the 3D Printing Plastics market with about 38% share in 2024, supported by strong adoption across aerospace, medical, and automotive sectors. The region benefits from advanced R&D, a mature additive manufacturing ecosystem, and high investment in industrial 3D printers. Major manufacturers use engineered polymers for prototyping and end-use parts. Hospitals and dental labs expand usage of biocompatible plastics for patient-specific models. The U.S. drives most demand due to large-scale manufacturing programs and strong material innovation. Growing partnerships between printer makers and polymer suppliers further strengthen regional growth.
Europe
Europe holds roughly 30% market share in 2024, driven by strong aerospace, automotive, and industrial engineering activity. Germany, the U.K., and France lead adoption as companies integrate additive manufacturing into production workflows. The region focuses on sustainability, boosting demand for recyclable and bio-based polymers. Aerospace firms rely on high-performance plastics, while automakers use engineered polymers for lightweight parts and tooling. Supportive government programs and research consortiums help expand commercial use. Europe’s strict quality standards encourage the development of advanced materials that meet structural and regulatory requirements in key industries.
Asia Pacific
Asia Pacific accounts for about 25% market share in 2024, showing rapid growth due to expanding electronics, automotive, and healthcare sectors. China, Japan, and South Korea invest heavily in additive manufacturing technologies and high-performance polymers. Manufacturers adopt plastics for faster prototyping, custom components, and tool optimization. Medical 3D printing rises with strong demand for anatomical models and dental applications. Local material suppliers increase production capacity to meet industrial needs. Government-supported innovation hubs and rising adoption in consumer goods manufacturing make Asia Pacific one of the fastest-growing regions.
Latin America
Latin America holds nearly 4% market share in 2024, with growing adoption in education, prototyping, and small-scale manufacturing. Brazil and Mexico lead the region as industries explore 3D-printed plastics for automotive parts, dental models, and consumer goods. Affordable desktop printers support early-stage adoption among designers and start-ups. Industrial use remains limited due to cost barriers, but interest increases as companies seek flexible and low-volume production options. Expansion of local service bureaus and government interest in technology-driven manufacturing help support gradual market growth.
Middle East & Africa
The Middle East & Africa region represents about 3% market share in 2024, driven primarily by adoption in healthcare, construction prototyping, and industrial training centers. Countries like the UAE and Saudi Arabia invest in advanced manufacturing programs that include 3D-printed plastics for medical devices and functional parts. Universities and research labs expand usage for design development. Industrial adoption grows slowly due to limited large-scale production facilities, but demand rises for custom components and lightweight prototypes. Government-backed innovation initiatives continue to improve regional awareness and infrastructure for polymer-based additive manufacturing.
3D Printing Plastics Market Segmentations:
By Type
- Photopolymers
- ABS & ASA
- Polyamide/Nylon
- Polylactic Acid
- Others
By Form
- Filament
- Ink
- Powder
By End-use
- Automotive
- Medical
- Aerospace & Defense
- Consumer Goods
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The 3D Printing Plastics market features strong competition from global material innovators and additive manufacturing leaders such as HP Inc., SABIC, Royal DSM N.V., Stratasys Ltd., Arkema Inc., Materialise NV, PolyOne Corporation, EnvisionTEC Inc., EOS GmbH Electro Optical Systems, and 3D Systems Corporation. These companies focus on engineered polymers, high-performance composites, and application-specific materials that support industrial-grade printing. Many players expand portfolios with heat-resistant nylons, reinforced blends, and biocompatible photopolymers to meet rising demand in aerospace, automotive, and healthcare. Partnerships with printer manufacturers strengthen product performance and improve compatibility. Firms also invest in R&D to enhance mechanical strength, accuracy, and recyclable material options. Growing interest in customized manufacturing pushes companies to develop integrated solutions that combine materials, hardware, and software.
Key Player Analysis
- HP Inc.
- SABIC
- Royal DSM N.V.
- Stratasys Ltd.
- Arkema Inc.
- Materialise NV
- PolyOne Corporation
- EnvisionTEC Inc.
- EOS GmbH Electro Optical Systems
- 3D Systems Corporation
Recent Developments
- In September 2025, SprintRay acquired EnvisionTEC/ETEC’s dental 3D printing business, including printers, materials, and IP. The deal expands access to resin-based dental 3D printing plastics and workflows.
- In November 2024, EOS unveiled the EOS P3 NEXT polymer SLS system at Formnext. The printer supports high-performance nylon and composite powders for industrial plastic part production.
- In November 2024, 3D Systems introduced VisiJet Armor Max and VisiJet M2P-CST Crystal for the ProJet MJP 2500 Plus. These new plastic materials target durable prototypes and castable parts in the 3D printing plastics market.
Report Coverage
The research report offers an in-depth analysis based on Type, Form, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for engineered polymers will rise as industries shift toward functional end-use parts.
- Adoption of high-temperature and reinforced plastics will expand in aerospace and automotive.
- Medical applications will grow with wider use of biocompatible materials for customized devices.
- Sustainable and recyclable polymers will gain traction as companies meet green targets.
- Industrial 3D printers will scale production, increasing material consumption across factories.
- Powder-based polymers will see stronger uptake due to better strength and design freedom.
- Digital inventory and on-demand manufacturing will boost long-term polymer demand.
- Material developers will introduce new composites to improve durability and heat resistance.
- Partnerships between printer makers and material suppliers will enhance compatibility and performance.
- Emerging economies will increase adoption as local manufacturing ecosystems mature.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for 3D Printing Plastics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is 3D Printing Plastics Market projected to grow between 2024 and 2032?
Which 3D Printing Plastics Market segment held the largest share in 2024?
What are the primary factors fueling the growth of 3D Printing Plastics Market?
Who are the leading companies in 3D Printing Plastics Market?
Which region commanded the largest share of 3D Printing Plastics Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1188 million → 2032: USD 6596.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global 3D Printing Plastics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global 3D Printing Plastics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global 3D Printing Plastics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global 3D Printing Plastics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global 3D Printing Plastics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global 3D Printing Plastics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global 3D Printing Plastics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global 3D Printing Plastics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1188 million → 2032: USD 6596.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global 3D Printing Plastics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global 3D Printing Plastics Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global 3D Printing Plastics Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global 3D Printing Plastics Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
