
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| 5G Chipset Market Size 2023 | USD 39,325 Million |
| 5G Chipset Market, CAGR | 35.9% |
| 5G Chipset Market Size 2032 | USD 457,535 Million |
Market Overview
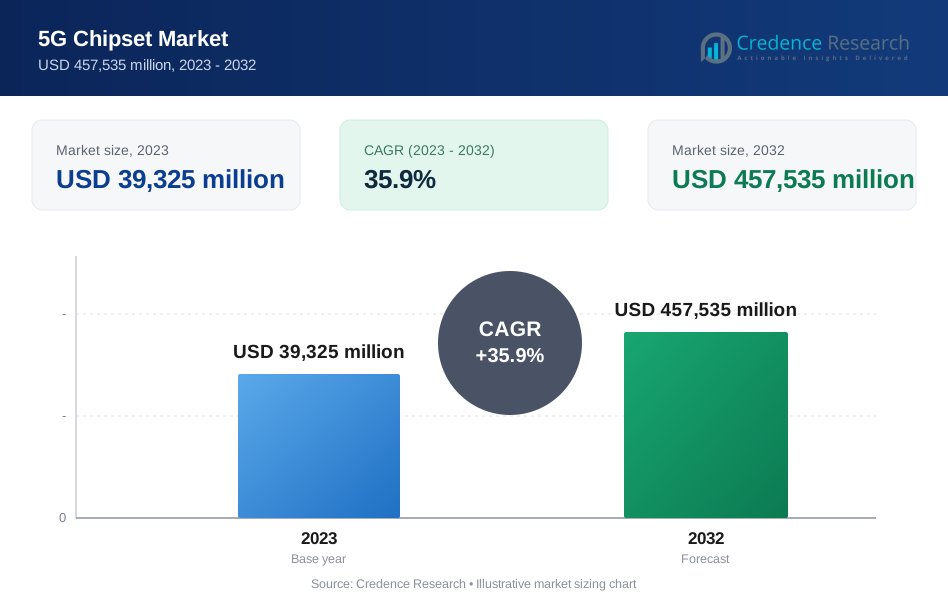
The Global 5G Chipset Market is projected to grow from USD 39,325 million in 2023 to an estimated USD 457,535 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 35.9% from 2024 to 2032. This growth is driven by the accelerating adoption of 5G networks worldwide, fueling demand for next-generation chipsets that enable faster data speeds, ultra-reliable connectivity, and enhanced network capacity.
Key market drivers include rising consumer demand for mobile broadband services, industrial automation, and innovative applications enabled by 5G, such as augmented reality (AR) and connected cars. Moreover, continuous research and development in semiconductor technologies have driven miniaturization, energy efficiency, and performance optimization in 5G chipsets. Trends such as the integration of mmWave technology and advancements in network slicing also contribute to market growth, enhancing the capabilities of 5G across multiple sectors, including healthcare, automotive, and manufacturing.
Geographically, the Asia-Pacific region dominates the global 5G chipset market due to rapid technological adoption, government initiatives, and a strong base of key players. North America and Europe also show significant potential, driven by advanced 5G rollouts and extensive R&D investments. Prominent market participants include Qualcomm Technologies Inc., MediaTek Inc., Intel Corporation, Samsung Electronics, Huawei Technologies, Broadcom Inc., and NXP Semiconductors, among others, shaping the competitive landscape with continuous innovation and strategic partnerships.
Market Drivers
Rapid Expansion and Adoption of 5G Infrastructure Worldwide
The growing demand for high-speed and reliable communication networks has led to the rapid deployment and adoption of 5G infrastructure across the globe. Countries, both developed and emerging, are investing heavily in building robust 5G networks to cater to increasing consumer and enterprise needs for seamless connectivity. For instance, numerous countries are actively investing in 5G networks to enhance connectivity for both consumers and enterprises. This investment is not limited to developed nations; emerging economies are also prioritizing the establishment of robust 5G frameworks to meet the rising demand for seamless communication. As the backbone of 5G technology, chipsets that facilitate ultra-reliable low-latency communication (URLLC), enhanced mobile broadband (eMBB), and massive machine-type communication (mMTC) are experiencing a surge in demand. The critical role of 5G chipsets in powering a range of use cases, from industrial automation and connected vehicles to immersive entertainment experiences, positions this market for exponential growth. Key market participants continue to innovate and introduce chipsets with high data throughput capabilities and energy efficiency, further accelerating the adoption curve.
Growing Demand for IoT and Smart Devices
The proliferation of Internet of Things (IoT) devices is a key driver for the 5G chipset market. As smart homes, smart cities, and industrial IoT solutions gain traction, the need for reliable, high-speed connectivity becomes paramount. The integration of 5G chipsets enables devices to operate seamlessly and process data faster, meeting the demands of data-intensive applications. Moreover, the proliferation of IoT devices significantly drives the demand for 5G chipsets. As smart cities and industrial IoT solutions become more prevalent, the necessity for high-speed, reliable connectivity grows. The integration of 5G chipsets allows these devices to communicate effectively and handle large volumes of data, which is crucial for applications in sectors like healthcare and automotive. This trend illustrates how 5G technology is designed to accommodate the unique demands of IoT, enabling a vast number of devices to connect simultaneously while maintaining low latency.In addition, the increase in connected devices in industries such as healthcare, automotive, and manufacturing has amplified the demand for chipsets that can offer ultra-low latency and enhanced capacity. As a result, manufacturers continue to develop specialized chipsets tailored for diverse IoT applications, pushing market growth further.
Technological Advancements in Semiconductor Technology
Ongoing advancements in semiconductor technology play a pivotal role in the expansion of the 5G chipset market. Continuous efforts in research and development have enabled significant improvements in the size, efficiency, and performance of chipsets. Miniaturization has made it possible to integrate 5G capabilities into a broader range of devices, including smartphones, tablets, laptops, and even wearable devices.Additionally, advancements in semiconductor technology are pivotal to the growth of the 5G chipset market. Continuous research and development efforts have led to improvements in the size, efficiency, and performance of chipsets. Innovations such as silicon carbide (SiC) and gallium nitride (GaN) materials are enhancing energy efficiency and processing power, making it feasible to integrate 5G capabilities into a broader range of devices including smartphones, laptops, and wearables. These technological advancements not only facilitate the deployment of 5G but also expand its applications across various industries, further accelerating market growth.The adoption of millimeter-wave (mmWave) spectrum and advancements in multi-mode 5G chipsets have further expanded the range of applications that can benefit from 5G connectivity-from augmented reality (AR) and virtual reality (VR) solutions to mission-critical applications in sectors like healthcare and defense.
Rising Consumer Demand for Mobile Broadband Services and Enhanced Connectivity The exponential increase in data consumption driven by streaming services, mobile gaming, and high-definition content is another key driver of the 5G chipset market. Consumers demand faster download and upload speeds, lower latency, and more stable connectivity, which 5G technology can deliver. This surge in consumer demand is compelling telecommunications providers and chipset manufacturers to accelerate the rollout of 5G networks and compatible devices. The integration of 5G chipsets into smartphones, laptops, and other devices enhances user experiences, driving market demand. Moreover, the pandemic-induced shift toward remote work, telemedicine, and online education has underscored the importance of fast, reliable connectivity, amplifying the need for 5G-enabled devices powered by advanced chipsets.
Market Trends
Rising Integration of AI and Machine Learning Capabilities in 5G Chipsets
A key trend in the 5G chipset market is the incorporation of artificial intelligence (AI) and machine learning (ML) capabilities to enhance overall network performance and device functionality. With 5G enabling ultra-fast data transfer speeds and low-latency communication, AI-driven solutions play a crucial role in optimizing data traffic management, predictive maintenance, and seamless user experiences across applications. For instance, AI algorithms are being utilized in 5G network planning and automation, allowing for more efficient resource allocation and management of network operations. This integration helps in optimizing data traffic management, which is particularly crucial in environments with high device density, such as smart cities and autonomous vehicle systems. Furthermore, AI-driven solutions enable predictive maintenance by analyzing patterns and anomalies in network traffic, thus improving overall reliability and user experience.Chipset manufacturers are increasingly embedding AI features to facilitate intelligent processing, enabling real-time decision-making and adaptive resource allocation. This trend is highly relevant in sectors such as smart manufacturing, autonomous vehicles, and smart city infrastructure, where AI-driven automation requires high reliability and precision. AI-integrated 5G chipsets offer enhanced energy efficiency, faster data processing, and superior security, making them indispensable in today’s data-centric environment.
Focus on mmWave Spectrum Adoption and Multi-Mode Chipset Solutions
The adoption of millimeter-wave (mmWave) spectrum is gaining traction due to its ability to deliver ultra-high-speed connectivity, albeit with a limited range. This trend has prompted major chipset manufacturers to focus on developing solutions that effectively harness mmWave technology to overcome signal propagation challenges, including beamforming and signal amplification. For example, companies are developing multi-mode chipsets that support various frequency bands, facilitating seamless connectivity across diverse network environments. This versatility is essential for ensuring compatibility in regions with varying levels of 5G infrastructure deployment. The development of multi-mode chipsets, which support multiple frequencies and standards (such as sub-6 GHz and mmWave), is also a notable trend. These versatile chipsets enable seamless connectivity across various network environments, providing higher compatibility and flexibility for both consumers and enterprises. The emphasis on such chipsets not only enhances user experiences but also promotes faster commercialization of 5G services across diverse geographies, accelerating the global 5G rollout and paving the way for new applications and use cases. The focus on mmWave technology allows for ultra-high-speed connectivity, which is critical for applications requiring low latency, such as real-time data processing and high-definition video streaming.
Market Restraints and Challenges
High Cost of 5G Infrastructure Deployment and Chipset Production
One of the primary challenges in the global 5G chipset market is the significant cost associated with 5G network infrastructure deployment and chipset production. Building and expanding 5G networks require substantial investments in new base stations, spectrum acquisition, and advanced network equipment, which can strain the budgets of service providers, especially in developing regions. The production of 5G chipsets themselves involves high costs due to the use of advanced semiconductor technologies and complex design processes. This cost burden impacts manufacturers and end-users alike, potentially slowing down the pace of 5G adoption, particularly in regions with limited financial resources or lower levels of economic development. Moreover, high costs can create barriers to entry for smaller companies, concentrating market power among established players and reducing competition, which may impact innovation and pricing.
Complexity of Global Standardization and Spectrum Allocation
The global 5G chipset market faces challenges related to the complexity of standardization and spectrum allocation across different regions. Unlike previous generations of mobile networks, 5G requires multiple frequency bands, including sub-6 GHz and mmWave, each with its own set of regulatory and technological considerations. Varying policies, spectrum availability, and licensing models across countries make it difficult for chipset manufacturers to develop globally compatible solutions that meet the diverse requirements of network operators and end-users. This fragmented regulatory landscape hampers the seamless rollout of 5G technology, increases development costs, and limits economies of scale for chipset manufacturers. Additionally, technical challenges such as managing interference, ensuring consistent performance, and addressing device compatibility in different regions further complicate the development and deployment process, creating obstacles to the rapid and uniform adoption of 5G technology worldwide.
Market Segmentation Analysis
By Type
The 5G chipset market by type comprises Application Specific Integrated Circuits (ASICs), tailored for specific 5G applications with optimized performance and cost efficiency, particularly in high-capacity network deployments. Radio Frequency Integrated Circuits (RFICs) are essential for wireless communication, managing multi-band and high-frequency processing for evolving 5G networks. Millimeter Wave Integrated Circuits (mmWave ICs) facilitate ultra-high-speed, low-latency connections and are vital for data-intensive applications like AR, VR, and smart cities, spurring investments due to the increasing adoption of mmWave spectrum. Cellular Integrated Circuits (Cellular ICs) drive connectivity in 5G mobile devices such as smartphones, tablets, and laptops, meeting the rising demand for fast mobile broadband. Other 5G chipset solutions, including programmable logic devices and digital signal processors, support diverse applications beyond these main categories.
By Frequency
By frequency, the global 5G chipset market encompasses three key bands. Sub-6 GHz frequencies are preferred for initial 5G rollouts worldwide due to their broad coverage and high reliability, balancing performance and range to enhance mobile broadband and IoT connectivity, especially in less dense regions. The 26-39 GHz mid-band spectrum offers a mix of high data speeds and moderate coverage, supporting applications like urban network densification and enterprise solutions, crucial for achieving high-capacity 5G potential in urban and suburban areas. Above 39 GHz frequencies, or mmWave bands, deliver ultra-high-speed and low-latency capabilities, essential for data-intensive and mission-critical applications such as autonomous vehicles, high-definition streaming, and immersive virtual experiences, driving the global commercialization of advanced 5G services.
Segments
Based on Type
- Application Specific Integrated Circuit (ASIC)
- Radio Frequency Integrated Circuit (RFIC)
- Millimeter Wave Integrated Circuit (mmWave IC)
- Cellular Integrated Circuit (Cellular IC)
- Others
Based on Frequency
- Sub-6 GHZ
- 26-39 GHZ
- Above 39 GHz
Based on Deployment Type
- Smartphone/Tablets
- Connected Vehicles
- Connected Devices
- Broadband Access Gateway Devices
- Others
Based on Industry Vertical
- Energy and Utilities
- Manufacturing
- IT and Telecommunication
- Media and Entertainment
- Transportation and Logistics
- Consumer Electronics
- Healthcare
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia-Pacific (45%)
The Asia-Pacific region holds the largest market share in the global 5G chipset market, accounting for approximately 45% of total revenue. This dominance is attributed to strong government initiatives, significant investments in 5G infrastructure, and a robust manufacturing base in countries such as China, South Korea, and Japan. China leads the market, driven by rapid network rollouts, mass production of 5G devices, and active participation from major telecom providers and chipset manufacturers. South Korea and Japan have been at the forefront of technological advancements and commercialization of 5G services, further boosting regional market growth. The region’s prominence is also supported by the increasing penetration of IoT devices, smart cities, and industrial automation solutions.
North America (25%)
North America represents around 25% of the global market share, driven primarily by the United States. The U.S. government’s initiatives to enhance 5G network capabilities, coupled with investments by key players such as Qualcomm, Intel, and Broadcom, have strengthened the regional market. The demand for high-speed mobile broadband, coupled with rising trends in autonomous vehicles, telemedicine, and smart manufacturing, further propels growth. Canada also plays a role in market expansion through government-backed 5G initiatives and technology partnerships. North America's strong focus on research and development and the presence of advanced telecom infrastructure enable the swift adoption of 5G-enabled devices, making the region a significant contributor to the market.
Key players
- Qualcomm Technologies, Inc. (U.S.)
- Broadcom (U.S.)
- Unisoc Communications, Inc. (China)
- Mediatek Inc. (Taiwan)
- Intel Corporation (U.S.)
- Samsung Electronics Co., Ltd. (South Korea)
- Huawei Technologies Co., Ltd. (China)
- Qorvo (U.S.)
- Xilinx Inc. (U.S.)
- Infineon Technologies AG (Germany)
Competitive Analysis
The global 5G chipset market is highly competitive, with key players focusing on innovation, strategic partnerships, and technological advancements to strengthen their market positions. Qualcomm Technologies leads with a diverse portfolio of 5G chipsets, leveraging its strong R&D capabilities and strategic partnerships with device manufacturers. Broadcom and Intel have carved out niches in network infrastructure and semiconductor solutions, while MediaTek’s cost-effective chipsets make it a strong contender in the consumer device segment. Huawei and Samsung continue to drive market growth with integrated 5G solutions and global reach. Emerging players such as Unisoc target price-sensitive markets, while Qorvo and Xilinx focus on RF solutions and programmable logic devices, respectively. Intense competition drives innovation, with each player seeking to capture market share by offering differentiated and high-performance solutions tailored to various applications and market needs.
Recent Developments
- In February 2023, Qualcomm launched the Snapdragon X75, its new 6th generation 5G radio frequency modem, enhancing compatibility with 5G-Advanced networks.
- In October 2023, Broadcom announced its latest 5G chipset solutions aimed at improving performance for mobile network operators and enhancing connectivity.
- In January 2024, Unisoc unveiled its new 5G chipset designed for low-cost smartphones, targeting emerging markets to expand 5G accessibility.
- In October 2024, MediaTek launched its Dimensity 9300 chipset, which integrates advanced AI features for enhanced mobile performance and connectivity.
- In March 2023, Intel introduced its new line of 5G chipsets focused on enhancing cloud and edge computing capabilities for enterprise applications.
- In July 2023, Samsung launched its Exynos 2200 chipset with integrated 5G capabilities, aimed at high-performance mobile devices.
- In August 2023, Huawei released its latest Balong chipset designed to support advanced 5G applications in smart cities and IoT devices.
- In April 2023, Xilinx announced a new series of adaptive compute acceleration platforms optimized for next-generation 5G networks.
Market Concentration and Characteristics
The Global 5G Chipset Market is characterized by a moderately high level of concentration, with a few leading players dominating the market due to their strong technological capabilities, extensive R&D investments, and robust partnerships. Major companies such as Qualcomm, MediaTek, Samsung, Huawei, and Intel exert significant influence, leveraging their expertise in semiconductor technology and broad market presence to capture substantial market share. The market is defined by rapid innovation, competitive pricing strategies, and the drive to offer differentiated products tailored to diverse applications, from consumer electronics to industrial automation. Smaller and emerging players focus on niche applications and cost-effective solutions to compete, while technological advancements, regulatory frameworks, and evolving standards play a critical role in shaping market dynamics and barriers to entry. The competitive landscape remains dynamic, driven by demand for high-speed connectivity, low-latency communication, and energy-efficient chipsets across industries.
Report Coverage
The research report offers an in-depth analysis based on Type, Frequency, Deployment Type, Industry Vertical and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The continued rollout of 5G infrastructure globally will drive the demand for advanced chipsets, supporting rapid connectivity growth and enabling diverse applications across industries.
- 5G chipsets will increasingly incorporate AI and machine learning capabilities, optimizing network performance, enabling predictive analytics, and enhancing data processing efficiency.
- The proliferation of IoT devices will spur demand for 5G chipsets capable of supporting seamless connectivity, fostering the growth of smart cities, smart homes, and industrial automation.
- mmWave technology will gain momentum, driven by the need for ultra-high-speed data transmission in dense urban environments, creating opportunities for specialized 5G chipsets.
- Market players will focus on reducing the cost of 5G chipsets, broadening market accessibility and accelerating adoption across consumer and enterprise applications in developing regions.
- Energy-efficient 5G chipsets will become crucial as energy costs rise and sustainability goals become more pressing, driving R&D investment into low-power, high-performance solutions.
- Growth in private 5G networks for enterprises, industrial automation, and mission-critical applications will increase demand for customizable and secure chipset solutions.
- The establishment of unified global standards and favorable regulatory policies will facilitate market growth, enhancing compatibility and accelerating the adoption of 5G chipsets worldwide.
- The growing adoption of 5G-compatible devices, including smartphones, laptops, and wearables, will create a robust demand for high-performance chipsets to meet user expectations.
- 5G chipsets will underpin emerging technologies such as augmented reality (AR), virtual reality (VR), and autonomous vehicles, unlocking new use cases and market opportunities for advanced solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Expansion of 5G Infrastructure
The accelerated global rollout of 5G networks is directly increasing demand for advanced chipsets that enable high-speed, low-latency connectivity. Investments by governments and telecom operators in both developed and emerging markets are driving the need for chipsets that support enhanced mobile broadband, ultra-reliable low-latency communication, and massive machine-type communication.
Proliferation of IoT and Smart Devices
The surge in connected devices across smart homes, cities, and industrial IoT applications is fueling the need for 5G chipsets capable of supporting large-scale, simultaneous device connectivity with minimal latency. This trend is particularly strong in sectors such as healthcare, automotive, and manufacturing, where reliable, high-speed data transmission is critical.
Advancements in Semiconductor Technology
Continuous innovation in semiconductor materials and design, including the adoption of silicon carbide (SiC) and gallium nitride (GaN), is enabling the production of smaller, more energy-efficient, and higher-performance 5G chipsets. These advancements allow for broader integration of 5G capabilities into a wide range of consumer electronics and industrial devices.
Integration of AI and Machine Learning in Chipsets
Chipset manufacturers are embedding AI and machine learning features to optimize network performance, enable real-time data processing, and support intelligent automation. This integration enhances the value proposition of 5G chipsets in applications such as autonomous vehicles, smart manufacturing, and predictive maintenance.
Adoption of mmWave and Multi-Mode Chipset Solutions
The increasing use of millimeter-wave (mmWave) spectrum and the development of multi-mode chipsets that support various frequency bands are expanding the range of 5G applications. These technologies enable ultra-high-speed connectivity and seamless operation across diverse network environments, driving adoption in data-intensive and mission-critical use cases.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the global 5G chipset market in 2023 and 2032, and what is the CAGR?
What are the key factors driving the growth of the 5G chipset market?
Which region holds the largest share of the global 5G chipset market?
How are advancements in semiconductor technology affecting the 5G chipset market?
Who are some of the prominent players in the 5G chipset market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Application Specific Integrated Circuit (ASIC)
- 1.2.2 Radio Frequency Integrated Circuit (RFIC)
- 1.2.3 Millimeter Wave Integrated Circuit (mmWave IC)
- 1.2.4 Cellular Integrated Circuit (Cellular IC)
- 1.2.5 Others
- 1.3 By Frequency
- 1.3.1 Sub-6 GHz
- 1.3.2 26-39 GHz
- 1.3.3 Above 39 GHz
- 1.4 By Deployment Type
- 1.4.1 Smartphone/Tablets
- 1.4.2 Connected Vehicles
- 1.4.3 Connected Devices
- 1.4.4 Broadband Access Gateway Devices
- 1.4.5 Others
- 1.5 By Industry Vertical
- 1.5.1 Energy and Utilities
- 1.5.2 Manufacturing
- 1.5.3 IT and Telecommunication
- 1.5.4 Media and Entertainment
- 1.5.5 Transportation and Logistics
- 1.5.6 Consumer Electronics
- 1.5.7 Healthcare
- 1.5.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 39,325 million → 2032: USD 457,535 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global 5G Chipset Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global 5G Chipset Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global 5G Chipset Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global 5G Chipset Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global 5G Chipset Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global 5G Chipset Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global 5G Chipset Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global 5G Chipset Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 39,325 million → 2032: USD 457,535 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global 5G Chipset Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Application Specific Integrated Circuit (ASIC)
- 12.3.7.2 Radio Frequency Integrated Circuit (RFIC)
- 12.3.7.3 Millimeter Wave Integrated Circuit (mmWave IC)
- 12.3.7.4 Cellular Integrated Circuit (Cellular IC)
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Frequency - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Sub-6 GHz
- 12.4.7.2 26-39 GHz
- 12.4.7.3 Above 39 GHz
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Smartphone/Tablets
- 12.5.7.2 Connected Vehicles
- 12.5.7.3 Connected Devices
- 12.5.7.4 Broadband Access Gateway Devices
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Industry Vertical - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Energy and Utilities
- 12.6.7.2 Manufacturing
- 12.6.7.3 IT and Telecommunication
- 12.6.7.4 Media and Entertainment
- 12.6.7.5 Transportation and Logistics
- 12.6.7.6 Consumer Electronics
- 12.6.7.7 Healthcare
- 12.6.7.8 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global 5G Chipset End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global 5G Chipset Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global 5G Chipset Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global 5G Chipset Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Qualcomm Technologies, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Broadcom
- 18.4 Unisoc Communications, Inc.
- 18.5 MediaTek Inc.
- 18.6 Intel Corporation
- 18.7 Samsung Electronics Co., Ltd.
- 18.8 Huawei Technologies Co., Ltd.
- 18.9 Qorvo
- 18.10 Xilinx Inc.
- 18.11 Infineon Technologies AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

