
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europe 5G Fixed Wireless Access (FWA) Market Size 2023 | USD 7,900.57 million |
| Europe 5G Fixed Wireless Access (FWA) Market, CAGR | 25.86% |
| Europe 5G Fixed Wireless Access (FWA) Market Size 2032 | USD 84,668.10 million |
Market Overview
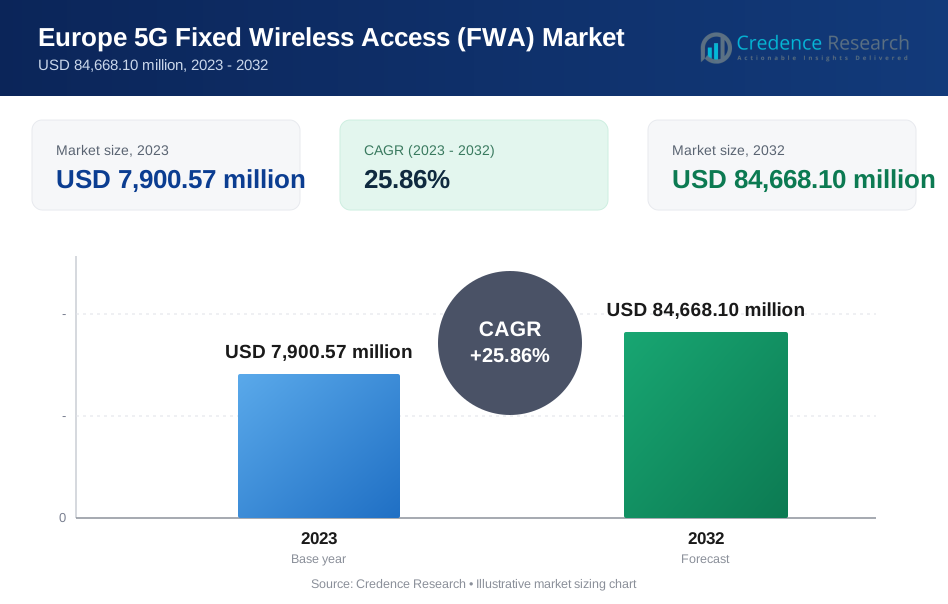
The Europe 5G Fixed Wireless Access (FWA) Market is projected to grow from USD 7,900.57 million in 2023 to an estimated USD 84,668.10 million by 2032, with a compound annual growth rate (CAGR) of 25.86% from 2024 to 2032. This rapid growth is driven by the increasing demand for high-speed internet connectivity and the expansion of 5G infrastructure across the region.
The main drivers of the 5G FWA market in Europe include the growing need for enhanced broadband speeds, the rise of remote work, and the increasing demand for low-latency connectivity. The adoption of 5G technology in urban and rural areas is a significant trend, enabling users in hard-to-reach regions to access high-speed internet. Additionally, advancements in 5G infrastructure and the roll-out of private networks are further fueling market expansion, offering businesses and consumers improved connectivity solutions.
Geographically, Western Europe is expected to lead the market, driven by substantial investments in 5G network development and strong demand for high-performance connectivity in countries like Germany, the UK, and France. Key players in the European 5G FWA market include Ericsson, Nokia, Huawei, Qualcomm, and Samsung, all of which are spearheading innovations in 5G technology and FWA solutions to cater to diverse consumer and business needs across the region.
Market Insights
- The Europe 5G FWA market is projected to grow from USD 7,900.57 million in 2023 to USD 84,668.10 million by 2032, with a CAGR of 25.86% from 2024 to 2032.
- The need for faster, reliable internet, driven by remote work, IoT, and digital transformation, is a key market driver.
- 5G FWA is enabling broadband access in rural and remote regions where traditional broadband infrastructure is limited or economically unfeasible.
- High costs of 5G deployment and infrastructure limitations, especially in rural areas, present challenges for widespread 5G FWA adoption.
- Countries like Germany, the UK, and France are leading the 5G FWA market due to significant investments in 5G networks and high demand for advanced connectivity.
- Government initiatives across Europe are promoting digital inclusion, supporting the expansion of 5G networks and FWA services.
- Major telecom operators such as Deutsche Telekom, Vodafone, and Orange, along with technology providers like Ericsson and Nokia, are intensifying competition and innovation in the market.
Market Drivers
Growing Demand for High-Speed Broadband Connectivity
The increasing demand for high-speed internet is one of the primary drivers for the Europe 5G Fixed Wireless Access (FWA) market. As digitalization accelerates across industries, both businesses and consumers require faster and more reliable internet connections to support cloud computing, streaming services, gaming, telemedicine, and remote work. For instance, during the COVID-19 pandemic, there was a significant surge in online activities, with remote work and telehealth services becoming mainstream. This shift highlighted the inadequacies of traditional broadband solutions, as many users experienced slow speeds and unreliable connections, particularly in rural areas where infrastructure is often lacking. In response, 5G FWA has emerged as a viable solution, enabling faster internet deployment without the extensive physical infrastructure required by fiber-optic systems.Traditional broadband solutions, such as fiber-optic and DSL connections, often face limitations in terms of speed, availability, and installation complexity. 5G FWA offers a compelling alternative by providing high-speed connectivity that is faster to deploy and more cost-effective, especially in areas with infrastructure gaps. The ability of 5G FWA to offer multi-gigabit speeds is crucial in an increasingly connected world where bandwidth demand continues to rise. Additionally, the convergence of multiple technologies-including artificial intelligence, virtual reality, and Internet of Things (IoT)-is further driving the need for enhanced connectivity, making 5G FWA a vital enabler for these innovations.
The Growing Adoption of Remote Work and Telecommuting
The global shift towards remote work has significantly influenced the demand for reliable internet services. In Europe, the trend toward telecommuting is expected to persist as businesses adopt more flexible work models. Remote workers need fast, secure, and stable internet connections to maintain productivity and collaborate effectively. In areas where traditional wired broadband solutions are not easily accessible or cost-prohibitive to deploy, 5G FWA serves as a practical solution to meet the growing needs of the workforce. By enabling seamless connectivity without the need for extensive cable infrastructure, 5G FWA helps bridge the digital divide, especially in rural and suburban areas that are underserved by traditional broadband providers.As more organizations invest in hybrid work models, the demand for reliable, high-speed fixed wireless access is set to rise. This trend underscores the importance of 5G FWA in supporting remote work environments and ensuring that employees can perform their tasks efficiently from any location.
Expansion of 5G Networks and Infrastructure
The ongoing expansion of 5G networks across Europe is a major catalyst for the growth of the 5G FWA market. Telecommunications operators are increasingly integrating 5G technology into their offerings, recognizing its potential to deliver ultra-low latency and high data transfer speeds. This integration is particularly beneficial for sectors that depend on real-time data transmission-such as agriculture and logistics-where timely information can significantly impact operations. As a result, businesses in these industries are turning to 5G FWA to ensure uninterrupted operations and support their digital transformation efforts.By using 5G to deliver fixed broadband services, operators can overcome the limitations of traditional fixed-line infrastructure-particularly in rural and remote locations where installing fiber or other wired broadband technologies may not be feasible. The rollout of 5G is not just about improving mobile connectivity; it also provides an opportunity for telcos to diversify their revenue streams by offering fixed broadband services through FWA. As governments and telecom companies continue to invest in 5G infrastructure, the availability of 5G FWA services is expected to increase, thus driving market growth.
Cost-Effectiveness and Faster Deployment
One of the standout advantages of 5G FWA over traditional broadband solutions is its cost-effectiveness and speed of deployment. Installing fiber-optic cables or traditional broadband infrastructure in remote or densely populated urban areas can be expensive, time-consuming, and disruptive. On the other hand, 5G FWA can be deployed much more quickly and at a lower cost. The fixed wireless approach requires fewer physical cables and infrastructure, reducing the overall cost of network deployment.This is especially beneficial in underserved or rural areas where investing in fiber networks may not be economically viable. The ease and speed of 5G FWA installation make it an attractive solution for service providers looking to expand their offerings and meet the demand for broadband services without significant capital expenditure. Moreover, 5G FWA can support a wide range of users-from individual consumers to businesses-offering scalable solutions that can easily adapt to evolving market needs. As telecom operators seek to maximize their network investments, FWA services present a compelling and flexible solution for broadband delivery.
Market Trends
Deployment of 5G FWA as a Key Solution for Rural and Remote Areas
One of the most prominent trends in the Europe 5G Fixed Wireless Access (FWA) market is the increasing deployment of 5G FWA as a solution for rural and remote areas where traditional broadband infrastructure, such as fiber optics and DSL, is limited or economically unfeasible. While urban areas have seen significant improvements in broadband connectivity, many rural regions across Europe still face challenges in terms of high-speed internet access. The cost and time required to lay down extensive fiber cables make it difficult for service providers to meet the needs of underserved populations. In response to these challenges, telecom operators are increasingly turning to 5G FWA as a more affordable and efficient alternative. For instance, in Italy, the collaboration between Nokia and EOLO has led to the deployment of Europe’s first 5G standalone mmWave network, specifically aimed at connecting underserved communities where traditional wired infrastructure is impractical or costly to establish. This initiative exemplifies how 5G FWA can effectively bridge the digital divide by providing high-speed internet access to regions that have historically been overlooked by conventional broadband services. With its ability to deliver high-speed internet over the air, 5G FWA helps rural consumers gain reliable broadband access. The ongoing expansion of 5G networks by operators such as Vodafone, Orange, and Deutsche Telekom is driving the adoption of FWA technology, making it a key tool in improving broadband access across diverse regions of Europe.
Integration of 5G with Fiber Networks to Enhance Performance
As the demand for high-speed, low-latency internet grows, telecom operators are increasingly integrating 5G with existing fiber networks to enhance the performance and reliability of FWA services. While 5G FWA on its own offers impressive speeds and connectivity, the integration with fiber-optic backhaul is enabling operators to deliver even more robust solutions. For instance, telecom operators are leveraging fiber-optic backhaul alongside 5G technology to deliver enhanced connectivity, particularly in urban and semi-urban areas where demand for high-bandwidth internet is rapidly increasing. This hybrid approach not only ensures faster and more reliable internet access but also positions FWA as a crucial component in future-proofing broadband delivery across diverse European regions.
Increased Focus on Private 5G Networks for Business Applications
A growing trend in the European 5G FWA market is the increasing focus on private 5G networks, particularly for business and enterprise applications. As industries such as manufacturing, logistics, healthcare, and education continue to digitize, there is a rising demand for secure, high-performance networks tailored to the specific needs of businesses. For instance, industries such as healthcare and manufacturing are increasingly adopting private 5G networks enabled by FWA, which allow for dedicated and secure connections essential for mission-critical applications. Private 5G networks ensure businesses have full control over their network infrastructure, which is crucial for maintaining security and ensuring network reliability in data-sensitive environments. With the ability to deploy these networks without the need for traditional wired broadband infrastructure, 5G FWA is seen as a cost-effective and scalable solution for enterprises seeking to improve operational efficiency and digital capabilities. Several large enterprises in Europe are already exploring and deploying private 5G networks as part of their broader digital transformation efforts, further accelerating the uptake of 5G FWA solutions.
Emergence of 5G FWA in Conjunction with Emerging Technologies
The combination of 5G FWA with emerging technologies is creating new opportunities for service providers and users alike. The ability of 5G to support massive amounts of data with ultra-low latency is making it an ideal complement to technologies such as Artificial Intelligence (AI), Virtual Reality (VR), Augmented Reality (AR), and the Internet of Things (IoT). As industries continue to embrace smart technologies, the demand for reliable, high-speed internet becomes even more critical. For instance, applications in artificial intelligence and smart city infrastructure rely heavily on high-performance connectivity that 5G FWA can provide, facilitating advancements in sectors ranging from entertainment to industrial IoT. Moreover, AI-driven applications in the healthcare sector, smart cities’ infrastructure, and connected vehicle systems all rely on high-performance connectivity that 5G FWA is well-positioned to provide. The implementation of 5G FWA allows for faster deployment and easier scalability of such technologies. Operators and businesses in Europe are leveraging 5G FWA to enable the next generation of smart services, driving innovation across various industries.
Market Challenges
Infrastructure and Coverage Limitations
While 5G Fixed Wireless Access (FWA) offers significant advantages in terms of speed and flexibility, one of the key challenges faced by the market is the limitations in infrastructure and coverage, especially in rural and remote areas. Although 5G networks are rapidly expanding across Europe, full nationwide coverage remains a challenge due to the high cost and complexity of deploying 5G infrastructure. In particular, the need for small cell networks and additional towers in low-density areas can increase costs and delay the widespread availability of 5G FWA services. While urban regions are benefiting from faster 5G rollouts, rural and less populated areas often face difficulties in obtaining sufficient 5G coverage, limiting the reach of FWA solutions. Additionally, the deployment of 5G requires regulatory approval, spectrum licensing, and collaboration with local authorities, which can further slow down network development and hinder the rapid adoption of 5G FWA services in underserved regions.
High Cost of 5G Deployment and Competition from Other Technologies
The high capital expenditure required for the deployment of 5G infrastructure poses a significant challenge for telecom operators, especially in the face of strong competition from other broadband technologies such as fiber-optic and satellite-based solutions. Deploying 5G infrastructure necessitates large investments in equipment, spectrum acquisition, and network maintenance, which can be difficult to justify, particularly in areas with lower population density or where existing infrastructure already meets demand. This high cost could lead to slower adoption and a longer payback period for service providers. Furthermore, competition from fiber broadband, which offers reliable and high-speed connections in urban areas, and low-earth orbit (LEO) satellite internet, which can provide global coverage without the need for ground-based infrastructure, may challenge the market's growth. These competing technologies could limit the overall market potential for 5G FWA, as they offer alternative broadband solutions that may be more cost-effective or easier to deploy in certain areas.
Market Opportunities
Expansion in Underserved and Rural Areas
One of the most significant market opportunities in the Europe 5G Fixed Wireless Access (FWA) market lies in expanding broadband access to underserved and rural areas. Many regions across Europe, particularly in less densely populated and rural locations, still struggle with slow or unreliable broadband due to the high costs and logistical challenges associated with deploying fiber-optic networks. 5G FWA presents a cost-effective and efficient alternative, offering the ability to deliver high-speed internet without the need for extensive physical infrastructure. As telecom operators and governments focus on bridging the digital divide, the deployment of 5G FWA in these regions provides an opportunity to cater to the growing demand for reliable connectivity. With the ongoing 5G rollout and government initiatives supporting digital inclusion, there is considerable potential for growth in areas where traditional broadband options are either unavailable or expensive to implement.
Integration with Emerging Technologies and Industry 4.0
The rise of emerging technologies such as the Internet of Things (IoT), artificial intelligence (AI), and Industry 4.0 creates a significant opportunity for the 5G FWA market in Europe. These technologies require high-speed, low-latency connectivity to function effectively, and 5G FWA is uniquely positioned to meet these needs. As businesses across industries such as manufacturing, healthcare, and logistics increasingly adopt smart solutions and automation, the demand for fast and reliable internet connections will continue to grow. 5G FWA provides a scalable and flexible solution to support these applications, enabling the seamless operation of connected devices, real-time data processing, and autonomous systems. This integration with emerging technologies presents an opportunity for telecom providers to offer tailored solutions to businesses looking to enhance their digital transformation efforts.
Market Segmentation Analysis
By Offering
The Europe 5G Fixed Wireless Access (FWA) market is divided into two key segments: hardware and services. The hardware segment includes the essential physical infrastructure required to support FWA services, such as routers, antennas, and base stations. As 5G technology advances, the demand for more sophisticated hardware to ensure high-speed, reliable connections continues to rise, particularly with the expanding 5G networks in both urban and rural areas. The services segment covers the operational side of 5G FWA, including network installation, maintenance, and customer support. Service providers are focusing on offering value-added services, such as customized packages and seamless connectivity solutions, to improve the user experience. This segment is expected to grow significantly as the adoption of 5G FWA services increases across both consumer and business sectors in Europe.
By Operating Frequency
The operating frequency of 5G Fixed Wireless Access (FWA) plays a crucial role in determining performance and coverage. Sub 6GHz frequencies are commonly used in the early stages of 5G rollouts, offering a balanced combination of coverage and data speed, making them ideal for suburban and rural areas. 24-39 GHz (Millimeter Wave) frequencies provide faster data speeds and lower latency but are limited by range, making them more suitable for urban environments with dense infrastructure. These frequencies enable high-capacity connections for residential and business applications in cities. Finally, Above 39GHz frequencies are anticipated to be used in advanced 5G deployments to offer ultra-high-speed connectivity, primarily in urban areas, though their use is constrained by the need for dense cell infrastructure and susceptibility to signal degradation.
Segments
Based on Offering
- Hardware
- Services
Based on Operating Frequency
- Sub 6GHz
- 24-39 GHz
- Above 39GHz
Based on Application
- Residential
- Commercial
- Industrial
- Government
Based on Region
- Urban
- Semi Urban
- Rural
Regional Analysis
Western Europe (45%)
Western Europe holds the largest share of the Europe 5G FWA market, accounting for approximately 45% of the market share. This is due to the region's advanced telecommunications infrastructure and strong government support for 5G rollout. Countries such as Germany, the United Kingdom, France, and the Netherlands are at the forefront of 5G adoption, with telecom operators like Deutsche Telekom, Vodafone, and Orange investing heavily in 5G networks. The demand for high-speed internet services in urban centers, combined with strong competition among service providers, is driving the rapid adoption of 5G FWA solutions. Additionally, these countries are focused on enhancing connectivity in underserved regions, where 5G FWA provides an efficient solution to bridge the digital divide.
Northern Europe (25%)
Northern Europe holds a notable market share of around 25%. Countries like Sweden, Finland, Denmark, and Norway are leading the charge in deploying 5G networks and adopting FWA technologies. The region benefits from high levels of technological innovation and a commitment to sustainability, with telecom operators focused on providing cutting-edge solutions. In particular, Sweden and Finland have strong governmental backing for digital inclusion initiatives, helping to promote the widespread adoption of 5G FWA in rural and remote areas. The region’s tech-savvy population also fosters demand for high-speed broadband solutions, further propelling the market.
Key players
- Deutsche Telekom AG
- Vodafone Group PLC
- Orange SA
- Telefónica SA
- TIM SpA (Telecom Italia Mobile)
- Ericsson
- Nokia
- Samsung
- Inseego Corp.
- Qualcomm Technologies, Inc
- Intel Corporation
- MediaTek Inc.
Competitive Analysis
The European 5G Fixed Wireless Access (FWA) market is highly competitive, with both telecom operators and technology providers vying for dominance. Leading telecom companies like Deutsche Telekom, Vodafone, and Orange are aggressively expanding their 5G networks to provide high-speed FWA services to urban and rural regions. These operators leverage their extensive infrastructure and customer bases to capture market share. Technology giants such as Ericsson, Nokia, Qualcomm, and Intel play a crucial role by supplying the essential hardware and network solutions needed for FWA deployments. Their advanced 5G equipment and chipsets are integral to ensuring high-speed, low-latency connectivity. Additionally, Samsung and MediaTek contribute through the development of innovative technologies and devices that enhance 5G FWA performance. The competitive landscape is marked by intense innovation, with companies focusing on strategic partnerships, infrastructure expansion, and technological advancements to secure a larger share of the rapidly growing market.
Recent Developments
- In December 2024, Nokia announced the deployment of Europe’s first 5G standalone mmWave network in collaboration with EOLO in Italy. This new infrastructure aims to enhance customer experience and connect underserved communities through Fixed Wireless Access services .
- In January 2024, Qualcomm launched a new generation of 5G FWA chipsets designed to improve bandwidth and connectivity for residential and enterprise users, promising a significant increase in data transfer rates.
- In March 2024, Samsung unveiled its next-generation 5G FWA solution targeting global markets, focusing on faster download speeds and improved coverage to enhance its presence in the European FWA market.
- In November 2024, Vodafone announced a partnership with several local governments across Europe to expand its 5G FWA services, aiming to enhance connectivity in rural areas.
- In October 2024, Telefónica launched a pilot program for its 5G FWA services in Spain, targeting remote regions to provide high-speed internet access where traditional broadband is limited.
- In August 2024, TIM announced the expansion of its 5G FWA network in rural areas of Italy, aiming to connect more households and businesses with high-speed internet.
Market Concentration and Characteristics
The Europe 5G Fixed Wireless Access (FWA) market exhibits a moderate to high level of concentration, with a few key players dominating the landscape, particularly telecom giants like Deutsche Telekom, Vodafone, and Orange, which control a significant portion of the market. These players are heavily investing in 5G infrastructure to expand service offerings, targeting both urban and underserved rural areas. Alongside telecom operators, technology providers such as Ericsson, Nokia, Qualcomm, and Intel contribute to the market by supplying critical hardware and network solutions. The market is characterized by rapid innovation, with companies focusing on enhancing connectivity speeds, network reliability, and service coverage. Additionally, the growing demand for high-speed internet, driven by remote work, IoT, and digital transformation, fosters competitive dynamics, with companies continually advancing their 5G FWA solutions to differentiate themselves in this expanding market. As a result, there is significant collaboration between telecom and technology firms, alongside increasing government involvement to bridge digital gaps.
Report Coverage
The research report offers an in-depth analysis based on Offering, Operating Frequency, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The rollout of 5G networks across Europe will continue to accelerate, providing more regions with the necessary infrastructure for widespread 5G FWA adoption. This expansion will drive increased availability and coverage of high-speed broadband services.
- 5G FWA will play a pivotal role in enhancing broadband access in rural and underserved areas. The ability to deliver high-speed internet without the need for expensive fiber installation will be critical in bridging the digital divide.
- As the adoption of IoT devices and smart city technologies grows, 5G FWA will enable the necessary connectivity to support real-time data processing and communication, empowering smarter infrastructure and services across urban areas.
- The need for faster and more reliable internet will continue to grow, driven by the increase in remote work, online education, and digital entertainment. 5G FWA will serve as an ideal solution to meet this growing demand for high-speed connectivity.
- The development of private 5G networks tailored to business needs will increase, providing secure, high-performance solutions for industries such as manufacturing, logistics, and healthcare, where low latency and high-speed connections are critical.
- Innovation in 5G FWA hardware and devices, such as routers, antennas, and chipsets, will continue, improving performance, reducing costs, and enhancing the overall user experience for both consumers and businesses.
- Telecom operators and technology companies will increasingly collaborate to deliver comprehensive 5G FWA solutions. These partnerships will focus on optimizing network infrastructure and creating seamless connectivity experiences for end users.
- Governments across Europe will continue to invest in policies and initiatives aimed at ensuring equitable broadband access, especially in rural and underserved regions, thus supporting the growth of 5G FWA as a key enabler of digital inclusion.
- Hybrid connectivity models, combining 5G FWA with fiber networks, will gain popularity. This will provide a balanced solution offering both high-speed connectivity and the reliability needed for a range of applications.
- With more operators entering the 5G FWA market, competition will intensify. Telecom companies will focus on offering competitive pricing, tailored service packages, and enhanced customer support to capture market share and meet diverse consumer needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for High-Speed Broadband Connectivity
The increasing need for faster and more reliable internet to support cloud computing, streaming, gaming, telemedicine, and remote work is driving the adoption of 5G FWA across Europe, especially as traditional broadband solutions often fall short in speed and availability.
Expansion of 5G Networks and Infrastructure
Significant investments by telecom operators and governments in 5G infrastructure are enabling broader coverage and higher performance, making 5G FWA a viable solution for both urban and rural areas where fiber deployment is limited or costly.
Cost-Effectiveness and Faster Deployment
5G FWA offers a more affordable and quicker alternative to traditional wired broadband, particularly in underserved or rural regions, as it requires less physical infrastructure and can be rolled out rapidly to meet growing connectivity needs.
Rising Adoption of Remote Work and Telecommuting
The shift towards remote and hybrid work models across Europe has heightened the need for stable, high-speed internet connections in homes and remote offices, positioning 5G FWA as a practical solution for areas lacking robust wired broadband.
Integration with Emerging Technologies and Industry 4.0
The proliferation of IoT, AI, and smart city initiatives requires ultra-low latency and high-speed connectivity, which 5G FWA can provide, supporting digital transformation in sectors like manufacturing, logistics, and healthcare.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Europe 5G Fixed Wireless Access (FWA) market in 2023 and 2032?
What are the main drivers of the Europe 5G FWA market?
Which regions in Europe are leading the 5G FWA market?
What is the projected compound annual growth rate (CAGR) for the Europe 5G FWA market?
Who are the key players in the Europe 5G FWA market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Offering
- 1.2.1 Hardware
- 1.2.2 Services
- 1.3 By Application
- 1.3.1 Residential
- 1.3.2 Commercial
- 1.3.3 Industrial
- 1.3.4 Government
- 1.4 By Operating Frequency
- 1.4.1 Sub 6GHz
- 1.4.2 24-39 GHz
- 1.4.3 Above 39GHz
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 7,900.57 million → 2032: USD 84,668.10 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe 5G Fixed Wireless Access (FWA) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe 5G Fixed Wireless Access (FWA) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe 5G Fixed Wireless Access (FWA) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe 5G Fixed Wireless Access (FWA) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe 5G Fixed Wireless Access (FWA) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe 5G Fixed Wireless Access (FWA) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Europe 5G Fixed Wireless Access (FWA) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe 5G Fixed Wireless Access (FWA) Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 7,900.57 million → 2032: USD 84,668.10 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe 5G Fixed Wireless Access (FWA) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Offering - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.7.3 Industrial
- 12.4.7.4 Government
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Operating Frequency - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Sub 6GHz
- 12.5.7.2 24-39 GHz
- 12.5.7.3 Above 39GHz
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Europe 5G Fixed Wireless Access (FWA) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe 5G Fixed Wireless Access (FWA) Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Country-Level Shares, 2023
- 14.2 Country Market Size Comparison, 2023
- 14.3 Country Market Forecasts, 2023-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe 5G Fixed Wireless Access (FWA) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe 5G Fixed Wireless Access (FWA) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Deutsche Telekom AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Vodafone Group PLC
- 18.4 Orange SA
- 18.5 Telefónica SA
- 18.6 TIM SpA (Telecom Italia Mobile)
- 18.7 Ericsson
- 18.8 Nokia
- 18.9 Samsung
- 18.10 Qualcomm Technologies, Inc
- 18.11 Intel Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

