
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Activated carbon market Size 2024 | USD 5506.97 million |
| Activated carbon market, CAGR | 5.4%. |
| Activated carbon market Size 2032 | USD 8387.59 million |
Market Overview
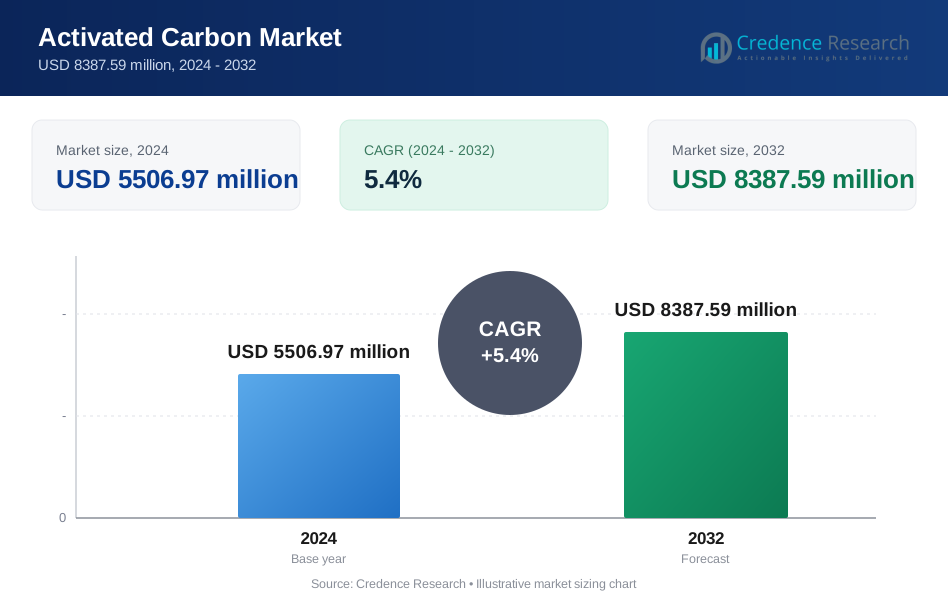
The global activated carbon market is expected to grow from USD 5506.97 million in 2024 to USD 8387.59 million by 2032, registering a CAGR of 5.4%.
The activated carbon market is driven by increasing demand across various industries, including healthcare, pharmaceuticals, water treatment, and cosmetics. Its use in detoxification and as a natural remedy for poisoning fuels growth in the medical sector. Growing awareness of its benefits in skincare, as well as its effectiveness in air and water purification, further boosts demand. Additionally, trends toward eco-friendly and sustainable solutions are encouraging the use of activated carbon in environmental applications. Innovations in product development, such as enhanced adsorption capacities and new formulations, are also contributing to the market's expansion.
The activated carbon market is geographically diverse, with key players operating in different regions to meet the growing demand across industries. North America, Europe, and Asia-Pacific are significant markets, driven by industrialization, environmental regulations, and rising awareness of air and water quality. Leading companies such as Boyce Carbon, Cabot Corporation, CarboTech AC GmbH, Haycarb (Pvt) Ltd., and Jacobi Carbons Group dominate the global market. These companies focus on technological innovations and strategic expansions to cater to the increasing demand in water treatment, air purification, and healthcare applications across various regions.
Market Drivers
Environmental Concerns and Regulations
The increasing demand for clean drinking water is underscored by various studies indicating that contaminants in water supplies pose significant health risks. For instance, research from the U.S. Environmental Protection Agency (EPA) highlights that activated carbon is recommended as a primary method for controlling synthetic organic chemicals in drinking water. This endorsement aligns with the growing regulatory emphasis on stringent water quality standards, which are aimed at ensuring public health safety. Additionally, air quality regulations are becoming more rigorous, with numerous government initiatives focused on reducing air pollution levels. Reports indicate that activated carbon is increasingly utilized in air filtration systems to meet these regulatory demands, reflecting a broader commitment to environmental sustainability.
Industrial Applications
Activated carbon's role in industrial applications is well-documented across multiple sectors. For example, the National Research Council has evaluated its effectiveness in the chemical industry, specifically noting its utility in purification and separation processes. The pharmaceutical sector also relies heavily on activated carbon for decolorizing agents during medicine production, ensuring that products meet safety and quality standards. Furthermore, a survey conducted by industry experts reveals that activated carbon is crucial in the food and beverage industry for removing impurities and enhancing product integrity. These findings illustrate the material's essential contribution to maintaining high standards across various industrial applications.
Healthcare and Personal Care
Activated carbon is gaining recognition in healthcare for its detoxifying properties, used in medical treatments like detoxification and wound care. In personal care, its ability to absorb impurities has led to its inclusion in skincare, hair care, and oral care products. As consumers seek natural solutions to improve their well-being, the demand for activated carbon in these industries is on the rise, contributing significantly to market growth.
Emerging Applications and Economic Growth
Activated carbon is being explored for innovative applications in energy storage, such as supercapacitors and batteries, offering potential for growth in the renewable energy sector. Additionally, its porous structure makes it suitable for gas storage and separation processes. As economies grow and disposable incomes rise, consumers are increasingly investing in products like air and water purifiers and personal care items containing activated carbon, further expanding the market.
Market Trends
Growth and Demand
The global activated carbon market is witnessing substantial growth due to its wide-ranging applications across various sectors. Industries like water treatment, air purification, and healthcare are increasingly turning to activated carbon to meet regulatory standards and address environmental concerns. For instance, the Centers for Disease Control and Prevention (CDC) reports that 780 million people worldwide lack access to clean water, highlighting a critical need for effective water purification solutions where activated carbon plays a vital role. Additionally, contaminated water consumption is linked to the deaths of 801,000 children under five each year, further emphasizing the urgency for robust purification methods. Rising awareness of environmental issues, coupled with stringent regulations, is driving the demand for activated carbon in air and water purification systems. This is especially true as governments worldwide push for cleaner environments and stricter air and water quality controls. Furthermore, industrial sectors such as chemicals, pharmaceuticals, and food and beverages are expanding their use of activated carbon for decolorization, purification, and odor removal, contributing significantly to the market's growth.
Key Trends and Regional Dynamics
Manufacturers are focusing on sustainability, prioritizing eco-friendly production methods and the responsible sourcing of raw materials to reduce the environmental footprint of activated carbon production. Technological innovations are also driving the development of new, enhanced products with superior performance and specialized applications for specific industries. Personal care products like skincare, haircare, and oral care are incorporating activated charcoal due to its ability to absorb impurities and toxins, further increasing its popularity. Additionally, emerging applications in energy and gas storage are expanding the scope of activated carbon’s potential. Regionally, the Asia-Pacific market is experiencing dominance, fueled by rapid industrialization and growing environmental concerns. Meanwhile, North America and Europe continue to show growth, particularly in high-quality activated carbon products and advanced applications. However, the market also faces challenges such as the availability of raw materials, price fluctuations, and evolving regulatory landscapes, which can impact both supply chains and demand. Despite these challenges, the market remains buoyed by opportunities in sustainability and innovation.
Market Challenges Analysis
Raw Material Availability and Cost
Activated carbon manufacturers face significant challenges regarding the availability and cost of raw materials, such as coconut shells and wood. Natural disasters, such as hurricanes and floods, along with fluctuations in agricultural production, can disrupt the supply chain, making it difficult to secure these essential raw materials. Additionally, price volatility in these raw materials adds to the uncertainty, directly impacting the cost of production and profit margins for manufacturers. As the demand for activated carbon increases across various industries, maintaining a stable and cost-effective supply of raw materials is crucial to sustain growth in the market. To mitigate these issues, manufacturers must explore sustainable sourcing strategies, diversify their suppliers, and improve supply chain resilience to reduce the impact of disruptions and price fluctuations.
Regulatory Hurdles and Market Competition
The activated carbon market is also challenged by stringent environmental regulations, particularly those related to wastewater treatment and air pollution control. Compliance with these regulations can be costly and complex, requiring manufacturers to adapt their production processes and product formulations regularly. For example, the Environmental Protection Agency (EPA) has set strict standards for the exposure of chemicals due to their toxicity, which leads to adverse effects on human health. As regulations evolve, manufacturers must stay updated to ensure continued compliance, which can lead to increased operational costs. Along with regulatory hurdles, the market is becoming increasingly saturated, with numerous competitors offering a wide range of activated carbon products. This intense competition places pressure on prices, reducing profit margins for many manufacturers. In response to these challenges, companies need to invest in technological innovations, improve quality control processes, and build strong brand awareness to differentiate their products. Additionally, strategic partnerships can help share knowledge, reduce costs, and improve market positioning. Furthermore, educating consumers about the benefits and applications of activated carbon can increase awareness and mitigate misconceptions that may hinder adoption.
Market Segmentation Analysis:
By Type:
The activated carbon market can be segmented based on product type into powdered activated carbon (PAC), granular activated carbon (GAC), and other specialized types. PAC is widely used in applications such as water treatment, air purification, and food processing due to its fine particle size and high surface area, which enhances adsorption efficiency. On the other hand, GAC is preferred in larger-scale applications, including industrial air and water treatment, due to its ability to be reactivated and reused, making it cost-effective. The "Other Types" category includes pelletized activated carbon and cloth-based activated carbon, which are gaining traction for specific applications such as mercury removal and in personal protective equipment. The demand for different types of activated carbon is driven by the specific needs of the industries, with each type offering distinct advantages in terms of efficiency, cost-effectiveness, and ease of use.
By Raw Material:
The raw material used in the production of activated carbon plays a significant role in determining its properties and applications. The primary raw materials include coal, coconut shells, wood, and peat. Coal-based activated carbon is widely used in industrial applications due to its high hardness and ability to adsorb a wide range of contaminants. Coconut shell-based activated carbon is in high demand for water purification and air filtration, owing to its high adsorption capacity and micropore structure. Wood and peat-based activated carbon are commonly used in applications where lower hardness is acceptable, such as in the food and beverage industry. The choice of raw material is largely influenced by the desired characteristics of the activated carbon and the specific application requirements. The rising focus on sustainable sourcing and environmental concerns is driving the demand for coconut-based and other eco-friendly activated carbon products.
Segments:
Based on Type:
- Powdered Activated Carbon
- Granular Activated Carbon
- Other Types
Based on Raw Material:
- Coal
- Coconut
- Wood
- Peat
- Other Raw Materials
Based on Application:
- Liquid Phase Application
- Gas Phase Application
Based on End-use Industry:
- Water Treatment
- Food & Beverages
- Pharmaceutical & Medical
- Automotive
- Industrial
- Other End-use Industries
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a prominent share in the market, accounting for approximately 35% of the global market share. The demand in this region is primarily driven by stringent environmental regulations, particularly in water treatment and air pollution control. The United States is the major contributor, with the increased focus on industrial applications, such as chemical and pharmaceutical processing, further boosting market demand. Additionally, the presence of key market players in the region, along with strong technological advancements, positions North America as a key market for activated carbon in various end-use industries, including healthcare and personal care.
Asia-Pacific
In contrast, the Asia-Pacific region is expected to witness the highest growth rate, with a market share of around 32%. The region's rapid industrialization, particularly in emerging economies like China and India, is fueling the demand for activated carbon. The increasing use of activated carbon in water and air purification systems is a key driver, along with growing concerns over environmental pollution. The expanding industrial base in countries like China and Japan, coupled with increased investments in environmental protection and clean technology, further supports the growth of activated carbon demand. The region is also a significant production hub, supplying both regional and global markets with activated carbon from raw materials like coconut shells and coal, contributing to the region's substantial market share.
Key Player Analysis
- Boyce Carbon
- CarbPure Technologies
- CarboTech AC GmbH
- Donau Chemie AG
- Haycarb (Pvt) Ltd.
- Cabot Corporation
- Evoqua Water Technologies LLC
- Osaka Gas Chemicals Co., Ltd.
- Kureha Corporation
- Kuraray Co.
- Carbon Activated Corporation
- Jacobi Carbons Group
- Hangzhou Nature Technology Co., Ltd.
- Sorbent JSC
- CarbUSA
Competitive Analysis
The activated carbon market is highly competitive, with several leading players focusing on innovation, product development, and regional expansion. Companies such as Boyce Carbon, Cabot Corporation, CarboTech AC GmbH, Haycarb (Pvt) Ltd., Jacobi Carbons Group, and Evoqua Water Technologies LLC are prominent players, consistently striving to enhance their market position. These companies are investing in research and development to improve product performance and meet the evolving demands for environmental sustainability, such as eco-friendly and high-efficiency activated carbon solutions. Strategic collaborations, mergers, and acquisitions are common among these players to expand their product portfolios and geographical reach. Additionally, the companies focus on optimizing manufacturing processes to reduce costs and enhance product quality. As the market grows, competition will intensify, pushing companies to adopt advanced technologies and differentiate their offerings to maintain a competitive edge in the global activated carbon market.
Recent Developments
- In January 2024, Germany-based chemical manufacturer Nordmannacquired Italy-based SD Chemicals S.r.l., a distributor of raw materials catering to the cosmetics industry catering to skin care, hair care and makeup applications. This acquisition will enable Nordmann to expand its presence and enhance customer reach.
- In January 2023, Ningbo Juhua Chemical & Science Co., Ltd. awarded a contract to Technip Energies for a Activated Carbon plant with an annual capacity of 72 kilo tons in Ningbo, Zhejiang, China. This is part of the company’s initiative to expand its petrochemical new material business.
- In March 2023, Evoqua Water Technologies LLC strengthened its presence in North America through the acquisition of the Texas-based industrial water treatment service business from Kemco Systems.
- In March 2023, Cabot Corporation recently launched the EVOLVE technology program that is involved in advancing sustainable reinforcing carbons. The purpose of the new technology launch is to recover the carbon product from the end-life tiers to renew the waste and reduce the carbon content.
- In June 2022, Albemarle Corporation announced that it is expected to restructure its Bromine and Lithium global business units (GBUs) as part of a new corporate framework aimed at enhancing its ability to meet customer demands and cultivate the necessary talent to thrive in a competitive global landscape.
- In August 2022, Ingevity acquired Nexeon Limited to establish its presence in the electric vehicle (EV) market and expand the opportunities of its existing activated carbon business.
Market Concentration & Characteristics
The activated carbon market exhibits moderate concentration, with a few key players dominating the landscape, while numerous smaller companies contribute to the overall market dynamics. Major players like Boyce Carbon, Cabot Corporation, CarboTech AC GmbH, and Jacobi Carbons Group hold substantial market shares due to their extensive product portfolios, strong distribution networks, and global reach. The market is characterized by a high degree of competition, with companies focusing on technological advancements, sustainable production, and tailored solutions to meet specific industrial requirements. While large companies dominate in terms of production capacity and resources, smaller companies often specialize in niche segments such as premium or eco-friendly activated carbon products. The market is also witnessing increased demand from emerging sectors like energy storage, air purification, and wastewater treatment. Regulatory pressures on environmental sustainability are prompting companies to adopt cleaner and more efficient production practices, shaping the overall market characteristics and concentration.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Type, Raw Material, Application, End-use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The activated carbon market will continue to grow due to increasing demand in water and air purification.
- Advancements in production technologies will lead to more efficient and sustainable activated carbon products.
- The market will see a rise in eco-friendly and sustainable sourcing practices as environmental concerns increase.
- The food and beverage industry will drive significant demand for activated carbon for decolorization and impurity removal.
- Emerging applications in energy storage and gas separation will open new growth opportunities.
- Regulatory pressures on air and water quality will push for higher adoption of activated carbon solutions.
- Manufacturers will focus on developing specialized products to meet the growing needs of industries such as pharmaceuticals and healthcare.
- Increasing industrialization in emerging markets like Asia-Pacific will further fuel the demand for activated carbon.
- E-commerce platforms will become key sales channels for activated carbon products, offering broader accessibility.
- Companies will increasingly invest in R&D to create innovative products that offer enhanced performance and cater to specific consumer needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Activated Carbon Market?
What factors are driving the growth of the Activated Carbon Market?
What are the key segments within the Activated Carbon Market?
What are some challenges faced by the Activated Carbon Market?
Who are the major players in the Activated Carbon Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5506.97 million → 2032: USD 8387.59 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Activated Carbon Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Activated Carbon Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Activated Carbon Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Activated Carbon Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Activated Carbon Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Activated Carbon Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Activated Carbon Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Activated Carbon Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5506.97 million → 2032: USD 8387.59 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Activated Carbon Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Activated Carbon Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Activated Carbon Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Activated Carbon Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
