
Market Overview:
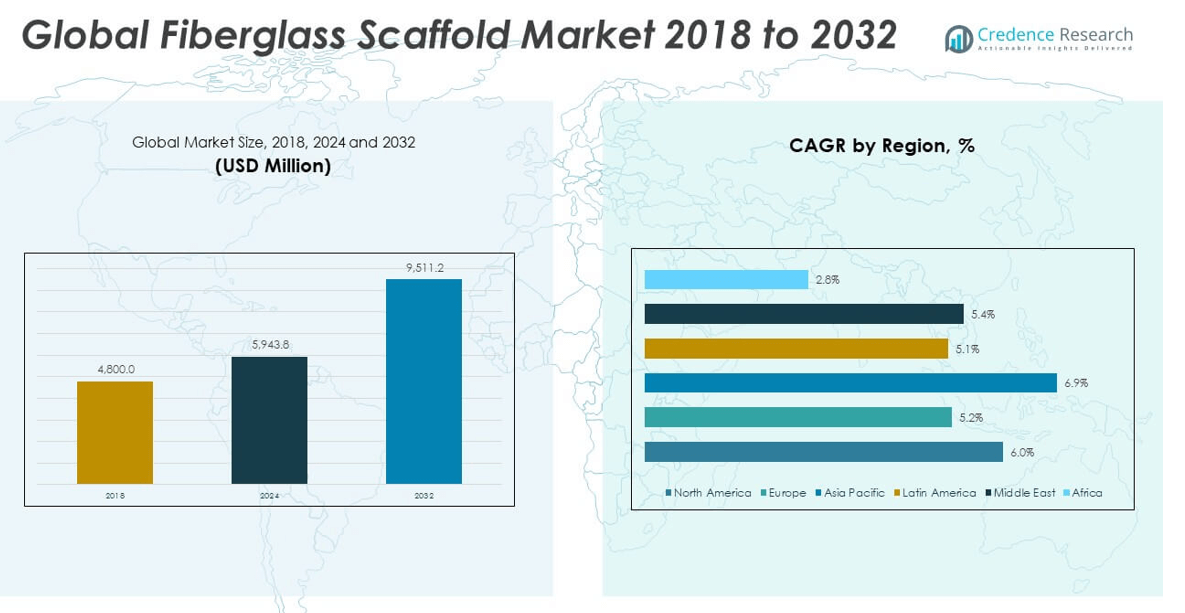
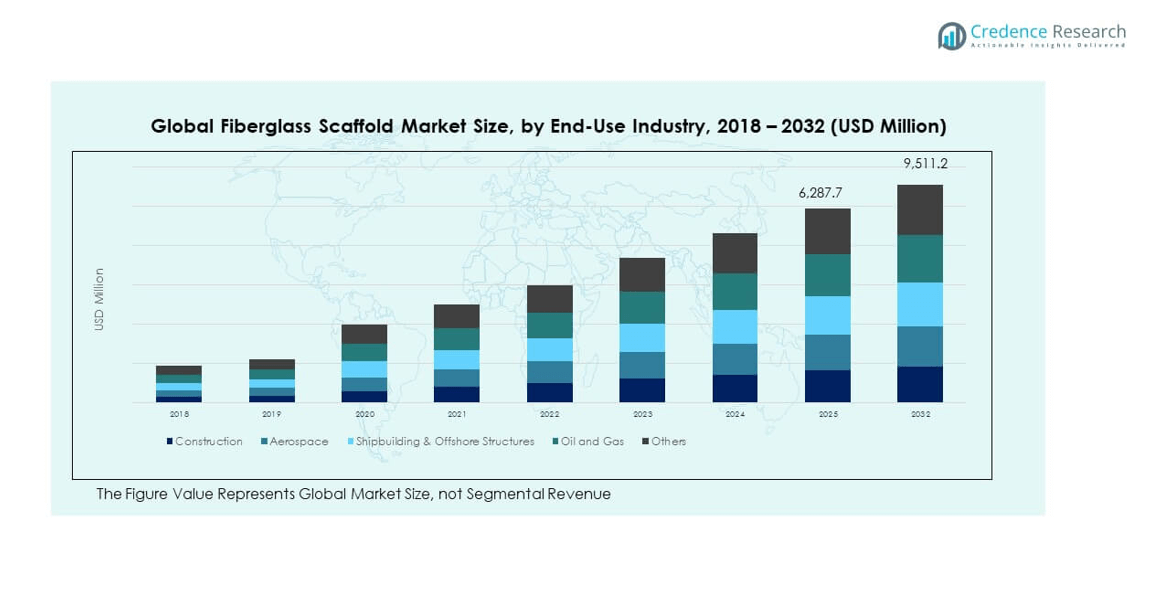
The Global Fiberglass Scaffold Market size was valued at USD 4,800.0 million in 2018 to USD 5,943.8 million in 2024 and is anticipated to reach USD 9,511.2 million by 2032, at a CAGR of 6.09% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fiberglass Scaffold Market Size 2024 | USD 5,943.8 million |
| Fiberglass Scaffold Market, CAGR | 6.09% |
| Fiberglass Scaffold Market Size 2032 | USD 9,511.2 million |
Market growth is driven by increasing demand for lightweight, corrosion-resistant scaffolding solutions in construction, maintenance, and industrial applications. Fiberglass scaffolds are preferred for their non-conductive properties, making them suitable for electrical and chemical environments. The growing emphasis on worker safety, coupled with regulatory requirements for using non-metallic scaffolding in certain industries, is boosting adoption. Advancements in fiberglass manufacturing technology are further enhancing product durability and load-bearing capacity.
Regionally, North America leads the fiberglass scaffold market due to strict safety regulations, high industrial maintenance activities, and widespread adoption in the utility and construction sectors. Europe follows, supported by stringent workplace safety laws and increasing infrastructure renovation projects. Asia-Pacific is emerging as the fastest-growing region, driven by rapid urbanization, industrial expansion, and rising investments in infrastructure across countries like China and India. Latin America and the Middle East are also witnessing steady growth, supported by ongoing construction and oil & gas sector developments.
Market Insights:
- The Global Fiberglass Scaffold Market was valued at USD 4,800.0 million in 2018, reached USD 5,943.8 million in 2024, and is projected to hit USD 9,511.2 million by 2032, registering a CAGR of 6.09% during the forecast period.
- Increasing demand for lightweight, non-conductive, and corrosion-resistant scaffolding in construction, industrial maintenance, and offshore projects is a key growth driver.
- Rising workplace safety standards and strict regulatory compliance are encouraging the adoption of fiberglass scaffolds across high-risk environments.
- Technological advancements in fiberglass manufacturing, including improved resin formulations and modular designs, are enhancing durability and performance.
- High initial costs compared to steel or aluminum scaffolds and limited awareness among small contractors are restraining market expansion.
- North America leads the market, driven by stringent safety regulations and strong industrial maintenance activities, while Europe follows with high adoption in infrastructure renovation.
- Asia-Pacific is witnessing the fastest growth, fueled by rapid urbanization, industrial expansion, and large-scale infrastructure investments in countries like China and India.
Market Drivers:
Rising Demand for Corrosion-Resistant and Lightweight Scaffolding Solutions in Construction and Industrial Sectors:
The Global Fiberglass Scaffold Market is experiencing significant momentum due to its superior material properties compared to traditional steel or aluminum scaffolds. It offers corrosion resistance, making it ideal for chemical plants, offshore facilities, and coastal construction sites where metal scaffolds deteriorate quickly. The non-conductive nature of fiberglass ensures worker safety in electrical environments, which has increased its adoption in power generation and maintenance projects. Construction companies are focusing on reducing downtime, and the lighter weight of fiberglass scaffolds supports faster installation and dismantling. Regulatory requirements in multiple industries are mandating the use of scaffolding materials that minimize electrical hazards. Increasing investments in infrastructure repair and facility maintenance are reinforcing demand. Oil and gas sectors, particularly offshore drilling platforms, are embracing fiberglass for its long service life. Continuous innovation in resin technology is further enhancing its strength and load capacity.
- For instance, Fibergrate replaced steel scaffolds in chemical plants with their FRP platforms and achieved a substantial reduction in corrosion-related maintenance, extending replacement cycles for scaffolds by up to 40% in corrosive environments. The non-conductive nature of fiberglass ensures worker safety in electrical environments, which has increased its adoption in power generation and maintenance projects.
Growing Emphasis on Workplace Safety Standards and Compliance with Industry Regulations:
Workplace safety remains a top priority across industries, and fiberglass scaffolding provides compliance advantages that drive market expansion. Governments and regulatory bodies in North America, Europe, and Asia-Pacific have strengthened guidelines on using non-metallic materials in high-risk environments. The Global Fiberglass Scaffold Market benefits from these regulations, as it aligns with requirements for non-conductivity and enhanced worker protection. Large industrial projects are prioritizing materials that reduce the risk of electrical shocks and fire hazards. Insurance companies are also influencing purchasing decisions by offering better terms for safer scaffold installations. Construction projects in refineries, substations, and chemical plants often specify fiberglass scaffolding in procurement tenders. Safety certifications such as ANSI, OSHA, and EN standards are encouraging contractors to invest in compliant scaffolding systems. The rising number of workplace safety audits is pushing industries toward adopting fiberglass scaffolding over conventional alternatives.
- For instance, National Ladder & Scaffold Co. supplies fiberglass scaffolding certified to meet ANSI standards for non-conductivity and chemical resistance, helping construction contractors reduce electrical incident rates in confined plant spaces. The Global Fiberglass Scaffold Market benefits from these regulations, as it aligns with requirements for non-conductivity and enhanced worker protection. Large industrial projects are prioritizing materials that reduce the risk of electrical shocks and fire hazards. I
Expanding Infrastructure Development in High-Risk and Harsh Environmental Conditions:
Infrastructure expansion in regions with extreme climates is boosting demand for durable scaffolding solutions. Fiberglass scaffolds maintain structural integrity in both high-humidity tropical areas and freezing cold zones, making them suitable for diverse geographies. The Global Fiberglass Scaffold Market is leveraging these advantages to capture opportunities in projects such as bridges, dams, tunnels, and power plants. Harsh industrial environments like petrochemical refineries and desalination plants require scaffolds that resist chemical degradation. Offshore wind farms and marine construction projects prefer fiberglass for its low maintenance requirements. Construction firms benefit from reduced replacement cycles, lowering overall project costs. Infrastructure stimulus programs in emerging economies are creating long-term procurement pipelines for scaffold manufacturers. The ability to perform in challenging environments without compromising safety makes fiberglass a preferred choice for specialized applications.
Technological Advancements in Fiberglass Manufacturing Enhancing Product Performance:
Innovations in pultrusion technology and advanced resin formulations are improving the performance and lifespan of fiberglass scaffolds. The Global Fiberglass Scaffold Market is witnessing the introduction of products with higher load-bearing capacity, better UV resistance, and improved impact strength. Manufacturers are developing modular scaffold systems that are easier to transport and assemble on-site. Enhanced slip-resistant surfaces and ergonomic designs are increasing worker comfort and productivity. New resin systems are offering greater resistance to fire and chemicals, expanding application possibilities. The integration of RFID and IoT-enabled components for scaffold tracking is improving inventory management for large contractors. Automation in manufacturing is reducing costs and improving product consistency. These advancements are helping fiberglass scaffolds compete more effectively against aluminum and steel alternatives in multiple industries.
Market Trends:
Rising Adoption of Modular and Customizable Fiberglass Scaffold Systems:
The demand for modular scaffold systems that can be quickly assembled and adapted to complex structures is increasing. The Global Fiberglass Scaffold Market is benefiting from the development of customizable solutions that cater to diverse project requirements. Modular designs reduce labor hours and enhance on-site flexibility, especially in maintenance and renovation projects. Industries are favoring scaffold systems that allow height adjustments and easy integration with safety accessories. Custom engineering for unique structures, such as ship hulls and refinery towers, is becoming common. Quick-lock mechanisms are replacing conventional fastening methods to speed up assembly. The trend toward compact storage solutions is also influencing scaffold design. These advancements are helping companies save time and reduce operational costs while maintaining safety standards.
- For instance, MJ-Gerüst’s COMBI metric modular scaffolding system offers up to eight connections per knot, with freely selectable intervals in heights of 0.50m, enabling flexible adjustments for industrial, shipbuilding, or refinery projects. Modular designs reduce labor hours and enhance on-site flexibility, especially in maintenance and renovation projects. Industries are favoring scaffold systems that allow height adjustments and easy integration with safety accessories.
Integration of Digital Technologies for Scaffold Safety and Asset Management:
Digital transformation is influencing scaffold management practices across industries. The Global Fiberglass Scaffold Market is seeing the integration of RFID tags, GPS tracking, and IoT-based monitoring systems. These technologies allow project managers to track scaffold usage, maintenance schedules, and location in real time. Digital inspection tools and safety sensors are being used to ensure compliance with safety regulations. Mobile applications are enabling remote inspection approvals, reducing project delays. Data analytics is being applied to optimize scaffold inventory distribution across multiple sites. The ability to monitor scaffold conditions helps reduce accidents and extend service life. Digital tools are also enhancing transparency in large-scale infrastructure projects. This technology-driven approach is increasing efficiency and reducing project risks.
- For instance, Avontus provides scaffold asset management software that, using RFID and cloud integration, has enabled scaffolding contractors to improve time utilization rates to 70–80% on high-turnover projects and reduce lost inventory incidents by over 10% in one year. These technologies allow project managers to track scaffold usage, maintenance schedules, and location in real time. Digital inspection tools and safety sensors are being used to ensure compliance with safety regulations.
Expanding Application in Renewable Energy and Offshore Projects:
Renewable energy projects such as wind and solar farms are creating new opportunities for fiberglass scaffolding. The Global Fiberglass Scaffold Market is benefiting from the need for lightweight, corrosion-resistant solutions in offshore and elevated installations. Fiberglass scaffolds are being used extensively for turbine maintenance and solar panel installation due to their electrical insulation properties. Offshore oil platforms and wind farms require scaffolds that withstand saltwater exposure and high winds. Contractors are increasingly choosing fiberglass over steel to minimize corrosion-related downtime. These projects often demand scaffolds that can be assembled in confined or elevated spaces. The growth of renewable energy infrastructure worldwide is creating steady demand for fiberglass scaffolds. Market players are tailoring designs specifically for these high-growth segments.
Increasing Use of Hybrid Scaffold Systems Combining Fiberglass with Other Materials:
Hybrid scaffolds that combine fiberglass with aluminum or steel components are gaining traction. The Global Fiberglass Scaffold Market is responding to the demand for systems that balance strength, weight, and cost. These hybrids are particularly useful in applications where full fiberglass systems may be cost-prohibitive. Combining materials allows for tailored solutions that maximize performance in specific conditions. For example, fiberglass platforms may be paired with aluminum frames for enhanced stability. Hybrid systems are also easier to repair and maintain, extending their lifespan. This trend is attracting industries looking for cost-effective yet high-performance scaffolding solutions. Manufacturers are investing in R&D to refine hybrid product lines for broader adoption.
Market Challenges Analysis:
High Initial Costs and Limited Awareness Among End Users:
The higher upfront cost of fiberglass scaffolds compared to steel or aluminum alternatives remains a major barrier to widespread adoption. The Global Fiberglass Scaffold Market faces resistance from small and medium-sized contractors with tight budgets. While long-term savings from reduced maintenance and replacement costs are significant, many buyers prioritize immediate expenditure over lifecycle value. Limited awareness of fiberglass scaffolding’s benefits also slows adoption in certain regions. Training requirements for proper installation and handling can further deter potential buyers. Some projects still prefer traditional materials due to familiarity and established supply chains. Manufacturers are addressing this challenge through targeted marketing and cost-reduction strategies. Educating customers about safety advantages and long-term cost efficiency is critical for market growth.
Supply Chain Limitations and Dependence on Specialized Manufacturing:
Fiberglass scaffolding production relies on specialized manufacturing processes and raw materials, making supply chains vulnerable to disruption. The Global Fiberglass Scaffold Market can be affected by fluctuations in resin and glass fiber availability. Production delays may occur when suppliers face capacity constraints or transportation issues. The need for precision in fabrication limits the number of qualified manufacturers, leading to longer lead times. International trade restrictions and tariffs can also impact material costs. Storage and transportation require careful handling to prevent damage, adding to logistical complexity. These supply chain constraints may hinder the ability to meet sudden spikes in demand. Strategic sourcing and localized manufacturing could help reduce these vulnerabilities.
Market Opportunities:
Expansion in Emerging Economies with Growing Infrastructure Investments:
Emerging economies are investing heavily in infrastructure, creating a fertile ground for fiberglass scaffold adoption. The Global Fiberglass Scaffold Market can tap into large-scale projects in Asia-Pacific, Latin America, and the Middle East. Governments are funding transportation, energy, and industrial development that require safe, durable scaffolding solutions. Contractors in these regions are increasingly seeking materials that withstand harsh weather and chemical exposure. The expansion of manufacturing hubs is boosting demand for industrial maintenance scaffolds. Introducing cost-competitive models tailored for these markets can accelerate penetration. Partnerships with local distributors and training programs can further increase adoption rates.
Product Diversification for Specialized Industrial Applications:
There is significant potential in diversifying product offerings to serve niche applications such as aerospace, shipbuilding, and pharmaceuticals. The Global Fiberglass Scaffold Market can benefit from designing scaffolds for environments with strict safety and hygiene requirements. Custom-engineered platforms for confined spaces or high-altitude work can differentiate products in a competitive landscape. Developing foldable or mobile fiberglass scaffolds can target maintenance and emergency repair markets. Offering specialized coatings for UV resistance or chemical protection can open additional revenue streams. Collaborating with industry-specific contractors can enhance product relevance and demand.
Market Segmentation Analysis:
By Product Type
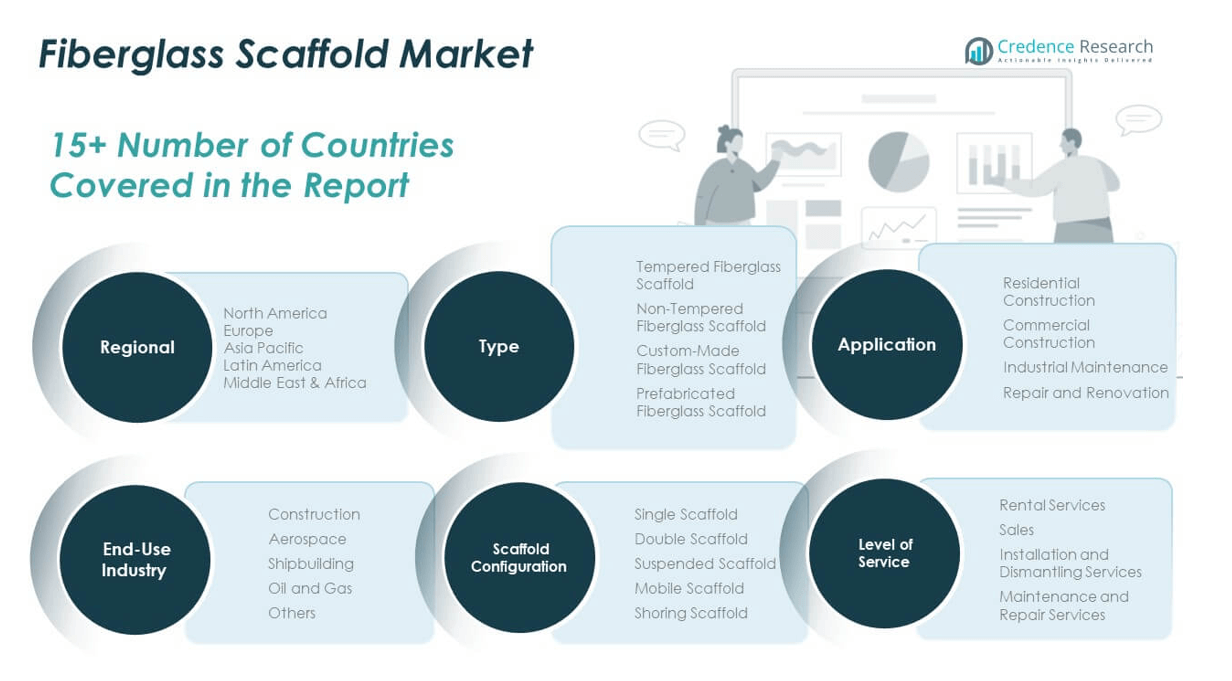
The Global Fiberglass Scaffold Market is segmented into tempered, non-tempered, custom-made, and prefabricated fiberglass scaffolds. Tempered variants lead the segment due to their superior strength, impact resistance, and suitability for high-load and long-duration projects. Non-tempered scaffolds are chosen for applications requiring flexibility and lighter structures. Custom-made designs address unique industrial, aerospace, or offshore requirements where standard solutions are insufficient. Prefabricated scaffolds are gaining traction for their quick assembly, consistent quality, and suitability for projects with tight timelines.
- For instance, tempered fiberglass scaffolds from National Ladder & Scaffold Co. are manufactured to support standing heights of up to 29ft for maintenance tasks, providing non-conductive safe access in hazardous locations. Non-tempered scaffolds are chosen for applications requiring flexibility and lighter structures.
By Application
Applications include residential construction, commercial construction, industrial maintenance, and repair and renovation. Commercial construction dominates due to large-scale infrastructure and real estate projects. Industrial maintenance is expanding in sectors where corrosion resistance and electrical insulation are crucial. Residential use benefits from lightweight handling, while the repair and renovation segment leverages modularity and reusability to work efficiently in confined or complex structures.
- For instance, Fibergrate supplied FRP platform systems to commercial building sites, reducing scaffold re-inspection intervals by 20% thanks to improved durability in outdoors and high-humidity environments. Industrial maintenance is expanding in sectors where corrosion resistance and electrical insulation are crucial. Residential use benefits from lightweight handling, while the repair and renovation segment leverages modularity and reusability to work efficiently in confined or complex structures.
By End-User Industry
End users include construction, aerospace, shipbuilding, oil and gas, and others. Construction holds the largest share due to ongoing urbanization and infrastructure development. Aerospace and shipbuilding industries adopt fiberglass scaffolds for safety and corrosion resistance. Oil and gas facilities prefer them for offshore and chemical-exposed environments. Other users include event staging, utilities, and manufacturing sectors with specialized access requirements.
By Scaffold Configuration
Configurations include single, double, suspended, mobile, and shoring scaffolds. Single and double scaffolds are widely used for standard building projects. Suspended scaffolds are essential for high-rise and offshore operations. Mobile scaffolds provide flexible movement for indoor and warehouse settings, while shoring scaffolds ensure stability during structural support tasks.
By Level of Service
Service levels include rental services, sales, installation and dismantling services, and maintenance and repair services. Rentals dominate due to cost efficiency and short-term needs, while sales cater to companies seeking long-term assets. Installation and dismantling services ensure compliance with safety standards. Maintenance and repair services extend scaffold lifespan, improving return on investment for asset owners.
Segmentation:
By Product Type
- Tempered Fiberglass Scaffold
- Non-Tempered Fiberglass Scaffold
- Custom-Made Fiberglass Scaffold
- Prefabricated Fiberglass Scaffold
By Application
- Residential Construction
- Commercial Construction
- Industrial Maintenance
- Repair and Renovation
By End-User Industry
- Construction
- Aerospace
- Shipbuilding
- Oil and Gas
- Others
By Scaffold Configuration
- Single Scaffold
- Double Scaffold
- Suspended Scaffold
- Mobile Scaffold
- Shoring Scaffold
By Level of Service
- Rental Services
- Sales
- Installation and Dismantling Services
- Maintenance and Repair Services
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Global Fiberglass Scaffold Market size was valued at USD 1,363.2 million in 2018 to USD 1,661.9 million in 2024 and is anticipated to reach USD 2,643.3 million by 2032, at a CAGR of 6.0% during the forecast period. North America holds approximately 28% of the global market share. Strong demand stems from the construction, oil and gas, and industrial maintenance sectors. Strict safety regulations and OSHA compliance standards encourage the use of non-conductive, corrosion-resistant scaffolds. The region benefits from high adoption in infrastructure renovation, commercial building projects, and utility maintenance. Leading players maintain robust distribution networks and rental services to support both short-term and long-term projects. The U.S. dominates regional consumption, with Canada and Mexico contributing steadily through industrial expansion. Growth is also driven by technological advancements and product customization to meet industry-specific needs.
Europe
The Europe Global Fiberglass Scaffold Market size was valued at USD 1,020.5 million in 2018 to USD 1,202.9 million in 2024 and is anticipated to reach USD 1,791.8 million by 2032, at a CAGR of 5.2% during the forecast period. Europe accounts for around 20% of the global market share. The region’s demand is shaped by strict workplace safety directives and strong adoption in commercial construction and industrial refurbishment. Countries like Germany, the UK, and France lead usage due to advanced industrial sectors and large-scale renovation programs. Marine and offshore industries in Northern Europe also contribute significantly. The emphasis on sustainable materials supports fiberglass adoption over traditional metals. Rental service penetration is high, catering to varying project scales. Economic stability and ongoing urban redevelopment fuel steady growth.
Asia Pacific
The Asia Pacific Global Fiberglass Scaffold Market size was valued at USD 1,857.6 million in 2018 to USD 2,364.7 million in 2024 and is anticipated to reach USD 4,034.0 million by 2032, at a CAGR of 6.9% during the forecast period. Asia Pacific holds the largest share at approximately 40% of the global market. Rapid urbanization, infrastructure investment, and industrial growth in China, India, and Southeast Asia drive strong demand. Construction booms in commercial and residential sectors are major contributors. Industrial maintenance in manufacturing hubs increases the need for corrosion-resistant and safe scaffolding systems. Offshore energy projects in Australia and Southeast Asia also add to demand. Competitive pricing from regional manufacturers strengthens adoption. Local government safety campaigns promote modern scaffold solutions, accelerating the transition from traditional steel structures.
Latin America
The Latin America Global Fiberglass Scaffold Market size was valued at USD 297.6 million in 2018 to USD 364.9 million in 2024 and is anticipated to reach USD 540.9 million by 2032, at a CAGR of 5.1% during the forecast period. Latin America contributes about 6% of the global market share. Growth is supported by construction and oil industry expansion in Brazil, Argentina, and Chile. Increasing investments in commercial complexes, infrastructure modernization, and industrial maintenance support demand. Offshore projects along the Atlantic coast require corrosion-resistant scaffolds. Adoption is slower compared to developed regions due to cost constraints, but rental services are helping bridge the gap. Governments are introducing safety regulations to standardize scaffold usage, boosting demand over the forecast period.
Middle East
The Middle East Global Fiberglass Scaffold Market size was valued at USD 196.8 million in 2018 to USD 229.4 million in 2024 and is anticipated to reach USD 345.2 million by 2032, at a CAGR of 5.4% during the forecast period. The Middle East holds about 4% of the global market share. Oil and gas, petrochemicals, and large infrastructure projects in GCC countries dominate demand. The harsh desert climate and chemical exposure in industrial settings make fiberglass scaffolds preferable. Mega-projects such as stadiums, airports, and commercial towers drive high-volume procurement. Saudi Arabia, UAE, and Qatar are leading users, supported by ambitious development plans under Vision 2030 and similar initiatives. Industrial maintenance requirements in refineries and desalination plants also sustain steady demand.
Africa
The Africa Global Fiberglass Scaffold Market size was valued at USD 64.3 million in 2018 to USD 120.1 million in 2024 and is anticipated to reach USD 155.9 million by 2032, at a CAGR of 2.8% during the forecast period. Africa represents about 2% of the global market share. Demand is largely concentrated in South Africa, Egypt, and Nigeria. The region’s adoption is influenced by mining, oil and gas, and infrastructure repair activities. High import dependency and budget limitations restrain faster adoption. Industrial sectors prioritize durability and safety in projects requiring scaffolding for power plants and manufacturing facilities. Growth potential lies in expanding commercial construction in urban areas. Strategic partnerships with local distributors are essential for increasing penetration in the region.
Key Player Analysis:
- Altrex B.V.
- Tubesca-Comabi
- Werner Co.
- Layher Holding GmbH & Co. KG
- PERI Group
- Harsco Corporation
- Instant Upright Ltd.
- Stepup Scaffold
- Sunbelt Rentals, Inc.
- BrandSafway
- Waco International
- Altrad Group
- ULMA Construction
- KHK Scaffolding & Formwork LLC
- Apollo Scaffold Services Ltd.
- Safway Group Holding LLC
- Lyndon SGB by BrandSafway
Competitive Analysis:
The Global Fiberglass Scaffold Market is competitive, with leading players focusing on innovation, compliance, and expanding market reach. Established companies such as Layher, PERI Group, Altrad, BrandSafway, and ULMA dominate through diversified product portfolios, advanced manufacturing capabilities, and global distribution networks. It is driven by continuous product upgrades, safety enhancements, and adaptation to industry-specific needs. Mid-tier players compete through cost-effective solutions, niche product offerings, and regional presence. Strategic partnerships with contractors, distributors, and rental service providers strengthen market positioning. Investments in automation, quality control, and modular design are critical for maintaining competitiveness. Market leadership depends on brand reliability, adherence to safety standards, and the ability to deliver durable, corrosion-resistant scaffolding systems tailored to varied applications.
Recent Developments:
- In April 2024, Altrex B.V. and Pop Up Products Limited renewed and extended their long-standing partnership for sales and distribution of mobile access towers, ladders, and associated products in the UK and Ireland through 2034. This collaboration, which began in 2009, has already led to innovative product launches such as the world's first one-person erect tower range (MiTOWER series) and the successful delivery of over 14,500 MI TOWER units into the regional market, demonstrating significant mutual growth and technical advancement.
- In June 2025, Tubesca-Comabi formed a strategic supply agreement with JLG’s Power Towers division, making Tubesca-Comabi the OEM partner for France. The partnership launched the R'Lift Smart range-a new push-around lift available in three working heights, featuring a folding composite platform and advanced safety mechanisms. Additionally, it brought Tubesca-branded versions of the Ecolift to the French market, expanding access equipment options with proven safety and operational efficiencies.
- On August 5, 2024, Werner Co. announced a corporate name change to ProDriven Global Brands, reflecting the organization’s transformation into a portfolio of brands serving the professional construction, industrial, and automotive markets. This newly rebranded entity maintains the Werner label and its other key brands globally, with no changes to their product lines or business relationships.
- In April 2025, Layher Holding GmbH & Co. KG commenced operations at a new, highly automated and energy-efficient production facility, "Plant 3". This expansive, 27-acre production center is dedicated to Allround Scaffolding components. With advanced digitalization, automation, photovoltaic systems, and a BEG 40 energy efficiency standard, this facility increases both production capacity and product quality for large-scale scaffolding projects, reinforcing Layher’s commitment to operational excellence and customer delivery readiness.
- In March 2024, Instant Upright Ltd. announced the upcoming launch of their Roof Edge Protection System-an adaptable, durable edge protection platform designed for rapid installation on flat and pitched roofs up to 10 degrees. The new system, built in compliance with BS EN 13374:2013 Class A and BS 13700:2021 safety standards, is engineered for longevity in challenging site conditions and aims to enhance construction worker safety across diverse project sites.
Market Concentration & Characteristics:
The Global Fiberglass Scaffold Market is moderately concentrated, with a few multinational companies holding significant market share alongside regional manufacturers serving niche needs. It is characterized by high entry barriers due to stringent safety certifications, specialized manufacturing requirements, and advanced material technology. Demand is driven by industrial maintenance, construction, and offshore projects, with strong emphasis on non-conductive and corrosion-resistant properties. Competition revolves around quality, regulatory compliance, service capabilities, and innovation in scaffold design. Long-term contracts, rental services, and strong distribution networks play a vital role in sustaining competitive advantage.
Report Coverage:
The research report offers an in-depth analysis based on end-user industry, scaffold configuration, product type, level of service and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Strong demand expected from infrastructure development and large-scale urban construction projects worldwide.
- Rising adoption in oil, gas, and petrochemical facilities due to corrosion resistance and safety benefits.
- Technological innovations to improve modularity, load-bearing strength, and UV/fire resistance.
- Increased market penetration in renewable energy sectors, including offshore wind and solar installations.
- Growing use in aerospace and shipbuilding industries for non-conductive and lightweight access solutions.
- Expansion of rental services to meet cost-sensitive customer requirements.
- Higher adoption rates in Asia-Pacific driven by industrialization and rapid urban expansion.
- Strategic collaborations and joint ventures among global and regional players to strengthen distribution.
- Development of hybrid scaffolding systems combining fiberglass with metals for enhanced performance.
- Stricter workplace safety regulations prompting faster replacement of traditional scaffolding materials.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Lightweight, Corrosion-Resistant Scaffolding
Fiberglass scaffolds are increasingly preferred over steel or aluminum due to their lightweight nature and superior resistance to corrosion, making them ideal for chemical plants, offshore facilities, and coastal construction sites where metal scaffolds deteriorate quickly.
Stringent Workplace Safety Regulations
Regulatory bodies in North America, Europe, and Asia-Pacific are mandating the use of non-conductive, non-metallic scaffolding in high-risk environments, driving adoption of fiberglass scaffolds to ensure compliance and enhance worker safety.
Technological Advancements in Fiberglass Manufacturing
Innovations in resin formulations, pultrusion technology, and modular scaffold designs are improving the durability, load-bearing capacity, and ease of assembly of fiberglass scaffolds, making them more attractive for a wider range of applications.
Expansion of Infrastructure and Industrial Projects in Emerging Markets
Rapid urbanization, industrial growth, and infrastructure investments in Asia-Pacific, Latin America, and the Middle East are fueling demand for durable, safe, and easy-to-install scaffolding solutions, with fiberglass scaffolds meeting these needs in challenging environments.
Growth in Renewable Energy and Offshore Sectors
The expansion of wind farms, solar installations, and offshore oil and gas projects requires scaffolding that is non-conductive and resistant to harsh weather and chemical exposure, positioning fiberglass scaffolds as the preferred solution for these specialized applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Fiberglass Scaffold Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Fiberglass Scaffold Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Global Fiberglass Scaffold Market?
Who are the leading companies in the Global Fiberglass Scaffold Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Residential Construction
- 1.2.2 Commercial Construction
- 1.2.3 Industrial Maintenance
- 1.2.4 Repair and Renovation
- 1.3 By Product Type
- 1.3.1 Tempered Fiberglass Scaffold
- 1.3.2 Non-Tempered Fiberglass Scaffold
- 1.3.3 Custom-Made Fiberglass Scaffold
- 1.3.4 Prefabricated Fiberglass Scaffold
- 1.4 By End-User Industry
- 1.4.1 Construction
- 1.4.2 Aerospace
- 1.4.3 Shipbuilding
- 1.4.4 Oil and Gas
- 1.4.5 Others
- 1.5 By Scaffold Configuration
- 1.5.1 Single Scaffold
- 1.5.2 Double Scaffold
- 1.5.3 Suspended Scaffold
- 1.5.4 Mobile Scaffold
- 1.5.5 Shoring Scaffold
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,943.8 million → 2032: USD 9,511.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fiberglass Scaffold Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fiberglass Scaffold Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fiberglass Scaffold Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fiberglass Scaffold Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fiberglass Scaffold Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fiberglass Scaffold Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fiberglass Scaffold Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fiberglass Scaffold Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,943.8 million → 2032: USD 9,511.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fiberglass Scaffold Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential Construction
- 12.3.7.2 Commercial Construction
- 12.3.7.3 Industrial Maintenance
- 12.3.7.4 Repair and Renovation
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Tempered Fiberglass Scaffold
- 12.4.7.2 Non-Tempered Fiberglass Scaffold
- 12.4.7.3 Custom-Made Fiberglass Scaffold
- 12.4.7.4 Prefabricated Fiberglass Scaffold
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Construction
- 12.5.7.2 Aerospace
- 12.5.7.3 Shipbuilding
- 12.5.7.4 Oil and Gas
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Scaffold Configuration - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Single Scaffold
- 12.6.7.2 Double Scaffold
- 12.6.7.3 Suspended Scaffold
- 12.6.7.4 Mobile Scaffold
- 12.6.7.5 Shoring Scaffold
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fiberglass Scaffold End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Fiberglass Scaffold Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Fiberglass Scaffold Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Fiberglass Scaffold Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Layher Holding GmbH & Co. KG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 PERI Group
- 18.4 Altrad Group
- 18.5 BrandSafway
- 18.6 ULMA Construction
- 18.7 Werner Co. (ProDriven Global Brands)
- 18.8 Tubesca-Comabi
- 18.9 Altrex B.V.
- 18.10 Instant Upright Ltd.
- 18.11 Sunbelt Rentals, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

