
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Advanced Materials for Semiconductors Market Size 2024 | USD 50,425 million |
| Advanced Materials for Semiconductors Market, CAGR | 12.3% |
| Advanced Materials for Semiconductors Market Size 2032 | USD 127,551 million |
Market Overview:
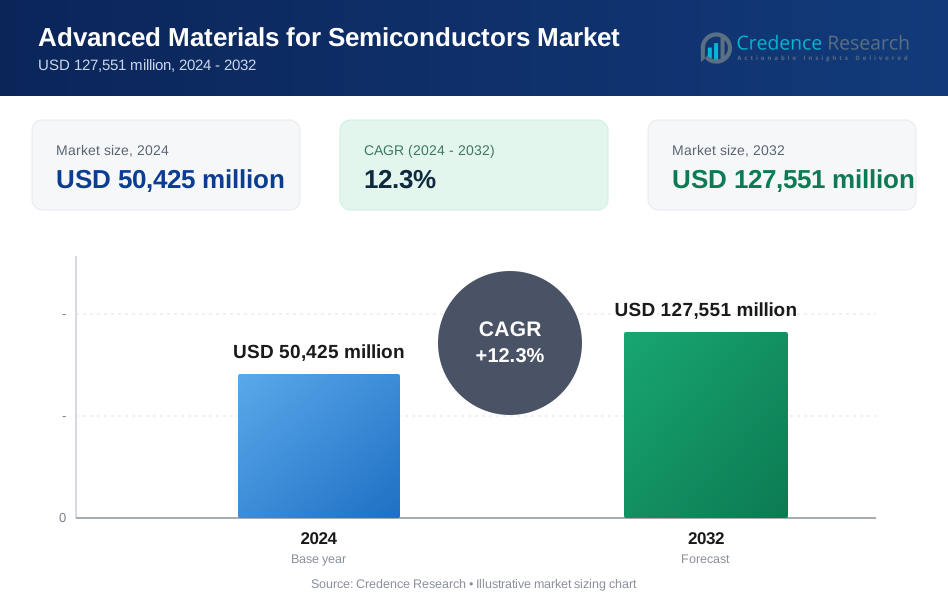
Advanced Materials for Semiconductors Market size was valued at USD 50,425 million in 2024 and is anticipated to reach USD 127,551 million by 2032, at a CAGR of 12.3% during the forecast period (2024-2032).
The market growth is primarily driven by the increasing miniaturization of semiconductor components, the rising demand for high-speed computing, and the expanding applications of AI and IoT. The shift towards advanced node technologies in semiconductor manufacturing is boosting the need for innovative materials such as high-k dielectrics, low-k interlayer dielectrics, gallium nitride (GaN), silicon carbide (SiC), and advanced photoresists. Additionally, the push for sustainability in the semiconductor industry is accelerating research and adoption of eco-friendly and energy-efficient materials. The growing demand for electric vehicles (EVs) is further driving the need for wide-bandgap materials like SiC and GaN, which offer superior thermal and electrical performance. Furthermore, advancements in extreme ultraviolet (EUV) lithography are reshaping the demand for next-generation photoresists and deposition materials.
Regionally, Asia-Pacific dominates the market, driven by major semiconductor manufacturing hubs in China, Taiwan, South Korea, and Japan. The region benefits from strong investments in semiconductor fabs, a robust electronics industry, and increasing R&D activities. The rapid expansion of China's semiconductor industry, supported by government policies, is significantly strengthening its global position. Additionally, Taiwan’s role as a leader in semiconductor foundries, with companies like TSMC, continues to influence global semiconductor material demand. North America is experiencing significant growth, supported by investments in semiconductor manufacturing and government initiatives like the CHIPS Act in the U.S. The region is also witnessing increased collaborations between material suppliers and chip manufacturers to develop next-generation semiconductor materials. Europe is also expanding, focusing on semiconductor self-sufficiency and innovation in advanced materials. The European Union's focus on reducing reliance on imports is driving investments in regional semiconductor manufacturing. Meanwhile, the Middle East and Africa, and Latin America are gradually entering the market with increasing investments in semiconductor manufacturing infrastructure and strategic collaborations with leading global chipmakers.
Market Insights:
- The market is projected to grow from USD 50,425 million in 2024 to USD 127,551 million by 2032, driven by increasing demand for advanced semiconductor materials.
- Miniaturization of semiconductor components and high-speed computing needs are accelerating the adoption of high-k dielectrics, low-k interlayer dielectrics, and advanced photoresists.
- The expansion of 5G and IoT technologies is fueling the demand for gallium nitride (GaN) and silicon carbide (SiC) in power electronics and RF applications.
- Government investments, including the U.S. CHIPS Act and Europe’s semiconductor strategy, are supporting domestic semiconductor manufacturing and material development.
- Electric vehicle growth is increasing the use of wide-bandgap materials like SiC and GaN for power efficiency and thermal performance improvements.
- High manufacturing costs, supply chain disruptions, and stringent environmental regulations present challenges for material manufacturers and suppliers.
- Asia-Pacific leads the market with 52% share, followed by North America at 28% and Europe at 15%, driven by regional investments in semiconductor fabrication and material innovation.
Market Drivers:
Increasing Demand for High-Performance Computing and Miniaturization:
The growing need for high-performance computing and miniaturization of semiconductor components is a major driver for the advanced materials for semiconductors market. As industries adopt artificial intelligence (AI), machine learning (ML), and big data analytics, there is a rising demand for advanced semiconductor chips that offer higher processing power and efficiency. For instance, Penn State's establishment of an advanced semiconductor lab, supported by the CHIPS Act, aims to enhance research and development capabilities in next-generation semiconductor technology, focusing on materials like gallium nitride and two-dimensional materials. Miniaturization of semiconductor components, driven by the transition to smaller node sizes such as 5nm and below, is increasing the need for high-k dielectrics, low-k interlayer dielectrics, and advanced photoresists. These materials enable better transistor performance, reduced power consumption, and enhanced chip reliability.
Expansion of 5G and IoT Technologies:
The rapid deployment of 5G networks and the increasing adoption of the Internet of Things (IoT) are fueling the demand for advanced semiconductor materials. 5G technology requires high-frequency, low-latency semiconductor components, which necessitate the use of materials like gallium nitride (GaN) and silicon carbide (SiC) for power amplifiers and radio frequency (RF) applications. For instance, the Indian government's Indigenous 5G Test Bed initiative provides a platform for testing and validating 5G products, promoting the development of indigenous technologies and encouraging the use of advanced semiconductor materials in IoT applications. IoT devices, including smart home systems, industrial automation solutions, and connected healthcare applications, require efficient semiconductor chips that rely on advanced materials to enhance durability and energy efficiency. The growing interconnectivity of electronic devices is further propelling the demand for innovative semiconductor materials.
Rising Investments in Semiconductor Manufacturing:
Government and private sector investments in semiconductor manufacturing are significantly driving the demand for advanced materials. Countries such as the U.S., China, Japan, and South Korea are making substantial investments to strengthen their domestic semiconductor production capabilities. For instance, the U.S. CHIPS Act has led to collaborations like the partnership between the U.S. and India to assess and enhance semiconductor infrastructure, aiming to boost the global supply chain. Initiatives like the U.S. CHIPS Act and the European Union’s semiconductor strategy are aimed at increasing self-sufficiency and reducing reliance on imports. These investments are fostering the development of cutting-edge fabrication processes that require high-performance materials, including next-generation deposition and etching materials, advanced packaging substrates, and low-power interconnects.
Growth in Electric Vehicles and Renewable Energy Applications:
The rising adoption of electric vehicles (EVs) and renewable energy solutions is further accelerating the need for advanced semiconductor materials. EV powertrains and charging infrastructure require power semiconductors that operate efficiently under high voltage and temperature conditions. For instance, the UK's investment in semiconductor research for electric vehicles focuses on improving power electronics, which are crucial for enhancing the efficiency and range of EVs. Materials such as GaN and SiC are becoming essential for power management and energy conversion in EVs, enabling higher efficiency and longer battery life. Additionally, renewable energy applications, including solar and wind energy systems, rely on advanced semiconductor components to optimize power conversion and grid stability. The push toward energy-efficient technologies is increasing the demand for semiconductor materials that enhance power management capabilities.
Market Trends:
Adoption of Wide-Bandgap Materials:
The increasing demand for high-performance and energy-efficient semiconductor devices is driving the adoption of wide-bandgap materials such as gallium nitride (GaN) and silicon carbide (SiC). These materials offer superior electrical properties, including higher thermal conductivity, lower energy loss, and improved power efficiency, making them essential for applications in power electronics, 5G infrastructure, and electric vehicles. For instance, Infineon Technologies' CoolSiC MOSFET G2 technology is a notable example, as it leverages silicon carbide to enable lower energy loss and enhance system efficiency. The shift toward GaN and SiC-based semiconductors is enhancing the performance of next-generation electronic devices, particularly in high-power and high-frequency applications.
Advancements in Extreme Ultraviolet Lithography:
The growing complexity of semiconductor fabrication is leading to increased adoption of extreme ultraviolet (EUV) lithography, which requires specialized materials such as advanced photoresists and high-purity deposition materials. EUV lithography enables the production of smaller and more powerful semiconductor chips by improving patterning precision and reducing defects. As semiconductor manufacturers continue to develop chips at 5nm and below, the demand for high-performance EUV-compatible materials is rising, supporting innovation in transistor scaling and chip miniaturization. For instance, Taiwan Semiconductor Manufacturing Company (TSMC) has successfully integrated EUV into its fabrication processes for advanced nodes like 5nm and 3nm, significantly enhancing chip performance and efficiency.
Rising Focus on Sustainable and Eco-Friendly Materials:
The semiconductor industry is increasingly focusing on sustainability, driving the demand for eco-friendly materials that reduce energy consumption and environmental impact. Manufacturers are exploring alternatives to traditional materials, such as biodegradable and low-carbon-footprint chemicals used in semiconductor fabrication. For instance, LG Display has made significant strides in eco-friendliness by reducing plastic usage in its OLED panels, achieving a plastic content rate of less than 5% and increasing recyclability to 92.7%. Additionally, the development of energy-efficient semiconductor materials is gaining traction, as companies aim to meet stricter regulatory requirements and improve the sustainability of their supply chains.
Expansion of Advanced Packaging Technologies:
The growing need for enhanced chip performance and integration is accelerating the adoption of advanced packaging technologies, such as 3D stacking, system-in-package (SiP), and fan-out wafer-level packaging (FOWLP). These techniques require specialized materials, including high-performance adhesives, advanced substrates, and innovative thermal interface materials. For instance, TSMC's CoWoS technology is a leading example of advanced packaging, offering high data transfer rates and low power consumption, making it suitable for high-performance computing applications. As semiconductor companies push for higher-density and power-efficient packaging solutions, the demand for next-generation materials that enhance reliability and reduce form factor is increasing.
Market Challenges Analysis:
High Manufacturing Costs and Supply Chain Constraints:
The development and production of advanced semiconductor materials involve complex and costly processes, posing a significant challenge for manufacturers. The fabrication of high-performance materials such as gallium nitride (GaN), silicon carbide (SiC), and high-k dielectrics requires specialized equipment, precise control, and extensive R&D investments. Additionally, the increasing demand for extreme ultraviolet (EUV) lithography-compatible materials adds to the cost burden, as these materials must meet stringent purity and performance requirements. The high capital expenditure required for material innovation and production scalability makes it difficult for smaller players to compete with established semiconductor material suppliers. Moreover, fluctuations in raw material availability, particularly for rare earth elements, lead to supply chain bottlenecks that impact production timelines and increase procurement costs. Supply chain disruptions, including raw material shortages and geopolitical trade restrictions, further impact production, leading to price fluctuations and delays in material availability. These challenges increase operational costs for semiconductor manufacturers and limit the scalability of next-generation semiconductor technologies.
Stringent Regulatory Standards and Environmental Concerns:
The semiconductor industry operates under strict regulatory frameworks related to environmental sustainability, material safety, and waste management. Advanced semiconductor materials often involve the use of hazardous chemicals and rare earth elements, leading to concerns about environmental impact and disposal regulations. As governments worldwide enforce stricter emissions and waste disposal laws, manufacturers must invest in sustainable production methods and eco-friendly materials, which can increase overall costs and complicate supply chain logistics. The growing emphasis on achieving carbon neutrality in semiconductor manufacturing is pressuring companies to adopt greener alternatives, which may require significant process modifications and increased operational expenses. Additionally, compliance with international standards and intellectual property restrictions can hinder market entry for new players, limiting innovation and competition. The increasing regulatory complexity across different regions creates additional challenges for companies looking to expand their global footprint while maintaining compliance with evolving environmental and trade policies.
Market Opportunities:
The increasing demand for advanced semiconductor technologies presents significant growth opportunities for material manufacturers. As industries such as artificial intelligence, high-performance computing, and quantum computing continue to evolve, the need for next-generation semiconductor materials is expanding. Wide-bandgap materials like gallium nitride (GaN) and silicon carbide (SiC) are gaining traction in power electronics, offering superior efficiency and performance in electric vehicles, renewable energy systems, and data centers. Additionally, the transition to smaller node sizes in semiconductor fabrication is driving the demand for high-k dielectrics, low-k interlayer dielectrics, and advanced photoresists, creating new avenues for innovation and investment in material science. The expansion of extreme ultraviolet (EUV) lithography in chip manufacturing also provides an opportunity for specialized material development, ensuring enhanced precision and reliability in semiconductor fabrication.
Growing government support and strategic investments in semiconductor manufacturing further contribute to market opportunities. Countries such as the U.S., China, and members of the European Union are investing heavily in domestic semiconductor production, encouraging the development of advanced materials to enhance supply chain resilience. Sustainability trends are also opening doors for eco-friendly semiconductor materials that reduce energy consumption and environmental impact. Companies that focus on developing green alternatives, such as biodegradable chemicals and energy-efficient substrates, are well-positioned to capitalize on this shift. Furthermore, the increasing demand for advanced packaging solutions, including 3D stacking and system-in-package (SiP) technologies, is creating new opportunities for materials that improve thermal management, conductivity, and chip integration.
Market Segmentation Analysis:
By Material Type
The market for advanced materials in semiconductors is segmented into high-k dielectrics, low-k interlayer dielectrics, gallium nitride (GaN), silicon carbide (SiC), photoresists, and advanced packaging materials. High-k and low-k dielectrics are essential for improving transistor performance and reducing power consumption in advanced semiconductor nodes. GaN and SiC are witnessing rapid adoption in power electronics due to their superior electrical and thermal properties, making them ideal for applications in electric vehicles, renewable energy, and 5G infrastructure.
By Application
Advanced semiconductor materials are widely used in logic devices, memory chips, power electronics, and optoelectronics. The increasing demand for high-performance computing and artificial intelligence is driving the need for logic and memory chips that rely on advanced materials for better efficiency and scalability. Power electronics applications, including electric vehicle powertrains and industrial automation, are benefiting from the adoption of GaN and SiC-based semiconductors. Optoelectronics, such as LEDs and laser diodes, continue to evolve with the use of advanced materials that enhance performance and energy efficiency.
By End-Use Industry
The key end-use industries for advanced semiconductor materials include consumer electronics, automotive, telecommunications, and industrial sectors. The growing demand for smartphones, laptops, and smart devices is fueling material innovations in consumer electronics. The automotive sector is witnessing increased use of advanced semiconductor materials in electric vehicles and autonomous driving technologies. Additionally, the expansion of 5G networks and cloud computing is driving the adoption of high-performance semiconductor materials in telecommunications infrastructure.
Segmentations:
By Material Type
- High-k dielectrics
- Low-k interlayer dielectrics
- Gallium nitride (GaN)
- Silicon carbide (SiC)
- Photoresists
- Advanced packaging materials
By Application
- Logic devices
- Memory chips
- Power electronics
- Optoelectronics
By End-Use Industry
- Consumer electronics
- Automotive
- Telecommunications
- Industrial sector
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific
Asia-Pacific holds the largest market share of 52%, driven by strong semiconductor manufacturing capabilities in China, Taiwan, South Korea, and Japan. The region benefits from extensive investments in semiconductor fabrication facilities, advanced packaging technologies, and material innovation. China continues to expand its semiconductor industry through government-backed initiatives, strengthening its supply chain for advanced materials. Taiwan, led by companies such as TSMC, plays a crucial role in semiconductor foundries, increasing demand for high-k and low-k dielectrics, photoresists, and deposition materials. South Korea's investment in memory chips and logic devices further fuels market growth, while Japan remains a key supplier of specialty semiconductor materials. The increasing adoption of AI and cloud computing in the region is further driving demand for high-performance semiconductor materials to support next-generation computing technologies.
North America
North America accounts for 28% of the market, supported by technological advancements, increasing semiconductor manufacturing investments, and government initiatives. The U.S., through the CHIPS Act, is focusing on strengthening domestic semiconductor production, driving the demand for high-performance materials such as gallium nitride (GaN), silicon carbide (SiC), and advanced packaging solutions. Major semiconductor manufacturers and material suppliers in the region are collaborating to enhance innovation in EUV lithography-compatible materials and sustainable alternatives. The rise in demand for AI-driven chips, high-performance computing, and data center infrastructure is further boosting the adoption of advanced semiconductor materials. The strong presence of leading semiconductor companies, including Intel, AMD, and NVIDIA, is accelerating research and development in cutting-edge materials for next-generation processors and AI accelerators.
Europe
Europe holds 15% of the market, with increasing efforts toward semiconductor self-sufficiency and the development of advanced materials. The European Union is investing in semiconductor manufacturing to reduce dependence on imports, supporting the demand for cutting-edge materials in chip production. Countries such as Germany, France, and the Netherlands are at the forefront of semiconductor research and innovation, with a strong focus on sustainable and energy-efficient materials. The presence of leading semiconductor equipment manufacturers, particularly in lithography and deposition technologies, is driving demand for advanced materials in the region. Europe’s emphasis on electric vehicles and renewable energy solutions is also fueling the adoption of silicon carbide (SiC) and gallium nitride (GaN) in power electronics applications. The increasing shift towards localized semiconductor production is encouraging investments in regional supply chains and material innovation.
Key Player Analysis:
- Foundries
- NXP Semiconductors
- Broadcom Inc
- Micron Technology
- Qualcomm
- Lam Research Corporation
- SK Hynix
- Texas Instruments
- Intel Corporation
- Applied Materials
- Taiwan Semiconductor Manufacturing Company
- Samsung Electronics
Competitive Analysis:
The advanced materials for semiconductors market is highly competitive, with key players focusing on innovation, strategic partnerships, and expansion to strengthen their market presence. Leading companies are investing in research and development to enhance material properties, improve manufacturing efficiency, and meet the evolving demands of semiconductor fabrication. For instance, Wolfspeed, Inc. has extended its silicon carbide wafer supply agreements to support high-performance semiconductor applications. The increasing adoption of extreme ultraviolet (EUV) lithography and advanced packaging solutions is driving competition among material suppliers to develop high-performance dielectric materials, photoresists, and deposition solutions. Market players are also expanding production capacities and forming collaborations with semiconductor manufacturers to ensure a stable supply chain and meet growing demand. Sustainability initiatives and the shift toward eco-friendly materials are becoming critical factors in competition, with companies investing in greener alternatives. As semiconductor technologies continue to evolve, innovation in material science will remain a key differentiator for gaining a competitive edge in the global market.
Recent Developments:
- In June 2023, Micron announced plans to build a new assembly and test facility in Gujarat, India, marking a significant expansion of its global manufacturing base to meet future demand for DRAM and NAND products.
- In January 2025, Micron Technology Construction of Micron's semiconductor assembly and testing facility in India is in full swing, with 60% of the work completed.
- In February 2023, Texas Instruments announced plans to build a new $11 billion 300-millimeter semiconductor wafer fabrication plant in Lehi, Utah, as part of its long-term manufacturing roadmap.
- In Dec 2024, Intel Foundry demonstrated advancements in transistor and packaging technologies at IEDM 2024, including breakthroughs in subtractive ruthenium and selective layer transfer for advanced packaging.
Market Concentration & Characteristics:
The advanced materials for semiconductors market is moderately concentrated, with a mix of established global players and specialized material suppliers driving innovation. Leading companies dominate the market through extensive R&D investments, strong supply chain networks, and strategic collaborations with semiconductor manufacturers. The market is characterized by continuous technological advancements, driven by the increasing demand for high-performance, miniaturized semiconductor components. The transition to advanced node sizes, the adoption of extreme ultraviolet (EUV) lithography, and the rise of 3D packaging solutions are influencing material development. The industry is also witnessing a shift toward eco-friendly and sustainable materials, driven by regulatory requirements and corporate sustainability initiatives. The presence of regional players catering to specific semiconductor applications further diversifies the competitive landscape. As semiconductor manufacturing processes become more complex, the demand for highly specialized materials will continue to shape market dynamics and innovation strategies.
Report Coverage:
The research report offers an in-depth analysis based on Material Type, Application, End-Use Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for advanced semiconductor materials will continue to rise as chip miniaturization and high-performance computing drive material innovation.
- Wide-bandgap materials such as gallium nitride (GaN) and silicon carbide (SiC) will see increased adoption in power electronics, electric vehicles, and 5G infrastructure.
- The expansion of artificial intelligence, machine learning, and quantum computing will accelerate the need for next-generation semiconductor materials.
- Extreme ultraviolet (EUV) lithography will require further advancements in photoresists, deposition materials, and etching solutions to support next-generation semiconductor fabrication.
- Sustainability initiatives will push manufacturers to develop eco-friendly semiconductor materials with lower environmental impact.
- Advanced packaging technologies, including 3D stacking and fan-out wafer-level packaging (FOWLP), will create demand for specialized bonding materials and thermal management solutions.
- Increasing government investments in semiconductor manufacturing will strengthen regional supply chains and drive the development of high-performance materials.
- The rise of smart devices, IoT, and edge computing will further fuel the need for energy-efficient and high-performance semiconductor materials.
- Collaboration between semiconductor manufacturers and material suppliers will play a crucial role in developing new solutions to meet the evolving industry needs.
- Continuous research and innovation in material science will remain essential for achieving higher efficiency, durability, and scalability in semiconductor applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current and projected market size of the advanced materials for semiconductors market?
What are the key factors driving market growth?
Which region dominates the market?
How is the electric vehicle sector influencing the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Advanced Materials for Semiconductors Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Advanced Materials for Semiconductors Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 50,425 million → 2032: USD 127,551 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Advanced Materials for Semiconductors Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Advanced Materials for Semiconductors Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Advanced Materials for Semiconductors Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Advanced Materials for Semiconductors Market Drivers
- 3.3 Advanced Materials for Semiconductors Market Restraints & Challenges
- 3.4 Advanced Materials for Semiconductors Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Advanced Materials for Semiconductors Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Advanced Materials for Semiconductors Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Advanced Materials for Semiconductors category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Advanced Materials for Semiconductors Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Advanced Materials for Semiconductors Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Advanced Materials for Semiconductors market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Advanced Materials for Semiconductors Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Advanced Materials for Semiconductors Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Advanced Materials for Semiconductors Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Advanced Materials for Semiconductors (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Advanced Materials for Semiconductors Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Advanced Materials for Semiconductors Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Advanced Materials for Semiconductors Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Advanced Materials for Semiconductors Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Advanced Materials for Semiconductors Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Advanced Materials for Semiconductors Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Advanced Materials for Semiconductors Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Advanced Materials for Semiconductors Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Advanced Materials for Semiconductors Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
