
Market Overview:
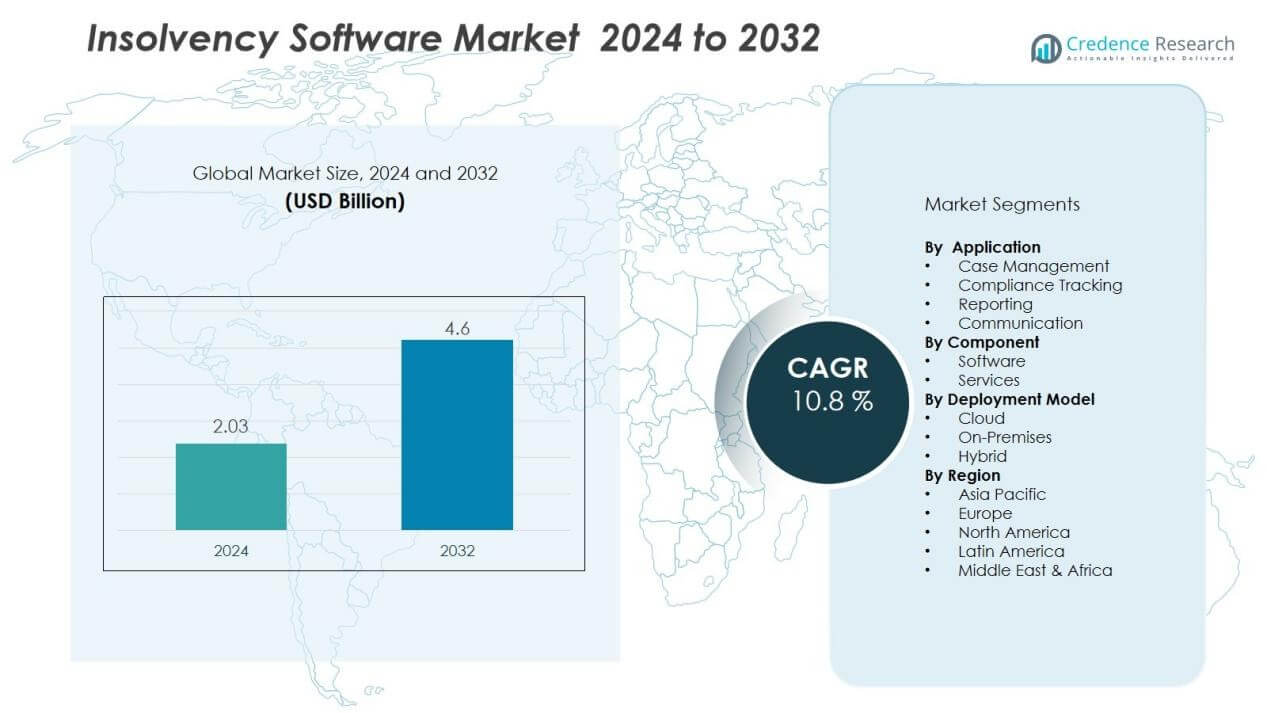
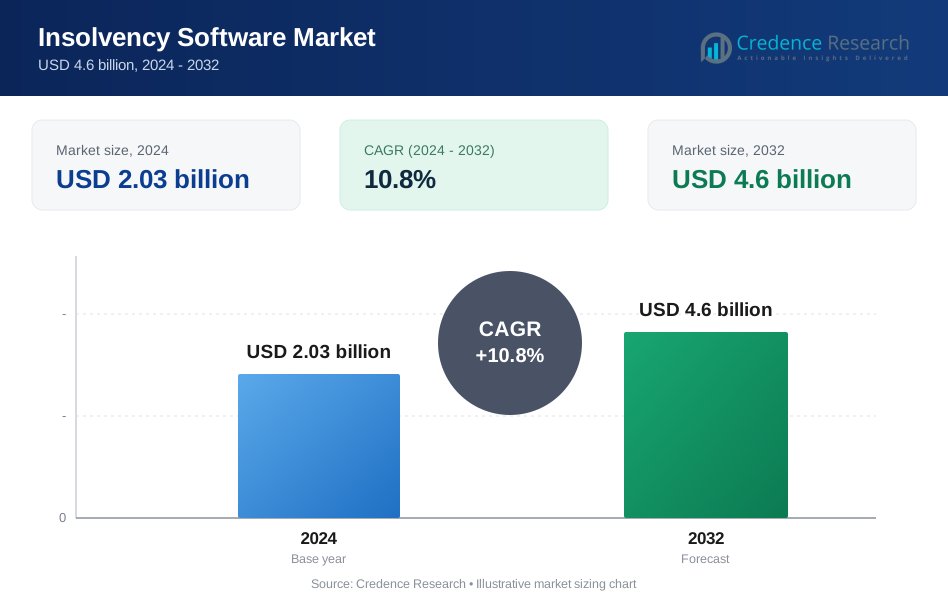
The insolvency software market size was valued at USD 2.03 billion in 2024 and is anticipated to reach USD 4.6 billion by 2032, at a CAGR of 10.8% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Insolvency Software Market Size 2024 | USD 2.03 Billion |
| Insolvency Software Market, CAGR | 10.8% |
| Insolvency Software Market Size 2032 | USD 4.6 Billion |
Key drivers include growing regulatory compliance needs, rising bankruptcy filings across industries, and demand for automation in insolvency proceedings. Cloud-based platforms and AI-enabled tools are enhancing case tracking, reporting, and creditor communication. The increasing pressure on businesses to manage financial restructuring quickly and cost-effectively further accelerates adoption. Vendors are also focusing on data security and integration with enterprise systems, which improves reliability and decision-making efficiency.
Regionally, North America holds the largest share due to early adoption of advanced financial technologies and strong regulatory frameworks. Europe follows with significant growth, supported by modernization of insolvency laws and digital initiatives. Asia-Pacific is projected to grow fastest, driven by increasing business insolvencies, expanding SME sector, and rising digitization of legal processes in China and India. Latin America and the Middle East & Africa are emerging markets, with adoption fueled by economic restructuring needs and modernization of financial governance.
Market Insights:
- The insolvency software market was valued at USD 2.03 billion in 2024 and is expected to reach USD 4.6 billion by 2032, growing at a CAGR of 10.8%.
- Rising demand for streamlined case management is fueling adoption, with businesses and regulators seeking efficient tools for faster workflows, accurate reporting, and improved transparency.
- Regulatory compliance pressures are increasing adoption, as software solutions help meet strict filing deadlines, maintain accurate records, and reduce risks of penalties.
- Cloud-based and AI-enabled platforms are transforming the insolvency software market by supporting predictive analytics, fraud detection, and real-time collaboration.
- Economic instability and fluctuating markets are driving higher insolvency cases across SMEs and large enterprises, boosting demand for digital restructuring tools.
- Challenges such as varying regulations, integration with legacy systems, and data security concerns continue to restrict seamless adoption, particularly among SMEs.
- North America leads with 38% share in 2024, followed by Europe with 29%, while Asia-Pacific at 23% is projected to grow fastest due to rising insolvencies and rapid digital transformation.
Market Drivers:
Rising Demand for Streamlined Insolvency Case Management
The insolvency software market benefits from the growing need to simplify complex insolvency proceedings. Businesses, practitioners, and regulators seek digital platforms that enhance transparency and efficiency. It allows faster document management, automated workflows, and accurate reporting, reducing administrative burdens. This shift supports professionals in handling higher caseloads with precision.
- For instance, McCambridge Duffy Group implemented FileInvite's document collection technology and achieved an 87.5% decrease in document collection time, with processes that previously took 40 days now completed in just 5 days
Increasing Focus on Regulatory Compliance and Governance
Regulatory frameworks around insolvency are becoming stricter across regions. The insolvency software market addresses this challenge by integrating compliance tools that align with evolving laws. It helps practitioners meet filing deadlines, maintain accurate records, and reduce risks of penalties. Compliance-driven adoption is creating strong momentum for specialized digital platforms.
- For instance, Epiq’s Bankruptcy Analytics platform integrates daily data from all 93 U.S. bankruptcy courts, enabling practitioners to automatically track and validate filings in real time.
Adoption of Cloud-Based and AI-Enabled Solutions
Cloud technology and artificial intelligence are reshaping insolvency practices. The insolvency software market is witnessing rising adoption of scalable cloud platforms that allow secure access and collaboration. It also leverages AI for predictive analytics, fraud detection, and automated decision support. These innovations improve accuracy and reduce operational costs for users.
Growing Insolvency Cases Across SMEs and Enterprises
Economic instability and market fluctuations have driven higher insolvency filings worldwide. The insolvency software market gains traction as organizations require tools to manage restructuring effectively. It supports small and medium enterprises in resolving financial distress with structured workflows. Rising insolvencies in large enterprises also expand demand for advanced, feature-rich platforms.
Market Trends:
Integration of Automation, Cloud, and Artificial Intelligence:
Automation, cloud platforms, and artificial intelligence are shaping the insolvency software market. It is driving adoption of tools that streamline document management, automate repetitive tasks, and improve reporting accuracy. Cloud-based solutions allow secure access, scalability, and real-time collaboration across multiple stakeholders. AI-driven features are enhancing fraud detection, predictive analytics, and workflow optimization, improving efficiency for practitioners and regulators. Vendors are also focusing on intuitive interfaces and integration with enterprise systems to ensure seamless operation. These technological advancements are reshaping insolvency management into a faster and more data-driven process.
- For instance, regulatory technology (RegTech) implementations, including those from firms like Deloitte, have enabled organizations to significantly reduce compliance costs compared to firms using manual processes. This is supported by market reports and industry analyses that consistently highlight RegTech's potential for driving efficiency gains and cost savings
Rising Demand for Security, Collaboration, and Global Expansion:
Data security and compliance have become critical in the insolvency software market. It is leading vendors to embed advanced encryption, multi-factor authentication, and compliance-focused modules. Growing demand for collaboration between creditors, administrators, and legal bodies is fueling adoption of centralized platforms. The expansion of cross-border insolvencies is also creating demand for globally compatible solutions that adapt to diverse legal frameworks. Vendors are targeting emerging markets in Asia-Pacific, Latin America, and the Middle East with localized platforms and regulatory support. The combination of security, collaboration, and international applicability is defining the market’s growth trajectory.
- Fact Check This and Give me Final Verdict "For Instance, Relativity's SaaS product, RelativityOne, serves more than 300,000 users in approximately 40 countries, including the U.S. Department of Justice and 198 of the Am Law 200.
Market Challenges Analysis:
Complex Regulatory Variations and Integration Barriers:
The insolvency software market faces challenges due to varying regulatory frameworks across regions. It must adapt constantly to evolving compliance requirements, which increases development complexity and costs for vendors. Integration with legacy enterprise systems and diverse legal databases often slows deployment. Many firms also face difficulties in ensuring interoperability between platforms used by regulators, creditors, and practitioners. These barriers limit seamless adoption, particularly in markets with fragmented regulations.
Data Security Concerns and Limited Awareness Among SMEs:
Data security remains a major concern in the insolvency software market. It involves handling sensitive financial records, making platforms vulnerable to cyber threats and breaches. Small and medium enterprises often lack awareness about the benefits of digital insolvency tools, delaying adoption. Limited budgets further restrict investment in advanced platforms among smaller firms. Vendors face the challenge of balancing affordability with robust security and advanced features. Addressing these concerns is essential to expand market reach across all enterprise sizes.
Market Opportunities:
Expansion of Cloud-Based and AI-Driven Platforms:
The insolvency software market offers strong opportunities through cloud-based and AI-enabled solutions. It enables real-time collaboration, predictive analytics, and automated workflows, making insolvency processes faster and more accurate. Cloud platforms also reduce infrastructure costs, which appeals to both large enterprises and SMEs. AI integration supports fraud detection and scenario planning, enhancing decision-making for practitioners and regulators. Growing demand for scalable and secure systems will push vendors to expand service portfolios. This shift is expected to drive long-term adoption across industries and regions.
Rising Adoption in Emerging Economies and SME Sector:
Emerging economies present significant growth opportunities for the insolvency software market. It is gaining traction as governments modernize insolvency frameworks and promote digital transformation. SMEs, which often face financial instability, are adopting cost-effective solutions to manage restructuring efficiently. Vendors can capture this segment by offering localized, affordable, and regulatory-compliant platforms. Cross-border insolvencies also open new markets, creating demand for globally adaptable solutions. Expanding into these regions and sectors provides a strong pathway for market growth.
Market Segmentation Analysis:
By Component:
The insolvency software market is segmented into software and services. Software holds the largest share due to strong adoption of automation, case management, and reporting tools. Services, including consulting, integration, and support, are expanding steadily as organizations require technical expertise. It helps businesses achieve compliance, optimize operations, and manage large insolvency caseloads effectively. Vendors are focusing on offering bundled solutions that combine software platforms with ongoing support.
- For Instances, Aryza Insolv's case management platform has supported more than 20 years of insolvency workflow innovation, automating tasks and offering seamless banking integration for numerous professional restructuring firms globally as of 2024.
By Deployment Model:
Cloud deployment leads the insolvency software market due to its scalability, cost efficiency, and accessibility. It enables practitioners, regulators, and creditors to collaborate in real time, improving case outcomes. On-premises deployment continues to serve organizations with strict data privacy requirements. It is particularly relevant for large firms that manage sensitive financial records and require in-house control. Hybrid models are emerging to balance flexibility and security, offering tailored deployment options for enterprises.
- For instance, The Insolvency Service in the UK adopted a cloud platform based on Microsoft Dynamics 365, resulting in processing straightforward claims up to four times faster and handling 80,000 claims annually.
By Application:
The insolvency software market covers applications such as case management, compliance tracking, reporting, and communication. Case management dominates due to the rising complexity of insolvency proceedings and demand for streamlined workflows. Compliance tracking is gaining traction with stricter regulatory oversight worldwide. It also supports reporting and creditor communication to ensure transparency and trust. Growing demand across diverse applications highlights the software’s role in driving efficiency and accountability.
Segmentations:
By Component:
- Software
- Services
By Deployment Model:
- Cloud
- On-Premises
- Hybrid
By Application:
- Case Management
- Compliance Tracking
- Reporting
- Communication
By Region:
North America
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America:
North America holds the largest share of the insolvency software market with 38% in 2024. It benefits from advanced digital infrastructure, strict regulatory compliance standards, and early adoption of technology. The United States drives demand through frequent restructuring cases and high legal complexity. Canada follows with steady adoption supported by modernization of insolvency frameworks. It is also boosted by strong vendor presence and continuous innovation in cloud-based platforms. Growing focus on automation and predictive analytics further strengthens the region’s dominance.
Europe:
Europe accounts for 29% of the insolvency software market in 2024. The region benefits from modernization of insolvency laws, cross-border restructuring, and government-backed digital initiatives. The United Kingdom, Germany, and France lead adoption, supported by developed financial and legal systems. Smaller economies in Eastern Europe are catching up as digitization accelerates in insolvency management. It is also supported by increasing collaboration between regulators and practitioners on transparent processes. Strong demand for secure and compliant solutions continues to fuel steady growth across the region.
Asia-Pacific:
Asia-Pacific represents 23% of the insolvency software market in 2024. The region is projected to grow fastest due to rising insolvency cases among SMEs and large enterprises. China and India drive adoption with rapid digital transformation and evolving insolvency frameworks. Japan, South Korea, and Southeast Asia add momentum through strong investment in financial technologies. It benefits from government reforms promoting structured insolvency management. Growing cross-border trade and regional collaborations also increase demand for globally adaptable solutions. Expanding digitization makes Asia-Pacific a key growth engine for the coming years.
Key Player Analysis:
- Altisource
- Caseware International Inc.
- Aryza Ltd.
- Cilo
- Fastcase
- Kroll
- PracticePanter
- Litera
- Epiq Global
- Stretto
Competitive Analysis:
The insolvency software market is highly competitive, with global and regional players focusing on innovation, compliance, and integration. Key companies include Altisource, Caseware International Inc., Aryza Ltd., Cilo, Fastcase, Kroll, PracticePanther, Litera, Epiq Global, and Stretto. It is driven by continuous investment in cloud-based solutions, AI-enabled tools, and enhanced data security features. Vendors are differentiating their offerings by providing comprehensive case management, compliance tracking, and creditor communication tools. Strategic partnerships with legal firms and financial institutions are helping players expand reach and strengthen market presence. It also witnesses rising competition from niche providers that offer localized and cost-effective platforms, targeting SMEs and emerging economies. The competitive landscape is shaped by a balance between large multinational vendors delivering advanced, feature-rich platforms and smaller firms offering agile, customized solutions. This mix of global scale and regional specialization defines the growth trajectory of the market.
Recent Developments:
- In May 2025, Altisource effected a 1-for-8 reverse stock split to maintain compliance with Nasdaq requirements, consolidating its shares and impacting its shareholder structure.
- In January 2025, Caseware International Inc. completed the acquisition of LeaseJava, a SaaS company specializing in automated lease accounting, strengthening its audit and assurance portfolio.
- In September 2025, Aryza Ltd. announced the acquisition of Bravure, expanding its global reach in technology-enabled debt sale and recovery solutions, especially within Australia.
Report Coverage:
The research report offers an in-depth analysis based on Component, Deployment Model, Application and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The insolvency software market will experience rising demand for AI-enabled platforms that enhance predictive analytics and decision-making.
- Vendors will focus on developing secure cloud-based solutions that support real-time collaboration across stakeholders.
- Global expansion will accelerate as insolvency frameworks modernize in emerging economies and new regulatory standards evolve.
- Integration with enterprise systems such as ERP and financial management software will improve efficiency and adoption rates.
- The growing number of SME insolvencies will create demand for cost-effective and scalable platforms tailored to smaller firms.
- Cross-border insolvencies will increase the need for globally adaptable solutions that align with diverse legal frameworks.
- Vendors will strengthen cybersecurity features, including advanced encryption and compliance modules, to address data security risks.
- User-friendly platforms with intuitive interfaces will gain preference, reducing training needs for practitioners and regulators.
- Partnerships between software providers, legal firms, and government agencies will expand to enhance platform credibility.
- Sustainability and digital transformation initiatives will encourage adoption of paperless, automated insolvency management solutions worldwide.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the insolvency software market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the insolvency software market projected to grow between 2024 and 2032?
Which insolvency software market segment held the largest share in 2024?
What are the primary factors fueling the growth of the insolvency software market?
Who are the leading companies in the insolvency software market?
Which region commanded the largest share of the insolvency software market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Insolvency Software Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Insolvency Software Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2.03 billion → 2032: USD 4.6 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Insolvency Software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Insolvency Software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Insolvency Software Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Insolvency Software Market Drivers
- 3.3 Insolvency Software Market Restraints & Challenges
- 3.4 Insolvency Software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Insolvency Software Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Insolvency Software Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Insolvency Software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Insolvency Software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Insolvency Software Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Insolvency Software market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Insolvency Software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Insolvency Software Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Insolvency Software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Insolvency Software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Insolvency Software Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Insolvency Software Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Insolvency Software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Insolvency Software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Insolvency Software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Insolvency Software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Insolvency Software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Insolvency Software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Insolvency Software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
