
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Air Pollution Control Systems Market Size 2024 | USD 84,315 Million |
| Air Pollution Control Systems Market, CAGR | 8.3% |
| Air Pollution Control Systems Market Size 2032 | USD 159,563.11 Million |
Market Overview
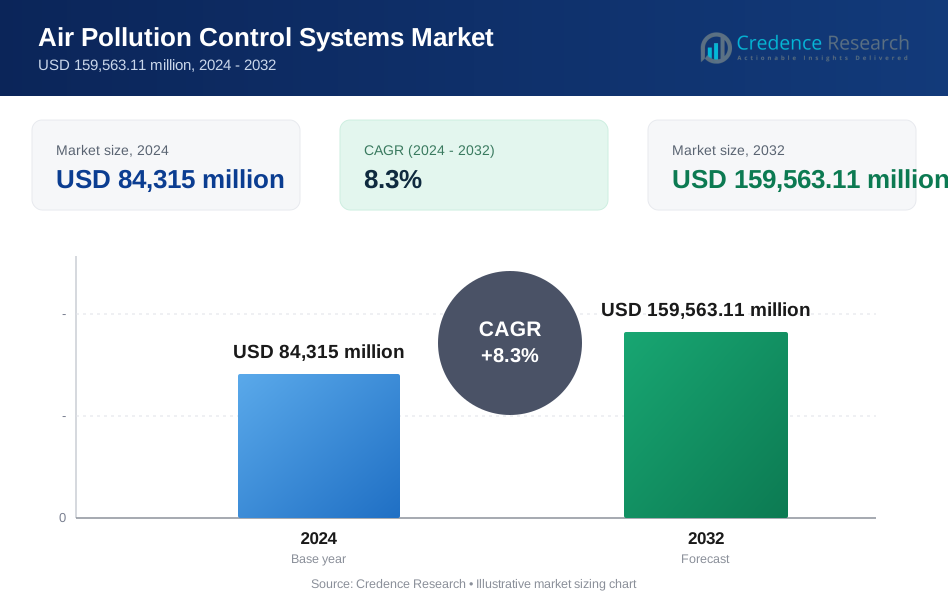
The Air Pollution Control Systems Market is projected to grow from USD 84,315 million in 2024 to an estimated USD 159,563.11 million by 2032, with a compound annual growth rate (CAGR) of 8.3% from 2024 to 2032.
Key drivers of the air pollution control systems market include increasing urbanization, industrial growth, and stricter environmental regulations aimed at reducing air pollution levels. Governments worldwide are implementing more stringent air quality standards, pushing industries to adopt air pollution control technologies to comply with these regulations. Additionally, rising public awareness of the health effects of air pollution, combined with greater emphasis on sustainability, is driving demand for advanced pollution control solutions. Industries such as manufacturing, power generation, and transportation are particularly focused on reducing emissions, leading to a surge in demand for air pollution control systems. Technological advancements in pollution control technologies, such as electrostatic precipitators, scrubbers, and filtration systems, are further supporting market growth.
Regionally, North America and Europe are major contributors to the air pollution control systems market, driven by regulatory pressure and government policies aimed at improving air quality. The United States, Canada, and European Union member states are all implementing comprehensive measures to reduce industrial emissions, which is driving market demand. In the Asia Pacific region, countries such as China and India are expected to witness significant growth due to rapid industrialization, increasing vehicle emissions, and government efforts to curb pollution levels. These countries are investing heavily in air pollution control technologies to meet both domestic and international environmental standards. Latin America and the Middle East & Africa are also experiencing growth in air pollution control systems adoption, particularly in industrial sectors, as these regions focus on improving air quality and adhering to global environmental agreements.
Market Insights
- The Air Pollution Control Systems Market is expected to grow significantly, with a projected increase from USD 84,315 million in 2024 to USD 159,563.11 million by 2032, driven by a CAGR of 8.3%.
- Rising urbanization, industrial expansion, and stricter government regulations on air quality are key factors driving the demand for pollution control technologies.
- Health concerns linked to poor air quality and greater public awareness are pushing industries to adopt advanced air pollution control systems to mitigate environmental and health risks.
- The market faces challenges, such as high implementation and maintenance costs of pollution control technologies, which may limit adoption in smaller industries or developing regions.
- Technological advancements in filtration, electrostatic precipitators, and scrubbers are enhancing the efficiency and effectiveness of air pollution control systems, promoting market growth.
- North America and Europe are leading the market, driven by stringent environmental regulations and governmental incentives for pollution control technologies.
- Rapid industrial growth in Asia Pacific, particularly in China and India, is fueling market expansion, while Latin America and the Middle East & Africa are also increasing their adoption of air pollution control systems to improve air quality.
Market Drivers
Government Regulations and Environmental Policies
Government regulations and environmental policies play a critical role in driving the demand for air pollution control systems. As air quality continues to be a major concern globally, numerous governments have introduced and reinforced policies aimed at curbing air pollution. For instance, the European Union’s Industrial Emissions Directive mandates that large industrial installations adopt technologies to reduce air emissions, pushing industries to adopt advanced pollution control systems. For instance, The World Bank’s 2020 report on "Air Pollution and Economic Growth" found that air pollution in developing countries reduces GDP by as much as 2% per year, prompting governments to implement stricter regulations to curb emissions. In 2020, the European Commission stated that the Industrial Emissions Directive aims to limit emissions of harmful substances from over 50,000 industrial facilities across Europe, with compliance required for emissions reductions in sectors like energy, manufacturing, and transportation. Similarly, the U.S. Environmental
Technological Advancements in Pollution Control
Technological innovation is one of the key drivers of the air pollution control systems market. As industries seek more efficient and cost-effective ways to manage emissions, there has been significant advancement in pollution control technologies. For instance, The U.S. Department of Energy (DOE) has been funding research and development projects to improve technologies such as electrostatic precipitators, baghouse filters, and scrubbers, which have become crucial in industries like cement production, power plants, and chemical manufacturing. In 2021, the U.S. DOE's Office of Energy Efficiency and Renewable Energy announced a funding opportunity of over $10 million to support the development of innovative carbon capture, utilization, and storage (CCUS) technologies. These projects aim to improve the efficiency of air pollution control systems, particularly in reducing carbon emissions from heavy industries.
Health and Economic Impacts of Air Pollution
The economic and health impacts of air pollution are significant drivers for the increased implementation of air pollution control systems. For instance, the World Health Organization (WHO), air pollution is responsible for approximately 7 million premature deaths each year. The WHO’s Global Air Quality Guidelines published in 2021 provide updated recommendations for acceptable levels of pollutants such as particulate matter (PM2.5) and nitrogen dioxide, influencing stricter regulations and policies for air quality management. Furthermore, air pollution imposes a substantial economic burden, with the WHO estimating that the economic losses from air pollution-related diseases account for over 5% of global GDP annually. In 2019, the World Bank released a report titled "The Cost of Air Pollution," which concluded that air pollution costs low- and middle-income countries more than $5 trillion every year in health costs and lost labor productivity. ion control systems to mitigate health risks and reduce economic losses.
Increased Public Awareness and Environmental Consciousness
Public awareness of air pollution’s harmful effects on health and the environment has dramatically increased over the past decade, further driving the demand for air pollution control systems. This shift is evident from both governmental actions and consumer behavior, as people and communities advocate for better air quality. For instance, the United Nations Environment Programme (UNEP) released a report titled "Air Pollution and Health," which highlighted the urgent need to address air pollution and its long-term health effects, particularly in urban areas. The UNEP emphasized that air pollution is the leading environmental risk factor for premature death and that addressing it through stricter regulations and pollution control technologies could significantly improve public health. Following this, many governments have been introducing public health campaigns aimed at reducing air pollution, which directly impacts the demand for air pollution control solutions.
Market Trends
Shift Towards Sustainable and Green Technologies
The growing focus on sustainability is a key trend shaping the air pollution control systems market. Governments and industries are increasingly committing to green technologies and cleaner processes to reduce their environmental footprint. For instance, in 2021, the International Renewable Energy Agency (IRENA) reported that the renewable energy sector is expected to expand significantly by 2030, driving demand for energy-efficient pollution control systems, particularly in energy-intensive industries such as cement and steel manufacturing. The European Union has adopted the Green Deal, aiming for carbon neutrality by 2050, which significantly impacts the industrial sector.
Integration of Artificial Intelligence and Automation
Another prominent trend in the air pollution control systems market is the integration of artificial intelligence (AI) and automation. AI-driven systems are revolutionizing pollution control by enabling real-time monitoring and optimization of emissions. For instance, the U.S. Department of Energy (DOE) has been working with industrial partners to incorporate AI technologies into pollution control mechanisms. The DOE’s 2021 initiative for advancing AI in industrial applications aims to enhance the accuracy of emissions monitoring and improve system efficiency. By leveraging AI, companies can predict pollution levels and adjust control systems accordingly, ensuring compliance with environmental regulations while minimizing costs.
Government Incentives and Financial Support
Governments are increasingly providing financial support to industries investing in air pollution control technologies, further boosting market growth. For example, in the U.S., the Environmental Protection Agency (EPA) has offered grants and subsidies to support the installation of air pollution control systems in critical sectors. In 2020, the EPA allocated over $50 million for the installation of pollution control technologies in small businesses and underserved communities through its "Clean Air Act" program. For instance, the Chinese government has committed to investing heavily in pollution control technologies as part of its 14th Five-Year Plan (2021-2025). The plan includes a substantial focus on environmental sustainability, with the government pledging to invest in cleaner technologies for major industrial sectors, including energy, manufacturing, and transport.
Emergence of Smart Cities and Urban Pollution Control
The rise of smart cities is driving increased demand for sophisticated pollution control systems. Urban areas, which are typically major contributors to air pollution due to industrial activities and transportation, are adopting advanced pollution control technologies to meet growing environmental standards. Governments are investing in smart city initiatives to address pollution, integrate renewable energy, and promote sustainability. For instance, the United Nations’ 2020 "World Urbanization Prospects" report emphasized the role of smart cities in improving urban air quality. According to the report, smart cities are using technologies like Internet of Things (IoT) sensors to monitor air pollution levels and manage pollution more effectively
Market Challenges Analysis
Regulatory Complexity and Compliance Costs
One of the key challenges facing the air pollution control systems market is the complexity of regulatory compliance. As environmental standards become more stringent globally, industries must navigate a complex web of regulations at the local, national, and international levels. This ever-evolving regulatory landscape requires continuous monitoring of compliance requirements, which can be both time-consuming and costly. For instance, companies operating across multiple regions must often adhere to different standards for emissions control, waste management, and air quality monitoring. Adapting to these regulations demands substantial investment in compliance measures and pollution control technologies. Moreover, frequent changes in regulatory frameworks can create uncertainty for industries, making long-term planning and budgeting difficult. Companies often face pressure to implement costly upgrades to their existing air pollution control systems or adopt new technologies to meet emerging regulations. pollution control systems, presents a significant barrier to growth in the market.
High Capital and Operational Costs
Another significant challenge in the air pollution control systems market is the high capital investment required for both the installation and maintenance of advanced pollution control technologies. Industries like power generation, manufacturing, and chemical production face substantial upfront costs when purchasing and installing equipment such as scrubbers, filters, and electrostatic precipitators. These systems are often technologically complex and require specialized knowledge for proper integration and operation. For instance, technologies such as carbon capture and storage (CCS) require extensive infrastructure and high installation costs, which can make them financially unviable for smaller or less capitalized companies. In addition to the initial investment, the operational and maintenance costs of air pollution control systems can also be a significant burden. Regular maintenance, monitoring, and repair of pollution control technologies require specialized personnel and can result in ongoing costs that impact profitability. Over time, as pollution control systems age, they may become less efficient, necessitating costly upgrades or replacements.
Market Opportunities
The air pollution control systems market is primarily segmented based on end-use industries, with industrial applications representing the largest share. Key sectors such as power generation, manufacturing, cement, chemicals, and steel production are significant contributors to the demand for air pollution control technologies. Industries in these sectors are heavily regulated due to their high emission levels, which makes compliance with stringent environmental standards a priority. Air pollution control systems such as electrostatic precipitators, baghouse filters, scrubbers, and catalytic converters are widely used to capture particulate matter, gases, and volatile organic compounds. The increasing focus on sustainability, along with the need for compliance with environmental regulations, is expected to further drive adoption in these sectors. Additionally, the shift towards cleaner and greener technologies, including renewable energy, is pushing industries to implement advanced pollution control solutions to reduce their carbon footprint and improve operational efficiency.
Geographically, the market is segmented into North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America and Europe are mature markets driven by stringent regulations and government policies aimed at reducing carbon emissions and improving air quality. The U.S. Environmental Protection Agency (EPA) and the European Union’s Green Deal are significant drivers of air pollution control systems adoption in these regions. In contrast, Asia-Pacific, particularly countries like China and India, is witnessing rapid growth due to industrialization and urbanization. Governments in these regions are implementing stricter emission standards and investing in pollution control technologies to combat severe air quality issues. The increasing focus on environmental sustainability and compliance with international climate agreements are expected to drive market growth in Asia-Pacific, making it a crucial region for future market expansion.
Market Segmentation Analysis
By Type
The air pollution control systems market is segmented by type into filtering systems, scrubbers, electrostatic precipitators, and catalytic converters. Filtering systems, including bag filters and HEPA filters, are widely used across various industries to capture particulate matter, ensuring compliance with environmental standards. Scrubbers, which remove gases and particulates from exhaust streams, are particularly dominant in industries such as power generation and chemical manufacturing. Electrostatic precipitators are another significant segment, primarily used for capturing fine particulate matter in industries like cement and steel production. Catalytic converters, mainly used in the automotive and industrial sectors, help reduce harmful emissions by converting pollutants into less harmful substances. The demand for these technologies is largely driven by stricter environmental regulations and a global push for cleaner air. Each type of air pollution control system has unique benefits and is chosen based on the specific needs of the industry, such as the type of pollutants produced and the scale of operation.
By Technology
The market is also segmented by technology, which includes fabric filters, wet scrubbers, electrostatic precipitators, catalytic converters, and carbon capture technologies. Fabric filters, commonly used in industries like cement and mining, are effective at capturing dust and particulate matter. Wet scrubbers, which use liquid to remove pollutants, are highly effective in controlling gaseous emissions and are often used in chemical and petrochemical industries. Electrostatic precipitators, which use electrical charges to remove particles, are favored in power generation and other energy-intensive industries. Catalytic converters are essential in reducing vehicle emissions and are integral to the automotive industry. Additionally, the growing adoption of carbon capture and storage (CCS) technologies is reshaping the market, particularly in industries with high carbon emissions, such as coal-fired power plants and heavy manufacturing. This segment is gaining momentum due to the global focus on reducing greenhouse gas emissions and combating climate change.
By End-User
The air pollution control systems market is segmented by end-user industries, including power generation, cement, chemical, steel, automotive, textiles, and mining. The power generation industry, especially those reliant on coal and other fossil fuels, is one of the largest consumers of air pollution control technologies due to the high levels of emissions from power plants. Cement and steel manufacturing also require robust pollution control systems due to the large amount of particulate matter and gases they generate. The chemical industry, with its complex processes, often uses scrubbers and electrostatic precipitators to meet air quality standards. The automotive sector is another key end-user, with catalytic converters being essential to reducing vehicle emissions. The growing focus on sustainability is pushing all these industries to invest in advanced technologies to reduce their environmental footprint. Additionally, emerging industries such as textiles and mining are increasingly adopting pollution control systems to mitigate the environmental impact of their operations, driven by rising regulatory pressures and environmental awareness.
Segmentations
Based on Product Type:
- Filtering Systems
- Scrubbers
- Electrostatic Precipitators
- Catalytic Converters
- Carbon Capture Technologies
Based on Technology:
- Fabric Filters
- Wet Scrubbers
- Electrostatic Precipitators
- Catalytic Converters
- Carbon Capture and Storage (CCS)
Based on End-User Industry:
- Power Generation
- Cement Manufacturing
- Chemical Processing
- Steel Production
- Automotive
- Textile
- Mining
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds a significant share of the air pollution control systems market, driven by stringent regulatory frameworks and a strong commitment to environmental sustainability. The United States, in particular, is a key player in the region, with the U.S. Environmental Protection Agency (EPA) enacting laws such as the Clean Air Act, which mandates industries to adopt advanced pollution control technologies. The country’s commitment to reducing emissions and transitioning to greener energy sources further boosts the demand for air pollution control systems. In addition to regulations, substantial investments in infrastructure and technological innovation also play a crucial role in North America's market growth. The region's focus on clean energy technologies, carbon capture and storage (CCS), and renewable energy solutions drives industries like power generation, chemical manufacturing, and automotive to implement state-of-the-art pollution control systems.
Europe
Europe is another dominant region in the air pollution control systems market, with aggressive environmental policies playing a pivotal role in shaping market dynamics. The European Union’s Green Deal and its target for carbon neutrality by 2050 push industries to implement technologies that minimize emissions and improve energy efficiency. Additionally, regulations such as the Industrial Emissions Directive and the European Climate Law further enhance the demand for air pollution control systems in sectors like power generation, cement manufacturing, and steel production. Countries such as Germany, the United Kingdom, and France are at the forefront of adopting clean technologies, including advanced air pollution control systems, to comply with EU-wide regulations.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the global air pollution control systems market. The region’s rapid industrialization, urbanization, and population growth are major contributors to its increasing demand for advanced pollution control technologies. China and India, in particular, are experiencing significant growth in their industrial sectors, with air quality issues becoming a critical concern. The Chinese government, in particular, has implemented stringent regulations such as the "Air Pollution Prevention and Control Action Plan" to reduce emissions from heavy industries, leading to substantial investments in pollution control systems. China, being the world’s largest emitter of greenhouse gases, has made significant strides in adopting advanced pollution control technologies. According to the Ministry of Ecology and Environment, over 300,000 enterprises have implemented air pollution control measures, with a continued push to upgrade these systems as emissions standards become stricter. India, similarly, is focusing on improving air quality and has introduced regulations to curb industrial emissions in sectors like power, manufacturing, and transportation.
Key Player Analysis
- Siemens AG
- Johnson Matthey
- Ducon Technologies Inc.
- Thermax Limited
- FLSmidth & Co. A/S
- Mitsubishi Hitachi Power Systems
- Babcock & Wilcox Enterprises, Inc.
- Donaldson Company, Inc.
- Emerson Electric Co.
- Sulzer Ltd.
Competitive Analysis
The competitive landscape of the air pollution control systems market is highly dynamic, with key players continually innovating to meet the evolving regulatory and environmental standards. Major companies like Siemens AG, Mitsubishi Hitachi Power Systems, and Babcock & Wilcox Enterprises are at the forefront, leveraging their extensive technological expertise and strong R&D capabilities to offer advanced pollution control solutions. These companies focus on product innovation, including the integration of AI and automation, to enhance the efficiency of air filtration, scrubbing, and carbon capture systems. Additionally, partnerships and strategic alliances are becoming a prominent growth strategy, with companies collaborating with governments and industry leaders to develop custom solutions that align with local regulations. For instance, many players are expanding their presence in emerging markets like Asia-Pacific, where rapid industrialization and stricter environmental regulations drive demand for more sophisticated air pollution control systems. Companies also increasingly focus on sustainability, aligning their products with global green initiatives and the push for carbon neutrality, which presents new opportunities for growth.
Recent Developments
- In May 2024, Mitsubishi Heavy Industries (MHI) joined forces with Chiyoda Corporation to enhance CO2 capture technology in Japan. Under this partnership, MHI will license their co-developed capture process to Chiyoda, enabling them to provide engineering services for carbon capture projects. This collaboration combines the strengths of both companies to help achieve decarbonization objectives.
- In January 2023, Donaldson Company, Inc. introduced Managed Filtration Services, integrating their iCue monitoring technology, industry knowledge, and service network. This offering provides condition-based maintenance and repair for industrial filtration equipment, aiming to optimize performance and minimize downtime.
Market Concentration & Characteristics
The air pollution control systems market exhibits moderate to high concentration, with a few dominant players controlling a significant share, while a multitude of smaller, regional companies caters to specific niches. Major players such as Siemens AG, Mitsubishi Hitachi Power Systems, and Ducon Technologies lead the market, benefiting from their extensive product portfolios, global reach, and significant investments in research and development. These large firms possess strong financial capabilities and technical expertise, enabling them to offer comprehensive, technologically advanced solutions like electrostatic precipitators, wet and dry scrubbers, and carbon capture systems. They also leverage strategic partnerships with governments and multinational corporations to secure large-scale contracts, particularly in industries like power generation, cement, and steel. At the same time, the market is characterized by the presence of smaller players that focus on providing specialized pollution control solutions tailored to specific industrial requirements or regions. These companies often compete by offering cost-effective alternatives or targeting emerging markets where demand is growing but competition is less intense. The market’s characteristics also include a high degree of regulatory influence, with players needing to adhere to stringent environmental standards and local government mandates. Additionally, technological innovation is a critical competitive differentiator, as industries seek solutions that not only comply with regulations but also enhance operational efficiency and reduce long-term costs. The market’s concentration and characteristics indicate a competitive environment where both established players and nimble, regional firms continue to evolve with shifting environmental, technological, and regulatory landscapes.
Report Coverage
The research report offers an in-depth analysis based on By product type, Technology, End-User, Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Regulatory pressures will continue to intensify, driving industries to adopt advanced air pollution control technologies to meet stricter environmental standards.
- Technological advancements, including AI and automation, will enhance the efficiency of air pollution control systems, enabling real-time monitoring and quicker responses to pollution levels.
- The shift towards sustainability will accelerate, with governments and industries prioritizing green technologies, further boosting demand for innovative pollution control solutions.
- Emerging markets, particularly in Asia-Pacific and Africa, will experience substantial growth in air pollution control system adoption as industrialization and urbanization increase.
- Carbon capture technologies will gain prominence as industries work to meet net-zero emissions targets and comply with evolving global climate policies.
- The rise of renewable energy sources will create new opportunities for pollution control systems, particularly in power generation and industrial applications.
- The proliferation of smart cities will lead to a surge in demand for integrated pollution monitoring and control systems to manage urban air quality.
- Growing public awareness of air pollution’s health impacts will prompt governments, businesses, and individuals to invest in cleaner technologies.
- Government incentives, grants, and funding for pollution control technologies will further facilitate the widespread adoption of air quality solutions.
- Increased collaboration among industry players, governments, and research institutions will drive innovation and lead to more effective and affordable air pollution control systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stricter Environmental Regulations
Governments worldwide are implementing more stringent air quality standards, compelling industries to adopt advanced air pollution control systems to comply with legal requirements and avoid penalties.
Industrialization and Urbanization
Rapid industrial growth and urban expansion, especially in Asia Pacific, are increasing emissions from manufacturing, power generation, and transportation, driving demand for pollution control technologies.
Technological Advancements
Innovations in filtration, electrostatic precipitators, scrubbers, and carbon capture technologies are making air pollution control systems more efficient and cost-effective, encouraging broader adoption across industries.
Health and Economic Concerns
Rising public awareness of the health risks and economic costs associated with air pollution is pressuring both governments and industries to invest in solutions that reduce harmful emissions and improve air quality.
Government Incentives and Funding
Financial support, grants, and subsidies from governments for installing pollution control systems are lowering the barriers to adoption, particularly for small and medium-sized enterprises and in emerging markets.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of Air Pollution Control Systems?
What factors are driving the Air Pollution Control Systems?
What are the key segments within the Air Pollution Control Systems?
What are some challenges faced by the Air Pollution Control Systems?
Who are the major players in the Top Air Pollution Control Systems?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Fabric Filters
- 1.2.2 Wet Scrubbers
- 1.2.3 Electrostatic Precipitators
- 1.2.4 Catalytic Converters
- 1.2.5 Carbon Capture and Storage (CCS)
- 1.3 By Product Type
- 1.3.1 Filtering Systems
- 1.3.2 Scrubbers
- 1.3.3 Electrostatic Precipitators
- 1.3.4 Catalytic Converters
- 1.3.5 Carbon Capture Technologies
- 1.4 By End-User Industry
- 1.4.1 Power Generation
- 1.4.2 Cement Manufacturing
- 1.4.3 Chemical Processing
- 1.4.4 Steel Production
- 1.4.5 Automotive
- 1.4.6 Textile
- 1.4.7 Mining
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 84,315 million → 2032: USD 159,563.11 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Air Pollution Control Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Air Pollution Control Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Air Pollution Control Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Air Pollution Control Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Air Pollution Control Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Air Pollution Control Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Air Pollution Control Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Air Pollution Control Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 84,315 million → 2032: USD 159,563.11 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Air Pollution Control Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fabric Filters
- 12.3.7.2 Wet Scrubbers
- 12.3.7.3 Electrostatic Precipitators
- 12.3.7.4 Catalytic Converters
- 12.3.7.5 Carbon Capture and Storage (CCS)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Filtering Systems
- 12.4.7.2 Scrubbers
- 12.4.7.3 Electrostatic Precipitators
- 12.4.7.4 Catalytic Converters
- 12.4.7.5 Carbon Capture Technologies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Power Generation
- 12.5.7.2 Cement Manufacturing
- 12.5.7.3 Chemical Processing
- 12.5.7.4 Steel Production
- 12.5.7.5 Automotive
- 12.5.7.6 Textile
- 12.5.7.7 Mining
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Air Pollution Control Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Air Pollution Control Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Air Pollution Control Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Air Pollution Control Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Siemens AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Johnson Matthey
- 18.4 Ducon Technologies Inc.
- 18.5 Thermax Limited
- 18.6 FLSmidth & Co. A/S
- 18.7 Mitsubishi Hitachi Power Systems
- 18.8 Babcock & Wilcox Enterprises, Inc.
- 18.9 Donaldson Company, Inc.
- 18.10 Emerson Electric Co.
- 18.11 Sulzer Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

