
Market Overview:
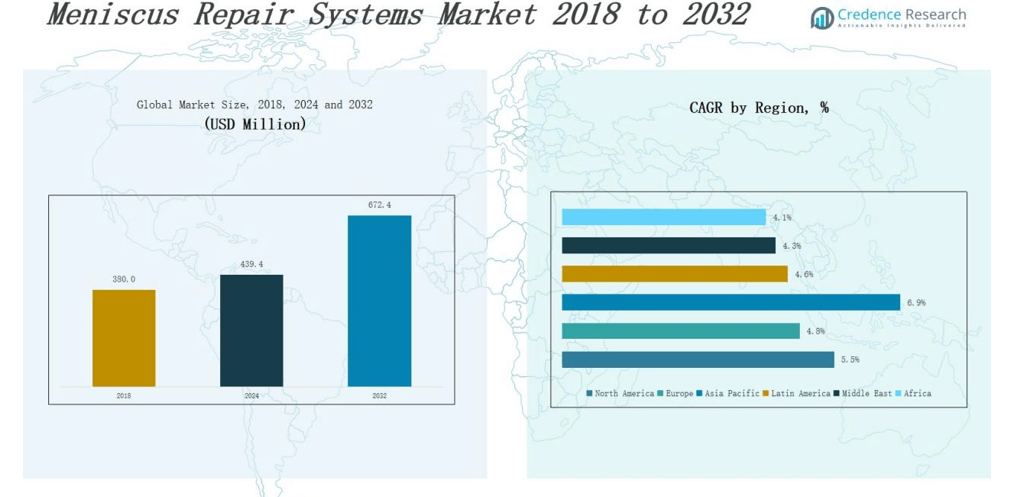
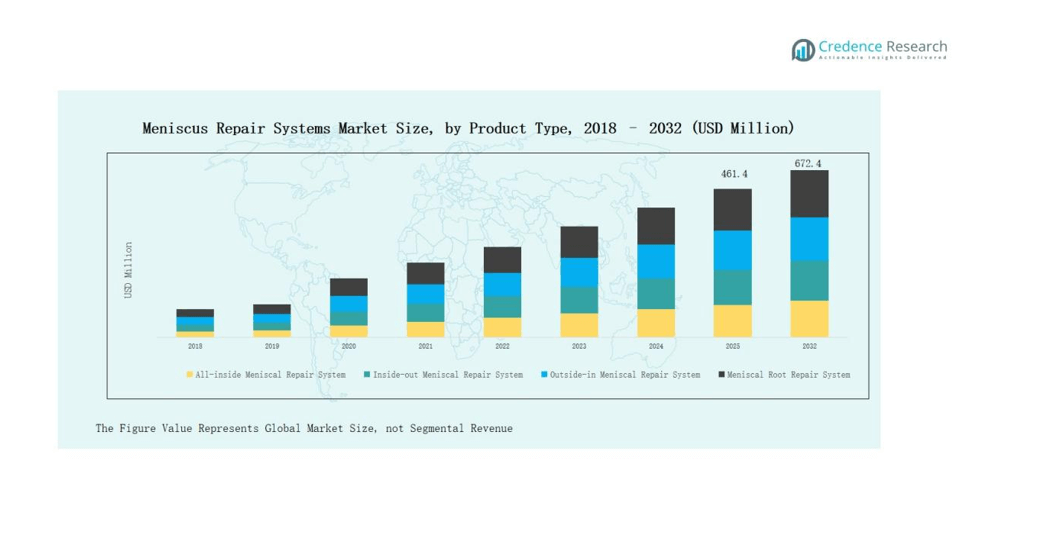
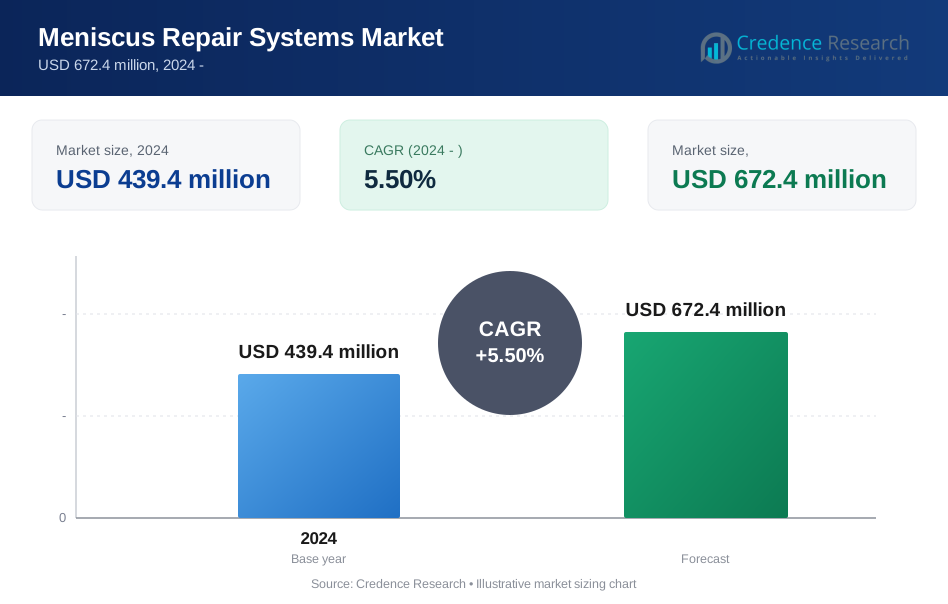
Meniscus Repair Systems Market size was valued at USD 380.0 million in 2018 to USD 439.4 million in 2024 and is anticipated to reach USD 672.4 million by 2032, at a CAGR of 5.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Meniscus Repair Systems Market Size 2024 | USD 439.4 million |
| Meniscus Repair Systems Market, CAGR | 5.5% |
| Meniscus Repair Systems Market Size 2032 | USD 672.4 million |
The meniscus repair systems market is shaped by key players such as Smith & Nephew, Arthrex, Johnson & Johnson (DePuy Synthes), Stryker Corporation, CONMED Corporation, Zimmer Biomet, Medtronic, and Karl Storz. These companies focus on advancing minimally invasive repair techniques, introducing bioabsorbable implants, and expanding their global distribution networks to strengthen market presence. Strategic partnerships, product innovations, and acquisitions are central to maintaining competitiveness. Regionally, North America leads the meniscus repair systems market, holding a dominant 42% share, supported by advanced healthcare infrastructure, high sports injury incidence, and strong adoption of arthroscopic procedures.
Market Insights
- The Meniscus Repair Systems Market grew from USD 380.0 million in 2018 to USD 439.4 million in 2024 and is expected to reach USD 672.4 million by 2032.
- Key players such as Smith & Nephew, Arthrex, Johnson & Johnson (DePuy Synthes), Stryker, CONMED, Zimmer Biomet, Medtronic, and Karl Storz drive innovation and global expansion.
- The all-inside meniscal repair system leads by product type with a 41% share, supported by minimally invasive techniques, reduced complications, and strong adoption in hospitals and clinics.
- By application, radial tear repair holds a 34% share, driven by rising sports-related injuries and higher incidence of degenerative knee conditions among aging populations.
- North America dominates with 38% share in 2024, followed by Europe at 28% and Asia Pacific at 23%, while Latin America, Middle East, and Africa collectively contribute smaller but growing shares.
Market Segment Insight
By Product Type
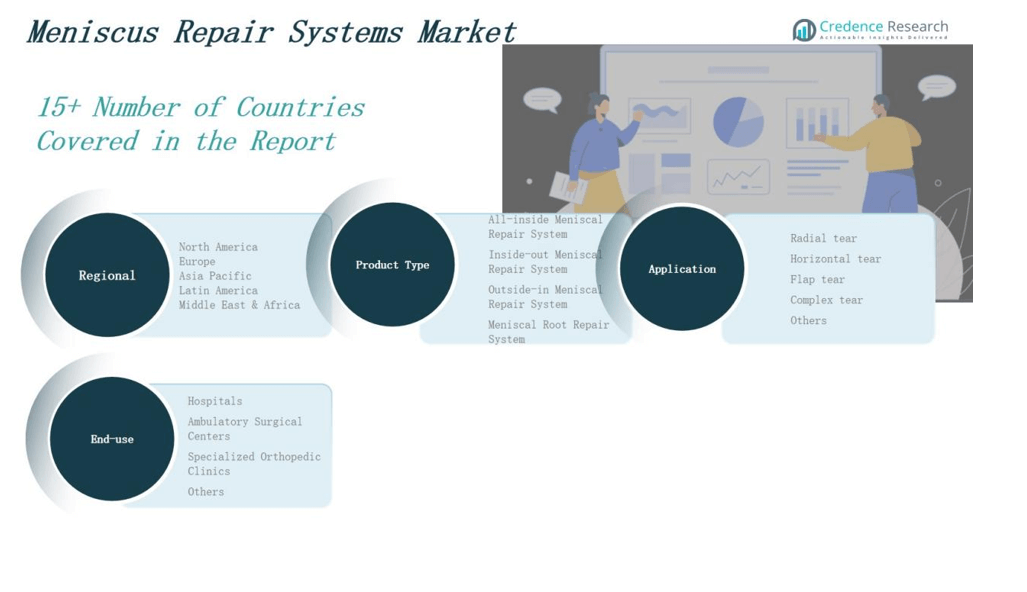
The all-inside meniscal repair system dominates the product type segment with a 41% market share. Its dominance is driven by minimally invasive surgical techniques, reduced operation time, and lower post-operative complications compared to traditional approaches. Surgeons prefer this system for faster recovery and higher patient comfort, boosting adoption across hospitals and specialty clinics. Inside-out systems follow due to their strong applicability in complex tears, while outside-in and meniscal root repair systems address niche requirements with growing adoption in advanced orthopedic centers.
- For instance, Smith & Nephew’s FAST-FIX 360 system has been cited in clinical studies for enabling secure suture fixation through a smaller incision, improving rehabilitation outcomes.
By Application
Radial tear repair leads the application segment, holding a 34% share of the market. Rising sports-related injuries and growing incidence of degenerative tears in aging populations fuel demand for advanced repair systems in this category. Horizontal tears and flap tears also show notable growth, supported by increased arthroscopic procedures. Complex tears, though less frequent, are gaining attention due to advancements in suturing technologies. The “others” segment, including rare tear types, contributes moderately with specialized system adoption.
- For instance, DePuy Mitek (a Johnson & Johnson company) announced that its TruStitch device is now being applied in complex and multi-planar tear configurations, expanding surgical options for challenging cases.
By End-User
Hospitals remain the leading end-user segment, accounting for a 46% market share. Their dominance stems from advanced surgical infrastructure, high patient footfall, and availability of skilled orthopedic surgeons. Ambulatory surgical centers are gaining momentum due to rising preference for outpatient minimally invasive surgeries and cost-efficient care models. Specialized orthopedic clinics show strong growth supported by focused expertise and adoption of innovative repair systems. Other end-users, including research and training institutes, contribute a smaller portion but aid in technology testing and adoption.
Market Overview
Rising Sports-Related Injuries and Trauma Cases
The meniscus repair systems market is expanding as sports injuries continue to rise globally. High-impact activities such as football, basketball, and skiing increase the prevalence of meniscus tears among athletes. Growing awareness of early intervention, coupled with advanced diagnostic tools, supports timely surgical treatment. The preference for meniscus preservation instead of removal has further boosted demand for repair systems. Hospitals and specialty clinics increasingly adopt advanced repair devices to reduce recovery time and restore joint function, strengthening market growth.
- For instance, Arthrex Inc. reported increased adoption of its all-inside meniscal repair devices, which are preferred for minimally invasive procedures that enhance recovery speed by up to 30% compared to traditional techniques.
Growing Geriatric Population with Degenerative Knee Conditions
The rising geriatric population fuels demand for meniscus repair systems due to increased susceptibility to degenerative joint diseases. Elderly patients often experience meniscal tears linked to aging cartilage, driving the need for effective surgical solutions. Minimally invasive systems have gained popularity among this demographic, offering faster recovery and fewer complications. The combination of aging populations, longer life expectancy, and growing healthcare access drives significant uptake. This factor ensures steady demand across developed regions and emerging economies where aging is accelerating.
- For instance, Smith+Nephew’s FAST-FIX FLEX Meniscal Repair System is commonly used in arthroscopic procedures among older patients, offering flexible implant delivery and shorter post-op rehabilitation compared to traditional sutures.
Technological Advancements in Arthroscopic Procedures
Innovations in arthroscopic techniques have strengthened the adoption of meniscus repair systems worldwide. Companies are introducing bioabsorbable implants, self-retrieving sutures, and advanced fixation devices to improve repair outcomes. Surgeons benefit from simplified procedures with enhanced accuracy and reduced risk of complications. Advancements in visualization technologies further support precise placement during repair surgeries. The availability of next-generation repair kits in hospitals and ambulatory surgical centers continues to attract investment, making technological progress a critical growth driver for the market.
Key Trends & Opportunities
Shift Toward Minimally Invasive and Outpatient Surgeries
A major trend shaping the meniscus repair systems market is the rising shift toward minimally invasive procedures. Outpatient arthroscopic surgeries are increasingly preferred due to reduced hospitalization costs and faster recovery times. Ambulatory surgical centers are witnessing strong adoption, supported by advanced repair systems tailored for efficiency. This trend creates opportunities for device manufacturers to introduce compact, user-friendly systems designed for outpatient care. Growing demand for cost-efficient healthcare delivery is expected to sustain this shift in both developed and emerging markets.
- For instance, Arthrex has expanded adoption of its Meniscus Cinch II system, which facilitates minimally invasive, suture-based repairs and is widely used in outpatient arthroscopies
Expansion in Emerging Economies and Untapped Markets
Emerging economies present strong growth opportunities in the meniscus repair systems market. Rising healthcare investments, expanding orthopedic infrastructure, and greater access to insurance coverage are fueling demand in regions such as Asia Pacific, Latin America, and the Middle East. Increasing participation in sports and growing awareness of arthroscopic solutions further support adoption. Global players are targeting these regions with tailored distribution strategies and affordable product offerings. The untapped potential of these markets provides companies with significant room for revenue expansion.
- For instance, Zimmer Biomet has expanded its footprint in Latin America with its OmniSpan Meniscal Repair System and integration of robotic surgery platforms like ROSA Robotics, which improves procedural efficiency and accessibility in countries like Brazil and Mexico.
Key Challenges
High Cost of Meniscus Repair Procedures and Devices
The elevated cost of meniscus repair systems remains a major barrier to adoption, particularly in low- and middle-income countries. Advanced arthroscopic devices and implants often carry high price tags, limiting access for patients without comprehensive insurance coverage. Even in developed markets, rising healthcare costs create challenges for hospitals balancing budgets. The cost factor not only restricts widespread use but also hampers adoption in outpatient settings. Addressing affordability is essential for manufacturers to capture a broader patient base globally.
Risk of Post-Surgical Complications and Failure Rates
Despite advancements, meniscus repair systems face challenges related to post-surgical complications. In some cases, patients experience incomplete healing, re-tears, or persistent knee pain. Such risks reduce confidence among surgeons and patients, particularly when repair outcomes remain unpredictable. Failure rates vary depending on tear type, surgical technique, and patient compliance. This concern highlights the need for continuous innovation in materials and suturing methods. Reducing complication rates is critical for ensuring long-term success and wider adoption of these systems.
Limited Availability of Skilled Orthopedic Surgeons
A shortage of trained orthopedic surgeons with expertise in advanced arthroscopic procedures hinders market expansion. Meniscus repair surgeries require precision, and the lack of skilled professionals in developing regions restricts adoption. Even in developed countries, rising demand for orthopedic procedures strains the available workforce. Training programs and workshops are being introduced, but gaps remain significant. The shortage limits the ability of hospitals and ambulatory centers to scale repair procedures effectively, creating a key challenge for the global market.
Regional Analysis
North America
North America dominates the meniscus repair systems market with a 38% share in 2024 and is expected to maintain its lead, growing from USD 157.2 million in 2024 to USD 240.1 million by 2032 at a CAGR of 5.5%. Growth is fueled by advanced healthcare infrastructure, high prevalence of sports injuries, and strong adoption of minimally invasive arthroscopic techniques. The U.S. remains the largest contributor, supported by favorable reimbursement policies, significant healthcare spending, and continuous product innovation from leading global players.
Europe
Europe holds the second-largest market position with a 28% share in 2024, projected to grow from USD 117.0 million in 2024 to USD 169.6 million by 2032 at a CAGR of 4.8%. Market growth is driven by a strong orthopedic device industry, rising geriatric population, and widespread use of advanced surgical procedures. Countries such as Germany, the UK, and France lead adoption due to well-established healthcare systems and a high incidence of degenerative knee conditions, while Eastern Europe shows steady demand expansion.
Asia Pacific
Asia Pacific represents a fast-growing region with a 23% share in 2024, expanding from USD 103.2 million in 2024 to USD 175.1 million by 2032 at the highest CAGR of 6.9%. Rising sports participation, increasing healthcare investments, and expanding orthopedic infrastructure in countries like China, India, Japan, and South Korea drive adoption. Growing awareness of minimally invasive procedures and broader insurance coverage further support demand. The region’s strong growth potential makes it a strategic focus for global players introducing cost-effective repair solutions.
Latin America
Latin America accounts for a 5% share in 2024, with market revenues increasing from USD 28.2 million in 2024 to USD 40.1 million by 2032 at a CAGR of 4.6%. Brazil leads regional adoption due to expanding sports culture, rising cases of knee injuries, and improving healthcare access. Argentina and Mexico also show steady demand, supported by growing investments in surgical technologies. However, limited reimbursement structures and uneven distribution of advanced healthcare facilities restrain faster adoption across the region.
Middle East
The Middle East holds a 3% share in 2024, with the market expected to rise from USD 17.5 million in 2024 to USD 24.5 million by 2032 at a CAGR of 4.3%. GCC countries lead adoption due to high investments in healthcare infrastructure and medical tourism. Sports-related injuries, particularly from football and athletics, drive repair system demand. Israel and Turkey also contribute significantly, supported by advanced orthopedic expertise. However, limited access in less-developed areas within the region constrains wider adoption.
Africa
Africa captures a 3% share in 2024, growing from USD 16.3 million in 2024 to USD 22.9 million by 2032 at a CAGR of 4.1%. South Africa dominates regional adoption due to better healthcare facilities and higher availability of orthopedic specialists. Egypt also shows rising demand supported by government healthcare initiatives. However, most of Africa faces challenges such as inadequate infrastructure, limited insurance coverage, and shortage of skilled surgeons. These barriers slow widespread adoption, but gradual improvements in healthcare investment provide growth opportunities.
Market Segmentations:
By Product Type
- All-inside Meniscal Repair System
- Inside-out Meniscal Repair System
- Outside-in Meniscal Repair System
- Meniscal Root Repair System
By Application
- Radial Tear
- Horizontal Tear
- Flap Tear
- Complex Tear
- Others
By End-User
- Hospitals
- Ambulatory Surgical Centers
- Specialized Orthopedic Clinics
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the meniscus repair systems market is characterized by the strong presence of multinational medical device companies alongside specialized orthopedic solution providers. Leading players such as Smith & Nephew, DePuy Synthes (Johnson & Johnson), Stryker, Zimmer Biomet, Arthrex, and CONMED Corporation hold significant market positions, supported by broad product portfolios, global distribution networks, and continuous investments in research and development. These companies focus on advancing minimally invasive repair technologies, introducing bioabsorbable implants, and enhancing arthroscopic instrumentation to improve patient outcomes and surgical efficiency. Emerging players like Arcuro Medical, BIOTEK, Chemex Trading SA, and Double Medical Technology are gaining visibility by offering cost-effective, innovative repair systems tailored for developing markets. Strategic collaborations with hospitals and sports medicine centers, along with training programs for surgeons, further strengthen market penetration. Intense competition is driving consolidation, product differentiation, and regional expansion strategies, shaping a dynamic market environment where technological innovation remains the key competitive advantage.
Key Players
- Smith & Nephew
- DePuy Synthes (Johnson & Johnson)
- Stryker
- Zimmer Biomet
- Arthrex, Inc.
- CONMED Corporation
- ARCURO Medical
- Chemex Trading SA
- BIOTEK
- Double Medical Technology Inc.
Recent Developments
- In December 2023, Arthrex launched the FiberStitch 1.5 implant system, featuring a 17% smaller delivery needle that provides stronger fixation and minimizes tissue disruption.
- In February 2025, Dr. Fleissner performed the world’s first meniscus repair using the new collagen-based RejuvaKnee™ implant. The device, recently cleared by the FDA, supports regeneration of natural meniscal tissue and offers faster access for patients.
- In April 2025, Native Orthopaedics received FDA 510(k) clearance for their Native Root System using Dragonfly™ technology to repair meniscal root tears. The knotless system will be available commercially starting May 2025 in select locations
- In January 2025, OrthoPreserve’s meniscus implant received FDA Breakthrough Device status and entered the TAP program, marking one of the first orthopedic devices to do so. The implant aims to restore meniscus function and address pain and mobility issues post-surgery.
Market Concentration & Characteristics
The Meniscus Repair Systems Market demonstrates moderate concentration, with a few global leaders commanding significant market shares while regional and niche players compete through specialized offerings. It is characterized by strong competition among established companies such as Smith & Nephew, DePuy Synthes, Stryker, Zimmer Biomet, Arthrex, and CONMED Corporation, which leverage extensive product portfolios and global distribution networks. The market relies heavily on technological innovation, with bioabsorbable implants, minimally invasive repair systems, and advanced suturing devices shaping competitive differentiation. It shows steady growth due to rising sports injuries, increasing geriatric patients with degenerative conditions, and growing demand for arthroscopic procedures. Market dynamics reflect high entry barriers created by regulatory requirements, capital investment needs, and surgeon training demands. While hospitals dominate adoption, ambulatory surgical centers and orthopedic clinics provide new avenues for growth. With steady innovation and expanding applications, it continues to evolve into a technology-driven, patient-focused market with global expansion opportunities.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for minimally invasive meniscus repair procedures will continue to increase globally.
- Hospitals will remain the leading end-user due to advanced infrastructure and skilled specialists.
- Ambulatory surgical centers will gain traction with rising preference for outpatient surgeries.
- Sports-related injuries will drive higher adoption of advanced repair systems.
- Aging populations will fuel steady demand for treatments addressing degenerative knee conditions.
- Bioabsorbable implants and innovative suturing devices will strengthen market penetration.
- Emerging economies will present strong opportunities with expanding healthcare infrastructure.
- Strategic collaborations between manufacturers and healthcare providers will enhance accessibility.
- Training programs for surgeons will become essential to support adoption in developing regions.
- Continuous innovation in arthroscopic visualization technologies will improve surgical outcomes and patient recovery.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Meniscus Repair Systems Market?
What factors are driving the growth of the Meniscus Repair Systems Market?
Which regions are leading the Meniscus Repair Systems Market?
Why is the aging population contributing to the market's growth?
What technological advancements are impacting the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Meniscus Repair Systems Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Meniscus Repair Systems Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 439.4 million → forecast year: USD 672.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Meniscus Repair Systems Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Meniscus Repair Systems Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Meniscus Repair Systems Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Meniscus Repair Systems Market Drivers
- 3.3 Meniscus Repair Systems Market Restraints & Challenges
- 3.4 Meniscus Repair Systems Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Meniscus Repair Systems Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Meniscus Repair Systems Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Meniscus Repair Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Meniscus Repair Systems Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Meniscus Repair Systems Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Meniscus Repair Systems market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Meniscus Repair Systems Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Meniscus Repair Systems Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Meniscus Repair Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Meniscus Repair Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Meniscus Repair Systems Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Meniscus Repair Systems Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Meniscus Repair Systems Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Meniscus Repair Systems Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Meniscus Repair Systems Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Meniscus Repair Systems Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Meniscus Repair Systems Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Meniscus Repair Systems Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Meniscus Repair Systems Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
