
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
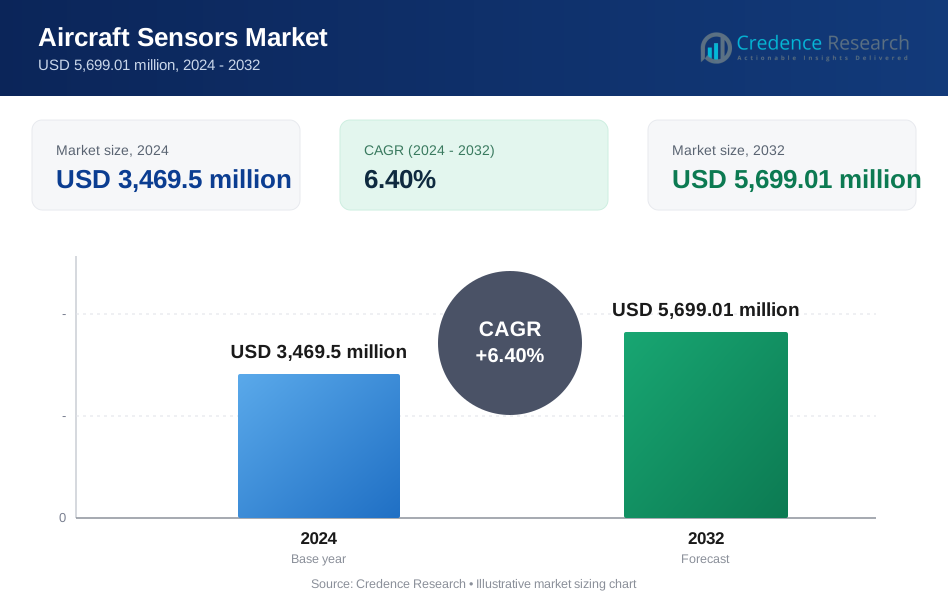
| Aircraft Sensors Market Size 2024 | USD 3,469.5 Million |
| Aircraft Sensors Market, CAGR | 6.40% |
| Aircraft Sensors Market Size 2032 | USD 5,699.01 Million |
Market Overview
The Aircraft Sensors Market is projected to grow from USD 3,469.5 million in 2024 to USD 5,699.01 million by 2032, at a compound annual growth rate (CAGR) of 6.40%.
The aircraft sensors market is driven by increasing demand for advanced avionics, rising air travel, and growing focus on aircraft safety and efficiency. Airlines are investing in modern aircraft equipped with sensors to enhance performance, reduce maintenance costs, and ensure compliance with stringent safety regulations. The trend toward lightweight and energy-efficient aircraft, alongside advancements in sensor technology, is boosting market growth. Additionally, the integration of IoT and AI in aviation for real-time data monitoring and predictive maintenance is further accelerating the adoption of aircraft sensors across the industry.
North America dominates the aircraft sensors market due to the strong presence of leading aerospace companies such as Honeywell International, Lockheed Martin, and General Electric. The region's focus on military modernization and expanding commercial aviation fuels demand for advanced sensors. Europe follows closely, with key players like Meggitt PLC, Safran S.A., and Thales Group driving growth, particularly in defense and commercial sectors. Asia-Pacific is witnessing rapid expansion, especially in China and India, due to increasing air travel demand and defense investments. Global key players such as TE Connectivity and Zodiac Aerospace also contribute significantly to market development.
Market Drivers
Safety and Reliability
Aircraft sensors play a critical role in ensuring safety and reliability by detecting potential hazards such as engine malfunctions, structural issues, or adverse weather conditions. These sensors provide real-time data, allowing pilots and maintenance teams to take preventive actions, reducing the risk of accidents. For instance, according to a report by the Federal Aviation Administration (FAA), the integration of advanced sensors has significantly reduced the number of in-flight incidents related to engine failures. Additionally, regulatory bodies in the aviation industry, such as the FAA and the European Union Aviation Safety Agency (EASA), impose stringent safety standards. Aircraft manufacturers are required to comply by integrating reliable sensors, ensuring that safety is prioritized in every flight, enhancing passenger confidence and operational reliability.
Fuel Efficiency and Environmental Concerns
The aviation industry is under pressure to reduce its environmental footprint, and sensors are pivotal in improving fuel efficiency and reducing emissions. By providing precise data on aircraft performance, sensors enable optimized flight operations, leading to significant reductions in fuel consumption. For instance, a study by the International Air Transport Association (IATA) found that the use of advanced sensors in modern aircraft has led to a noticeable decrease in fuel burn per flight hour. This contributes to lower operating costs and aligns with global sustainability goals. As airlines strive to adopt greener practices, the use of advanced sensors helps in minimizing environmental impact, supporting the transition toward more sustainable aviation practices while ensuring operational efficiency and meeting environmental regulations.
Technological Advancements
Advancements in sensor technology have led to the development of smaller, lighter, and more accurate sensors, which enhance aircraft performance by reducing weight and providing more precise measurements. Miniaturized sensors allow aircraft to achieve better fuel efficiency, while also improving overall functionality. Furthermore, sensors are increasingly being integrated with avionics and flight control systems, enhancing the performance and safety of modern aircraft. These technological improvements enable better data collection and analysis, empowering airlines to make informed decisions and improving the overall efficiency of aircraft operations.
Increasing Air Traffic and Advanced Aviation Systems
As global air traffic continues to grow, airlines are expanding their fleets to meet rising passenger demand, resulting in a higher demand for aircraft sensors. These sensors ensure that the growing fleet of aircraft operates efficiently and safely. Additionally, the development of autonomous flight systems, unmanned aerial vehicles (UAVs), and electric aircraft heavily depends on advanced sensors for navigation, control, and safety. In military and defense applications, sensors are used for surveillance, reconnaissance, and as integral components in weapon systems, further driving the demand for sensor technology across various aviation sectors.
Market Trends
Miniaturization and Advanced Materials
The trend toward miniaturization and weight reduction is significantly shaping the aircraft sensors market. Manufacturers are increasingly focused on developing smaller, lighter sensors that reduce the overall weight of the aircraft, which directly improves fuel efficiency and operational performance. Advanced materials such as carbon fiber and composites are being used to create these compact sensors, offering durability without compromising on functionality. Additionally, the use of cutting-edge materials like silicon carbide and gallium nitride has enhanced the durability and reliability of sensors, particularly in harsh environments where aircraft performance is critical. This combination of miniaturization and material innovation is driving the development of sensors that are not only more efficient but also capable of withstanding extreme conditions. Furthermore, advanced manufacturing techniques, such as additive manufacturing or 3D printing, are being explored to produce custom-designed sensors. This innovation is reducing manufacturing costs, shortening lead times, and offering new possibilities for sensor customization. For instance, Airbus Services subsidiary Satair has supplied the first certified additively manufactured part to fly on an in-service commercial airliner. Airlines and manufacturers are benefiting from the flexibility of these techniques, which allow for tailored solutions that meet the unique demands of modern aircraft. As technology continues to evolve, the integration of smaller, more durable sensors is expected to play a pivotal role in advancing the efficiency and safety of both commercial and military aircraft.
Integration, Connectivity, and AI
The integration of sensors with other aircraft systems is a growing trend, enabling more comprehensive monitoring and control. Sensor fusion allows multiple sensors to work together with avionics, flight control systems, and navigation systems to provide a detailed understanding of aircraft performance. This integration improves real-time decision-making, enhances safety, and streamlines aircraft operations. Moreover, data connectivity is becoming a standard feature in modern sensors, with wireless technologies allowing the transmission of real-time data to ground stations or other aircraft. This connectivity enables predictive maintenance and remote diagnostics, improving operational efficiency and reducing downtime. The rise of artificial intelligence (AI) and machine learning (ML) is further transforming how sensors are utilized. AI and ML algorithms analyze the vast amounts of data generated by sensors to detect anomalies, predict potential maintenance issues, and optimize aircraft performance. These technologies are critical for the development of autonomous flight systems, where sensors need to make intelligent decisions without human intervention. Autonomous aircraft and unmanned aerial vehicles (UAVs) heavily rely on sensors for navigation, obstacle avoidance, and system control, while electric aircraft require sensors for monitoring battery performance and temperature. As AI-driven analytics become more prevalent, the role of sensors will expand, creating new opportunities for enhanced aircraft safety, performance, and efficiency across both commercial and defense aviation sectors.
Market Challenges Analysis
Cost, Complexity, and Integration Challenges
The development and manufacturing of advanced aircraft sensors come with high costs, especially as features like miniaturization, enhanced durability, and wireless connectivity are integrated. These sophisticated sensors require specialized expertise for installation, calibration, and ongoing maintenance, which adds to the overall expense for airlines and manufacturers. For instance, NASA’s Fiber Optic Sensing System (FOSS) technology combines advanced strain sensors and innovative algorithms into a robust package that accurately and cost-effectively monitors a host of critical parameters in real time. Additionally, the complexity of sensor systems presents further challenges, particularly when it comes to integrating them with other aircraft systems. Sensors from different manufacturers may not be fully interoperable, necessitating additional efforts to ensure compatibility and smooth operation. This issue is especially prominent when upgrading legacy systems, as integrating newer sensors with older aircraft technology can be time-consuming and costly. The need for highly skilled personnel to install, monitor, and troubleshoot these complex systems also drives up operational costs. Furthermore, sensor compatibility with a wide range of aircraft models adds another layer of complexity. As airlines seek to upgrade their fleets with modern sensors to enhance safety and performance, the integration of these systems into both older and new aircraft remains a challenge. This hurdle is exacerbated by the need for regular updates to ensure that new sensor technologies are aligned with current safety and regulatory standards. The process of achieving seamless integration between various sensor types and aircraft systems is a significant technical challenge, impacting overall efficiency and performance.
Reliability, Security, and Regulatory Compliance
Ensuring the reliability and durability of aircraft sensors in harsh environments is a major challenge. These sensors are exposed to extreme temperatures, vibrations, and electromagnetic interference, all of which can affect their performance and longevity. Sensor failures can lead to safety risks, operational disruptions, and costly delays, making reliability a top priority for manufacturers. Overcoming these challenges requires rigorous testing and the use of materials that can withstand these tough conditions, but achieving this level of reliability often drives up production costs. Data security and privacy also pose significant challenges in the aircraft sensor market. Sensors are increasingly connected to wireless networks and IoT systems, collecting vast amounts of sensitive data related to aircraft operations and passengers. This makes them vulnerable to cyberattacks, raising concerns over data breaches and unauthorized access. Protecting passenger privacy, especially when biometric sensors are involved, is another critical issue. In addition to cybersecurity, sensor manufacturers face the challenge of navigating complex regulatory landscapes. As aviation authorities continuously update safety standards, manufacturers must ensure that their products meet the latest regulations. Obtaining certification for new sensor technologies can be a lengthy and costly process, further complicating market entry for new innovations.
Market Segmentation Analysis:
By Platform:
The aircraft sensors market is segmented by platform into fixed-wing aircraft, rotary blade aircraft, and unmanned aerial vehicles (UAVs). Fixed-wing aircraft, including commercial and military categories, hold a significant share due to their extensive use in global aviation. Commercial aircraft, further segmented into narrow-body, wide-body, regional jets, and business jets, are major consumers of sensors, driven by the increasing demand for air travel and the need for efficient flight operations. Military aircraft, including combat and transport planes, also require advanced sensor technology for operational efficiency and safety in critical missions. Rotary blade aircraft, including commercial helicopters and military helicopters, rely on sensors for precise control, navigation, and safety in complex environments. UAVs, with their expanding applications in surveillance, defense, and commercial sectors, are increasingly adopting sensors for navigation, payload management, and real-time monitoring. The growing use of UAVs is further expected to boost sensor demand, particularly in defense and commercial applications.
By Sensor Type:
Aircraft sensors are categorized by type, with temperature, pressure, force, speed, and torque sensors being crucial for monitoring engine performance, environmental conditions, and mechanical operations. Accelerometers, gyroscopes, and radar sensors are essential for flight control and navigation, while proximity, position, and GPS sensors aid in situational awareness and precise movements. Advanced sensors like angle of attack, airspeed, and altitude sensors are critical for aircraft safety and performance, particularly during flight operations. Smoke detection sensors and vibration sensors are used for monitoring cabin conditions and ensuring structural integrity. As the aviation industry evolves, the integration of these sensors is becoming more sophisticated, with wireless connectivity, sensor fusion, and AI-based data analytics enhancing overall system functionality. The demand for highly accurate, durable, and reliable sensors is driving innovation, with manufacturers focusing on developing sensors that can withstand harsh conditions while delivering precise data to ensure the safety and efficiency of modern aircraft operations.
Segments:
Based on Platform
- Fixed-Wing Aircraft
- Commercial Aircraft
- Narrow Body
- Wide Body
- Regional Jet
- Business Jet
- Military Aircraft
- Combat Aircraft
- Transport Aircraft
- Commercial Aircraft
- Rotary Blade Aircraft
- Commercial Helicopters
- Military Helicopters
- UAVs
Based on Sensor Type
- Temperature Sensor
- Pressure Sensor
- Force Sensor
- Speed Sensor
- Torque Sensor
- Accelerometer Sensor
- Flow Sensor
- Position Sensor
- Proximity Sensor
- GPS Sensor
- Gyroscope
- Radar Sensor
- Smoke Detection Sensor
- Angle of Attack Sensor
- Level Sensor
- Vibration Sensors
- Airspeed and Altitude Sensor
- Others
Based on Application
- Engine, Turbine, and APU
- Flight Controls and Actuation
- Landing Gear & Brakes
- Environmental Control System
- Doors & Slides
- Cabin, Galley, and Cargo
- Cockpit Controls
Based on Connectivity
- Wired Sensors
- Wireless Sensors
Based on End-Use
- OEM
- Aftermarket
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest market share, accounting for over 35% of the global aircraft sensors market. This dominance is attributed to the region's well-established aviation industry and the presence of key players such as Boeing, Lockheed Martin, and Raytheon Technologies. The U.S. government’s high defense spending and focus on modernizing military aircraft fleets, including combat aircraft and UAVs, drive the demand for advanced sensor technologies. Additionally, North America's commercial aviation sector continues to grow, with airlines investing in newer aircraft that integrate cutting-edge sensors for fuel efficiency, safety, and operational optimization. The increasing use of UAVs for both military and commercial applications further fuels the growth of aircraft sensors in this region.
Asia-Pacific
Asia-Pacific is rapidly emerging as one of the fastest-growing markets for aircraft sensors, with a market share of approximately 25%. The region's growth is primarily driven by the expanding commercial aviation sector, particularly in countries like China and India, which are experiencing a surge in air travel demand. This has led to significant fleet expansions, requiring advanced sensors to ensure safety, compliance with international regulations, and operational efficiency. Additionally, rising defense investments, particularly in China, Japan, and India, have increased the demand for military aircraft and UAVs equipped with sophisticated sensors. The region's growing focus on indigenous aircraft development and the adoption of UAVs in various sectors are expected to further bolster the aircraft sensors market.
Key Player Analysis
- Meggitt PLC (The U.K.)
- TE Connectivity (Switzerland)
- Thales Group (France)
- Honeywell International, Inc. (The U.S.)
- General Atomics Corporation (The U.S.)
- Zodiac Aerospace (France)
- General Electric Company (The U.S.)
- Curtiss-Wright Corporation (The U.S.)
- Woodward Inc. (The U.S.)
- Lockheed Martin Corporation (The U.S.)
- Schneider Electric SE (France)
- The Raytheon Company (The U.S.)
- Safran S.A. (France)
- Ametek, Inc. (The U.S.)
Competitive Analysis
The competitive landscape of the aircraft sensors market is characterized by the presence of several prominent players that leverage advanced technologies and extensive industry experience. Key players include Honeywell International, Inc., Ametek, Inc., General Electric Company, Meggitt PLC, Safran S.A., Woodward Inc., Thales Group, Zodiac Aerospace, Curtiss-Wright Corporation, Schneider Electric SE, General Atomics Corporation, The Raytheon Company, TE Connectivity, and Lockheed Martin Corporation. These companies are focusing on innovation, integrating cutting-edge technologies like IoT and AI into their sensor solutions to enhance performance and reliability. Strategic partnerships and collaborations are common, enabling firms to expand their product offerings and improve market reach. Additionally, these players are investing heavily in R&D to develop next-generation sensors that meet evolving safety and efficiency standards in the aviation industry. As competition intensifies, maintaining technological leadership and adapting to regulatory changes will be crucial for sustaining market position.
Recent Developments
- In October 2024, Honeywell was awarded a $103 million contract by the U.S. Army to provide its Next-Generation APN-209 Radar Altimeter system.
- In August 2024, Woodward was selected by Boeing to design innovative rotary actuators for the NASA Sustainable Flight Demonstrator X-66A aircraft.
- In June 2024, GE Aerospace advanced the development of hybrid electric engines with NASA, embedding electric motor/generators in a high-bypass commercial turbofan.
- In January 2024, Thales air data solution was selected to equip Eve Air Mobility’s eVTOL aircraft, providing critical information such as airspeed, airflow, and altitude.
- In August 2023, Parker Meggitt received certification for iPRESS, a long-range wireless tire pressure sensor for aviation.
Market Concentration & Characteristics
The aircraft sensors market exhibits moderate concentration, with a mix of established multinational corporations and emerging players driving competition. Leading firms such as Honeywell International, General Electric, and Safran S.A. dominate the market, leveraging their extensive research and development capabilities, strong brand recognition, and comprehensive product portfolios. These companies focus on innovative technologies, including advanced materials, IoT integration, and AI-driven data analytics, to enhance sensor performance and reliability. The market is characterized by a high degree of collaboration, with manufacturers frequently partnering with airlines and defense contractors to tailor solutions that meet specific operational needs. Additionally, the market is influenced by stringent regulatory requirements and safety standards, prompting companies to invest significantly in compliance and certification processes. As demand for advanced aircraft sensors continues to grow, especially with the rise of UAVs and electric aircraft, competition is expected to intensify, fostering further innovation and market expansion.
Report Coverage
The research report offers an in-depth analysis based on Platform, Sensor Type, Application, Connectivity, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The aircraft sensors market is projected to grow significantly due to increasing air travel demand and fleet expansions.
- Advances in sensor technology, including miniaturization and enhanced accuracy, will drive innovation and efficiency.
- The integration of artificial intelligence and machine learning will improve data analysis and predictive maintenance capabilities.
- There will be a growing emphasis on sustainability, leading to the development of sensors that support fuel efficiency and reduce emissions.
- The rise of unmanned aerial vehicles (UAVs) will increase the demand for specialized sensors for navigation and obstacle avoidance.
- Enhanced connectivity through wireless sensor networks will enable real-time data transmission and improved monitoring.
- Increased investment in defense and military applications will boost the adoption of advanced sensor technologies.
- Collaborative partnerships among manufacturers, airlines, and technology providers will facilitate customized sensor solutions.
- Regulatory compliance will drive innovations in safety and reliability, requiring more advanced sensor systems.
- The market will see a shift toward aftermarket sensor upgrades as airlines seek cost-effective solutions for existing fleets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancements in Sensor Technology
Ongoing innovations in sensor miniaturization, accuracy, and durability are enabling the development of lighter and more efficient aircraft. These technological improvements allow for enhanced data collection and integration with avionics, supporting better performance, fuel efficiency, and safety in both commercial and military aviation.
Integration of IoT and AI for Predictive Maintenance
The adoption of IoT connectivity and artificial intelligence in aviation is transforming aircraft maintenance by enabling real-time monitoring and predictive analytics. This reduces unplanned downtime, lowers maintenance costs, and increases operational reliability, driving airlines and OEMs to invest in advanced sensor solutions.
Stringent Safety and Regulatory Requirements
Aviation authorities such as the FAA and EASA mandate rigorous safety standards, compelling aircraft manufacturers and operators to integrate high-performance sensors for compliance. These regulations ensure continuous demand for reliable and accurate sensors to monitor critical systems and enhance passenger safety.
Fleet Expansion and Modernization
The global increase in air travel and defense spending is prompting airlines and military organizations to expand and modernize their fleets. New aircraft platforms and retrofits require advanced sensors for improved efficiency, safety, and compliance, fueling market growth.
Growth of UAVs and Autonomous Systems
The rapid adoption of unmanned aerial vehicles (UAVs) and the development of autonomous flight systems are creating new demand for specialized sensors. These platforms rely heavily on sensors for navigation, obstacle avoidance, and system control, expanding the market beyond traditional manned aircraft.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aircraft Sensors market?
What factors are driving the growth of the Aircraft Sensors market?
What are the key segments within the Aircraft Sensors market?
What are some challenges faced by the Aircraft Sensors market?
Who are the major players in the Aircraft Sensors market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Platform
- 1.2.1 Fixed-Wing Aircraft
- 1.2.2 Rotary Blade Aircraft
- 1.2.3 Unmanned Aerial Vehicles (UAVs)
- 1.3 By Application
- 1.3.1 Engine, Turbine, and APU
- 1.3.2 Flight Controls and Actuation
- 1.3.3 Landing Gear & Brakes
- 1.3.4 Cabin, Galley, and Cargo
- 1.4 By Sensor Type
- 1.4.1 Temperature Sensor
- 1.4.2 Pressure Sensor
- 1.4.3 Accelerometer Sensor
- 1.4.4 Gyroscope
- 1.4.5 Airspeed and Altitude Sensor
- 1.5 By Connectivity
- 1.5.1 Wired Sensors
- 1.5.2 Wireless Sensors
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,469.5 million → 2032: USD 5,699.01 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aircraft Sensors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aircraft Sensors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aircraft Sensors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aircraft Sensors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aircraft Sensors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aircraft Sensors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aircraft Sensors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aircraft Sensors Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,469.5 million → 2032: USD 5,699.01 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aircraft Sensors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Platform - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fixed-Wing Aircraft
- 12.3.7.2 Rotary Blade Aircraft
- 12.3.7.3 Unmanned Aerial Vehicles (UAVs)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Engine, Turbine, and APU
- 12.4.7.2 Flight Controls and Actuation
- 12.4.7.3 Landing Gear & Brakes
- 12.4.7.4 Cabin, Galley, and Cargo
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sensor Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Temperature Sensor
- 12.5.7.2 Pressure Sensor
- 12.5.7.3 Accelerometer Sensor
- 12.5.7.4 Gyroscope
- 12.5.7.5 Airspeed and Altitude Sensor
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Connectivity - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Wired Sensors
- 12.6.7.2 Wireless Sensors
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aircraft Sensors End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aircraft Sensors Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aircraft Sensors Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aircraft Sensors Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Honeywell International, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 General Electric Company
- 18.4 Safran S.A.
- 18.5 Thales Group
- 18.6 Meggitt PLC
- 18.7 TE Connectivity
- 18.8 Zodiac Aerospace
- 18.9 Woodward Inc.
- 18.10 Curtiss-Wright Corporation
- 18.11 Ametek, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

